
 Hydrogen Storage Cylinders Market | 2026-2036
Hydrogen Storage Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Storage Cylinders Market Insights
Subscription-based cylinder recertification and predictive maintenance is hardening as a recurring revenue layer alongside hardware sales. Hexagon Composites leverages its automated filament winding capacity to dominate Type IV composite output for heavy mobility. Worthington Industries anchors North American manufacturing through backward integration into steel processing. NPROXX specializes in high-pressure systems for rail and bus OEMs, differentiating on TÜV-certified designs.
Hydrogen storage cylinders are pressure vessels engineered to contain gaseous or liquid hydrogen at operating pressures typically ranging from 350 to 700 bar, constructed from carbon-fiber-reinforced polymer, aluminum, or steel with polymer liners to prevent embrittlement and permeation. Their primary purpose is to enable safe, dense energy storage for mobile and stationary hydrogen applications where weight efficiency and cycle durability determine total cost of ownership. Composite cylinders command premium positioning in transportation due to their superior gravimetric density, while steel cylinders retain industrial process share where weight sensitivity is lower. Metal hydride storage technology occupies a niche in portable power and backup systems where ambient-temperature discharge eliminates cryogenic infrastructure.
DOT and ISO standards govern cylinder design, testing, and recertification intervals in the United States, while ECHA's REACH framework and the EU's F-Gas Regulation shape material compliance and end-of-life protocols across Europe. Japan's METI enforces JIS standards that accelerate Type IV adoption in fuel cell buses and commercial vehicles. Stakeholders must weigh regional certification divergence against platform standardization economics as fleet operators scale cross-border deployments.
Market Dynamics
Type IV composite cylinder manufacturing is consolidating around automated filament winding capabilities as fleet operators demand lighter storage systems for heavy-duty hydrogen mobility. This technology shift compresses cost curves while fragmenting competitive positioning between capital-intensive specialists and legacy metal vessel producers.
Growth Catalysts
- EU Green Deal hydrogen backbone:Germany's fuel cell bus and truck fleets are scaling cylinder procurement under binding national hydrogen import targets. Fleet tenders now specify 700-bar Type IV systems as baseline.
- METI hydrogen roadmap:Japan's commercial vehicle segment is accelerating composite cylinder adoption through JIS-certified designs for fuel cell buses and heavy trucks.
- Carbon-fiber-reinforced polymer advances:Improved tow placement precision is reducing fiber scrap rates in high-pressure vessel production, narrowing the cost gap with steel alternatives.
Market Restraints
- Carbon fiber supply concentration:Aerospace-grade fiber production clusters in Japan, the United States, and Germany, exposing cylinder manufacturers to allocation risk during demand surges.
- DOT recertification burden:United States operators face 15-year cylinder retirement mandates and costly hydrostatic retest protocols that inflate total cost of ownership.
- Metal hydride niche competition:Ambient-temperature solid-state storage systems capture portable power and backup applications where cryogenic infrastructure is uneconomical.
Strategic Opportunities
- Subscription recertification services:Predictive maintenance platforms for cylinder fleets create recurring revenue streams alongside hardware sales in Germany and Japan.
- Rail OEM integration:TÜV-certified high-pressure systems for hydrogen locomotives remain underpenetrated in European rail networks.
- Stationary storage hybridization:Composite cylinders paired with electrolyzer installations offer buffer capacity for renewable hydrogen production sites.
Industry Challenges
- Filament winding technician scarcity:Automated production lines still require specialized operators for carbon fiber placement and quality verification.
- Cross-border certification divergence:DOT, ISO, and JIS testing protocols create friction for cylinder suppliers serving multinational fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Storage Cylinders Market |
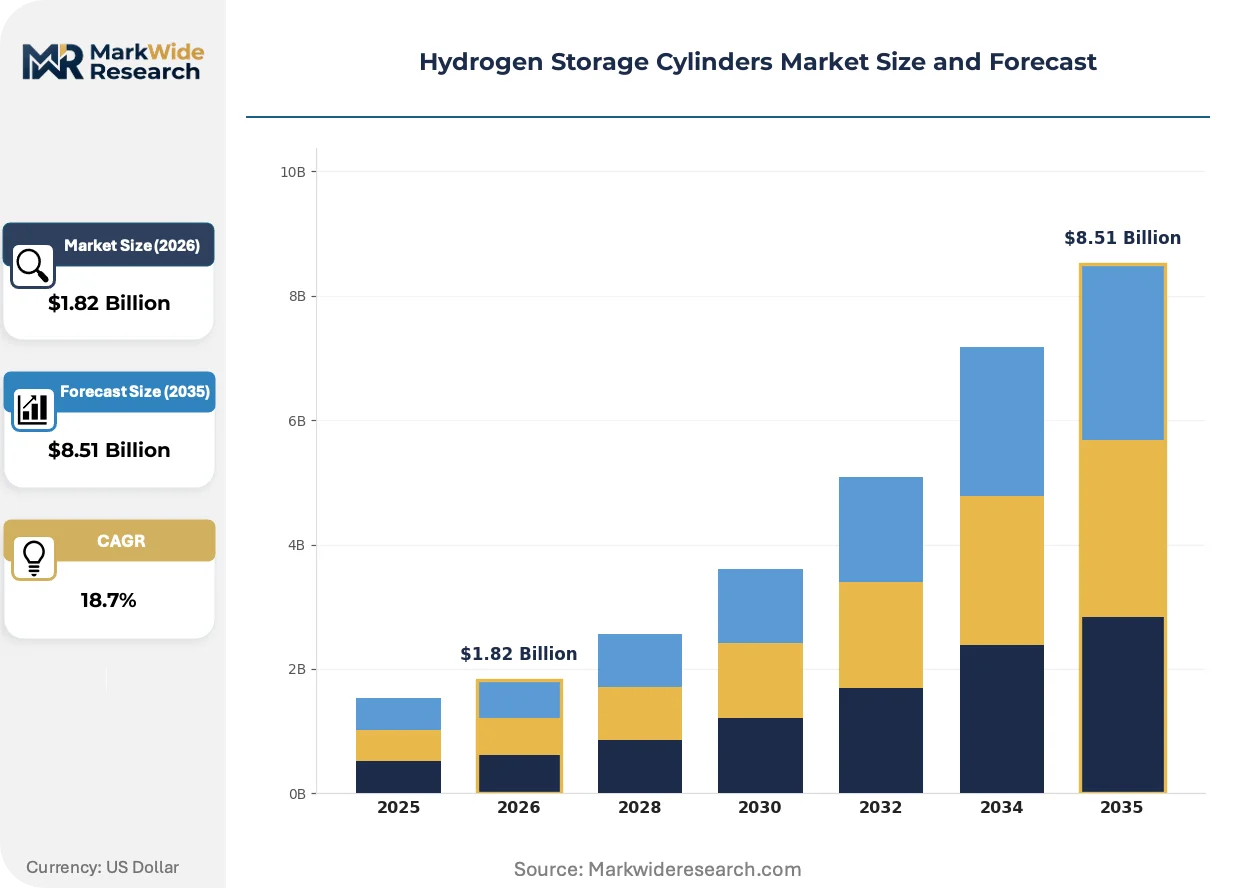
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $8.51 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Cylinders, Steel Cylinders, Aluminum Cylinders, Liner-Based Cylinders Technology: Compressed Hydrogen Storage, Liquid Hydrogen Storage, Metal Hydride Storage, Chemical Hydrogen Storage End User: Transportation, Industrial, Power Generation, Aerospace Application: Fuel Cell Vehicles, Backup Power Systems, Portable Power, Industrial Processes |
| Companies Covered | Hexagon Composites, Worthington Industries, Luxfer Holdings, Air Liquide, Quantum Fuel Systems, NPROXX, Faber Industrie, Linde, Plastic Omnium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Storage Cylinders Market Trends and Innovations
Manufacturing automation and materials science are compressing production timelines for high-pressure hydrogen vessels while regulatory frameworks harden around safety and traceability requirements. These forces are reshaping competitive positioning across the value chain.
Type IV carbon-fiber-reinforced polymer liner technology is consolidating as the dominant architecture for 700-bar transportation applications. Heavy-duty truck and bus OEMs in Germany and Japan are specifying all-composite designs to maximize gravimetric storage density. This shift is consolidating procurement around suppliers with captive automated winding capacity and certified polymer liner extrusion.
REACH framework amendments and the EU F-Gas Regulation are tightening material compliance and end-of-life protocols for polymer-lined cylinders across Europe. Manufacturers must now document full substance traceability and recycling pathways to maintain market access. German and French fleet operators are responding by embedding circularity requirements into tender specifications.
Fleet operators are unbundling cylinder procurement from vehicle platform purchases, creating dedicated hydrogen infrastructure procurement functions. This disintermediation of traditional OEM supply chains is compressing pricing negotiation cycles and elevating certification transparency as a selection criterion. The pattern is most visible in German commercial vehicle leasing pools and Japanese fuel cell bus consortia.
Hydrogen Storage Cylinders Market Segmentation
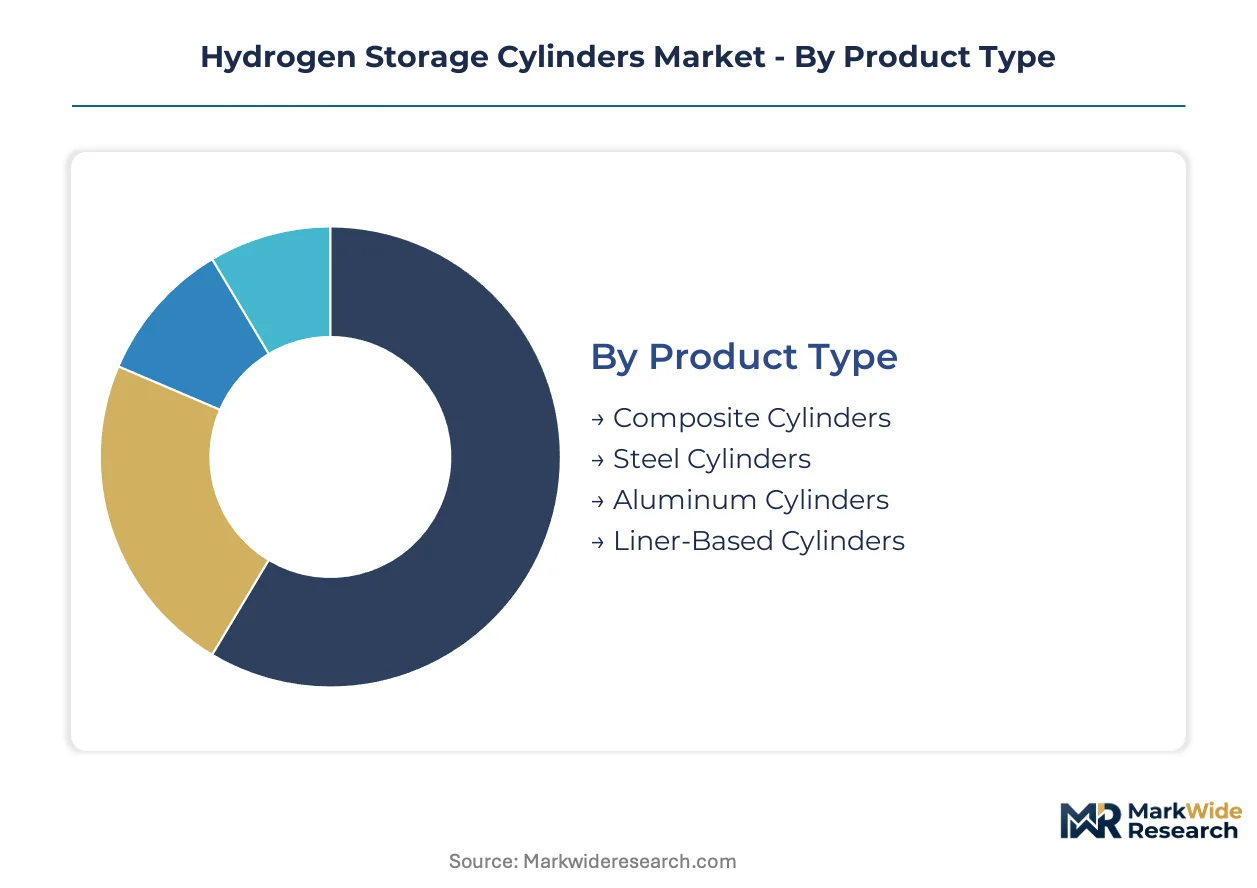
Segmentation in hydrogen storage cylinders maps directly to certification pathways and total cost of ownership calculations. Fleet operators match cylinder specifications to pressure requirements, duty cycles, and regional compliance mandates.
Product Type:
Type IV composite cylinders require ISO 19881 and UNR 134 certification for 700-bar transportation use, while steel alternatives fall under simpler DOT 3AA protocols for industrial stationary storage.
- Composite Cylinders:Carbon-fiber-reinforced polymer construction with thermoplastic liners delivers gravimetric densities exceeding 5.7 wt% hydrogen. German fuel cell bus fleets and Japanese heavy-duty truck OEMs specify these exclusively for 700-bar systems under JIS and TÜV certification schemes.
- Steel Cylinders:Seamless chromium-molybdenum construction withstands 350-bar operating pressures with minimal fiber allocation risk. Industrial process operators in Germany retain these for stationary buffer storage where weight penalties are irrelevant and DOT recertification costs are amortized over fifteen-year lifecycles.
- Aluminum Cylinders:Seamless aluminum alloy vessels with polymer liners occupy mid-pressure niches in portable power applications.
- Liner-Based Cylinders:Polymer-lined aluminum or steel hybrids target cost-sensitive transportation pilots transitioning from steel to full composite architectures.
Composite cylinders sit at the top of the volume ranking, with liner-based configurations climbing the fastest as procurement teams hedge fiber price volatility.
Technology:
Technology selection determines infrastructure requirements and thermodynamic efficiency trade-offs across mobile and stationary deployments.
- Compressed Hydrogen Storage:Gaseous containment at 350-700 bar dominates transportation economics. German and Japanese fleet tenders specify 700-bar Type IV systems exclusively for fuel cell buses and heavy trucks, with METI's hydrogen roadmap accelerating JIS-certified adoption timelines.
- Liquid Hydrogen Storage:Cryogenic systems at -253°C enable dense maritime and aerospace applications. Japanese port infrastructure and German hydrogen import terminals are scaling LH2 bunkering capacity under EU Green Deal hydrogen backbone targets.
- Metal Hydride Storage:Solid-state absorption releases hydrogen at ambient temperatures without compression infrastructure. Backup power installations in German industrial parks favor these for silent discharge and minimal maintenance protocols.
- Chemical Hydrogen Storage:Liquid organic hydrogen carriers and ammonia cracking systems target long-duration maritime transport where conventional compression is uneconomical.
Compressed hydrogen storage holds the dominant volume position, with liquid hydrogen storage gaining share fastest in maritime and aerospace niches.
End User:
End-user concentration shapes procurement scale and certification stringency across the value chain.
- Transportation:Fuel cell vehicle OEMs and fleet operators drive composite cylinder demand through binding decarbonization mandates. German commercial vehicle leasing pools and Japanese fuel cell bus consortia now maintain dedicated hydrogen infrastructure procurement functions separate from vehicle platform purchases.
- Industrial:Refinery hydrogen delivery and ammonia production facilities utilize steel cylinders for process buffer storage. German chemical clusters integrate cylinder farms with electrolyzer installations under EU F-Gas Regulation material compliance requirements.
- Power Generation:Grid-scale hydrogen storage for renewable balancing commands premium certification tiers.
- Aerospace:Satellite and drone propulsion systems require ultra-lightweight containment with specialized aerospace-grade fiber specifications.
Transportation commands the largest procurement volumes, with power generation expanding most quickly as renewable hydrogen storage scales.
Application:
Application segmentation aligns cylinder specifications to duty cycle intensity and discharge rate requirements.
- Fuel Cell Vehicles:Heavy-duty trucks and buses require 700-bar Type IV systems with rapid-fill protocols. German fleet tenders now specify all-composite designs as baseline, while Japanese METI enforcement of JIS standards accelerates domestic adoption curves.
- Backup Power Systems:Telecommunications and data center operators favor metal hydride and compressed gas configurations for silent operation. German industrial parks deploy these under REACH framework end-of-life documentation requirements.
- Portable Power:Construction equipment and remote site generators utilize lightweight aluminum and composite cylinders for mobility.
- Industrial Processes:Steel mills and chemical plants employ high-volume steel cylinder arrays for continuous hydrogen feedstock delivery.
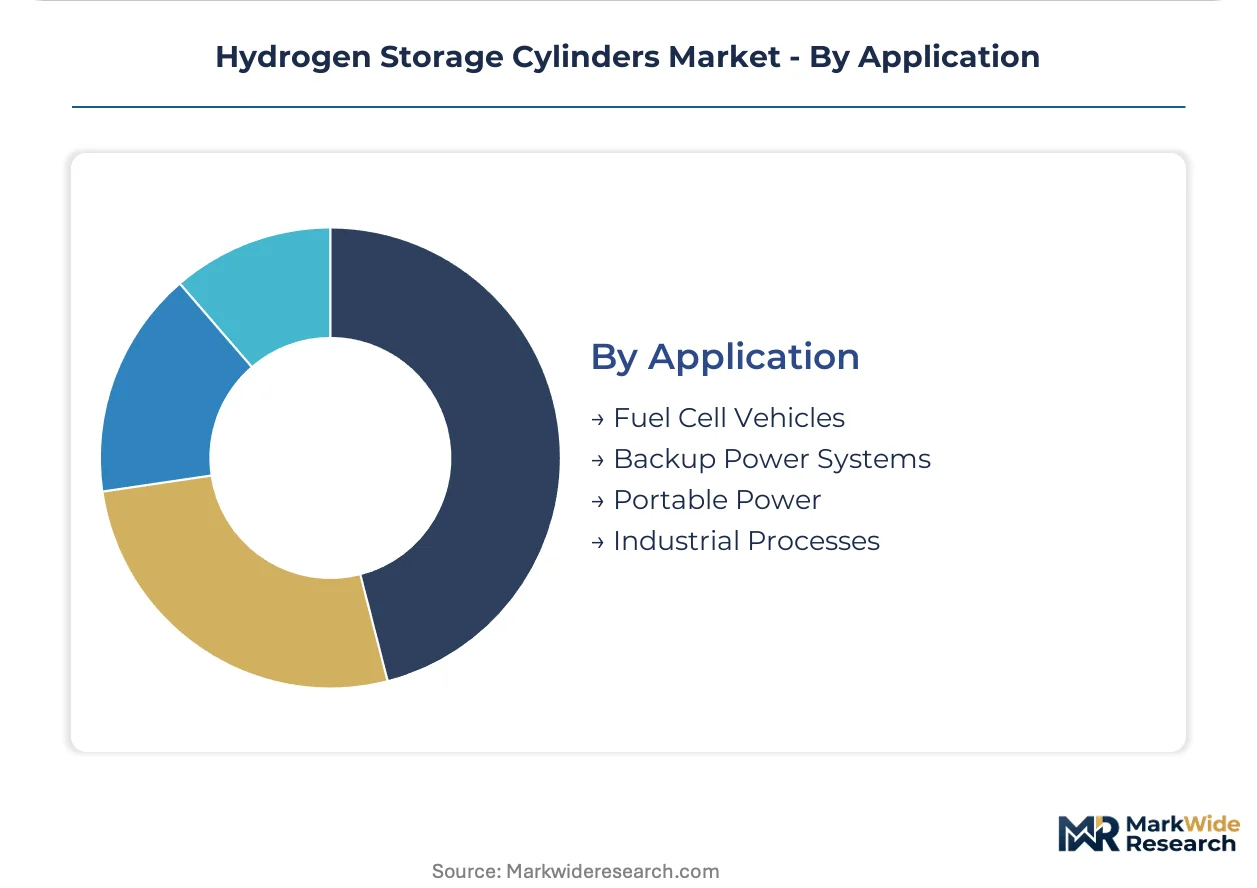
Fuel cell vehicles anchor procurement volumes, with backup power systems showing the steepest expansion trajectory as grid reliability concerns mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as cylinder producers migrate capacity toward jurisdictions with streamlined certification pathways and aligned hydrogen infrastructure subsidies. Cost-of-compliance gaps between DOT, ISO, and JIS regimes now determine where automated winding capacity concentrates.
Germany
Fuel cell bus and heavy truck fleets under KBA oversight are scaling 700-bar Type IV procurement through binding national hydrogen import targets. The EU Green Deal hydrogen backbone mandates cylinder specifications that align with TÜV certification protocols. Industrial clusters in North Rhine-Westphalia integrate cylinder farms with electrolyzer installations under ECHA REACH material compliance requirements.
Japan
METI's hydrogen roadmap accelerates composite cylinder adoption in commercial vehicle segments through JIS-certified design enforcement. Fuel cell bus consortia now maintain dedicated hydrogen infrastructure procurement functions separate from vehicle platform purchases. Manufacturing gravity concentrates in the Chubu region around Nagoya, where filament winding specialists serve heavy-duty transport OEMs.
United States
DOT 15-year cylinder retirement mandates and hydrostatic retest protocols inflate total cost of ownership for fleet operators. NHTSA and DOT standards govern design and recertification intervals that diverge from ISO frameworks. The Gulf Coast hydrogen hub initiative in Texas and Louisiana is attracting cylinder buffer storage deployments for refinery hydrogen delivery networks.
China
MIIT standards and dual carbon goals are accelerating domestic Type IV capacity buildout for fuel cell commercial vehicles. GB standards for high-pressure vessels are converging with ISO protocols to enable export qualification. Manufacturing clusters in the Yangtze River Delta around Shanghai are scaling automated winding lines to serve both domestic bus fleets and European export contracts.
South Korea
MFDS and national hydrogen economy roadmap targets are driving cylinder demand for fuel cell heavy trucks and port equipment. Seoul Capital Area fleet operators are specifying 700-bar composite systems for urban logistics decarbonization. Busan-Ulsan industrial corridors integrate cylinder storage with hydrogen import terminal infrastructure under government-backed hydrogen cluster initiatives.
Hydrogen Storage Cylinders Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with capital-intensive composite winding operations consolidating around automated production platforms while legacy metal vessel producers defend industrial process niches. The structure tilts toward tiered concentration: filament winding specialists with captive polymer liner extrusion command premium positioning in transportation, steel cylinder fabricators anchor stationary storage economics, and hybrid aluminum-composite producers occupy mid-pressure transition segments. Dominant competitive moves include backward integration into carbon fiber supply arrangements and strategic partnerships with rail and bus OEMs for TÜV-certified system integration.
Among Norwegian and North American composite specialists, Hexagon Composites and Worthington Industries exemplify divergent scale strategies in high-pressure vessel manufacturing. Hexagon's automated filament winding capacity anchors Type IV output for heavy mobility applications, while Worthington's backward integration into steel processing secures cost positioning in industrial cylinder arrays. NPROXX occupies a specialist position within the TÜV-certified rail and bus OEM integration tier, representing the high-pressure systems archetype for European hydrogen locomotive deployments.
| Leading Market Players |
|---|
| Hexagon Composites |
| Worthington Industries |
| Luxfer Holdings |
| Air Liquide |
| Quantum Fuel Systems |
| NPROXX |
| Faber Industrie |
| Linde |
| Plastic Omnium |
| Others |
Pricing and Supply Chain Analysis
German fuel cell bus fleet operators and Japanese commercial vehicle consortia concentrate procurement volume, forcing suppliers toward subscription-based recertification bundles that embed predictive maintenance alongside hardware transactions. This buyer archetype consolidation compresses pricing negotiation cycles while elevating certification transparency as a primary selection criterion.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for Type IV composite cylinders as automated filament winding lines achieve scale. Three-tier pricing structure across premium, standard, and economy levels separates TÜV-certified rail systems from JIS-compliant bus configurations and uncertified industrial steel alternatives. Pricing pressure stems from carbon fiber allocation risk during aerospace demand surges. Industrial process operators exhibit highest price sensitivity due to fifteen-year DOT recertification cost amortization, while rail OEMs accept premium positioning for TÜV-certified integration.
Supply Chain Analysis
Refurbishment flows for DOT-mandated cylinder retirement create reverse logistics complexity as German and United States operators face fifteen-year hardware lifecycles. Manufacturing gravity centers on Japan, Germany, and China for carbon fiber supply and filament winding capacity. Raw material dependencies include aerospace-grade carbon fiber tow, thermoplastic liner polymers, and chromium-molybdenum steel billet. Single-source vulnerability concentrates in Japanese aerospace fiber production. Distribution runs through dedicated hydrogen infrastructure procurement functions that German and Japanese fleet operators have separated from vehicle platform purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where binding EU Green Deal hydrogen backbone targets and METI roadmap enforcement create demand visibility that transcends commodity cyclicality.
For Market Incumbents:Lock in captive carbon fiber supply arrangements with Japanese and German aerospace-grade producers before allocation crunches intensify. Expand automated winding capacity in the Chubu region to serve METI-accelerated commercial vehicle adoption. Metal hydride solid-state substitutes threaten portable power and backup segments where ambient-temperature discharge eliminates compression infrastructure.
For New Entrants and Emerging Players:The premium-to-economy price gap in TÜV-certified rail systems offers white-space entry as European hydrogen locomotive deployments remain underpenetrated. Target stationary storage hybridization where composite cylinders pair with electrolyzer buffer installations under EU F-Gas Regulation compliance requirements. Pursue JIS certification partnerships with Nagoya-area winding specialists as the fastest go-to-market pathway.
For Investors and Strategic Acquirers:Rail OEMs and hydrogen locomotive integrators represent the most active acquirer category in this space as TÜV-certified system demand outpaces captive supply. Five-to-ten year viability hinges on filament winding technician pipeline development and cross-border certification harmonization. Monitor EU REACH framework amendments and F-Gas Regulation enforcement intensity as inflection indicators for polymer-lined cylinder material compliance costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Supply | Secures allocation priority during aerospace demand surges from Japanese producers. |
| TÜV Certification Investment for Rail Systems | Unlocks European hydrogen locomotive procurement under KBA oversight requirements. |
| Subscription Recertification Platform Launch | Captures recurring revenue from German fleet operator fifteen-year DOT mandates. |
| JIS Certification Partnership in Chubu Region | Accelerates METI roadmap compliance for Japanese fuel cell bus consortia. |
| Stationary Storage Hybridization Development | Positions composite cylinders for electrolyzer buffer installations under EU Green Deal targets. |
Research Methodology
Multiple input streams — primary interviews with filament winding specialists, fleet procurement directors, and TÜV certification engineers; secondary validation through KBA registration databases, METI hydrogen roadmap disclosures, and ECHA REACH substance tracking; plus customs records for carbon fiber trade flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including cylinder type architecture, pressure tier certification, end-use application intensity, and regional regulatory framework clustering. CAGRs were derived from installed base expansion curves and replacement cycle analysis. Forecast inputs incorporated EU hydrogen import target binding commitments and JIS standard enforcement timelines.
Caveats apply where carbon fiber supply allocation shocks or divergence between DOT, ISO, and JIS recertification protocols could materially shift the outlook. Practitioners should monitor EU F-Gas Regulation amendment progress and METI hydrogen roadmap revision signals for early indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Marine Energy Storage System Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Power Bank Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Water Electrolysis Machine Market
Energy Storage
Battery Storage Inverter Market