
 Grid Scale Battery Storage Sales Market | 2026-2036
Grid Scale Battery Storage Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Grid Scale Battery Storage Sales Market Insights
Lithium iron phosphate chemistry is realigning cost structures across grid-scale deployments by displacing nickel-cobalt-manganese formulations in duration applications. CATL leverages massive manufacturing scale to dominate the LFP supply chain for utility projects. Tesla Energy sustains technology leadership through integrated power electronics and software stacks. Fluence Energy differentiates via its AI-driven optimization platform that controls dispatch across multiple battery technologies.
Grid scale battery storage encompasses electrochemical systems rated at one megawatt or above, designed for frequency regulation, peak shaving, and renewable firming through charge-discharge cycles lasting two to eight hours. These installations interface with high-voltage transmission infrastructure and require power conversion systems capable of four-quadrant operation. Lithium-ion products capture the dominant share of new capacity additions due to declining cell costs and proven cycle life. Flow batteries occupy a specialized position in long-duration segments where discharge requirements exceed six hours. Energy Management Systems represent a critical margin pool as software layers determine revenue optimization across energy, capacity, and ancillary service markets.
FERC, China's National Energy Administration, and Germany's Bundesnetzagentur each shape market access rules that determine how battery assets monetize grid services. FERC Order 841 and Order 2222 specifically mandate that regional transmission organizations and independent system operators establish participation models for electric storage resources. Stakeholders must monitor evolving capacity market designs and carbon border adjustments that will determine project economics and technology selection across jurisdictions.
Market Dynamics
Lithium iron phosphate chemistry is compressing project economics across utility-scale deployments by displacing nickel-cobalt-manganese formulations in four-to-eight-hour duration applications. This chemistry shift is reshaping supplier hierarchies and procurement criteria for independent power producers.
Growth Catalysts
- FERC Order 2222:Aggregated battery resources now access wholesale electricity markets in the United States, creating new revenue streams for distributed storage assets.
- Renewable intermittency:Wind and solar generation volatility in Germany, China, and the United States is forcing grid operators to procure multi-gigawatt storage portfolios for firming services.
- LFP manufacturing scale:Gigafactory expansion across battery cell production is driving down unit costs for utility project developers.
Market Restraints
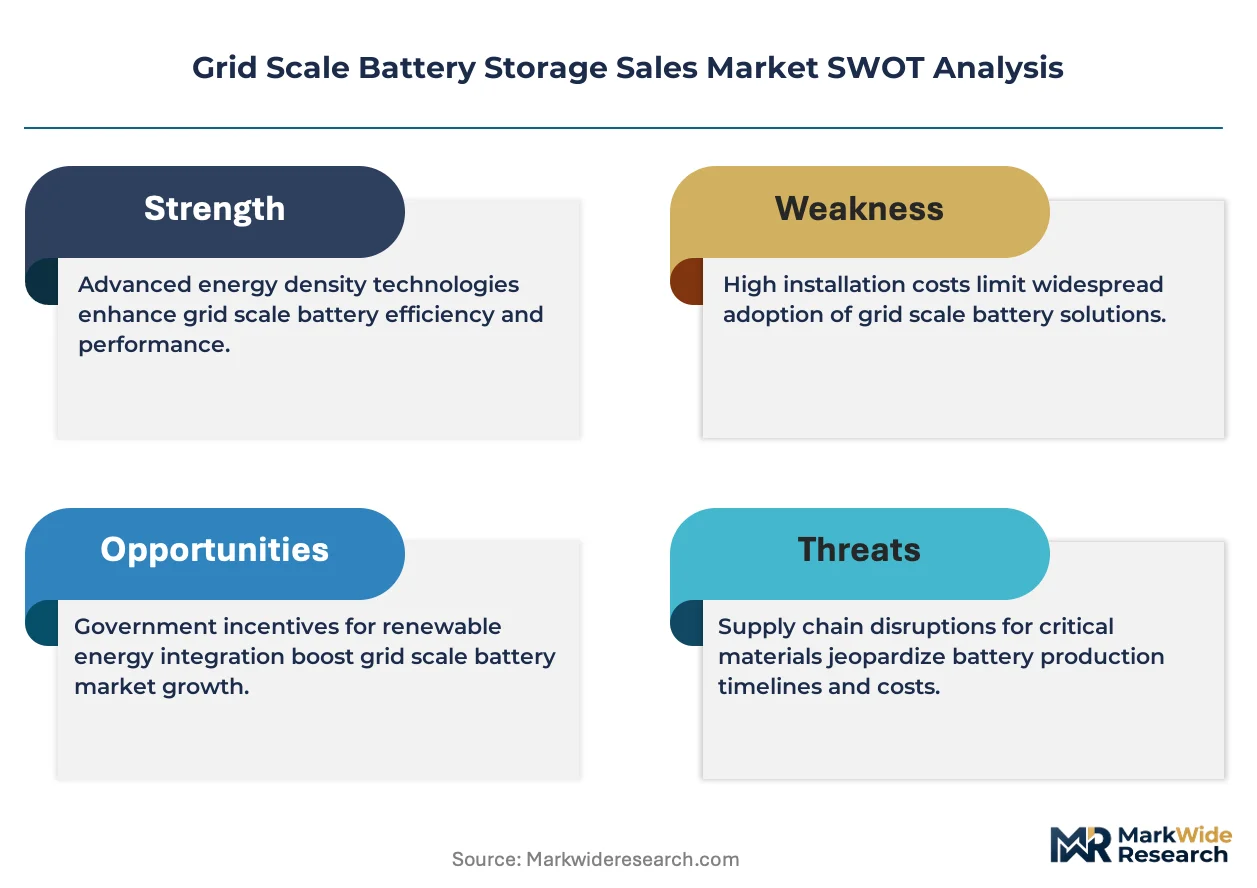
- Lithium carbonate volatility:Raw material price swings from South American and Australian concentrate suppliers destabilize project finance assumptions.
- Supply concentration:Cathode active material production clusters in China create geopolitical exposure for developers in North America and Europe.
- Duration ceiling:Lithium-ion electrochemistry faces fundamental energy density limits beyond eight-hour discharge, constraining long-duration applications.
Strategic Opportunities
- India storage procurement:State electricity distribution companies are issuing tenders for grid-connected battery systems to manage evening peak demand.
- Flow battery hybridization:Vanadium redox systems paired with lithium-ion front-ends capture both high-power and long-duration revenue stacks.
- Behind-the-meter aggregation:Commercial and industrial battery fleets participating in demand response programs unlock ancillary service revenues previously reserved for utility assets.
Industry Challenges
- Power electronics integration:Four-quadrant inverter commissioning requires scarce field engineering talent familiar with high-voltage substation protocols.
- Fire safety certification:UL 9540A test protocol completion timelines extend project development schedules by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid Scale Battery Storage Sales Market |
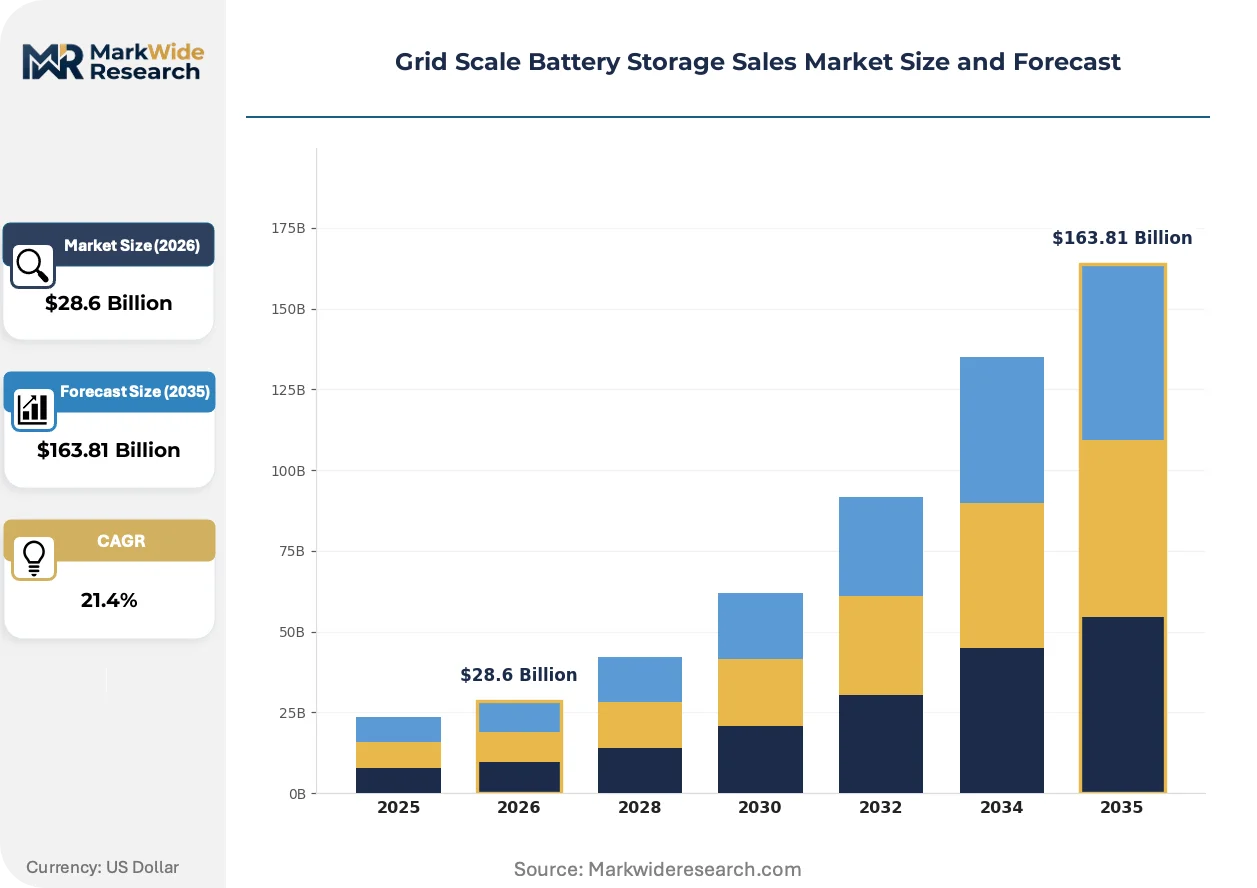
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $163.81 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Flow Batteries, Nickel-Cadmium Technology: Energy Management Systems, Battery Management Systems, Thermal Management Systems, Power Conversion Systems End User: Utility Companies, Industrial Applications, Commercial Facilities, Renewable Energy Integrators Installation: Onsite, Offsite, Modular, Centralized |
| Companies Covered | CATL, LG Energy Solution, Tesla Energy, Fluence Energy, BYD, Samsung SDI, Sumitomo Electric Industries, NGK Insulators, GS Yuasa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid Scale Battery Storage Sales Market Trends and Innovations
Solid-state battery architectures and artificial intelligence-driven dispatch optimization are converging to redefine performance benchmarks for grid-connected storage. These developments are compressing technology refresh cycles and expanding addressable revenue streams.
Solid-state electrolyte technology is integrating ceramic and polymer composite separators to eliminate thermal runaway risks in high-density cell configurations. Utility developers in California and Texas are piloting these systems for urban substation deployments where fire safety codes are most stringent. The technology is integrating passive safety features that reduce balance-of-plant costs and enable indoor installation options previously unavailable to lithium-ion systems.
China's National Energy Administration has mandated grid-forming inverter capabilities for new battery interconnects above 50 megawatts, requiring frequency support functions beyond simple energy arbitrage. This policy compresses the supplier base to firms with advanced power electronics expertise. Project developers are responding by restructuring procurement specifications to prioritize grid-code compliance over standalone cell cost metrics.
Merchant storage developers are unbundling energy management software from hardware supply contracts, creating standalone procurement channels for optimization platforms. This shift fragments the traditional integrated system vendor model and exposes hardware suppliers to margin compression. The unbundling is most advanced in Texas ERCOT and United Kingdom balancing markets where algorithmic trading sophistication determines project returns.
Grid Scale Battery Storage Sales Market Segmentation
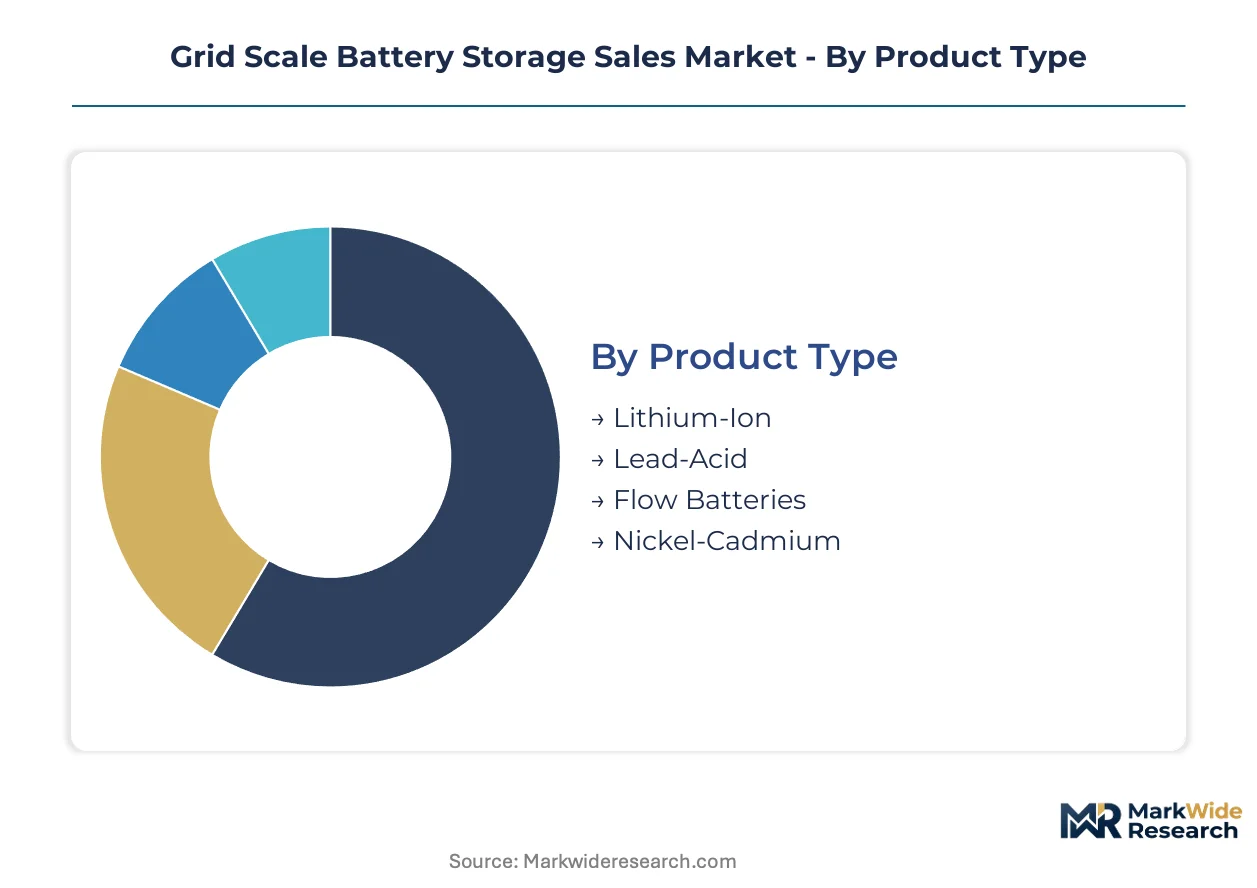
Technology selection in grid-scale storage hinges on discharge duration requirements and revenue stack composition. Procurement patterns diverge sharply between frequency regulation markets favoring high-power systems and renewable firming applications demanding multi-hour duration.
Product Type:
Lithium-ion systems command volume leadership while flow batteries capture premium positioning in long-duration niches.
- Lithium-Ion:Lithium iron phosphate chemistry dominates four-to-eight-hour utility deployments through manufacturing scale advantages. Procurement concentrates in Texas ERCOT and California CAISO markets where energy arbitrage and ancillary service revenues justify capital intensity. CATL and Tesla Energy supply chains anchor project development timelines.
- Flow Batteries:Vanadium redox systems eliminate capacity fade across 20-year operational lifespans. Demand clusters in Germany and Japan where six-hour-plus discharge requirements exceed lithium-ion energy density limits. Utility procurement in these markets prioritizes duration over power density.
- Lead-Acid:Mature recycling infrastructure supports limited grid stabilization roles in emerging markets with constrained capital budgets.
- Nickel-Cadmium:Extreme temperature tolerance sustains niche deployments in Middle Eastern substation applications where ambient conditions degrade lithium-ion performance.
Today's leader: Lithium-Ion. Tomorrow's challenger: Flow Batteries.
Technology:
Software layers are capturing margin expansion as hardware commoditizes across cell supply chains.
- Energy Management Systems:Algorithmic dispatch optimization determines revenue capture across energy, capacity, and frequency regulation markets. Fluence Energy and Tesla Autobidder platforms differentiate through machine learning-driven bidding strategies. Merchant developers in United Kingdom and Texas markets unbundle EMS procurement from hardware contracts.
- Power Conversion Systems:Four-quadrant inverters enable grid-forming capabilities mandated by China's National Energy Administration for interconnects above 50 megawatts. Supplier concentration in power electronics expertise compresses procurement options for project developers.
- Battery Management Systems:Cell-level monitoring prevents thermal runaway propagation across utility-scale arrays.
- Thermal Management Systems:Liquid cooling architectures extend cycle life in high-C-rate applications.
Software-defined revenue optimization is expanding fastest, while power electronics integration remains the critical path constraint.
End User:
Utility procurement drives volume scale as commercial aggregation models fragment traditional customer structures.
- Utility Companies:Independent power producers and grid operators deploy multi-gigawatt portfolios to manage intermittency from wind and solar generation. FERC Order 841 mandates participation models enabling storage resources in wholesale markets. Procurement in United States, China, and Germany concentrates capacity additions.
- Renewable Energy Integrators:Solar-plus-storage and wind-plus-storage hybrids require DC-coupled architectures optimizing round-trip efficiency. Developers in California and Australia prioritize co-located configurations capturing investment tax credit stacking.
- Industrial Applications:C&I battery fleets participate in demand response programs through FERC Order 2222 aggregation frameworks.
- Commercial Facilities:Behind-the-meter installations target peak demand charge reduction and backup power resilience.
Utility-scale procurement anchors current deployment volumes. Aggregated distributed resources are climbing the fastest.
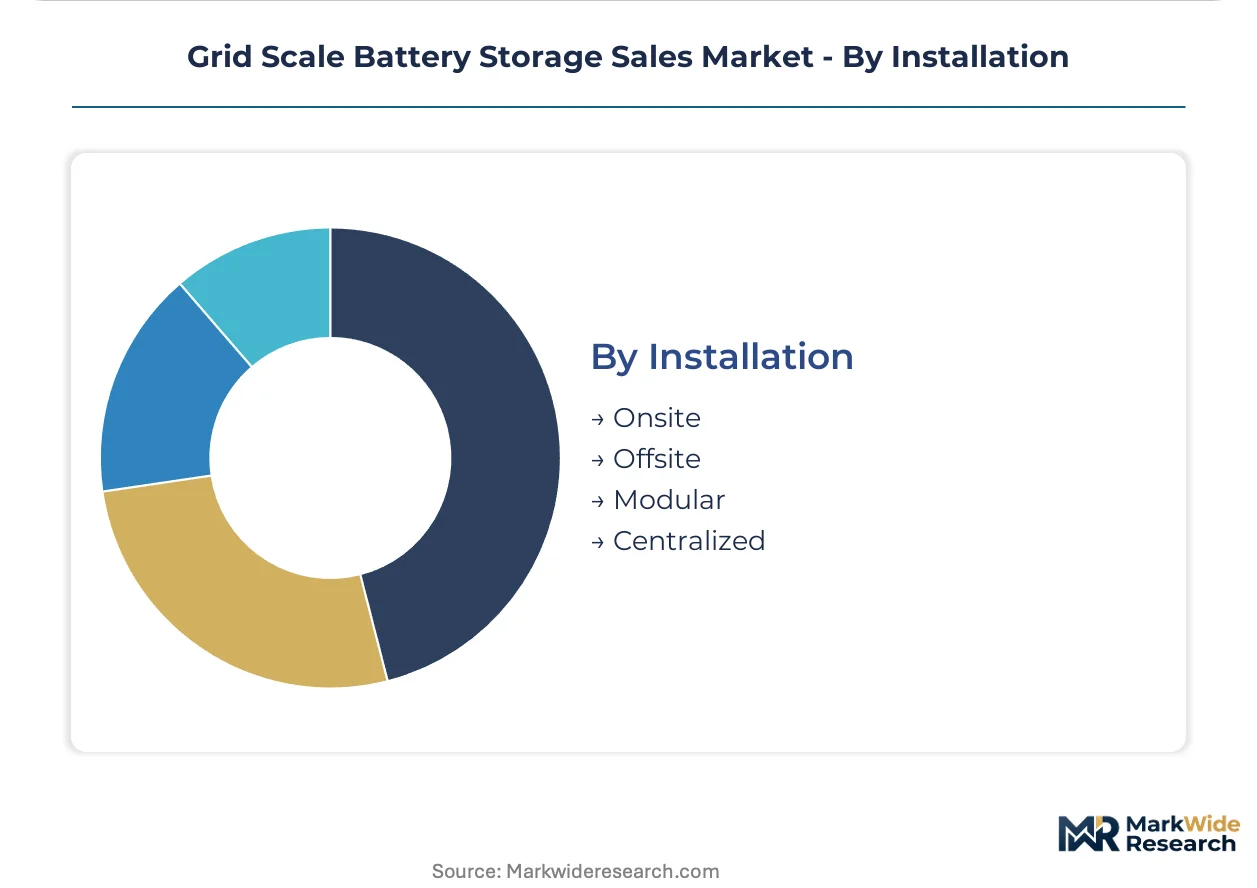
Installation:
Modular architectures are displacing centralized designs as project developers prioritize construction risk mitigation.
- Modular:Containerized 2-5 megawatt building blocks enable phased commissioning and technology refresh flexibility. Procurement specifications in United States and European markets increasingly mandate factory-integrated systems reducing field assembly complexity. Fluence and Tesla Energy compete on deployment velocity metrics.
- Centralized:Single-site 100+ megawatt installations optimize land use and interconnection costs for utility-scale portfolios. China's State Grid and Southern Power Grid deploy centralized configurations in provincial renewable bases.
- Onsite:Co-location with generation assets minimizes transmission upgrade requirements.
- Offsite:Standalone storage connects at transmission nodes providing system-wide grid services.
Modular approaches dominate new procurement. Centralized configurations retain share in utility-direct programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas anchors grid-scale battery deployment through ERCOT's merchant market structure and transmission congestion pricing. Independent power producers in the state have procured multi-gigawatt storage portfolios to capture energy arbitrage and ancillary service revenues. FERC Order 841 mandates participation models that enable these assets in wholesale electricity markets.
United States
California's CAISO market drives procurement through resource adequacy requirements and solar-plus-storage investment tax credit stacking. FERC Order 2222 enables aggregated distributed resources to access wholesale markets. The Imperial Valley and Lancaster clusters concentrate utility-scale deployments co-located with photovoltaic generation.
China
Provincial renewable bases in Qinghai and Xinjiang mandate storage co-location with wind and solar installations. The National Energy Administration requires grid-forming inverter capabilities for interconnects above 50 megawatts. CATL's manufacturing concentration in Fujian and Tesla's Shanghai Gigafactory anchor cell supply chains serving domestic project pipelines.
Germany
The Bundesnetzagentur implements capacity market designs and grid stability auctions that remunerate frequency regulation services. Industrial clusters in North Rhine-Westphalia and Bavaria deploy vanadium redox systems for six-hour-plus discharge requirements. Renewable intermittency from the Energiewende drives multi-gigawatt storage procurement targets.
India
State electricity distribution companies in Gujarat and Rajasthan issue tenders for grid-connected systems managing evening peak demand. The Central Electricity Authority mandates storage obligations for solar and wind project developers. Manufacturing incentives under the PLI scheme attract cell production investment in Tamil Nadu and Telangana.
Australia
The Australian Energy Market Operator integrates battery resources into frequency control ancillary services markets. South Australia's Hornsdale Power Reserve demonstrated grid-scale viability, prompting replication in New South Wales and Victoria. The National Electricity Law reforms enable aggregated behind-the-meter participation in wholesale dispatch.
Grid Scale Battery Storage Sales Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and software integration dimensions. The supplier base concentrates around three strategic archetypes: integrated cell-to-system vendors, pure-play energy management platforms, and industrial conglomerates with captive battery divisions. Dominant competitive moves include backward integration into cathode active material production and unbundling of software procurement from hardware supply contracts.
Within the integrated-system tier, CATL, Tesla Energy, and Fluence Energy exemplify divergent approaches to value capture. CATL occupies a position anchored in manufacturing scale advantages for lithium iron phosphate chemistry. Tesla Energy sits within the software-hardware convergence archetype through power electronics and dispatch optimization integration. Fluence Energy represents the platform-specialist model with AI-driven bidding strategies across multiple battery technologies. Regional specialists including LG Energy Solution and Samsung SDI maintain positions in premium-tier procurements where cycle life and warranty terms determine selection criteria.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Tesla Energy |
| Fluence Energy |
| BYD |
| Samsung SDI |
| Sumitomo Electric Industries |
| NGK Insulators |
| GS Yuasa |
| Others |
Pricing and Supply Chain Analysis
Lithium iron phosphate manufacturing scale-up across gigafactory complexes in China and North America compresses unit economics while concentrating cathode active material production in Fujian and Sichuan provinces. This chemistry transition simultaneously erodes nickel-cobalt-manganese premium positioning and exposes developers to single-source procurement exposure for processed lithium carbonate.
Pricing Analysis
Input-cost pass-through from South American and Australian spodumene concentrate suppliers dominates project finance structures, with lithium carbonate volatility destabilizing developer margins. Three-tier pricing structure across premium, standard, and economy levels separates grid-forming inverter bundles from basic energy arbitrage configurations from refurbished cell assemblies. Pricing pressure stems from CATL's manufacturing scale advantages compressing hardware margins. Merchant developers in Texas ERCOT exhibit highest price sensitivity, while German utility-direct procurement prioritizes warranty duration over cell cost.
Supply Chain Analysis
Cathode active material supply rests on Chinese processed lithium carbonate and synthetic graphite production, with South Korean and Japanese suppliers capturing premium-tier power electronics. Raw material dependencies span lithium concentrate from Chile and Australia, processed cobalt from the Democratic Republic of Congo, and separator membranes from Japanese specialty chemical producers. Supply chain risk centers on tariff exposure for North American developers sourcing Chinese-manufactured cells. Distribution runs through EPC contractors and integrated system vendors delivering factory-integrated containerized units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid-scale battery storage functions as a margin-expansion story as lithium iron phosphate chemistry drives hardware commoditization and software layers capture premium pricing. LFP manufacturing scale advantages compress cell costs while algorithmic dispatch platforms extract ancillary service revenues.
For Market Incumbents: Deepen backward integration into cathode active material production to offset lithium carbonate volatility and supply concentration in China. Secure grid-forming inverter certification ahead of China's National Energy Administration mandates to defend against power electronics specialists. Prioritize software unbundling strategies that expose hardware competitors to margin compression. For New Entrants and Emerging Players: Launch via behind-the-meter aggregation platforms targeting commercial and industrial fleets in FERC Order 2222 jurisdictions. India's state electricity distribution company tenders present the most penetrable geography given constrained domestic manufacturing and PLI scheme incentives. Pursue vanadium redox hybridization partnerships to differentiate in six-hour-plus duration segments. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play energy management software vendors unbundled from hardware supply chains. Long-term viability favors platforms with algorithmic trading sophistication across multiple battery chemistries. Watch FERC capacity market design reforms as the inflection signal for merchant storage developer returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | CATL's Fujian complexes demonstrate captive lithium carbonate processing insulating margin from spot volatility. |
| Grid-Forming Inverter Certification | China's National Energy Administration mandates compress supplier base to firms with advanced power electronics expertise. |
| Energy Management Software Unbundling | Texas ERCOT and UK balancing markets fragment integrated vendor models through standalone optimization procurement. |
| Flow Battery Hybridization Partnerships | Vanadium redox front-ends paired with lithium-ion capture both high-power and long-duration revenue stacks. |
| Behind-the-Meter Aggregation Platforms | FERC Order 2222 enables commercial and industrial fleets to access wholesale ancillary service revenues. |
Research Methodology
Direct dialogue with utility planning officers, independent power producer project developers, EPC contractors, and grid operators anchored qualitative assessment, validated against FERC filings, EIA storage deployment databases, IEA renewable integration reports, and regional transmission organization interconnection queues. Secondary sources included customs records for lithium carbonate trade flows and cathode active material production disclosures. Bottom-up project pipeline aggregation triangulated against top-down market sizing from cell manufacturing capacity announcements.
Bottom-up capacity installation tracking across the analysis window modeled technology segmentation by chemistry type, duration class, and grid service revenue stack. Top-down demand assessment incorporated renewable intermittency curves, resource adequacy mandates, and wholesale market price volatility patterns. Segmentation dimensions spanned product type, technology layer, end-user archetype, and installation configuration. CAGRs derived from weighted average of utility procurement trajectories and merchant developer deployment schedules, with sensitivity testing around lithium carbonate price scenarios and inverter lead times.
Several conditions sit outside the modeled scope, including breakthrough solid-state battery commercialization timelines, radical FERC market redesign beyond Order 841 and 2222 implementations, and geopolitical disruption of South American lithium concentrate supply. Forecasts reflect documented assumptions regarding manufacturing scale curves and regulatory stability. A small set of named triggers warrants ongoing watch: China's dual carbon policy acceleration, India PLI scheme manufacturing localization, and Germany's Bundesnetzagentur capacity market reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Marine Energy Storage System Market
Energy Storage
Battery Energy Storage Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Solar Storage System Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Ultracapacitors Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
South America Energy Storage Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Home Solar Energy Storage Battery Market