
 United Kingdom Electric Vehicle Battery Separator Market | 2026-2036
United Kingdom Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Electric Vehicle Battery Separator Market Insights
Solid-state battery development is fragmenting conventional separator architectures across the United Kingdom supply base. Asahi Kasei Corporation anchors polyolefin membrane production for lithium-ion cell manufacturers serving British OEM programs. SK IE Technology leverages ceramic-coated separator expertise to compete in premium electric vehicle platforms assembled at UK plants. Toray Industries sustains R&D intensity around thinner, higher-temperature films that meet next-generation cell chemistry requirements.
Electric vehicle battery separators are microporous or non-woven membranes, typically 5-30 micrometres thick, manufactured from polyethylene or polypropylene through wet or dry stretching processes; their primary function is to prevent electrical short circuits between anode and cathode while permitting ionic transport. Microporous polyolefin films currently dominate installed capacity due to proven cycle life and cost structure, though ceramic-coated variants command margin pools in performance-oriented segments. Passenger vehicle applications absorb the majority of separator volume, while commercial vehicle platforms represent the fastest-growing demand category as fleet electrification accelerates.
The UK's Office for Product Safety and Standards enforces battery safety regulations that directly shape separator thermal stability requirements, while BSI standards alignment with EU REACH and RoHS frameworks governs material composition and chemical compliance. The Department for Transport's automotive transformation fund conditions grant support on domestic supply chain localization, including separator manufacturing. Stakeholders must monitor how evolving solid-state battery timelines reshape separator technology roadmaps and capital allocation decisions.
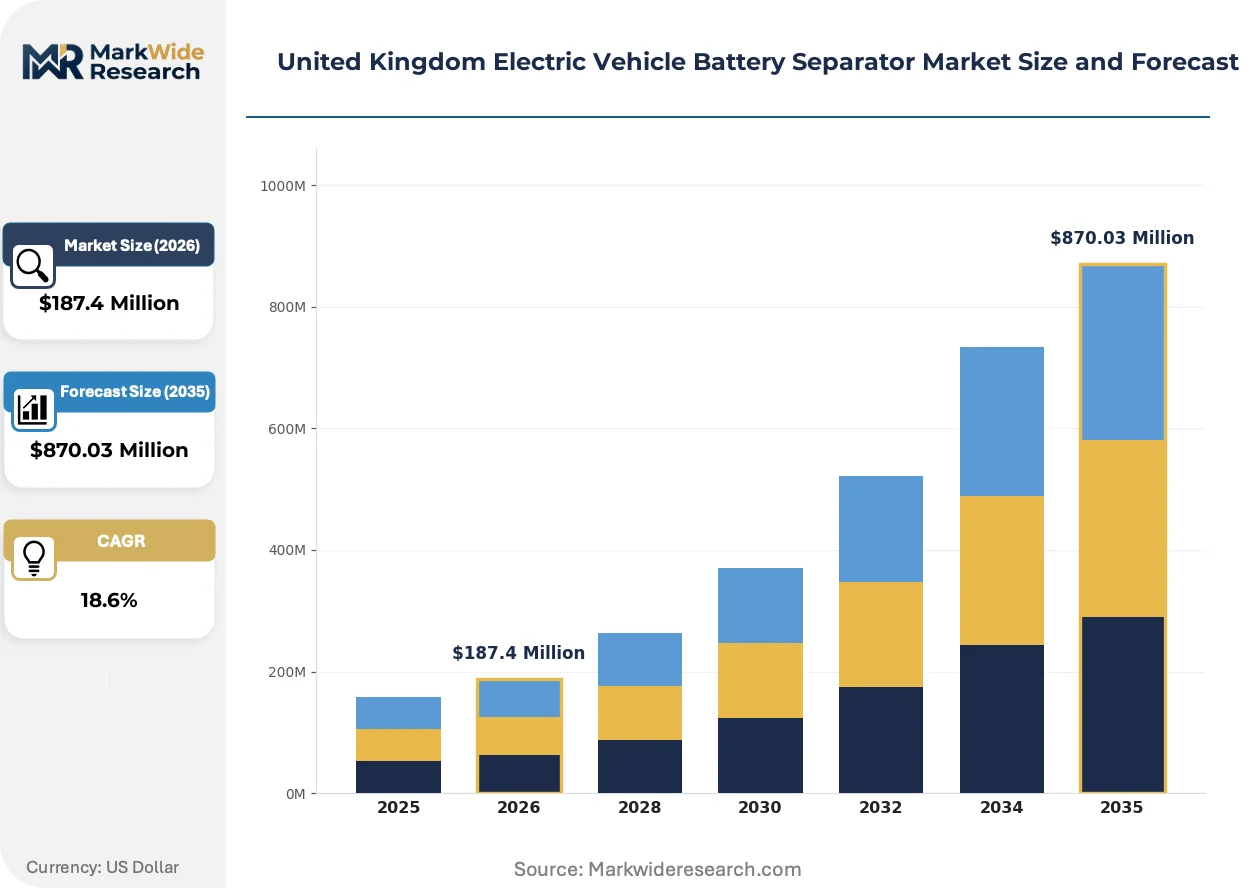
Market Dynamics
The UK's 2030 internal combustion engine sales ban is forcing separator manufacturers to accelerate domestic capacity buildout ahead of projected cell factory commissioning timelines. This regulatory deadline compresses investment cycles and redirects technical roadmaps toward solid-state compatibility.
Growth Catalysts
- Automotive Transformation Fund:The Department for Transport conditions grant disbursement on domestic separator production localization, pulling manufacturing investment into the West Midlands cluster.
- Solid-state battery timelines:Next-generation cell chemistry development is creating demand for ceramic-coated and composite separator architectures that withstand higher operating temperatures.
- Fleet electrification:Commercial vehicle operators are scaling battery procurement faster than passenger OEMs, expanding separator volume requirements for heavy-duty platforms.
Market Restraints
- Polyolefin resin concentration:Feedstock supply depends on a narrow base of petrochemical producers, exposing margins to hydrocarbon price volatility.
- Technical limitation in thickness reduction:Current wet-stretching processes face yield degradation below 7 micrometres, constraining energy density gains for premium cell designs.
- REACH compliance costs:ECHA substance registration requirements add fixed regulatory overhead that disadvantages small-scale domestic entrants against integrated Asian suppliers.
Strategic Opportunities
- Scottish Highlands cell factory corridor:Underdeveloped separator supply infrastructure around planned gigafactory sites offers first-mover positioning for coating and finishing operations.
- Recyclable separator substrates:Technology convergence between bio-based polymers and closed-loop battery recycling creates material differentiation pathways.
- Direct OEM contracting:British cell manufacturers are bypassing distributor networks for separator procurement, enabling margin capture through technical service bundling.
Industry Challenges
- Electrolyte compatibility engineering:Separator-surface chemistry expertise shortages delay qualification timelines for novel high-voltage electrolyte formulations.
- Capex intensity in coating lines:Ceramic deposition equipment requires eight-figure capital commitments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Electric Vehicle Battery Separator Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microporous, Non-Woven, PE, PP End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Production, Assembly, Testing, Quality Control Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | Asahi Kasei Corporation, SK IE Technology, Toray Industries, W-SCOPE Corporation, SEMCORP Co., Sumitomo Chemical Co., Mitsubishi Chemical Group Corporation, UBE Corporation, ENTEK International LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Electric Vehicle Battery Separator Market Trends and Innovations
Solid-state electrolyte development is fragmenting established separator supply relationships across British cell manufacturers. Technical roadmaps now diverge between incremental polymer improvements and radical architecture shifts.
Ceramic-coated polyolefin composites are rendering obsolete conventional uncoated membranes in premium electric vehicle applications. British OEMs specify these variants for 800-volt architectures requiring enhanced thermal runaway resistance. The technology is compressing margin pools for commodity separator producers while elevating technical service requirements.
The UK's Office for Product Safety and Standards is tightening thermal stability testing protocols for separator materials used in passenger vehicle battery packs. Manufacturers must now demonstrate shutdown functionality at elevated temperatures to maintain market access. Premium platform suppliers are responding by accelerating ceramic coating adoption ahead of formal enforcement dates.
Fleet operators are consolidating separator procurement through direct master service agreements with cell manufacturers rather than component distributors. This channel compression eliminates traditional markup layers and shifts technical accountability upstream. The pattern is most visible in West Midlands commercial vehicle electrification programs where volume certainty justifies contract restructuring.
United Kingdom Electric Vehicle Battery Separator Market Segmentation
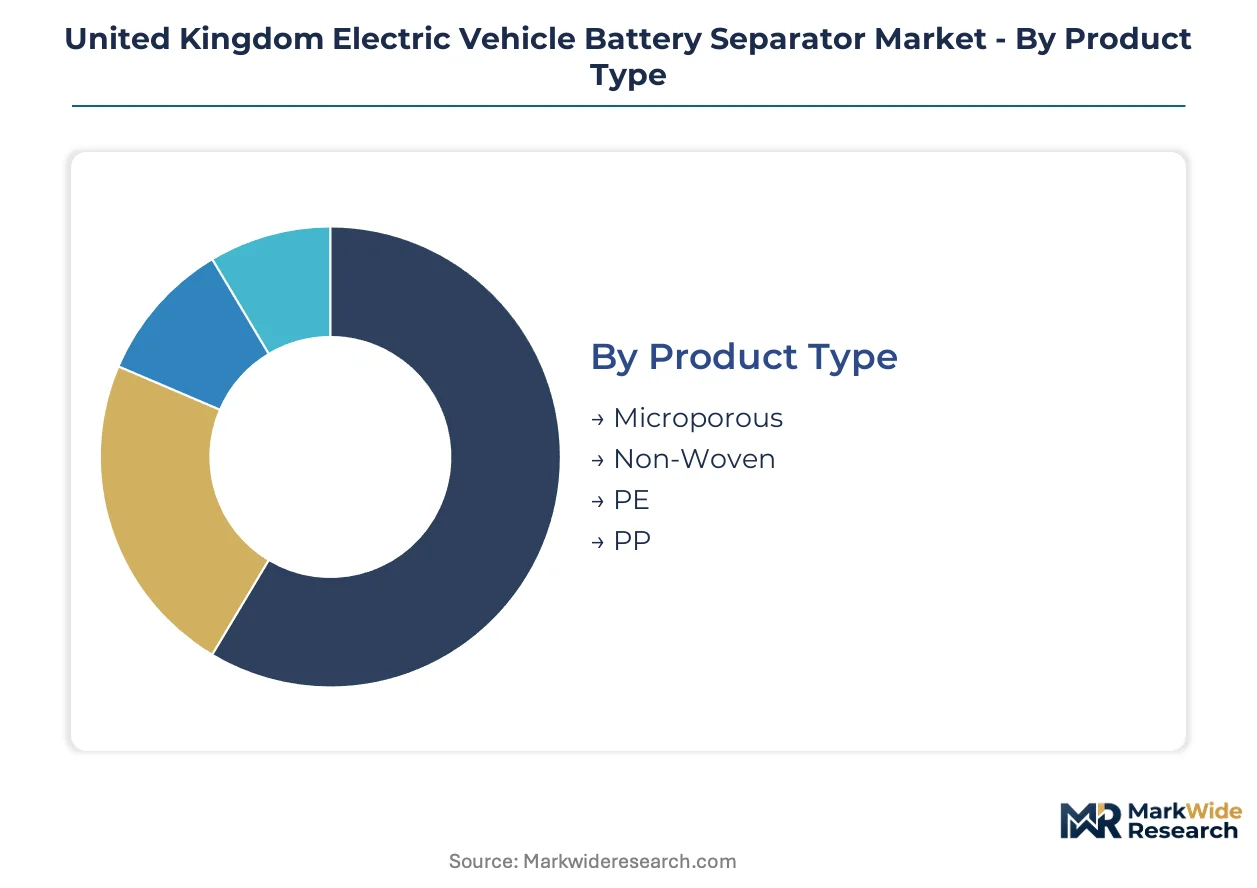
Separator procurement patterns diverge sharply across customer tiers and manufacturing stages in the United Kingdom. Technical specifications and regulatory compliance requirements reshape demand composition within each segment cluster.
Product Type:
Cost tier positioning determines separator selection logic for British cell manufacturers and automotive OEMs.
- Microporous:Wet-stretched polyethylene films dominate installed capacity due to proven shutdown functionality and established supply chains from Asahi Kasei and Toray Industries. West Midlands cell factories specify these variants for volume passenger vehicle programs where cost discipline outweighs marginal performance gains.
- Non-Woven:Synthetic fiber mats fabricated through electrospinning or melt-blowing processes offer superior electrolyte retention and thermal stability. Scottish Highlands gigafactory projects are evaluating these architectures for solid-state battery pilot lines where conventional polyolefin compatibility remains unproven.
- PE:Polyethylene substrates processed through biaxial stretching deliver the thinnest commercial membranes at sub-10 micrometre gauges.
- PP:Polypropylene variants tolerate higher operating temperatures and find niche deployment in commercial vehicle battery packs.
Microporous separators command the established base. The steepest expansion trajectory runs through non-woven architectures.
End User:
Customer type concentration shapes pricing power and technical service bundling across the United Kingdom supply base.
- OEMs:British automotive manufacturers including Jaguar Land Rover and Nissan Sunderland are consolidating separator procurement through direct master service agreements with cell suppliers. These contracts embed technical qualification support and volume commitment penalties that compress distributor margins.
- Tier-1 Suppliers:Battery system integrators such as Hyperbat and Britishvolt procurement subsidiaries manage separator specification for multiple OEM programs simultaneously. Their aggregated demand creates leverage for ceramic-coated variant access at negotiated price tiers.
- Aftermarket Providers:Independent battery rebuilders and remanufacturing specialists source commodity-grade separators through distributor channels.
- Vehicle Assemblers:Commercial vehicle builders in the West Midlands cluster are bypassing traditional tier-1 structures for direct separator contracting.
OEMs command the established base. The steepest volume climb runs through vehicle assemblers consolidating procurement for fleet electrification programs.
Manufacturing Stage:
Application maturity across production phases determines separator qualification intensity and margin capture potential.
- Production:Raw membrane extrusion and stretching operations concentrate among Asian suppliers with limited United Kingdom presence. Domestic coating and finishing investments are emerging as the primary localization opportunity under Automotive Transformation Fund conditions.
- Assembly:Separator stacking and cell winding integration occurs at British gigafactory sites where contamination control protocols add facility cost premiums.
- Testing:Thermal shutdown verification and puncture resistance validation represent fixed cost burdens for market entry.
- Quality Control:Statistical process monitoring and lot traceability systems are mandatory for United Kingdom Office for Product Safety and Standards compliance.
Production commands the established base. The steepest capability buildout runs through assembly-stage localization investments.
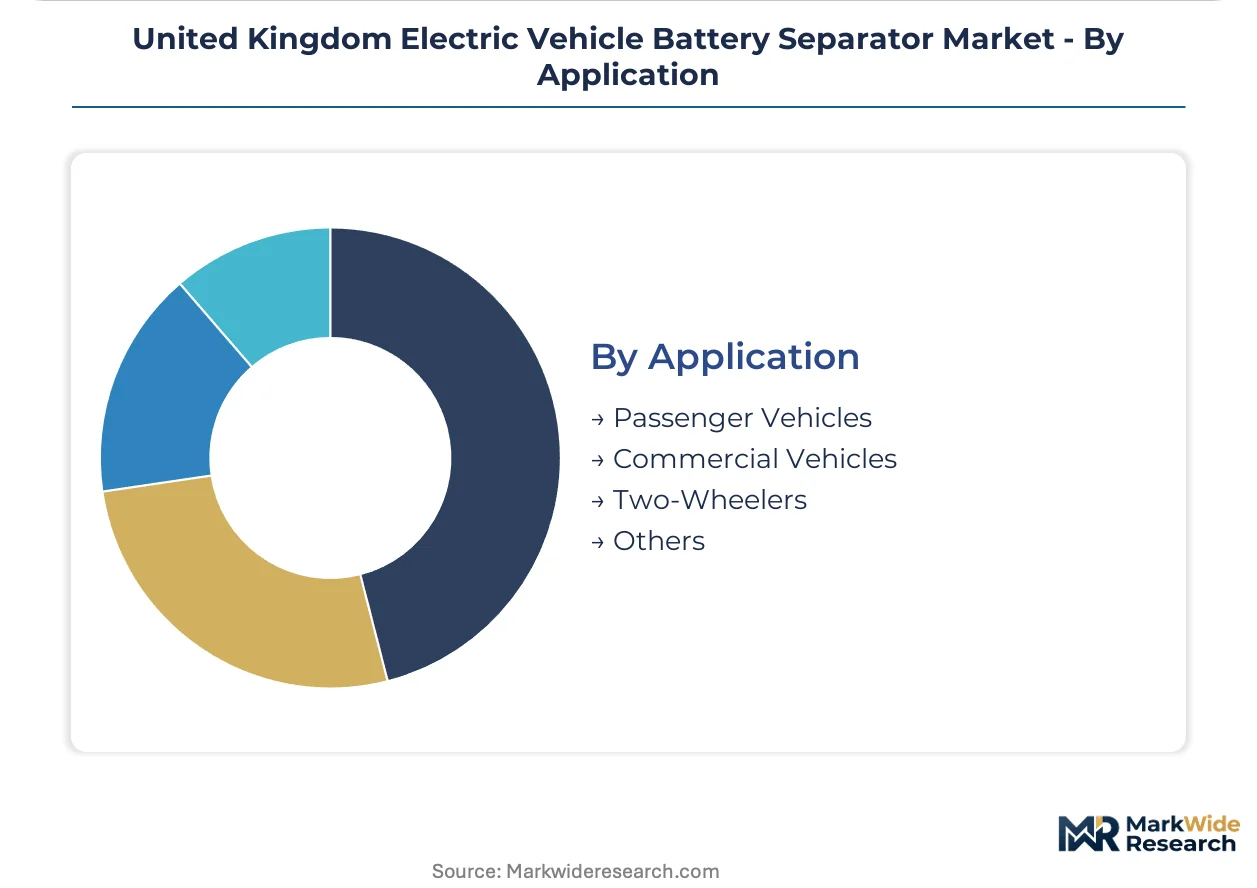
Application:
Vehicle category segmentation drives separator specification divergence across thermal management and cycle life requirements.
- Passenger Vehicles:High-volume battery electric platforms from British OEMs absorb the majority of separator volume, with 800-volt architectures mandating ceramic-coated variants for enhanced thermal runaway resistance.
- Commercial Vehicles:Heavy-duty truck and bus electrification programs in the West Midlands are expanding separator demand most quickly, with fleet operators specifying thicker membranes for extended cycle life under high-C-rate operation.
- Two-Wheelers:Micromobility battery packs utilize commodity-grade separators with reduced thickness tolerance requirements.
- Others:Stationary storage and marine applications represent emerging qualification targets for United Kingdom separator distributors.
Passenger vehicles command the established base. The steepest demand expansion runs through commercial vehicle electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean separator manufacturers export ceramic-coated polyolefin membranes to British cell factories clustered in England's industrial heartland. The trade corridor funnels high-performance separator architectures through Rotterdam and Felixstowe ports to serve OEM qualification timelines ahead of the 2030 ICE ban.
England
West Midlands automotive manufacturing around Birmingham and Coventry concentrates separator demand from Jaguar Land Rover and commercial vehicle electrification programs. The Department for Transport's Automotive Transformation Fund conditions grant disbursement on domestic coating and finishing operations. Cell factory assembly sites in Sunderland and Coventry are commissioning contamination-controlled winding facilities for separator integration.
Scotland
Scottish Highlands gigafactory corridors near Inverness and Dundee are attracting separator coating investments to supply solid-state battery pilot lines. The Scottish Government's Green Jobs Fund supports supply chain localization for planned cell manufacturing capacity. Planned facilities around Grangemouth petrochemical infrastructure offer feedstock proximity for polymer substrate processing.
Wales
South Wales battery manufacturing zones near Newport and Cardiff are emerging as secondary demand centers for separator qualification programs. The Welsh Government's Advanced Manufacturing Investment Scheme targets component supply chain gaps for electric vehicle production. Testing laboratories in Cardiff are developing thermal shutdown validation protocols aligned with Office for Product Safety and Standards requirements.
Northern Ireland
Belfast metropolitan manufacturing is leveraging historical aerospace composite expertise for separator substrate development programs. Invest Northern Ireland's advanced materials grants support R&D collaborations between local universities and separator coating technology providers. The region's underdeveloped cell manufacturing base limits near-term procurement volume but offers qualification partnerships for novel architectures.
United Kingdom Electric Vehicle Battery Separator Market Competitive Landscape
On the supply side, the industry is consolidated around integrated Asian chemical conglomerates with captive polymer production and proprietary stretching technologies. Market access for British cell manufacturers flows through three dominant archetypes: integrated resin-to-membrane producers, specialized coating technology licensors, and regional distribution partners managing qualification logistics. Competitive positioning depends on backward integration into polyolefin resin production and forward integration into ceramic deposition capabilities.
Among Japanese chemical conglomerates, Asahi Kasei Corporation, Toray Industries, and Sumitomo Chemical Co. occupy positions representing the integrated membrane production archetype. These entities exemplify supply relationships anchored by wet-stretched polyethylene expertise and established qualification pathways with British OEMs. Their market presence reflects decades of lithium-ion cell chemistry co-development rather than commodity supply contracts.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| SK IE Technology |
| Toray Industries |
| W-SCOPE Corporation |
| SEMCORP Co. |
| Sumitomo Chemical Co. |
| Mitsubishi Chemical Group Corporation |
| UBE Corporation |
| ENTEK International LLC |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic ceramic coating operations is compressing lead times and elevating price premiums for British cell manufacturers qualifying 800-volt architectures ahead of the 2030 ICE ban. This utilization squeeze simultaneously rewards incumbent Asian suppliers with pricing power and forces domestic assemblers into long-term offtake commitments that lock in cost structures.
Pricing Analysis
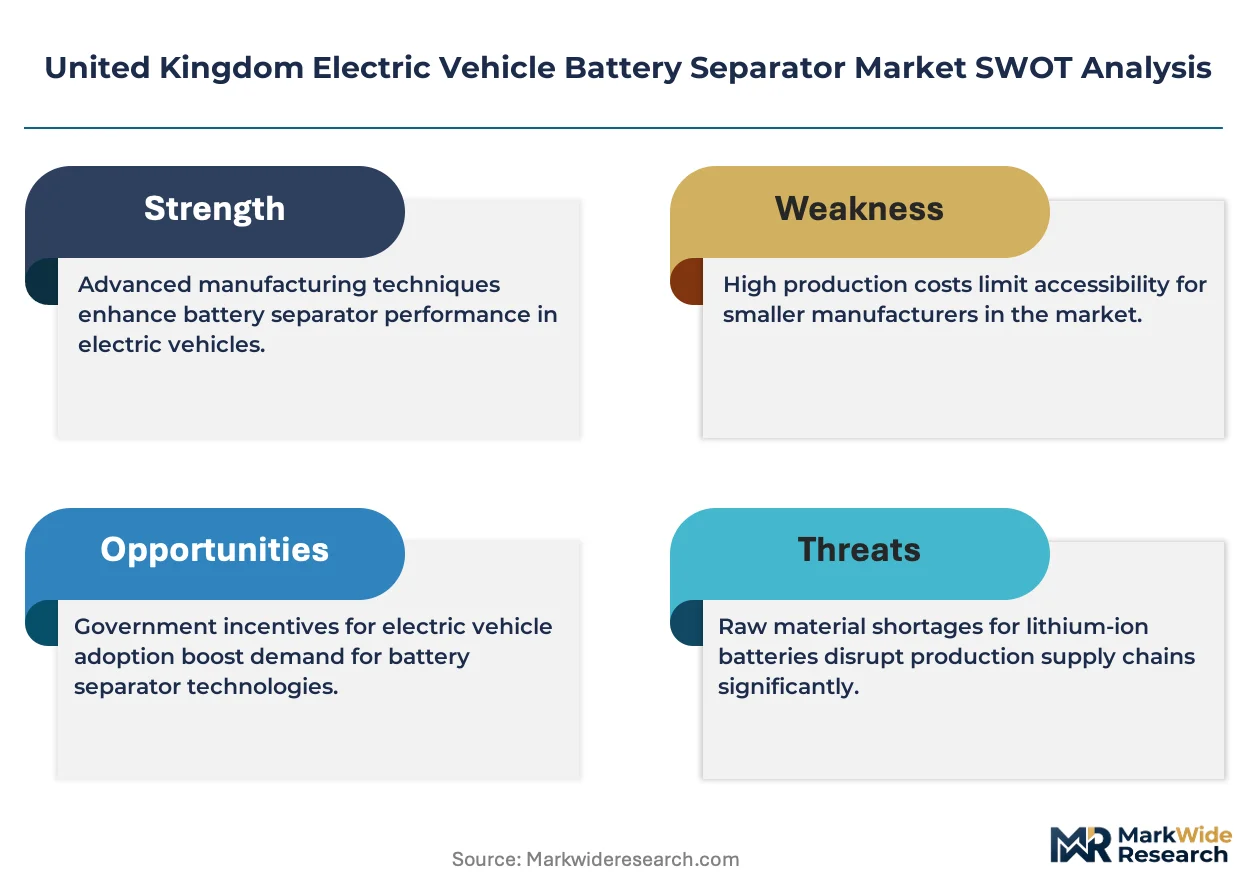
The technology-generation pricing gap between conventional wet-stretched polyethylene membranes and next-generation ceramic-coated composites spans approximately three-to-one in unit cost terms. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal stability certification grade and volume commitment scale, with automotive OEM master service agreements commanding the deepest discounts. Cost compression in commodity uncoated membranes is intensifying because Chinese polyolefin exports are flooding European spot markets. Fleet operators consolidating procurement through direct cell manufacturer contracts demonstrate the highest price sensitivity, while premium passenger vehicle platforms show relative inelasticity for safety-critical ceramic variants.
Supply Chain Analysis
Export-control regimes limiting advanced ceramic deposition equipment transfers are constraining domestic capacity buildout timelines for British coating operations. Raw membrane supply concentrates in Japan, South Korea, and China, with wet-stretched polyethylene substrates and ceramic precursor materials drawing from this narrow geographic base. Single-source vulnerability runs through the polyolefin resin stream where three petrochemical conglomerates control global supply. Distribution runs through Rotterdam and Felixstowe port corridors to West Midlands assembly sites, with contamination-controlled logistics adding facility cost premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Electric Vehicle Battery Separator Market represents a high-growth disruption anchored by the 2030 internal combustion engine sales ban and the forced migration toward solid-state-compatible ceramic architectures.
For Market Incumbents: Build technical service moats around electrolyte compatibility engineering to defend against emerging solid-state battery developers bypassing conventional separator supply chains. Deepen backward integration into polyolefin resin production to hedge hydrocarbon price volatility exposure. Accelerate qualification support investments for Scottish Highlands gigafactory corridors to preempt coating capacity localization by competitors. For New Entrants and Emerging Players: Pursue first-mover positioning in recyclable bio-based separator substrates where technical standards remain unsettled and incumbent qualification pathways offer limited advantage. The Scottish Highlands cell factory corridor presents the most penetrable geography given underdeveloped separator infrastructure and Green Jobs Fund support availability. Lead with technical partnership proposals to solid-state battery pilot lines rather than commodity volume plays. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ceramic coating equipment lines where eight-figure deposition system commitments now represent minimum viable scale. Long-term viability across the analysis window favors acquisition targets possessing established thermal shutdown certification with the United Kingdom Office for Product Safety and Standards and existing coating operational capability. Monitor solid-state battery timeline announcements from British cell manufacturers as the critical signal for separator technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Capacity Buildout | Domestic deposition lines qualify for Automotive Transformation Fund grants while reducing lead time exposure. |
| Backward Integration into Polyolefin Resin | Captive feedstock supply insulates margin structures from petrochemical price volatility. |
| Solid-State Battery Partnership | Early alignment with next-generation cell chemistry developers secures architecture specification influence. |
| Scottish Highlands Geographic Expansion | Green Jobs Fund support and gigafactory proximity create first-mover advantage in underdeveloped supply infrastructure. |
| Recyclable Substrate R&D Investment | Bio-based polymer development addresses emerging closed-loop battery recycling regulatory requirements. |
Research Methodology
Desk research of trade flow databases, petrochemical capacity registries, and regulatory filing archives preceded structured interviews with separator procurement leads at British cell manufacturers, ceramic coating equipment vendors, and automotive OEM platform engineers. Primary fieldwork with West Midlands automotive cluster stakeholders and Scottish Highlands gigafactory development teams combined with secondary validation against Department for Transport grant disbursement records and Office for Product Safety and Standards technical bulletins. Bottom-up unit demand estimates triangulated against top-down market value reconstructions.
The analytical framework held the 2030 ICE ban enforcement date fixed while varying solid-state battery commercialization timelines and ceramic coating capacity commissioning schedules across the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement tier, manufacturing stage localization, and vehicle application category. CAGRs derived from fitted growth curves applied to qualified demand estimates, with inputs from automotive transformation fund commitment trajectories and fleet electrification procurement schedules.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Asian membrane producers would shift outcomes beyond modeled ranges. Material shifts in solid-state battery electrolyte compatibility requirements or United Kingdom REACH substance restriction expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
EV Battery Sealant Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market