
 Double Layer Super-Capacitor Market | 2026-2036
Double Layer Super-Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Double Layer Super-Capacitor Market Foresight
The double layer super-capacitor market is pivoting around a widening gap between aerospace-grade components with extended cycle life and mass-market units for consumer electronics. Maxwell Technologies leverages its dry electrode patent portfolio to dominate high-reliability defense and satellite applications. Skeleton Technologies anchors European production with graphene-based cells for heavy transport and grid stabilization. LS Materials competes on manufacturing scale across the Asia-Pacific industrial base.
Double layer super-capacitors store energy through electrostatic charge separation at porous carbon electrode-electrolyte interfaces, achieving power densities exceeding 10 kW/kg with cycle lives surpassing one million charge-discharge events. Electrochemical capacitors retain the largest installed base in grid frequency regulation and wind turbine pitch control. Carbon-based technology leads manufacturing volume due to mature activated carbon supply chains, while graphene-based technology occupies the premium tier for applications demanding lowest equivalent series resistance. Automotive applications absorb the fastest-growing share of new capacity as 48V mild-hybrid architectures proliferate.
EPA tailpipe regulations and NHTSA fuel economy standards in the United States compel automotive OEMs to integrate super-capacitor buffers for regenerative braking energy recovery. Japan's METI sets performance benchmarks for energy storage density that Panasonic Corporation and NEC TOKIN navigate through continuous R&D programs. China's MIIT mandates domestic content thresholds for grid-scale storage components, redirecting supply chain investment toward certified local producers. Stakeholders must monitor how evolving carbon sourcing disclosure requirements under the EU CSRD reshape raw material procurement strategies and tier-one supplier qualification timelines.
Market Dynamics
Automotive OEM procurement of electrochemical capacitors for regenerative braking systems is compressing supplier lead times while carbon electrode manufacturing improvements simultaneously lower unit costs across the value chain.
Growth Catalysts
- EPA Tailpipe Regulations:United States automotive OEMs must integrate super-capacitor buffers to meet fuel economy standards, creating mandatory demand pull from NHTSA compliance timelines.
- 48V Mild-Hybrid Architectures:Powertrain electrification programs across Germany, Japan, and South Korea are specifying high-power-density cells for kinetic energy recovery during deceleration events.
- Activated Carbon Supply Chain Maturation:Porous carbon electrode manufacturing scale-up in East Asian industrial clusters is reducing per-unit material costs and shortening qualification cycles for new suppliers.
Market Restraints
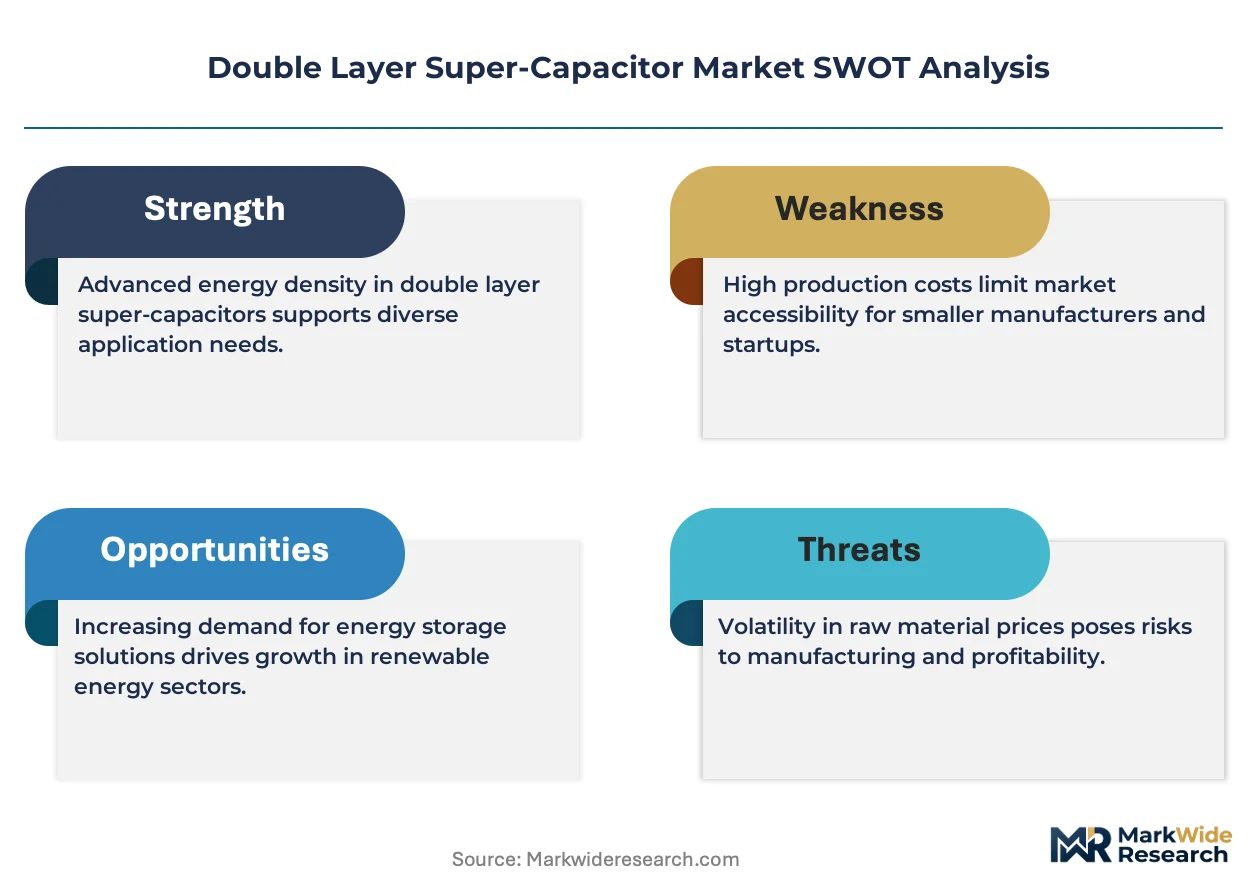
- Electrolyte Cost Volatility:Acetonitrile and propylene carbonate feedstock prices fluctuate with petrochemical commodity indices, compressing gross margins for cell assemblers without backward integration into chemical precursors.
- Geographic Supply Concentration:High-purity activated carbon production clusters in specific East Asian jurisdictions create single-source vulnerability for European and North American module integrators.
- Energy Density Ceiling:Electrostatic charge storage mechanisms fundamentally limit gravimetric energy density versus lithium-ion intercalation chemistry, restricting addressable applications in long-duration electric mobility.
Strategic Opportunities
- Grid-Scale Frequency Regulation:FERC Order 841 implementation in the United States is opening wholesale electricity markets to fast-responding storage assets, creating procurement channels independent of traditional utility RFP processes.
- Wind Turbine Pitch Control Retrofit:Existing onshore installations across Northern Europe require backup power system upgrades, substituting electrochemical capacitors for maintenance-intensive battery banks in nacelle emergency feathering systems.
- Graphene-Carbon Hybrid Electrodes:Converging nanomaterial synthesis with roll-to-roll coating processes is enabling next-generation cells with equivalent series resistance below 0.3 milliohms for premium aerospace and defense applications.
Industry Challenges
- Electrochemist Talent Scarcity:Specialized expertise in interfacial charge transfer phenomena and porous electrode characterization remains concentrated in academic and national laboratory settings, constraining private-sector R&D velocity.
- EU CSRD Carbon Sourcing Disclosure:Tier-one supplier qualification timelines are extending as OEMs demand granular supply chain transparency for activated carbon feedstocks, requiring new documentation systems and third-party verification protocols.
- Legacy System Integration Complexity:Super-capacitor modules must interface with existing power electronics architectures designed around battery voltage profiles, necessitating custom balancing circuitry and thermal management redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Layer Super-Capacitor Market |
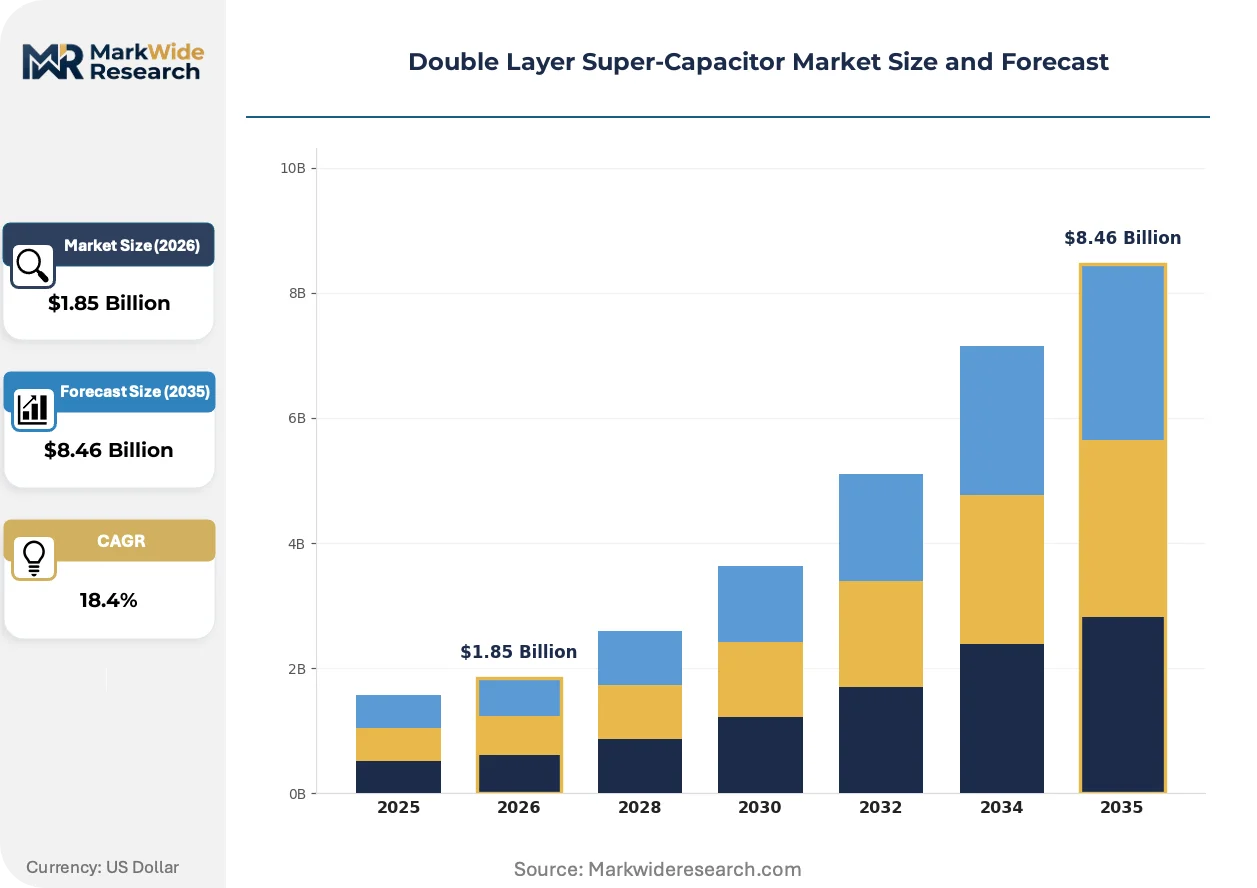
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
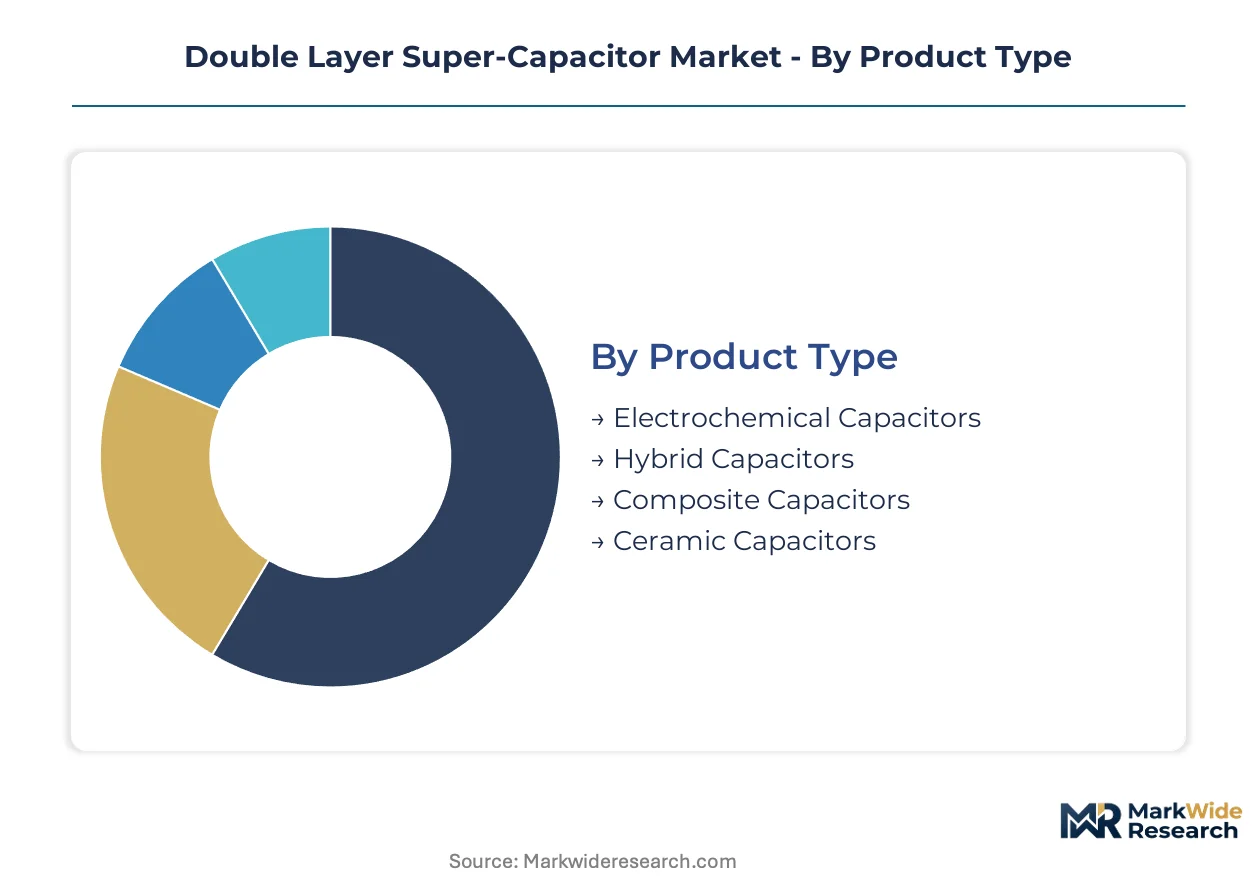
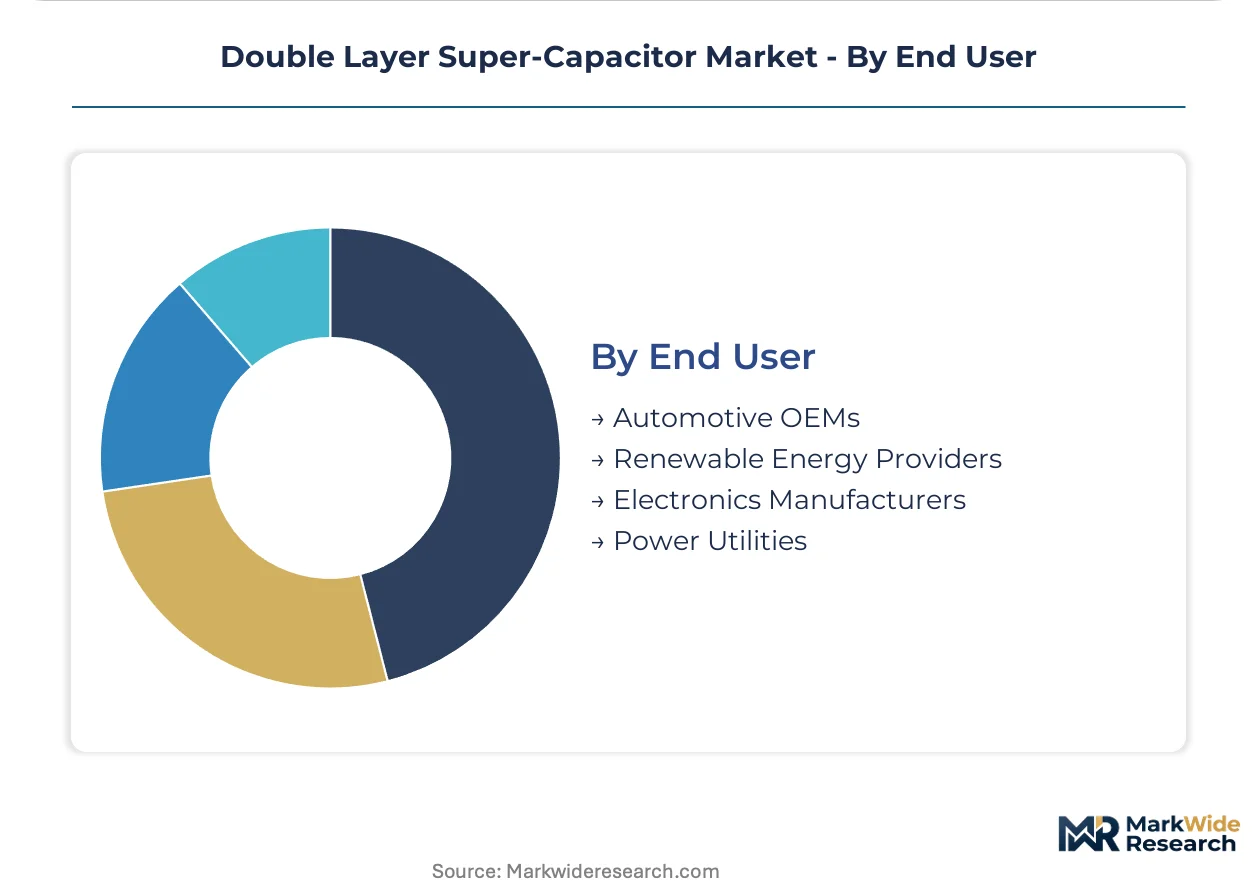
| Segmentation | Product Type: Electrochemical Capacitors, Hybrid Capacitors, Composite Capacitors, Ceramic Capacitors Application: Energy Storage Systems, Automotive Applications, Consumer Electronics, Industrial Machinery Technology: Graphene-based Technology, Carbon-based Technology, Polymer Electrolyte Technology, Metal Oxide Technology End User: Automotive OEMs, Renewable Energy Providers, Electronics Manufacturers, Power Utilities |
| Companies Covered | Maxwell Technologies, LS Materials, Nippon Chemi-Con Corporation, Eaton, CAP-XX, Panasonic Corporation, Skeleton Technologies, LS Mtron, NEC TOKIN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Layer Super-Capacitor Market Shifts & Advancements
Dry electrode coating processes are displacing solvent-based manufacturing methods, while regulatory pressure on supply chain transparency accelerates material traceability investments across the value chain.
Graphene-enhanced carbon electrodes are decentralizing performance hierarchies in the super-capacitor market. These nanostructured materials achieve surface areas exceeding 2,600 square meters per gram, enabling unprecedented charge storage density. Heavy transport OEMs in Northern Europe are adopting graphene-based cells for opportunity-charging bus fleets, prioritizing cycle life over upfront cost. This technology is decentralizing sourcing strategies as specialized carbon producers bypass traditional activated carbon supply chains entirely.
EU CSRD mandatory sustainability reporting is reshaping procurement qualification frameworks for energy storage components. The directive requires granular disclosure of upstream carbon intensity and conflict mineral content, compelling electrode suppliers to implement blockchain-traceable material tracking. Automotive and grid-scale buyers in Germany, France, and the Netherlands are now screening vendors on CSRD alignment timelines, with non-compliant suppliers facing exclusion from approved vendor lists by 2027.
Industrial automation clusters are consolidating super-capacitor procurement through integrated energy service contracts rather than component spot purchasing. German automotive suppliers and South Korean semiconductor fabs are bundling storage asset provision with predictive maintenance and performance guarantees, transferring operational risk to cell manufacturers and system integrators. This contracting model is most visible in Baden-Württemberg and Gyeonggi Province, where facility managers prioritize uptime assurance over capital expenditure control.
Double Layer Super-Capacitor Market Segmentation
Double layer super-capacitor procurement patterns diverge sharply between standardized commodity cells for consumer electronics and engineered-to-order modules for aerospace and grid-scale frequency regulation. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command premium pricing.
Product Type:
Customization intensity spans from off-the-shelf cylindrical cells to fully specified rack-mounted systems requiring thermal management integration.
- Electrochemical Capacitors:Electrostatic charge storage at porous carbon-electrolyte interfaces delivers power densities exceeding 10 kW/kg with cycle lives surpassing one million events. Automotive OEMs in Germany and Japan specify these for 48V mild-hybrid regenerative braking systems where rapid charge acceptance trumps energy density.
- Hybrid Capacitors:Asymmetric electrode configurations combining battery-type Faradaic reactions with capacitive double-layer mechanisms extend energy density toward 30 Wh/kg. South Korean electronics manufacturers integrate hybrid cells into uninterruptible power supplies for semiconductor fabrication facilities.
- Composite Capacitors:Multi-material electrode architectures blending activated carbon with conductive polymers serve niche defense applications requiring wide temperature tolerance.
- Ceramic Capacitors:Solid-state dielectric construction eliminates electrolyte leakage risks for implantable medical devices and downhole oil exploration electronics.
Leading the category by volume: Electrochemical Capacitors. Expanding most quickly: Hybrid Capacitors.
Application:
Cost tier stratification separates mass-market consumer electronics from capital-intensive industrial infrastructure with decade-long depreciation schedules.
- Energy Storage Systems:Grid-connected installations for frequency regulation and renewable firming require megawatt-scale module arrays with active balancing circuitry. FERC Order 841 implementation in the United States is opening wholesale electricity markets to these fast-responding assets outside traditional utility procurement channels.
- Automotive Applications:48V electrical architectures specify super-capacitor buffers for kinetic energy recovery during deceleration, with EPA tailpipe regulations and NHTSA fuel economy standards mandating integration timelines.
- Consumer Electronics:Compact cylindrical cells power wireless sensor networks and handheld device flash charging where space constraints dominate specification sheets.
- Industrial Machinery:Automated guided vehicles and robotic welding systems deploy super-capacitor banks for peak power shaving and emergency shutdown sequencing.
Capturing dominant share: Energy Storage Systems. Climbing the fastest: Automotive Applications.
Technology:
Manufacturing maturity separates established activated carbon supply chains from emerging nanomaterial synthesis requiring specialized capital equipment.
- Carbon-based Technology:Mature porous carbon electrode manufacturing leverages established supply chains for coconut shell and petroleum pitch precursors, dominating unit economics for high-volume automotive and consumer applications.
- Graphene-based Technology:Single-atom-thick carbon lattices achieve surface areas exceeding 2,600 square meters per gram with equivalent series resistance below 0.3 milliohms. Heavy transport operators in Northern Europe specify graphene cells for opportunity-charging bus fleets where cycle life economics override upfront cost premiums.
- Polymer Electrolyte Technology:Solid or gelled ionic conductors eliminate flammability concerns for confined-space installations in maritime and mining equipment.
- Metal Oxide Technology:Pseudocapacitive ruthenium and manganese oxide coatings enhance charge storage density for pulse power aerospace and defense applications.
Highest shipment volumes: Carbon-based Technology. Steepest expansion trajectory: Graphene-based Technology.
End User:
Customer concentration patterns range from fragmented electronics contract manufacturers to consolidated automotive tier-one suppliers with multi-year qualification cycles.
- Automotive OEMs:Powertrain electrification programs across Germany, Japan, and South Korea specify super-capacitor buffers for regenerative braking, with procurement teams compressing supplier lead times as 48V architecture deployment accelerates.
- Renewable Energy Providers:Wind turbine operators across Northern Europe retrofit nacelle emergency feathering systems, substituting electrochemical capacitors for maintenance-intensive battery banks in pitch control backup power.
- Electronics Manufacturers:South Korean semiconductor fabs and German automotive suppliers bundle storage procurement through integrated energy service contracts transferring operational risk to cell manufacturers.
- Power Utilities:Transmission system operators specify grid-scale frequency regulation assets with fifteen-year performance guarantees and predictive maintenance obligations.
Commanding largest procurement volumes: Automotive OEMs. Gaining share fastest: Renewable Energy Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive corridor drives European procurement intensity for regenerative braking systems, with Stuttgart-based OEMs compressing supplier lead times for 48V mild-hybrid architectures.
Germany
Industrial automation clusters in Baden-Württemberg and Bavaria absorb electrochemical capacitors for robotic welding systems and automated guided vehicles. The EU CSRD mandates granular carbon sourcing disclosure, extending tier-one supplier qualification timelines. Skeleton Technologies anchors European production with graphene-based cells from its Dresden facility for heavy transport applications.
Japan
Powertrain electrification programs at Tokyo and Nagoya-based automotive OEMs specify high-power-density cells for kinetic energy recovery. METI performance benchmarks for energy storage density drive continuous R&D programs at Panasonic Corporation and NEC TOKIN. Kanto region semiconductor fabs bundle storage procurement through integrated energy service contracts.
United States
EPA tailpipe regulations and NHTSA fuel economy standards compel Detroit-based automotive OEMs to integrate super-capacitor buffers. FERC Order 841 opens wholesale electricity markets to fast-responding grid-scale frequency regulation assets. Texas and California transmission system operators specify fifteen-year performance guarantees for frequency regulation installations.
South Korea
Gyeonggi Province semiconductor fabrication facilities deploy hybrid capacitors for uninterruptible power supply systems. MIIT-mandated domestic content thresholds for grid-scale storage redirect supply chain investment toward certified local producers. LS Materials and LS Mtron compete on manufacturing scale across the Asia-Pacific industrial base from their Seoul Capital Area operations.
China
MIIT mandates domestic content thresholds for grid-scale storage components, redirecting supply chain investment toward certified local producers. Yangtze River Delta industrial clusters manufacture activated carbon electrodes at scale, reducing per-unit material costs. Shenzhen and Shanghai-based module integrators face qualification cycle compression as automotive procurement accelerates.
Double Layer Super-Capacitor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across electrode technology specialization, with graphene-based cell manufacturers commanding pricing power against activated carbon commodity producers. The vendor base stratifies into three tiers: aerospace-grade specialists with extended cycle life guarantees, automotive-scale suppliers qualified for 48V mild-hybrid programs, and consumer electronics commodity producers. Two dominant competitive moves are reshaping positioning: backward integration into activated carbon precursor supply chains, and strategic partnerships between cell manufacturers and power electronics integrators to reduce system-level qualification friction.
Within the premium-tier vector, Maxwell Technologies represents the aerospace-grade specialist archetype with dry electrode patent positioning, while Skeleton Technologies exemplifies European graphene-based production for heavy transport. LS Materials occupies the scale-driven archetype across Asia-Pacific manufacturing. These three anchors illustrate how geographic clustering around carbon precursor sources and automotive OEM qualification hubs determines competitive positioning.
| Leading Market Players |
|---|
| Maxwell Technologies |
| LS Materials |
| Nippon Chemi-Con Corporation |
| Eaton |
| CAP-XX |
| Panasonic Corporation |
| Skeleton Technologies |
| LS Mtron |
| NEC TOKIN |
| Others |
Supply & Pricing Matrix
Acetonitrile and propylene carbonate feedstock indices cascade through super-capacitor manufacturing tiers, compressing margins for cell assemblers lacking backward integration into chemical precursors while amplifying pricing power for electrode producers with captive carbon sourcing. This commodity-cost transmission splits the market into aerospace-grade premium tiers anchored to cycle-life guarantees and automotive-volume tiers competing on per-kilowatt procurement benchmarks.
Pricing Analysis
Value-based pricing anchors to guaranteed cycle-life throughput for grid-scale frequency regulation contracts, with Texas and California transmission operators paying fifteen-year performance premiums. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified cells with sub-0.3 milliohm ESR from automotive 48V buffers and consumer electronics commodity cylinders. Cost compression in the standard tier is intensifying because activated carbon electrode manufacturing scale-up in East Asian clusters erodes differentiation. Automotive OEM procurement teams exhibit highest price sensitivity, while defense satellite programs prioritize cycle-life assurance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with high-purity activated carbon production clusters in specific East Asian jurisdictions, creating qualification bottlenecks for European and North American module integrators. Manufacturing gravity draws from coconut shell precursor processing in Southeast Asia, petroleum pitch carbonization in East Asia, and graphene synthesis pilot lines in Northern Europe. Feedstock exposure rests on acetonitrile solvent supply from petrochemical commodity indices and conductive additive imports from specialized chemical producers. Tariff exposure on carbon electrode imports is reshaping procurement strategies for German automotive tier-one suppliers. Distribution runs through direct OEM qualification channels for automotive and grid-scale segments, with spot purchasing surviving only in consumer electronics replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU CSRD carbon sourcing disclosure mandate erects a compliance moat that favors electrode suppliers with blockchain-traceable material tracking systems already operational, while disqualifying legacy producers lacking granular upstream documentation capabilities.
For Market Incumbents: Acquire activated carbon precursor processing assets in Southeast Asia to secure feedstock cost control against petrochemical index volatility. Skeleton Technologies and Maxwell Technologies should expand Dresden and San Diego facility capacity respectively to capture FERC Order 841 grid-scale procurement windows before qualification cycles extend under evolving EU transparency requirements. Electrochemist talent scarcity at national laboratories threatens R&D velocity for graphene-electrode development programs. For New Entrants and Emerging Players: Digital-channel route through integrated energy service contracts offers bypass around traditional OEM qualification barriers for industrial automation clusters in Baden-Württemberg and Gyeonggi Province. White-space targets include wind turbine pitch control retrofit markets across Northern Europe and opportunity-charging bus fleet deployments where cycle-life economics override upfront premiums. Semiconductor fabrication facility UPS integration represents the most penetrable segment for hybrid capacitor newcomers lacking automotive-scale manufacturing credentials. For Investors and Strategic Acquirers: Distressed-cycle entries favor graphene-electrode specialists with MIIT certification for Chinese grid-scale procurement in the Yangtze River Delta manufacturing corridor. Long-term viability across the analysis window hinges on CSRD alignment timelines and domestic content threshold navigation in multiple jurisdictions. Monitor activated carbon supply contract renegotiation patterns as the inflection indicator for margin compression versus pricing power shifts across tier-one supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Precursors | Captive coconut shell and petroleum pitch sourcing insulates margin structures from acetonitrile index volatility. |
| CSRD-Aligned Supply Chain Certification | Blockchain-traceable material tracking qualifies vendors for German automotive approved vendor lists. |
| Graphene-Electrode Manufacturing Scale-Up | Dresden and Northern European pilot lines target heavy transport opportunity-charging bus fleet specifications. |
| Integrated Energy Service Contracting | Performance-guaranteed storage provision transfers operational risk from Baden-Württemberg facility managers to cell manufacturers. |
| FERC Order 841 Market Participation | Fast-responding frequency regulation assets access wholesale electricity markets outside traditional utility RFP channels. |
Research Methodology
Trade databases, SEC filings from publicly listed energy storage component manufacturers, and EIA grid interconnection records formed the secondary backbone, supplemented by customs data tracking activated carbon electrode import flows. Primary interviews with automotive tier-one supplier procurement directors, electrochemical capacitor plant managers, grid operator storage asset planners, and EU regulatory compliance officers validated secondary findings. Bottom-up cell shipment tallies by application segment triangulated against top-down market value estimates derived from OEM procurement disclosure patterns.
Historical trendline analysis of electrode manufacturing cost curves and automotive 48V architecture deployment rates informed projection parameters across the modeling period. Segmentation dimensions modeled include product type customization intensity, application cost-tier stratification, technology manufacturing maturity, and end-user concentration patterns. CAGRs were derived from curve-fitting observed adoption rates against regulatory compliance timeline constraints, with FERC Order 841 implementation pace and MIIT domestic content threshold enforcement serving as key demand-side forecast inputs.
The model holds under stable petrochemical feedstock pricing and continued EPA tailpipe regulation enforcement; deviation in acetonitrile supply disruptions or CSRD disclosure requirement acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Solar Storage System Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Battery Energy Storage Market
Energy Storage
Grid Scale Battery Storage Sales Market