
 Germany Energy Storage Systems Market | 2026-2036
Germany Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Energy Storage Systems Market Foresight
Utility procurement concentration is realigning as municipal energy cooperatives and industrial offtakers fragment the buyer base alongside traditional transmission operators. RWE AG leverages its lignite-to-renewables transition to anchor large-scale battery project pipelines in the Rhineland. Fluence Energy Inc. competes through technology leadership in grid-forming inverters and software-integrated storage architectures. STEAG GmbH specializes in repurposing retired thermal sites into battery storage hubs, sustaining geographic dominance in Germany's industrial west.
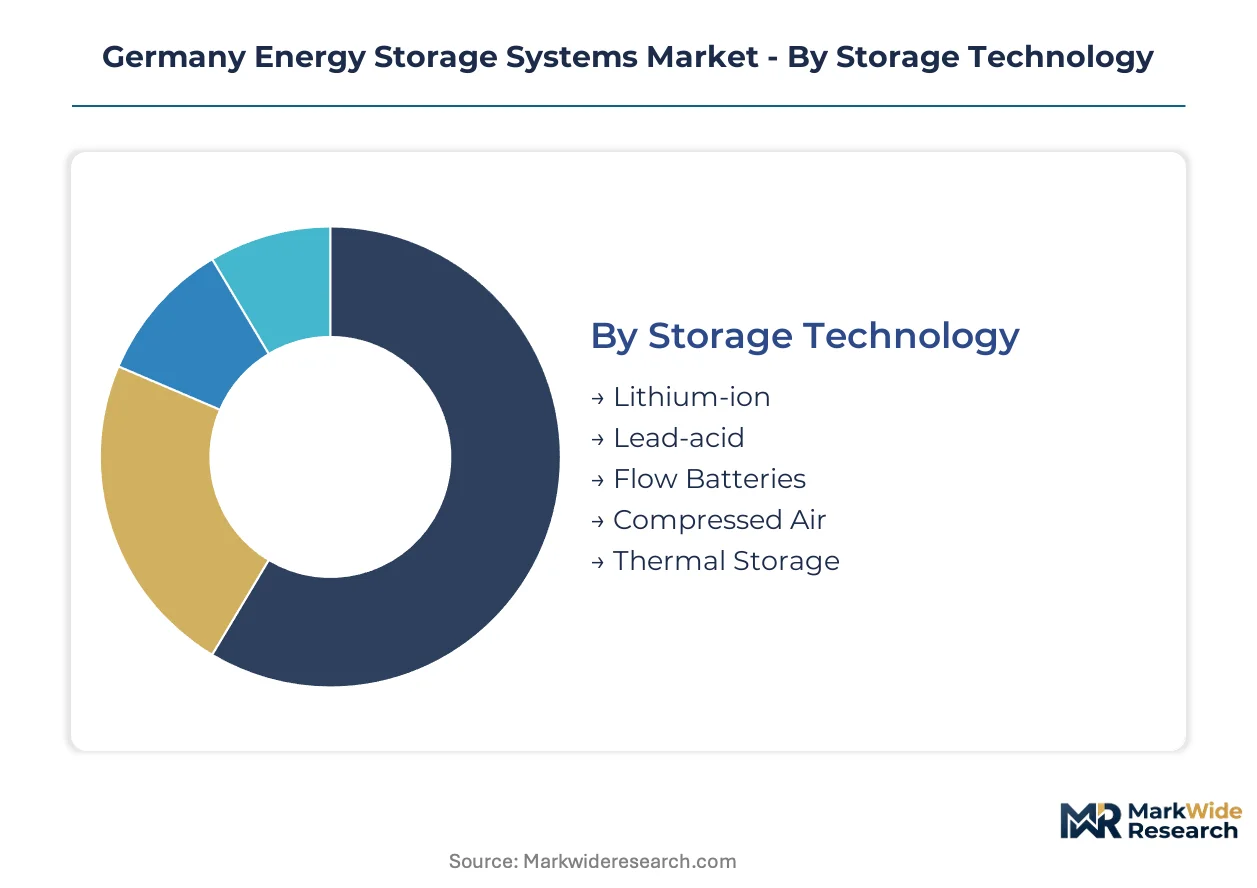
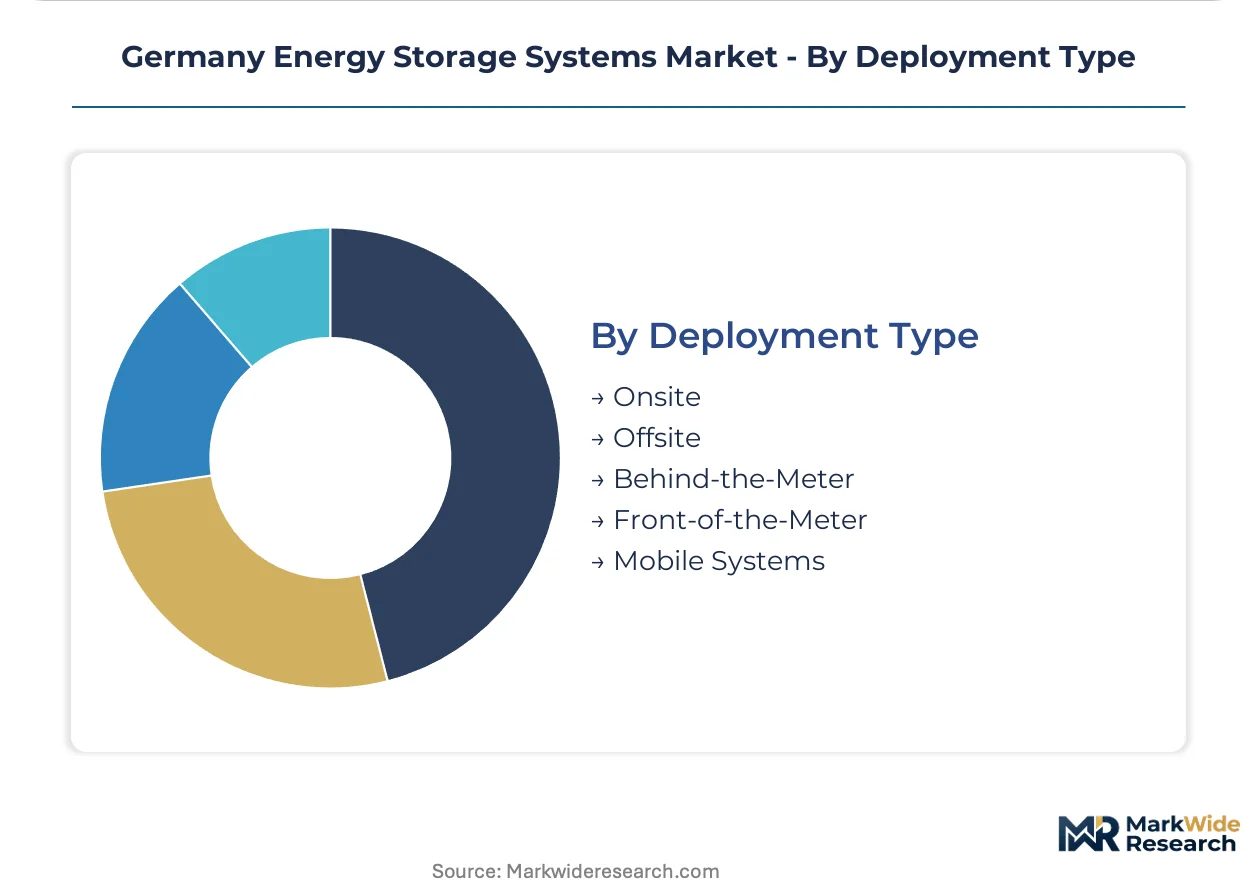
Germany energy storage systems encompass electrochemical, mechanical, and thermal technologies engineered to capture electrical energy during low-demand periods and discharge it during peak load or supply intermittency, with lithium-ion cells dominating current deployments due to energy densities exceeding 250 Wh/kg and declining cell costs. The storage technology dimension shows lithium-ion systems occupying the majority of installed capacity while flow batteries attract long-duration applications. Application segmentation reveals renewable integration as the fastest-growing demand vector, though grid stabilization retains the deepest margin pool due to ancillary service contracts. Deployment type analysis indicates front-of-the-meter projects dominate utility-scale revenue, yet behind-the-meter installations accelerate fastest among commercial buildings seeking peak shaving.
Germany's Federal Network Agency (Bundesnetzagentur) enforces grid codes requiring frequency response capabilities from storage assets, while EU Green Deal targets and the national EEG revision mandate storage co-location with new renewable installations. KBA emissions standards for commercial vehicle fleets indirectly stimulate mobile storage demand for charging infrastructure. Stakeholders must monitor Berlin's pending capacity market design and Bavaria's storage-specific permitting accelerations to calibrate capital allocation timing.
Market Dynamics
Grid-forming inverter technology is collapsing the traditional separation between generation assets and storage, forcing transmission operators to rewrite interconnection standards while municipal cooperatives gain procurement leverage.
Growth Catalysts
- EEG Revision Mandates:Germany's revised renewable energy framework requires storage co-location with new wind and solar installations, creating guaranteed offtake for battery developers in Bavaria and Schleswig-Holstein.
- Industrial Electrification:North Rhine-Westphalia's chemical and steel clusters are deploying behind-the-meter systems to manage peak loads and avoid grid fees.
- Frequency Response Markets:Bundesnetzagentur grid codes now compensate storage assets for primary frequency regulation, opening revenue stacking for utility-scale operators.
Market Restraints
- Lithium Supply Concentration:Cathode active material processing concentrates in China, exposing German integrators to geopolitical supply shocks and forced labor due diligence requirements under EU Corporate Sustainability Due Diligence Directive.
- Permitting Velocity:Bavaria's environmental review processes for greenfield storage sites average 18-24 months, compressing project IRRs and deterring speculative development.
- Flow Battery Cost Premium:Vanadium redox systems remain 40-60% above lithium-ion on installed cost basis, limiting uptake despite superior cycle life for 8+ hour duration applications.
Strategic Opportunities
- Thermal Site Repurposing:Retired lignite and hard coal plants in the Rhineland offer grid-connected brownfield locations with existing substations and cooling infrastructure.
- Vehicle-to-Grid Convergence:KBA emissions standards for commercial fleets are accelerating bidirectional charging infrastructure, creating mobile storage pools that utilities can dispatch.
- Long-Duration Chemistry:Iron-air and zinc-bromine technologies are approaching commercial scale for seasonal shifting, addressing the 100+ hour gap in current lithium-dominated portfolios.
Industry Challenges
- Power Electronics Talent Scarcity:Grid-forming inverter design and firmware engineering expertise concentrates at a handful of institutes and former wind converter specialists, constraining project execution timelines.
- Legacy SCADA Integration:Distribution system operators in eastern Germany operate heterogeneous control architectures that resist standardized storage dispatch protocols, forcing costly custom integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Energy Storage Systems Market |
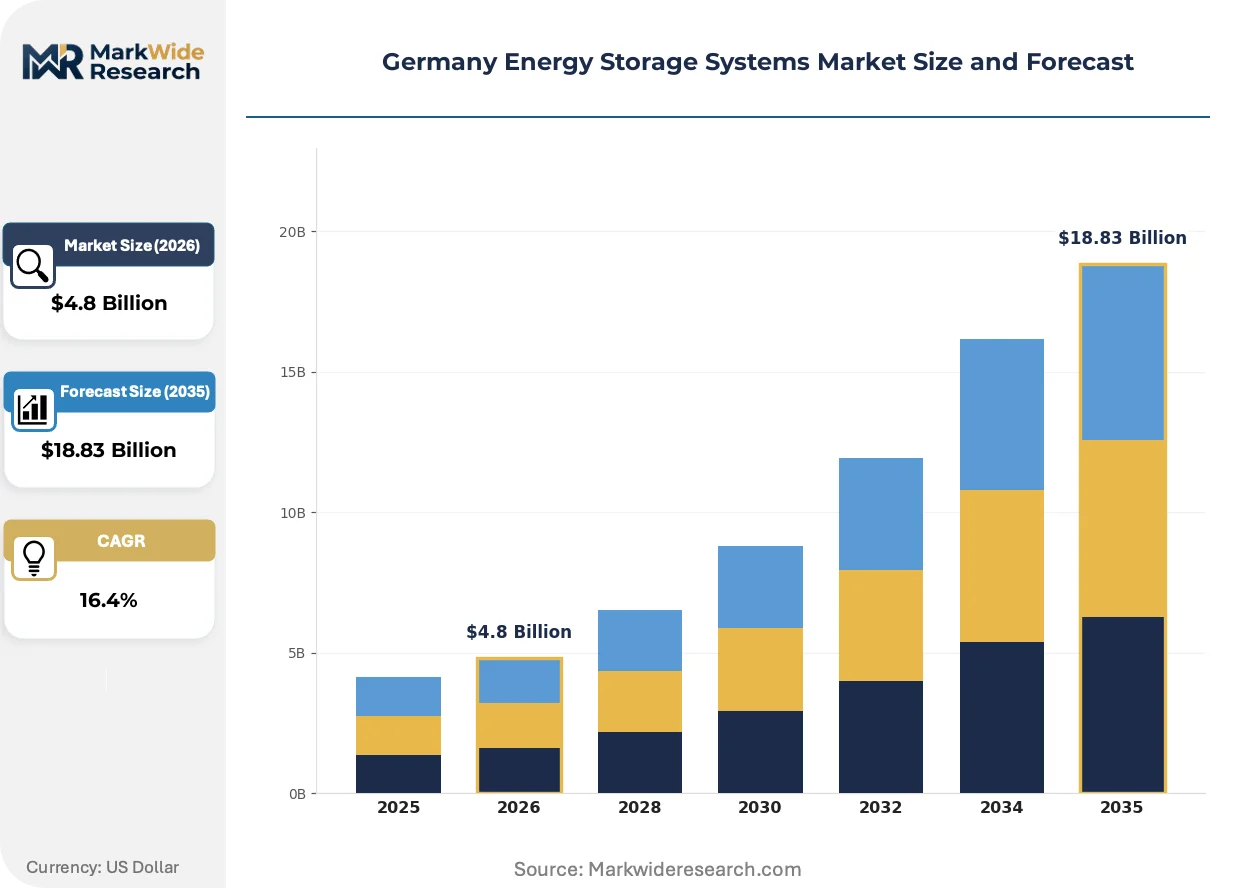
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Technology: Lithium-ion, Lead-acid, Flow Batteries, Compressed Air, Thermal Storage Application: Grid Stabilization, Renewable Integration, Peak Shaving, Uninterruptible Power Supply, Backup Power End User Industry: Utilities, Commercial Buildings, Manufacturing, Data Centers, Telecommunications Deployment Type: Onsite, Offsite, Behind-the-Meter, Front-of-the-Meter, Mobile Systems |
| Companies Covered | Enel SpA, RWE AG, Renewable Energy Systems Ltd, STEAG GmbH, Fluence Energy Inc., Sungrow Power Supply Co. Ltd, TotalEnergies, Neoen, Trianel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Energy Storage Systems Market Shifts & Advancements
Software-defined storage architectures are collapsing the hardware-software boundary, enabling virtual power plant aggregation and predictive degradation management that reshape asset financing structures.
Solid-state battery chemistries are decentralizing risk allocation in project finance. These systems promise reduced thermal runaway probability and extended calendar life. Munich-based industrial offtakers are piloting sulfide-electrolyte cells for critical backup applications. The technology is decentralizing insurance premiums and enabling longer-term debt tenors for storage-backed project bonds.
The EU Green Deal's 2040 climate target revision is tightening storage deployment timelines. Member states must demonstrate 90% renewable electricity by 2040, forcing Germany to accelerate grid-scale procurement. The Federal Ministry for Economic Affairs is streamlining Bundesnetzagentur permitting for storage co-located with offshore wind interconnectors. Industrial buyers in Hamburg and Bremen are pre-contracting capacity to secure queue positions.
Aggregated procurement consortia are displacing single-utility tendering. Municipal energy cooperatives in Baden-Württemberg and Saxony are pooling demand to negotiate battery supply agreements directly with cell manufacturers. This model fragments the buyer base and compresses integrator margins while shifting warranty risk to end-users. The pattern is most visible among commercial and industrial clusters seeking 10-50 MWh systems for peak shaving.
Germany Energy Storage Systems Market Segmentation
Storage procurement patterns in Germany fragment across technology maturity, application economics, and buyer sophistication. Segment boundaries blur as grid-forming inverters enable multi-revenue stacking and municipal cooperatives reshape traditional utility procurement channels.
Storage Technology:
Cost tier and cycle life requirements differentiate buyer preferences across industrial, utility, and commercial segments.
- Lithium-ion:Dominates current deployments through energy densities exceeding 250 Wh/kg and modular containerized architectures. North Rhine-Westphalia's chemical clusters and Bavarian solar parks concentrate demand, driven by declining cell costs and established recycling infrastructure under the EU Battery Regulation.
- Flow Batteries:Vanadium redox systems deliver 8+ hour duration capability with minimal capacity degradation across 20,000+ cycles. Long-duration applications in Schleswig-Holstein's wind corridors attract project developers seeking multi-day shifting capability, constrained by 40-60% installed cost premiums versus lithium-ion.
- Lead-acid:Mature technology serving backup power niches in telecommunications and rural substations where capital constraints outweigh energy density requirements.
- Compressed Air:Mechanical storage leveraging underground salt caverns in northern Germany for seasonal arbitrage, limited by specific geology requirements.
- Thermal Storage:Molten salt and phase-change materials capturing industrial waste heat in Rhineland steel and cement facilities.
Lithium-ion leads volumes today; flow batteries are gaining share fastest in utility-scale procurement.
Application:
Revenue model complexity determines technology selection and project finance structure.
- Renewable Integration:Co-location mandates under Germany's revised EEG framework create guaranteed offtake channels. Bavarian solar and Schleswig-Holstein wind developers deploy storage to smooth intermittency and capture price arbitrage, with grid codes requiring frequency response capabilities.
- Grid Stabilization:Primary frequency regulation contracts through Bundesnetzagentur mechanisms deliver the deepest margin pools. Transmission operators in Hamburg and Bremen procure utility-scale assets for ancillary services, with software-integrated architectures enabling revenue stacking across multiple grid products.
- Peak Shaving:Industrial offtakers in North Rhine-Westphalia avoid grid fees through behind-the-meter deployment.
- Uninterruptible Power Supply:Data centers in Frankfurt and Munich prioritize power quality and seamless transfer.
- Backup Power:Critical infrastructure mandates drive municipal procurement for hospitals and emergency services.
Grid stabilization commands premium margins currently; renewable integration shows the steepest expansion trajectory.
End User Industry:
Procurement scale and technical sophistication shape vendor relationships and contract structures.
- Utilities:Traditional transmission operators anchor front-of-the-meter procurement with 100+ MWh project scales. Municipal energy cooperatives in Baden-Württemberg and Saxony fragment the buyer base through aggregated demand pooling, compressing integrator margins while shifting warranty risk.
- Manufacturing:Steel and chemical clusters in the Rhineland deploy behind-the-meter systems for process continuity and peak load management, with KBA emissions standards indirectly stimulating mobile storage for fleet charging.
- Commercial Buildings:Peak shaving applications accelerate fastest among logistics facilities and retail chains seeking demand charge reduction.
- Data Centers:Frankfurt's hyperscale facilities prioritize lithium-ion for space-constrained installations.
- Telecommunications:Rural 5G infrastructure drives lead-acid and early lithium-ion replacement cycles.
Utilities retain largest individual contract values; manufacturing is climbing the fastest as electrification deepens.
Deployment Type:
Regulatory jurisdiction and meter boundary determine interconnection standards and revenue access.
- Front-of-the-Meter:Grid-connected utility-scale projects dominate revenue concentration with direct access to frequency regulation markets. Brownfield thermal site repurposing in the Rhineland leverages existing substations and cooling infrastructure, accelerating permitting timelines.
- Behind-the-Meter:Commercial and industrial installations bypass utility procurement queues through onsite deployment. Bavarian manufacturing facilities and North Rhine-Westphalia chemical plants aggregate into virtual power plants, creating dispatchable capacity pools.
- Onsite:Co-located with generation or load assets for dedicated use.
- Offsite:Remote storage serving multiple offtakers through wheeling arrangements.
- Mobile Systems:Vehicle-to-grid infrastructure and portable units for construction and events.
Front-of-the-meter captures largest installed capacity; behind-the-meter expands most quickly among commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's storage deployment velocity outpaces France's utility-scale procurement, though both operate under shared EU Green Deal mandates. National regulatory frameworks and industrial cluster configurations create distinct sub-regional demand patterns across German states.
Bavaria
Solar park developers and agricultural cooperatives drive behind-the-meter installations under the revised EEG framework. The Bundesnetzagentur enforces frequency response capabilities for all new grid-connected assets. Munich's industrial corridor hosts manufacturing facilities piloting solid-state battery systems for critical backup applications.
North Rhine-Westphalia
Chemical and steel clusters deploy peak-shaving systems to avoid grid fees and manage process continuity. KBA emissions standards for commercial fleets stimulate mobile storage infrastructure for charging networks. The Rhineland's retired lignite sites transform into brownfield battery hubs with existing substation access.
Baden-Württemberg
Municipal energy cooperatives aggregate procurement demand to negotiate directly with cell manufacturers. The state's automotive supply chain expertise feeds into power electronics engineering for grid-forming inverters. Stuttgart's manufacturing base concentrates commercial and industrial storage deployments for peak load management.
Lower Saxony
Offshore wind interconnectors drive front-of-the-meter utility-scale procurement with streamlined Bundesnetzagentur permitting. Salt cavern geology enables compressed air storage pilots for seasonal arbitrage. Hanover's logistics facilities accelerate behind-the-meter installations for demand charge reduction.
Hamburg and Bremen
Port industrial complexes pre-contract storage capacity to secure queue positions for electrified cargo handling. The Federal Ministry for Economic Affairs prioritizes northern port cities for grid-scale procurement acceleration. Maritime logistics clusters deploy systems for crane electrification and cold chain reliability.
Germany Energy Storage Systems Market Competitive Landscape
German producers anchor the utility-scale project development tier; international technology specialists hold the grid-forming inverter and software-integrated architecture segments. The vendor base concentrates around three strategic archetypes: vertically integrated energy majors repurposing thermal assets, pure-play battery integrators, and municipal cooperative consortiums. Competitive moves center on brownfield site acquisition and direct cell manufacturer partnerships.
Among Germany-based energy majors, RWE AG and STEAG GmbH exemplify the thermal-transition archetype, leveraging retired fossil fuel infrastructure for grid-connected storage deployment. Fluence Energy Inc. represents the international technology specialist tier, occupying a position in software-integrated storage architectures. These three entities illustrate the competitive structure: domestic incumbents with asset-heavy legacies, global integrators with technology differentiation, and emerging cooperative procurement vehicles fragmenting traditional utility channels.
| Leading Market Players |
|---|
| Enel SpA |
| RWE AG |
| Renewable Energy Systems Ltd |
| STEAG GmbH |
| Fluence Energy Inc. |
| Sungrow Power Supply Co. Ltd |
| TotalEnergies |
| Neoen |
| Trianel |
| Others |
Supply & Pricing Matrix
Municipal energy cooperatives and industrial offtakers in North Rhine-Westphalia and Bavaria are fragmenting procurement channels, compressing integrator margins and forcing project-based pricing with performance-linked payment terms. This buyer-base shift concentrates negotiating leverage among aggregated demand pools while exposing developers to warranty risk transfer and extended equipment financing tenors.
Pricing Analysis
Capacity additions in China's cathode active material processing facilities are reshaping price floors for lithium-ion cell supply contracts bound for German integrators. Three-tier pricing structure across premium, standard, and economy levels differentiates offerings based on cycle life guarantees and grid-forming inverter certification tiers. Cost compression in containerized battery systems is intensifying because municipal cooperatives are pooling demand to negotiate direct manufacturer agreements. Commercial and industrial clusters seeking 10-50 MWh peak-shaving systems exhibit the highest price sensitivity, while transmission operators procuring frequency regulation assets prioritize performance over unit cost.
Supply Chain Analysis
Domestic-content mandates under the EU Battery Regulation are reshaping sourcing patterns for German integrators, requiring provenance documentation and recycling infrastructure commitments. Cathode active material processing draws from China, South Korea, and Japan, while cell assembly concentrates in Poland and Hungary to serve European demand. German project developers source power electronics from domestic specialists and Taiwanese semiconductor foundries. Single-source vulnerability in lithium hydroxide refining creates exposure to geopolitical supply shocks. Distribution runs through EPC contractors and direct utility procurement channels, with brownfield thermal site repurposing accelerating project delivery timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Declining lithium-ion cell costs and premium-tier solid-state pilot deployments are expanding margin capture opportunities for technology-differentiated players across the German storage market.
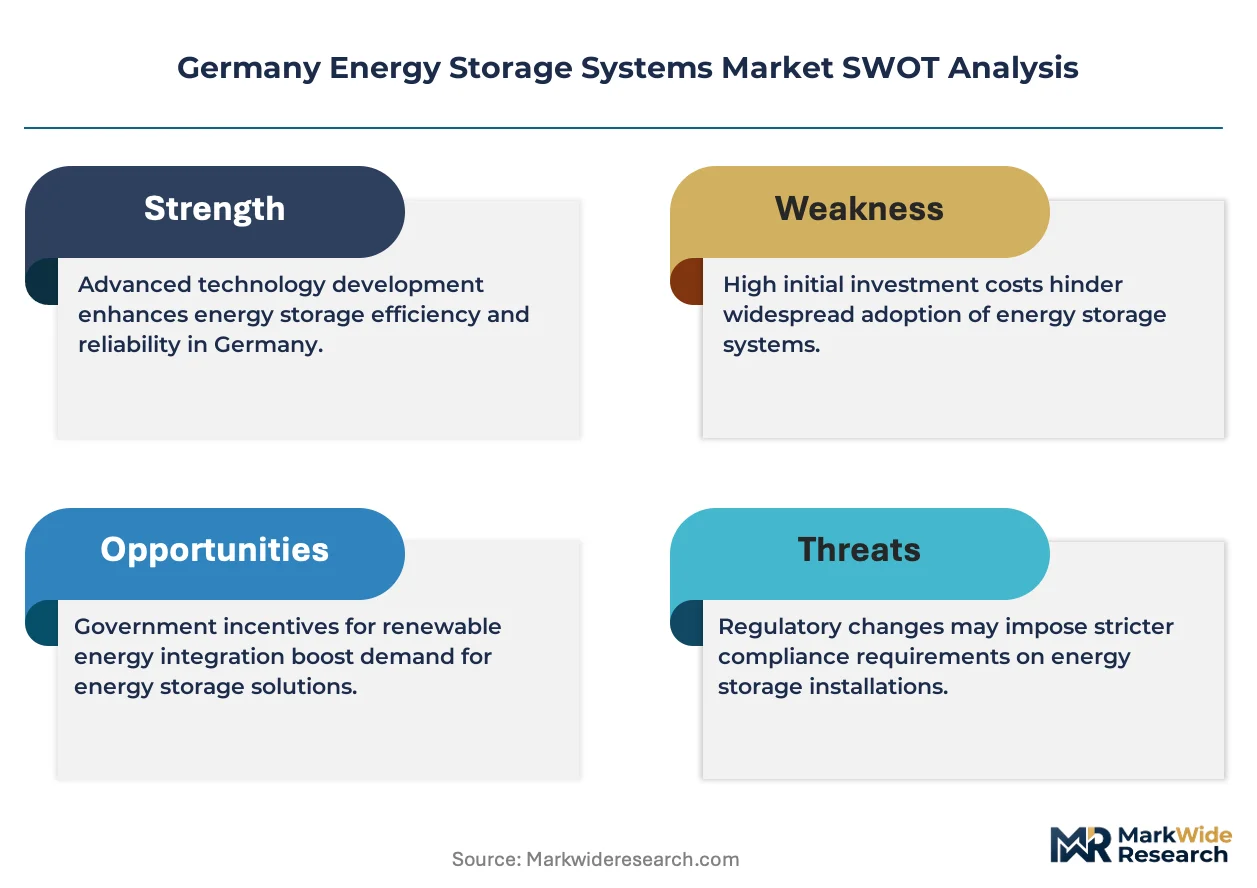
For Market Incumbents: Hedge against municipal cooperative procurement fragmentation by securing long-term cell supply agreements with Korean and Chinese manufacturers before aggregated demand pools consolidate bargaining power. Anchor project pipelines through brownfield thermal site acquisition in the Rhineland, leveraging existing substation infrastructure to compress development timelines and defend against pure-play integrators with software-defined architectures. For New Entrants and Emerging Players: The 40-60% installed cost gap between vanadium redox flow batteries and lithium-ion systems creates white-space entry for long-duration chemistry specialists targeting Schleswig-Holstein's wind corridors. Focus initial deployment on 8+ hour duration applications where cycle life economics offset capital cost premiums, using revenue-stacking software to access multiple grid products and accelerate project financeability. For Investors and Strategic Acquirers: Vertically integrated energy majors transitioning from thermal generation are the most active acquirer in this space, seeking grid-connected development platforms and power electronics engineering capabilities. Acquisition targets with brownfield site portfolios and Bundesnetzagentur interconnection queue positions offer the strongest long-term viability. The signal to watch is Berlin's pending capacity market design, which would revalue frequency regulation assets and trigger portfolio reallocation across utility-scale developers.| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Thermal Site Repurposing | Rhineland lignite plant conversions leverage existing substations to accelerate grid-scale storage permitting timelines. |
| Direct Cell Manufacturer Partnerships | Municipal cooperatives in Baden-Württemberg bypass integrators to negotiate supply agreements and shift warranty risk. |
| Grid-Forming Inverter Certification | Bundesnetzagentur frequency response mandates create premium tier differentiation for software-integrated architectures. |
| Long-Duration Chemistry Scale-Up | Iron-air and zinc-bromine technologies address seasonal shifting gaps in lithium-dominated utility portfolios. |
| Vehicle-to-Grid Infrastructure Buildout | KBA emissions standards for commercial fleets create mobile storage pools dispatchable by transmission operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against Bundesnetzagentur regulatory filings, IEA technology deployment databases, and project development tracking services. Bottom-up capacity addition modeling and top-down market sizing triangulated across technology, application, and deployment type segmentation dimensions.
Historical reference periods anchored the projection horizon to observed deployment velocities under prior EEG framework iterations and carbon neutrality mandate trajectories. The analytical framework modeled storage technology, application economics, end-user industry, and deployment type segments across the modeling period. CAGRs were derived from installed capacity buildout curves and revenue per megawatt-hour trajectories, incorporating grid code evolution and industrial electrification intensity as forecast inputs.
Caveats apply where lithium supply concentration, Bavaria permitting velocity delays, or Berlin capacity market design revisions could materially shift the outlook. Forecasts reflect assumptions about technology cost curves and regulatory enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Power Bank Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Energy Storage Software Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Natural Gas Storage Market