
 Battery Storage Boxes Market | 2026-2036
Battery Storage Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Storage Boxes Market Insights
China is reconfiguring capacity additions across battery enclosure manufacturing zones to serve both domestic energy storage procurement and export commitments. CATL leverages integrated cell-to-box architectures that compress assembly steps and reduce thermal interface layers. BYD Energy Storage anchors vertical production from lithium extraction through finished enclosure testing. Tesla Energy differentiates through software-defined thermal controls embedded at the enclosure level.
Battery storage boxes are engineered enclosures that house electrochemical cells, integrating fire suppression media, thermal runaway venting pathways, and electrical buswork into a sealed structural unit rated for outdoor installation. Wall thickness typically ranges from 1.5 mm to 3 mm cold-rolled steel or aluminum alloy, with intumescent coatings applied to achieve UL 9540A cell-level fire containment. Lithium-ion configurations dominate commercial procurement due to energy density requirements, while solid-state variants occupy emerging pilot contracts where safety premiums offset cost disadvantages. Modular design technology leads utility-scale deployments by enabling field-replaceable sub-units without system shutdown.
The International Electrotechnical Commission publishes IEC 62619 for lithium cell safety in industrial applications, while the EU Battery Directive mandates recycled content disclosures that reshape enclosure material sourcing across European supply chains. China's GB standards through SAMR enforce structural integrity testing for grid-connected storage installations. Stakeholders must monitor how divergent fire-testing protocols between jurisdictions affect cross-border product certification timelines and inventory positioning.
Market Dynamics
Utility-scale storage procurement is compressing enclosure lead times as developers race to qualify for US IRA production tax credits before statutory deadlines expire, forcing manufacturers to reconfigure assembly lines for modular, field-swappable architectures.
Growth Catalysts
- US IRA Tax Credits:The Inflation Reduction Act's standalone storage investment tax credit is accelerating utility procurement timelines, pulling forward demand from 2027-2028 into 2025-2026.
- Germany Residential Attachment:Rooftop solar mandates in new construction are driving battery attachment rates above 80% in Bavaria and Baden-Württemberg, expanding enclosure volumes for sub-20kWh systems.
- IEC 62619 Harmonization:Converging international safety standards for lithium-ion industrial cells is reducing certification duplication costs for enclosure suppliers serving multiple export markets.
Market Restraints
- Aluminum Alloy Volatility:Cold-rolled steel and 6061-T6 aluminum price swings are compressing gross margins for enclosure fabricators locked into fixed-price utility contracts.
- Chinese Supply Concentration:Over 70% of cell-to-box integrated manufacturing capacity sits in Fujian and Guangdong provinces, creating geographic risk for buyers seeking supply diversification.
- Solid-State Cost Premium:Emerging solid-state cell formats require thicker thermal barriers and redundant venting pathways that add 15-25% material cost without commensurate energy density gains.
Strategic Opportunities
- India Grid-Scale Procurement:Central Electricity Authority mandates for 500 GW non-fossil capacity by 2030 are opening tender opportunities for containerized storage enclosures in Rajasthan and Gujarat solar parks.
- EU Battery Directive Compliance Services:Recycled content disclosure requirements are creating a secondary market for enclosure material traceability and carbon accounting software integration.
- Cell-to-Box Convergence:Direct cell bonding to enclosure walls is eliminating separate module housings, compressing bill-of-materials and assembly labor for Tier 1 integrators.
Industry Challenges
- UL 9540A Testing Bottlenecks:Cell-level fire propagation certification queues at Underwriters Laboratories are extending product launch timelines by 4-6 months for new enclosure designs.
- Thermal Runaway Simulation Talent:Computational fluid dynamics expertise for venting pathway optimization remains scarce, with fewer than 200 qualified engineers across North American and European supplier bases.
- Legacy SCADA Integration:Utility buyers require Modbus and DNP3 protocol compatibility that forces enclosure-level control hardware retrofits, adding engineering overhead to standardized designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Storage Boxes Market |
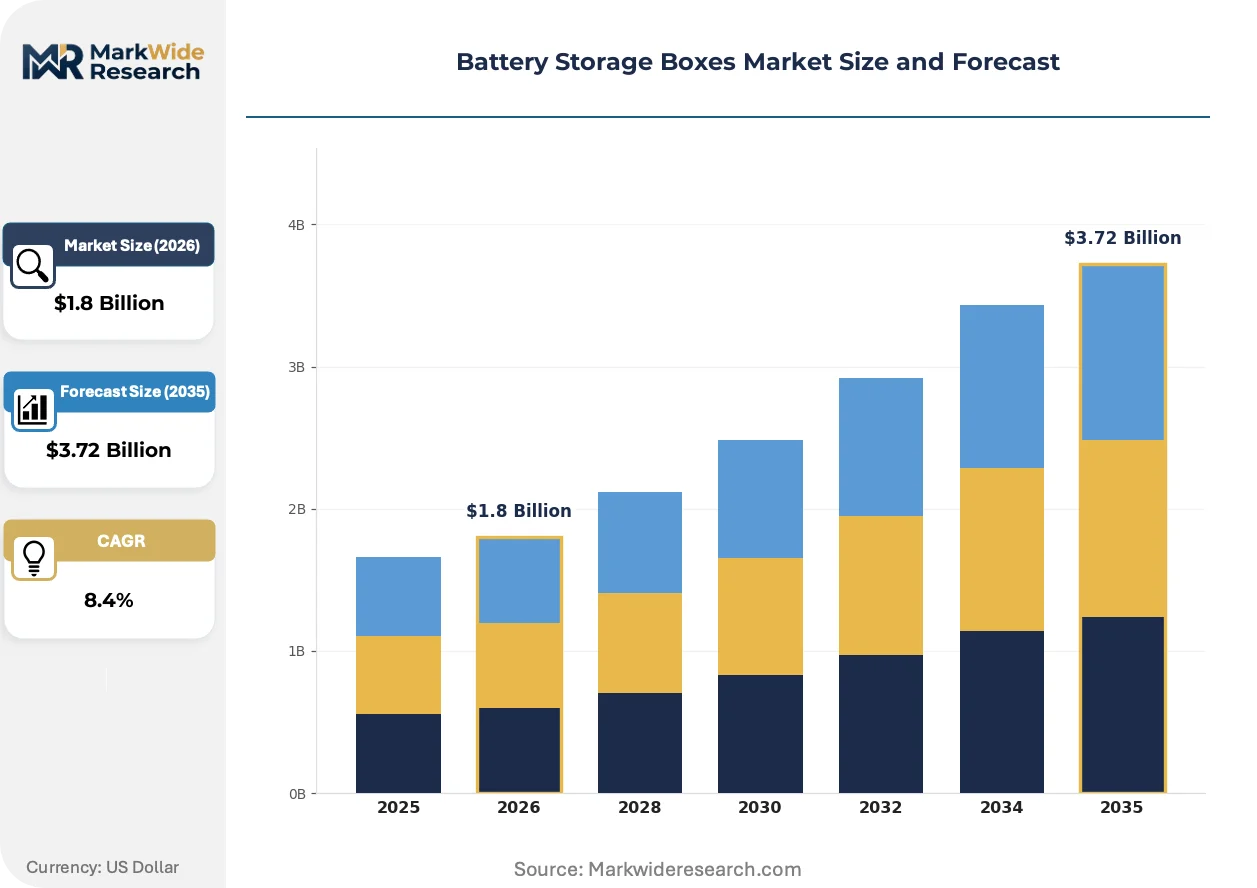
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Technology: Modular Design, Thermal Management, Fire-Resistant, Smart Monitoring, Shockproof Application: Renewable Energy Storage, Grid Stabilization, Uninterruptible Power Supply, Electric Vehicle Charging End User: Utility Providers, Telecom Operators, Data Centers, Commercial Facilities |
| Companies Covered | Sungrow, Siemens, CATL, Pylontech, EVE Energy, BYD Energy Storage, LG Energy Solution, Powin, Tesla Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Storage Boxes Market Trends and Innovations
Enclosure architecture is converging around software-defined thermal management and predictive fire suppression, displacing passive cooling designs that dominated the 2018-2023 procurement cycle.
Intumescent coating chemistry is migrating from epoxy-based formulations to water-based thin-film intumescents that achieve equivalent UL 9540A ratings at 40% reduced dry weight. US utility developers are specifying these coatings for rooftop and elevated installations where structural load limits constrain legacy approaches. The shift is compressing shipping costs and enabling ground-mounted enclosures to migrate from concrete pads to lighter helical pile foundations.
China's GB standards through SAMR now mandate seismic qualification testing for grid-connected storage enclosures in seismic zones 7 and above, mirroring California's Title 24 requirements. Manufacturers serving both markets are consolidating test protocols to single qualification runs, reducing certification costs for dual-destination products. The EU Battery Directive's recycled content mandates are accelerating parallel adoption of post-consumer aluminum in German and French enclosure production.
Buyer consolidation among independent power producers is concentrating procurement authority with engineering-procurement-construction firms that bundle enclosure specification into turnkey EPC contracts. This disintermediates traditional distributor channels in Texas and California, where Fluor, Bechtel, and Burns & McDonnell now direct material sourcing for 60% of utility-scale deployments. The shift is compressing supplier margins while extending payment terms to 90-120 days.
Battery Storage Boxes Market Segmentation
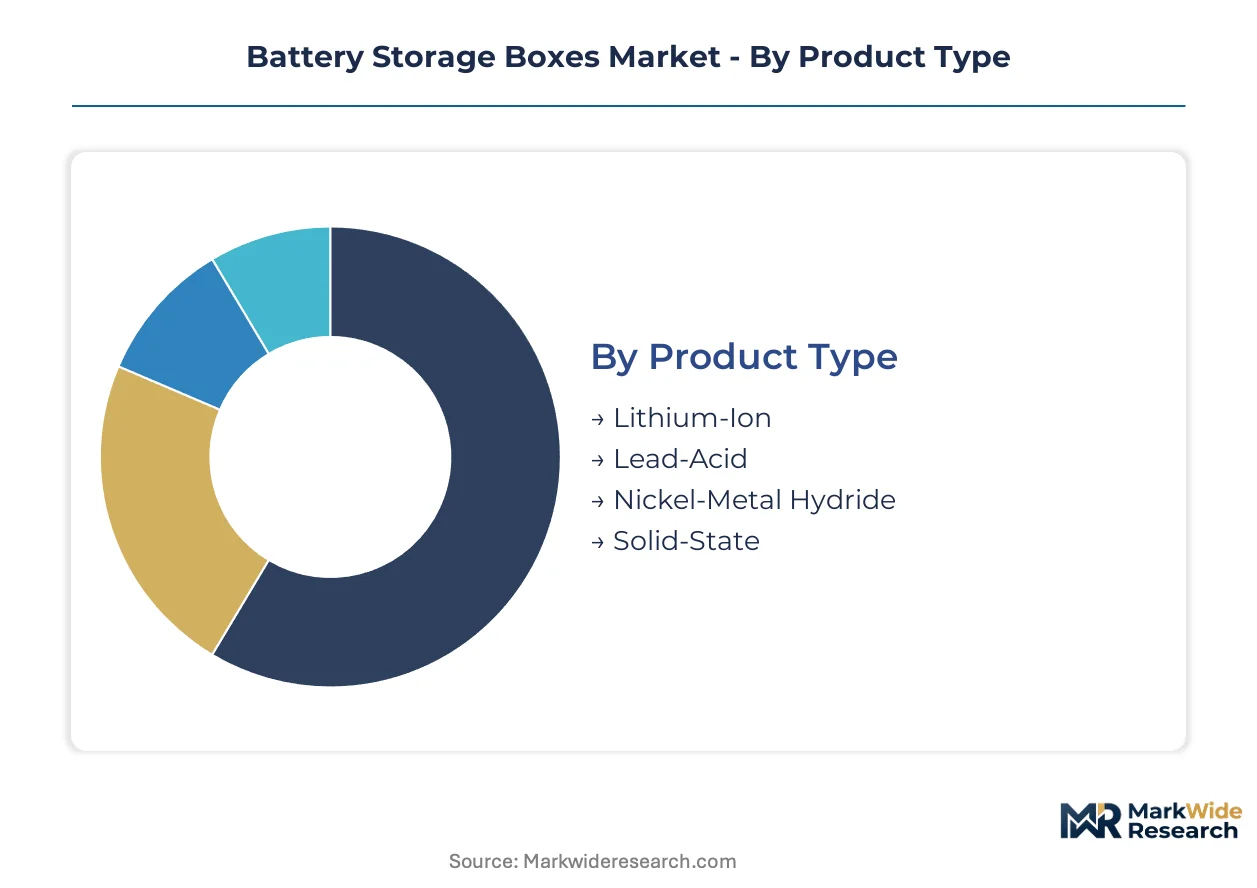
Battery storage box segmentation reveals how chemistry choices, enclosure technologies, and deployment contexts reshape procurement patterns. Suppliers configure product lines around thermal runaway containment requirements and installation environment constraints.
Product Type:
Chemistry selection dictates enclosure wall thickness, venting pathway geometry, and fire suppression media integration.
- Lithium-Ion:Cells with cobalt-oxide or iron-phosphate cathodes require 1.5-3mm steel or aluminum housings with intumescent coatings rated to UL 9540A. Demand concentrates in utility-scale deployments across Texas and California solar-plus-storage projects where IRA tax credits compress procurement timelines.
- Solid-State:Ceramic electrolyte configurations enable thinner thermal barriers but demand redundant venting channels and precision-machined compression fixtures. Pilot contracts in Bavaria and Baden-Württemberg residential installations absorb early production as safety premiums offset 15-25% material cost disadvantages.
- Lead-Acid:Flooded and valve-regulated designs persist in telecom backup applications with simpler ABS or steel enclosures.
- Nickel-Metal Hydride:Rare-earth hydride chemistries occupy niche industrial forklift and rail signaling markets with moderate thermal management requirements.
Lithium-ion commands the established base. The steepest expansion runs through solid-state.
Technology:
Enclosure engineering priorities shift from passive containment to active thermal intervention and predictive safety systems.
- Thermal Management:Liquid-cooled cold plates and phase-change materials embedded in enclosure floors maintain cell temperatures within 15-35°C operating windows. CATL and Tesla Energy embed software-defined controls that modulate coolant flow based on real-time load profiles in Arizona and Nevada grid installations.
- Modular Design:Field-replaceable sub-units with standardized 19-inch rack or container footprints enable capacity expansion without system shutdown. Fluor and Bechtel specify these architectures for 60% of Texas and California utility-scale EPC contracts.
- Fire-Resistant:Intumescent coatings and ceramic fiber barriers achieve IEC 62619 and GB standard compliance for industrial lithium systems.
- Smart Monitoring:Cell-level voltage and temperature telemetry routed through Modbus or DNP3 protocols satisfies utility SCADA integration mandates.
- Shockproof:Seismic qualification to SAMR GB standards and California Title 24 applies in zones 7 and above.
Thermal management anchors premium positioning. Modular architectures gain share fastest in utility procurement.
Application:
Deployment context determines enclosure IP ratings, foundation specifications, and grid interconnection hardware.
- Renewable Energy Storage:Containerized enclosures buffer intermittent solar and wind output with 4-hour duration configurations. Rajasthan and Gujarat solar parks in India drive tender volumes under Central Electricity Authority mandates for 500 GW non-fossil capacity.
- Grid Stabilization:Fast-frequency response installations require sub-second dispatch capability with reinforced electrical buswork and isolation transformers. North American independent system operators specify these for transmission deferral in congested corridors.
- Uninterruptible Power Supply:Data center and telecom applications prioritize compact footprints and acoustic attenuation.
- Electric Vehicle Charging:Co-located storage buffers DC fast-charger demand spikes in commercial parking structures.
Renewable pairing dominates current procurement. Grid stabilization offers the most rapid capacity expansion.
End User:
Buyer sophistication and contract structures fragment pricing power across the value chain.
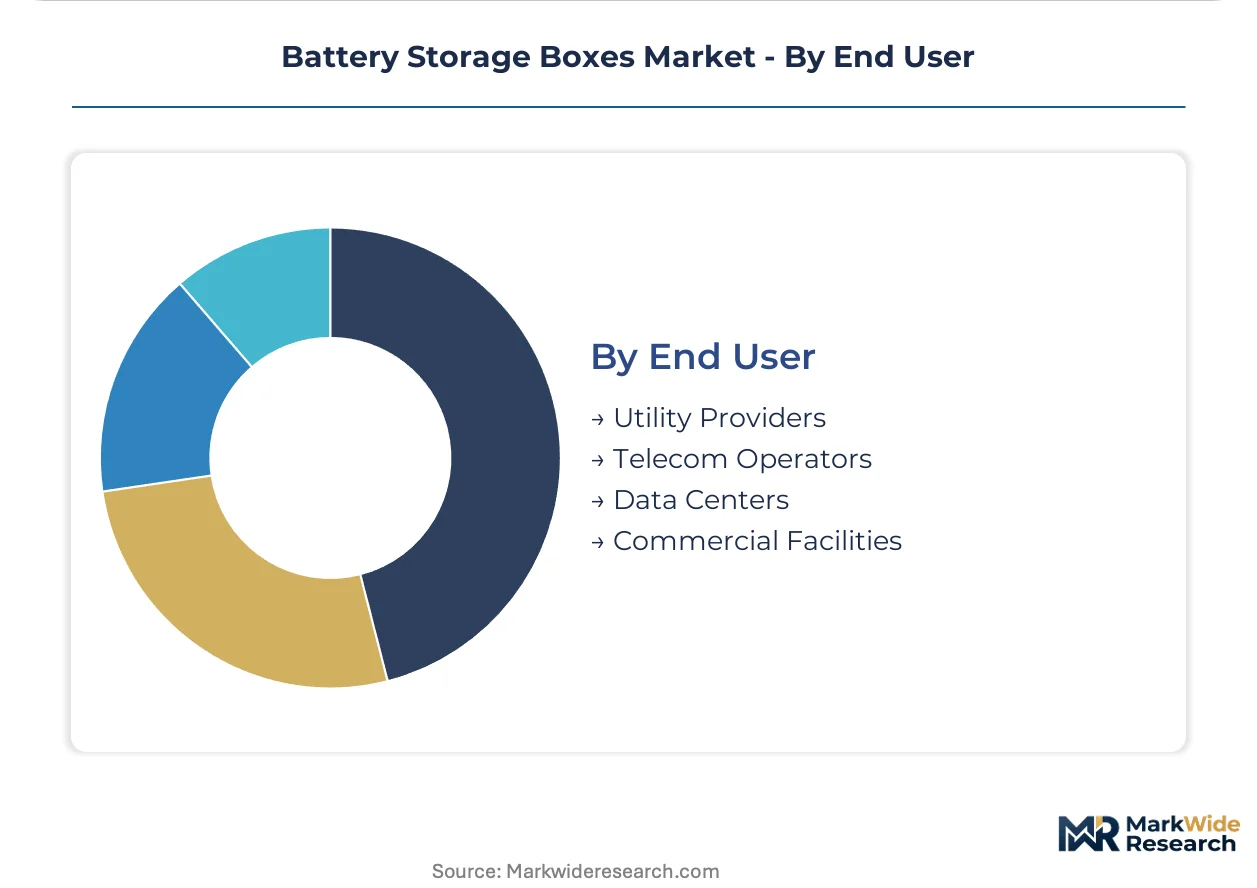
- Utility Providers:Engineering-procurement-construction firms bundle enclosure specifications into turnkey contracts with 90-120 day payment terms. Consolidated procurement authority with Fluor, Bechtel, and Burns & McDonnell compresses supplier margins while demanding UL 9540A certification.
- Data Centers:Hyperscale operators specify N+1 redundancy with lithium-ion enclosures integrated into building management systems. Northern Virginia and Frankfurt clusters drive volume for 10-20 MWh behind-the-meter installations.
- Telecom Operators:Tower companies prioritize lead-acid replacement cycles and remote monitoring compatibility.
- Commercial Facilities:Retail and manufacturing sites deploy sub-500kWh systems for peak shaving and backup power.
Utility procurement commands volume concentration. Data center demand expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards for seismic qualification and fire containment anchor China's regulatory framework for battery storage enclosures, with Fujian and Guangdong provinces concentrating integrated cell-to-box manufacturing capacity.
United States
Utility-scale developers in Texas and California compress procurement timelines to qualify for IRA standalone storage tax credits before statutory deadlines expire. FERC Order 2222 enables distributed energy resource aggregation that expands enclosure demand for behind-the-meter installations. Arizona and Nevada host grid-scale deployments where software-defined thermal controls from Tesla Energy modulate coolant flow based on real-time load profiles.
Germany
Rooftop solar mandates in new construction drive battery attachment rates above 80 percent in Bavaria and Baden-Württemberg, expanding volumes for sub-20kWh residential enclosures. The EU Battery Directive mandates recycled content disclosures that reshape material sourcing across European supply chains. Industrial clusters in North Rhine-Westphalia concentrate manufacturing for containerized utility systems serving continental grid stabilization contracts.
China
Domestic energy storage procurement and export commitments reconfigure capacity additions across battery enclosure manufacturing zones. GB standards through SAMR enforce structural integrity testing for grid-connected installations in seismic zones 7 and above. CATL leverages integrated cell-to-box architectures in Fujian facilities that compress assembly steps and reduce thermal interface layers.
India
Central Electricity Authority mandates for 500 GW non-fossil capacity by 2030 open tender opportunities for containerized storage enclosures in Rajasthan and Gujarat solar parks. BIS certification requirements for electrical equipment create compliance checkpoints for imported enclosure systems. Manufacturing clusters in Maharashtra and Karnataka develop domestic fabrication capacity to serve anticipated procurement waves.
Australia
Grid-scale renewable integration drives demand for 4-hour duration containerized enclosures in New South Wales and Victoria transmission networks. The country's national energy regulator enforces connection standards that specify enclosure-level protection and monitoring capabilities. Queensland solar parks deploy modular architectures enabling field-replaceable sub-units without system shutdown.
Battery Storage Boxes Market Competitive Landscape
Integrated cell-to-box specialists and modular system architects split the market between architectures that compress bill-of-materials and designs that prioritize field serviceability. The vendor base concentrates among Asian manufacturers with captive cell production and North American integrators with software-defined control layers. Two strategic archetypes dominate: vertically integrated battery producers that enclose proprietary cell formats, and independent enclosure fabricators that qualify third-party electrochemistry. Competitive moves center on capacity expansion in Indian and Southeast Asian manufacturing zones and strategic partnerships between enclosure suppliers and engineering-procurement-construction firms.
Within the integrated-manufacturer tier, CATL and BYD Energy Storage represent archetypes of upstream-controlled production spanning lithium extraction through finished enclosure testing. Tesla Energy occupies a distinct position embedding software-defined thermal controls at the enclosure level. These three companies exemplify how control over cell chemistry and thermal management software creates differentiation in utility procurement cycles where IRA tax credit deadlines compress supplier qualification timelines.
| Leading Market Players |
|---|
| Sungrow |
| Siemens |
| CATL |
| Pylontech |
| EVE Energy |
| BYD Energy Storage |
| LG Energy Solution |
| Powin |
| Tesla Energy |
| Others |
Pricing and Supply Chain Analysis
Aluminum alloy price volatility determines both tier spreads between certified and uncertified enclosures and the geographic reconfiguration of fabrication networks. Contract manufacturers locked into fixed-price utility offtake agreements absorb margin compression when 6061-T6 aluminum spot markets swing, forcing selective backward integration into cold-rolled steel sourcing and regional buffer stock positioning.
Pricing Analysis
Geographic price spreads between Chinese export quotations and European domestic fabrication run 15-25 percent after EU carbon border adjustment and recycled content disclosure compliance costs. Three-tier pricing structure across UL 9540A-certified premium, IEC 62619-standard, and uncertified economy levels separates utility-scale EPC bundles from residential retrofit volumes. Cost compression in the economy tier is intensifying because Fujian and Guangdong capacity expansions outpace Indian and Southeast Asian qualification timelines. Independent power producers exhibit the highest price sensitivity due to bundled EPC contract structures, while data center operators accept premiums for N+1 redundancy and building management system integration.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn Industrial Internet, Jabil, and Flex holding dedicated energy storage enclosure lines across Shenzhen, Suzhou, and Penang facilities. Raw material feeds draw from Chilean lithium carbonate, Australian spodumene concentrate, and domestic Chinese cold-rolled steel from Baowu Steel Group. Single-source vulnerability sits with 70 percent-plus cell-to-box integrated capacity anchored in Fujian and Guangdong provinces, exposing buyers to SAMR export license variability and US tariff exposure. Distribution runs through engineering-procurement-construction firm direct procurement, disintermediating traditional distributor channels in Texas and California utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state cell format maturation threatens incumbent lithium-ion enclosure architectures with obsolescence risk as ceramic electrolyte configurations achieve cost parity. Incumbents must navigate this substitution trajectory while defending utility-scale procurement relationships.
For Market Incumbents: Pre-empt solid-state displacement by embedding software-defined thermal controls that retrofit across cell chemistry transitions, and anchor capacity additions in Rajasthan and Gujarat manufacturing zones to capture Indian Central Electricity Authority procurement waves ahead of domestic fabrication qualification. Certification investment in BIS compliance creates channel control leverage against late entrants. For New Entrants and Emerging Players: Pursue EU Battery Directive compliance service white space, specifically material traceability software and carbon accounting integration for German and French enclosure producers. The most penetrable segment sits with sub-20kWh residential systems in Bavaria and Baden-Württemberg where attachment rates exceed 80 percent but incumbent software layers remain underdeveloped. A direct-to-utility developer go-to-market angle bypasses EPC bundling that compresses margins in Texas and California. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors cell-to-box integrators with captive thermal management IP over modular fabricators dependent on third-party electrochemistry. Long-term viability across the projection horizon rests on control over venting pathway engineering and computational fluid dynamics talent pools. Acquisition targets should display backward integration into lithium extraction or forward integration into SCADA protocol compatibility. The signal to watch is UL 9540A testing queue duration as a proxy for new entrant qualification friction.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Box Architecture Deployment | CATL and BYD compression of assembly steps eliminates separate module housings and thermal interface layers. |
| Software-Defined Thermal Control Integration | Tesla Energy embeds predictive fire suppression algorithms that displace passive cooling designs in Arizona and Nevada. |
| Indian Manufacturing Footprint Establishment | Maharashtra and Karnataka clusters serve Central Electricity Authority 500 GW non-fossil capacity mandates. |
| EU Battery Directive Compliance Service Launch | Recycled content disclosure requirements reshape material sourcing across German and French supply chains. |
| Seismic Qualification Consolidation | Dual SAMR GB and California Title 24 testing reduces certification costs for earthquake zone deployments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, independent power project developers, EPC contractors with enclosure specification authority, grid operators, and thermal management system engineers. Secondary validation drew from FERC interconnection queues, EIA storage deployment databases, IEA stationary storage outlooks, and SAMR GB standard publication records. Bottom-up enclosure shipment tallies by chemistry and technology tier were triangulated against top-down utility procurement pipeline aggregations.
Calibration against historical deployment trajectories in Texas, California, and Germany anchored volume projections across the analysis window. Segmentation dimensions modeled span chemistry selection, enclosure technology tier, application context, and end-user procurement structure. CAGRs were derived from logistic diffusion curves fitted to policy incentive expiration schedules and manufacturing capacity commissioning timelines. Industry-specific forecast inputs include IRA tax credit qualification deadlines and IEC 62619 harmonization progress across notified bodies.
Macroeconomic conditions sit as an overlay; deviation in aluminum alloy spot prices, lithium carbonate contract terms, or cross-border tariff schedules would shift the trajectory. Forecasts reflect underlying assumptions about SAMR export license continuity and UL 9540A testing throughput capacity. Quarterly review of FERC interconnection queue depth, Indian BIS certification issuance rates, and EPC firm procurement bundle specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Ultracapacitors Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
Water Electrolysis Machine Market