
 Solid-State Car Battery Market | 2026-2036
Solid-State Car Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Solid-State Car Battery Market Analysis
Subscription-based battery health monitoring and software-defined range optimization is pivoting how solid-state car battery value gets captured. QuantumScape Corporation leads ceramic separator manufacturing at scale in California. Toyota Motor Corporation anchors its strategy around sulfide electrolyte chemistry for next-generation EV platforms. Samsung SDI competes through aggressive R&D spending on bulk intercalation architectures.
A solid-state car battery replaces liquid or gel electrolytes with ion-conducting solids such as sulfides, oxides, or polymers, enabling lithium metal anodes and energy densities exceeding conventional lithium-ion systems by eliminating thermal runaway risks. The technology serves primarily to extend electric vehicle range while compressing charging intervals and fire hazards. Lithium metal chemistry dominates current pilot production due to its theoretical capacity advantage, though solid polymer form factors attract aftermarket interest for retrofit compatibility. Thin film manufacturing remains cost-prohibitive for mass automotive deployment, pushing margin concentration toward composite electrolyte approaches that balance ionic conductivity with mechanical durability.
The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations that reshape cell qualification requirements for European OEMs. China's MIIT enforces GB standards on solid electrolyte stability testing, while Japan's METI coordinates domestic supply chain consortia through national technology roadmaps. Stakeholders must track which electrolyte chemistry achieves automotive qualification first, as this determination will lock in manufacturing equipment investments and patent licensing structures for the decade ahead.
Market Dynamics
The transition from pilot production to automotive qualification is compressing equipment lead times and locking in electrolyte chemistry commitments before cost curves have stabilized.
Growth Catalysts
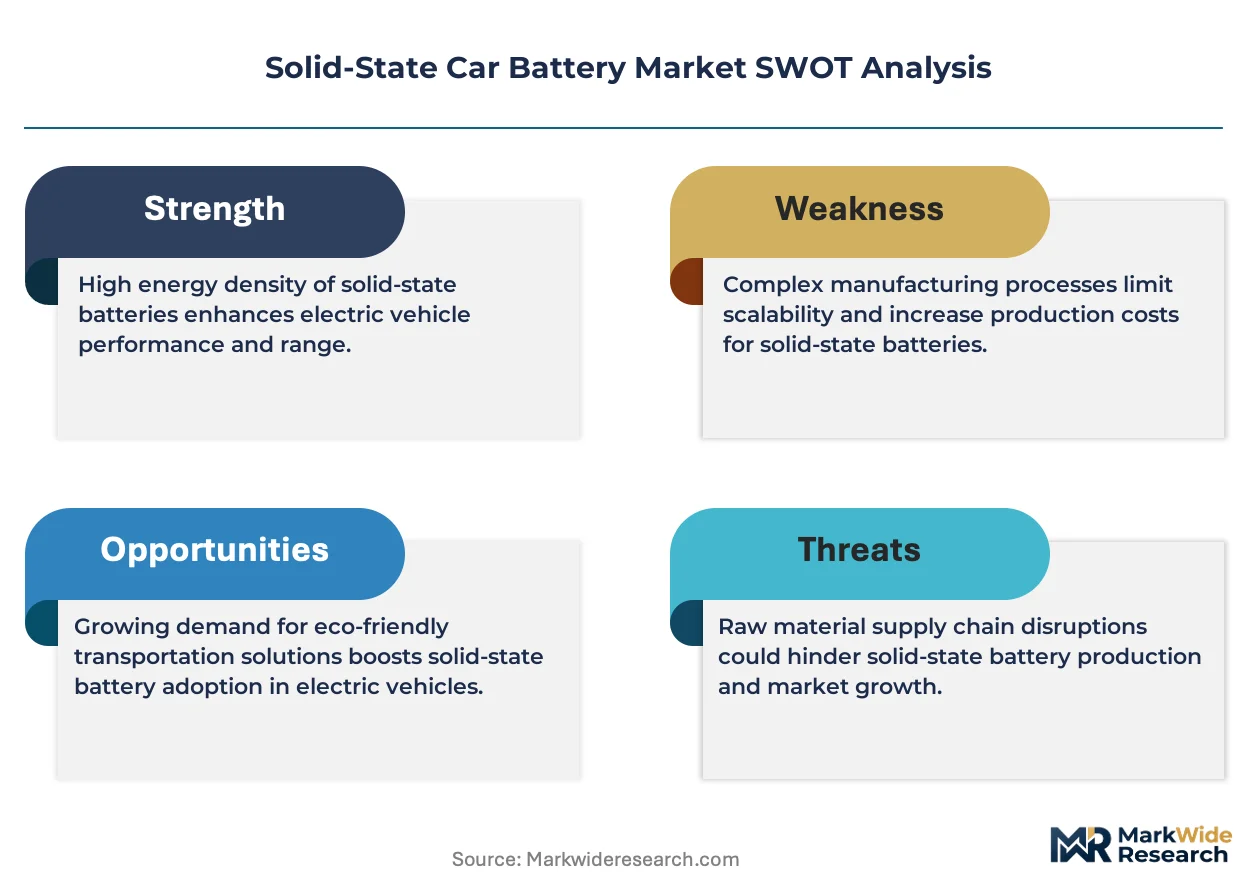
- EU Battery Regulation:Recycled content mandates and carbon footprint declarations force OEMs to qualify solid-state cells for European platforms, accelerating supplier certification timelines.
- Sulfide electrolyte breakthroughs:Toyota's pilot lines in Japan demonstrate manufacturable lithium-metal interfaces, validating sulfide chemistry for volume production.
- Fast-charging infrastructure buildout:China's GB standards on solid electrolyte stability testing create regulatory clarity that de-risks cellmaker capital commitments.
Market Restraints
- Lithium metal supply concentration:Primary lithium extraction concentrates in South American salt flats and Australian hard-rock mines, creating geopolitical exposure for anode material security.
- Thin-film manufacturing cost floor:Vacuum deposition equipment and cleanroom requirements impose capital intensity that excludes mid-tier cellmakers from sulfide electrolyte production.
- Solid polymer substitution:Polymer electrolyte architectures offer retrofit compatibility for existing lithium-ion pack designs, diverting aftermarket investment from ceramic separator development.
Strategic Opportunities
- India's PLI scheme:Advanced chemistry cell production incentives create first-mover advantage for solid-state manufacturing capacity serving domestic EV demand.
- Software-defined battery management:Cloud-based health monitoring and range optimization services generate recurring revenue streams independent of hardware margins.
- Aviation electrification:Regional electric aircraft platforms demand energy densities above 400 Wh/kg, a threshold only lithium-metal solid-state architectures can satisfy.
Industry Challenges
- Dendrite suppression engineering:Lithium metal anode cycling stability requires interface engineering expertise that remains scarce across automotive cell development teams.
- Automotive qualification timelines:UN 38.3 and UN ECE R100 certification cycles for solid-state chemistries extend 18-24 months beyond conventional lithium-ion validation.
- Patent thicket navigation:Oxide and sulfide electrolyte IP portfolios held by Japanese and Korean consortia complicate licensing negotiations for Western cellmakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid-State Car Battery Market |
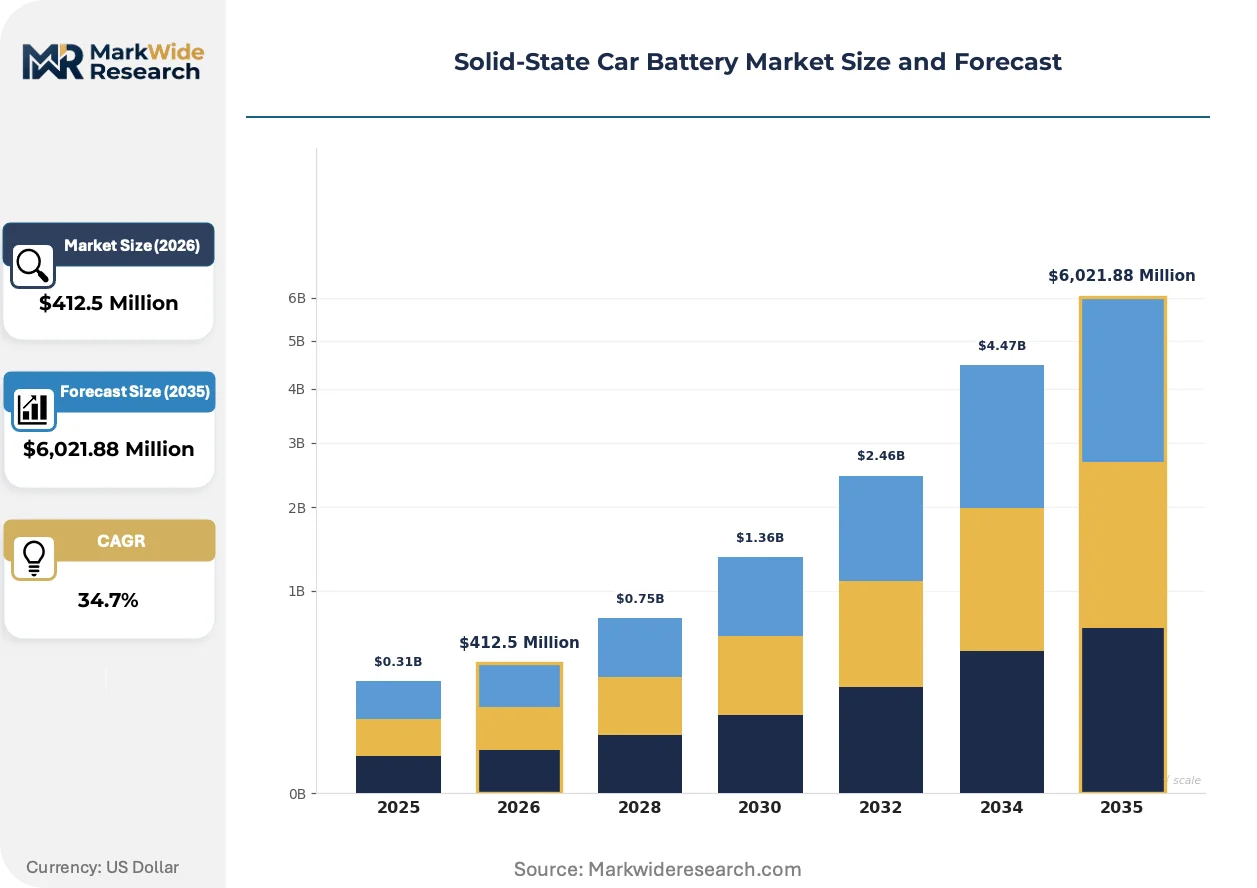
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $6,021.88 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Metal, Sulfur, Sodium Ion, Solid Polymer End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Thin Film, Bulk Intercalation, Composite Electrolytes, Multiparticulate Form Factor: Prismatic, Cylindrical, Pouch, Custom Designs |
| Companies Covered | Solid Power, Inc., QuantumScape Corporation, ProLogium Technology Co, Ltd., Factorial Energy, Blue Solutions, CATL, Toyota Motor Corporation, Samsung SDI, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid-State Car Battery Market Emerging Trajectories
Electrolyte manufacturing is automating quality control steps that previously required manual intervention, while regulatory pressure on carbon intensity reshapes qualification criteria.
Composite electrolyte architectures combining sulfide conductivity with oxide mechanical stability are automating defect detection through in-line impedance spectroscopy. BMW and Volkswagen qualification programs demand six-sigma uniformity across separator thickness, forcing equipment suppliers to integrate machine vision at every coating stage. This automation is compressing yield learning curves from 36 months toward 18 months for pilot-to-production transitions.
China's MIIT enforcement of GB standards on solid electrolyte stability testing mandates thermal abuse propagation resistance that exceeds UN 38.3 baselines. Cellmakers must submit third-party validation data from 150°C nail penetration and external short circuit tests before receiving automotive supply permits. Korean manufacturers are responding by consolidating R&D with domestic materials suppliers to accelerate iterative formulation testing.
Fleet operators in California and Germany now specify battery health transparency as a procurement criterion, displacing upfront cost-per-kWh as the dominant purchasing metric. Leasing companies and mobility-as-a-service providers demand real-time state-of-health data feeds to optimize residual value calculations. This specification shift concentrates contract awards with cellmakers offering embedded telemetry and predictive degradation modeling.
Solid-State Car Battery Market Segmentation
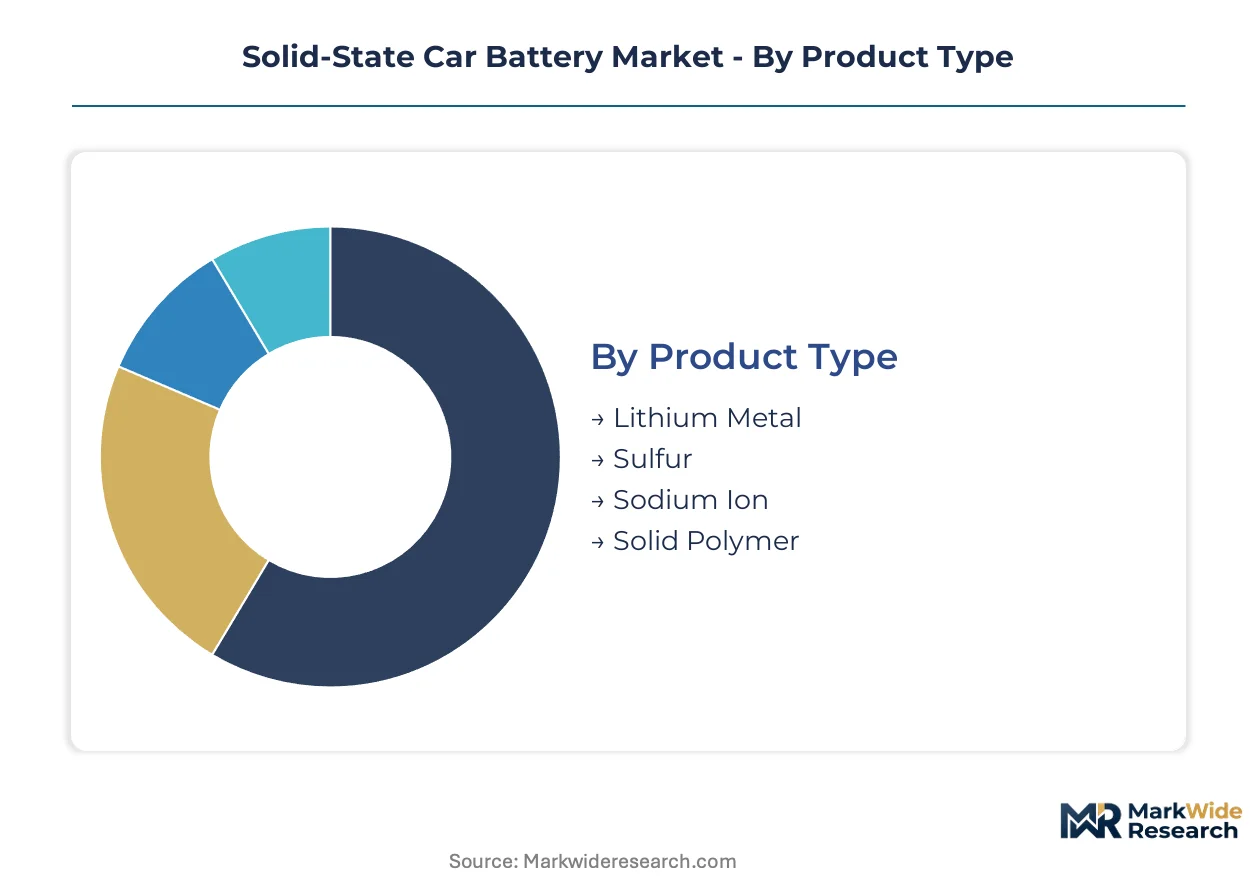
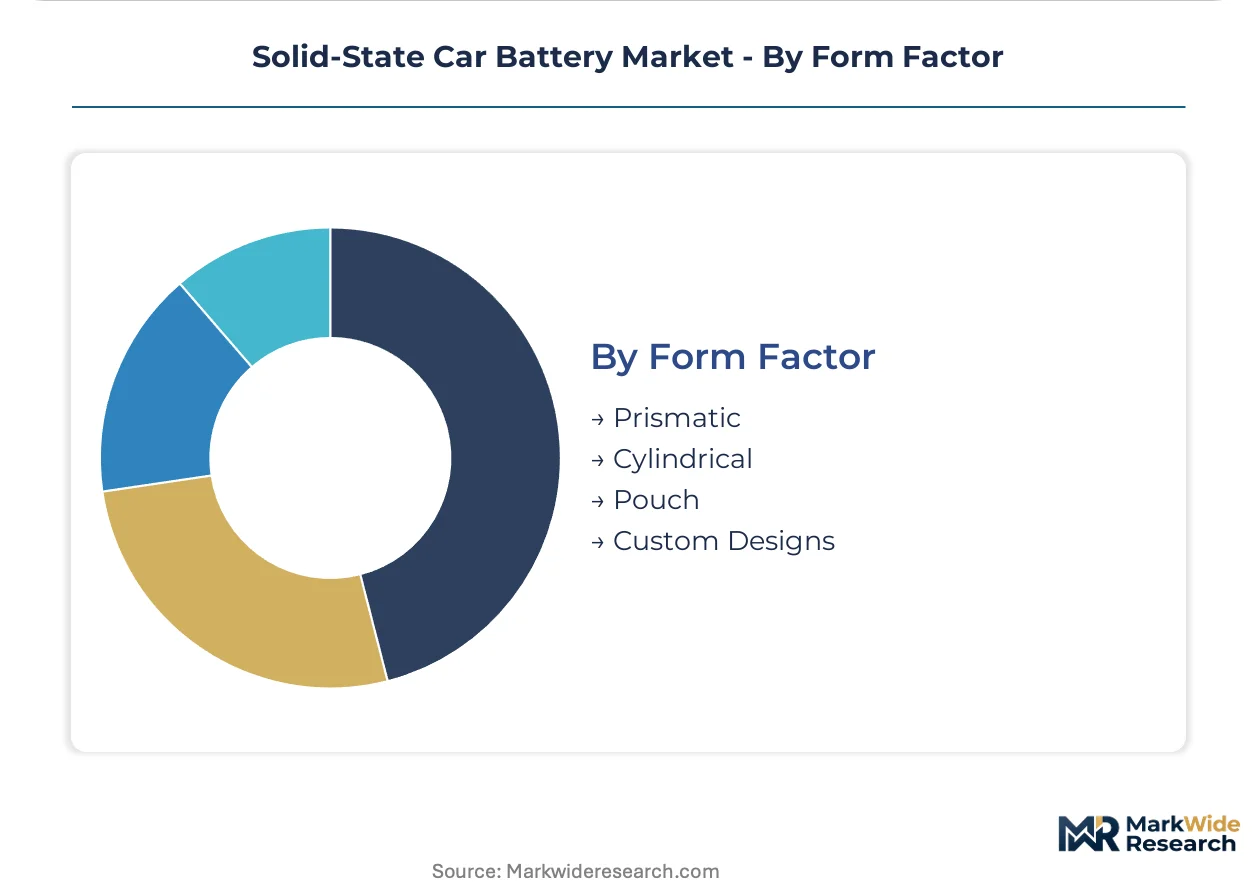
Solid-state car battery procurement decisions cascade through chemistry selection, manufacturing scale, and pack integration requirements. Each segmentation dimension locks in distinct equipment investments, supply chain partnerships, and qualification timelines that shape competitive positioning across the value chain.
Product Type:
Cost tier determines which chemistry platforms attract capital commitment versus pilot-stage evaluation.
- Lithium Metal:Delivers theoretical energy density above 400 Wh/kg through lithium anodes paired with ceramic or sulfide electrolytes. Toyota's pilot lines in Japan and QuantumScape's California manufacturing validate this chemistry for premium EV platforms demanding maximum range extension.
- Sulfur:Combines lithium metal anodes with sulfur cathodes to achieve cost advantages over oxide-based systems while maintaining solid-state safety benefits. Korean cellmakers concentrate development here for mid-market EV applications where energy density requirements sit below aviation thresholds but above conventional lithium-ion capabilities.
- Sodium Ion:Eliminates lithium supply chain exposure through abundant sodium chemistry, trading energy density for material security.
- Solid Polymer:Offers retrofit compatibility with existing lithium-ion pack architectures, attracting aftermarket investment for fleet conversions.
Lithium Metal leads on scale; Sulfur leads on momentum.
End User:
Volume concentration shifts procurement power toward integrators controlling platform design decisions.
- OEMs:BMW, Volkswagen, and Toyota direct qualification programs that compress supplier certification timelines through six-sigma uniformity mandates across separator thickness.
- Tier-1 Suppliers:Samsung SDI and contemporary cellmakers invest in bulk intercalation architectures to secure long-term supply contracts with platform architects.
- Aftermarket Providers:Fleet operators in California and Germany specify battery health transparency as procurement criteria, displacing upfront cost-per-kWh metrics.
- Vehicle Assemblers:Contract manufacturers integrate pre-qualified cells from approved supplier lists, limiting direct electrolyte chemistry selection authority.
OEMs concentrate design authority; Aftermarket Providers are expanding most quickly through software-defined service models.
Technology:
Manufacturing maturity separates near-term deployable platforms from capital-intensive development-stage approaches.
- Thin Film:Vacuum deposition equipment and cleanroom requirements impose capital intensity that excludes mid-tier cellmakers from sulfide electrolyte production.
- Bulk Intercalation:Samsung SDI anchors aggressive R&D spending here, targeting volume production scalability through conventional coating and calendaring equipment adapted for solid electrolyte slurries.
- Composite Electrolytes:Balances sulfide ionic conductivity with oxide mechanical stability, automating defect detection through in-line impedance spectroscopy.
- Multiparticulate:Architectures incorporating multiple ceramic phases to suppress dendrite propagation at lithium metal interfaces.
Bulk Intercalation dominates near-term capacity; Composite Electrolytes show steepest expansion trajectory through qualification program adoption.
Form Factor:
Pack integration constraints and thermal management requirements drive geometry selection across vehicle platforms.
- Prismatic:Dominates European OEM qualifications where BMW and Volkswagen demand six-sigma uniformity across separator thickness for cell-to-pack architectures.
- Cylindrical:Tesla's legacy format investments create path dependency, though solid-state adaptation requires redesigned electrode winding equipment.
- Pouch:Flexible packaging accommodates solid polymer electrolyte expansion during cycling, attracting aftermarket retrofit applications.
- Custom Designs:Aviation electrification platforms specify non-standard geometries to maximize volumetric energy density within airframe constraints.
Prismatic captures automotive volume; Custom Designs gain share fastest through aviation electrification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward jurisdictions offering regulatory clarity and capital subsidies for solid-state cell qualification. The cost-of-compliance gap between automotive-grade certification regimes is reshaping where pilot lines convert to volume manufacturing.
United States
California fleet operators and leasing companies now specify real-time battery health telemetry as a procurement requirement. The Inflation Reduction Act domestic content provisions accelerate supplier certification timelines for solid-state pack assembly. QuantumScape's manufacturing presence in San Jose anchors sulfide electrolyte development for premium EV platforms.
Germany
BMW and Volkswagen qualification programs demand six-sigma uniformity across separator thickness for cell-to-pack architectures. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations that reshape cell qualification requirements. Bavarian industrial clusters coordinate equipment supplier integration for automated defect detection systems.
China
CATL and domestic cellmakers scale composite electrolyte production for mid-market EV platforms serving domestic demand. MIIT enforcement of GB standards on solid electrolyte stability testing mandates thermal abuse propagation resistance exceeding UN 38.3 baselines. Yangtze River Delta manufacturing corridors concentrate pilot-to-production transitions for sulfide chemistry platforms.
Japan
Toyota's pilot lines in Nagoya demonstrate manufacturable lithium-metal interfaces, validating sulfide chemistry for volume production. METI coordinates domestic supply chain consortia through national technology roadmaps targeting automotive qualification. Kanto region research clusters concentrate dendrite suppression engineering expertise for next-generation anode development.
South Korea
Samsung SDI anchors aggressive R&D spending on bulk intercalation architectures to secure long-term supply contracts. Korean manufacturers consolidate R&D with domestic materials suppliers to accelerate iterative formulation testing under GB standard requirements. Busan-Ulsan industrial complexes house pilot production lines for aviation electrification platforms demanding energy densities above 400 Wh/kg.
Solid-State Car Battery Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with chemistry-specific intellectual property holders commanding premium positioning in qualification-driven procurement. The vendor base concentrates around three strategic archetypes: integrated automotive OEMs with captive cell development, independent solid-state specialists pursuing licensing revenue, and diversified lithium-ion incumbents adapting existing manufacturing infrastructure. Dominant competitive moves include strategic partnerships for electrolyte material supply security and geographic expansion toward jurisdictions offering production incentives and regulatory clarity.
Within the independent specialist tier, QuantumScape Corporation and Solid Power, Inc. exemplify US-based ventures pursuing ceramic separator manufacturing scale. ProLogium Technology Co, Ltd. represents Taiwan-headquartered players targeting sulfide electrolyte commercialization for automotive qualification. Factorial Energy occupies a position among venture-backed developers pursuing lithium-metal interface engineering for next-generation pack architectures.
| Leading Market Players |
|---|
| Solid Power, Inc. |
| QuantumScape Corporation |
| ProLogium Technology Co, Ltd. |
| Factorial Energy |
| Blue Solutions |
| CATL |
| Toyota Motor Corporation |
| Samsung SDI |
| LG Energy Solution |
| Others |
Supply Flow & Price Mechanics
Bulk intercalation manufacturing transitions are compressing unit economics while redistributing margin capture toward electrolyte material suppliers controlling sulfide and oxide precursor networks. This production-method shift simultaneously lowers capital barriers for mid-tier cellmakers and concentrates pricing power among Japanese and Korean chemical conglomerates with captive electrolyte synthesis capabilities.
Pricing Analysis
Direct-to-OEM contracting eliminates distributor markups for automotive qualification volumes, though aftermarket channels retain 15-25 point premiums for solid polymer retrofit packs. Pricing stratifies across aviation-grade certification, automotive qualification, and aftermarket compatibility tiers, with UN ECE R100 certification adding substantial cost premiums. Cost compression in sulfide electrolyte production is intensifying as Chinese GB standard compliance enables scale economies, though lithium metal anode supply constraints limit downstream price erosion. Fleet operators in California demonstrate lowest price sensitivity due to residual value optimization priorities, while vehicle assemblers in emerging markets remain most cost-constrained.
Supply Chain Analysis
Automotive qualification gating concentrates electrolyte precursor supply among Japan, South Korea, and Germany, where METI-coordinated consortia and KBA certification regimes validate supplier networks. Raw material dependencies center on lithium metal from Australian hard-rock and Chilean brine operations, sulfide precursors from Korean chemical processors, and ceramic oxide substrates from German specialty materials producers. Single-source vulnerability persists for dendrite-suppression interface coatings, where patent-thicket restrictions limit qualified supplier pools. Distribution runs through Tier 1 integrators holding OEM-approved supplier list status, with direct cellmaker-OEM relationships emerging for aviation electrification platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state car battery economics represent a margin-expansion trajectory as composite electrolyte yields improve and software-defined battery management unlocks recurring revenue streams independent of hardware commoditization pressures.
For Market Incumbents: Deploy captive electrolyte synthesis capacity to defend margin position against Korean and Japanese chemical suppliers consolidating precursor supply. Secure long-term lithium metal offtake agreements with Australian and Chilean producers to hedge anode material concentration risk. Accelerate UN ECE R100 certification investments to maintain OEM-approved supplier list status as qualification timelines compress. For New Entrants and Emerging Players: Solid polymer retrofit compatibility offers the most penetrable white-space for aftermarket fleet conversions in California and Germany, where battery health transparency specifications displace upfront cost metrics. Target aviation electrification platforms demanding energy densities above conventional lithium-ion thresholds, where qualification barriers remain lower than automotive volumes. Pursue direct contracting with regional electric aircraft developers as a go-to-market angle bypassing entrenched automotive supply chains. For Investors and Strategic Acquirers: Valuations sit cheapest among venture-backed developers with lithium-metal interface engineering expertise but lacking manufacturing scale. Long-term viability framing centers on which electrolyte chemistry achieves automotive qualification first, locking in decade-long equipment and licensing structures. Watch for GB standard compliance announcements from Chinese cellmakers as the inflection signal indicating sulfide chemistry cost curves have crossed commercial viability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Material Backward Integration | Captures margin from Japanese and Korean chemical suppliers controlling sulfide precursor networks. |
| Aviation Electrification Partnership | Secures early revenue from Lilium and Joby Aviation platforms demanding 400 Wh/kg energy density. |
| GB Standard Compliance Investment | Unlocks Chinese domestic market access under MIIT enforcement exceeding UN 38.3 baselines. |
| Software-Defined Battery Management Launch | Generates recurring revenue from California fleet operators specifying health telemetry procurement. |
| Composite Electrolyte Manufacturing Scale-Up | Balances sulfide conductivity with oxide stability for BMW six-sigma uniformity mandates. |
Methodological Framework
Bottom-up OEM platform modeling reconciled against top-down electrolyte chemistry production tracking forms the analytical core of this study. Primary interviews with cell development executives, Tier 1 supplier procurement leads, OEM platform engineers, and aviation electrification program directors combined with secondary validation from SEC filings, MIIT GB standard enforcement records, EU Battery Regulation implementation documents, and vehicle production databases. Triangulation across these sources ensures supply-side capacity estimates align with demand-side qualification timelines.
Input-output matrices map electrolyte chemistry selection through manufacturing equipment investments, patent licensing structures, and regional regulatory compliance costs across the projection horizon. Segmentation dimensions include product chemistry, end-user procurement authority, manufacturing technology maturity, and pack form factor integration constraints. CAGRs derive from iterative convergence of capacity buildout schedules, automotive qualification timeline probabilities, and fleet operator specification shifts toward software-defined service models.
The model holds under sustained automotive electrification policy support and lithium metal supply continuity; deviation in sulfide electrolyte stability breakthroughs or EU Battery Regulation enforcement intensity would shift volume and value trajectories. Forecasts reflect documented assumptions regarding pilot-to-production yield learning curves and OEM platform standardization decisions. A model refresh is warranted upon material change in GB standard compliance timelines or METI technology roadmap revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
North America NMC Battery Pack Market
Batteries
Europe Industrial Battery Market
Batteries
Grid-Scale Lead-Acid Battery Market
Batteries
Lithium Marine Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
Disposable Batteries Market
Batteries
High Voltage Battery Market
Batteries
East Europe Battery Market
Batteries
Micro Battery Market
Batteries
India Alkaline Battery Market
Batteries
Industrial Backup Battery Market
Batteries
DMC for Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Automotive Start-Stop Battery Market