
 Ocular Trauma Devices Market | 2026-2036
Ocular Trauma Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Trauma Devices Market Intelligence
ISO 13485 certification is reorganizing competitive access in the Ocular Trauma Devices Market, filtering out contract manufacturers lacking quality management rigor. Alcon Inc leverages vertically integrated ophthalmic manufacturing to sustain supply chain control across suture and shield portfolios. Johnson & Johnson Vision Care Inc anchors its position through R&D intensity in polymer-based ocular protection systems. Carl Zeiss Meditec AG differentiates via precision optical integration into trauma diagnostic workflows.
Ocular trauma devices encompass sterile implements for mechanical protection, wound closure, and pressure modulation following corneal, scleral, or adnexal injury, typically fabricated from medical-grade silicone, nylon, or absorbable polymers and sterilized via gamma irradiation or ethylene oxide processing to meet biocompatibility standards. Surgical repair technology leads the technology dimension due to established reimbursement pathways for laceration and rupture intervention, while injection therapy represents the fastest-expanding segment as intravitreal drug delivery protocols proliferate in emergency settings. Ophthalmology clinics dominate end-user procurement for scheduled trauma follow-up, though ambulatory surgical centers capture margin pools through same-day procedural bundling.
The FDA governs device classification and 510(k) clearance timelines for ocular trauma products entering the United States, while the EU MDR extends conformity assessment burdens through notified body scrutiny of biocompatibility and clinical evidence. ISO 10993 biological evaluation standards further shape material selection and testing protocols for manufacturers targeting dual-territory registration. Stakeholders must monitor evolving notified body capacity constraints in Europe and FDA digital health pre-certification pilots that could reshape software-integrated trauma device pathways.
Market Dynamics
Emergency trauma centers in the United States are consolidating procurement authority into centralized supply chains, compressing vendor access windows and forcing manufacturers to demonstrate ISO 13485 compliance before contract eligibility. This structural concentration is reshaping competitive entry barriers across sterile ocular protection and wound closure portfolios.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited premarket notification reviews for Class II ophthalmic devices are accelerating product clearance timelines for trauma repair kits targeting corneal laceration intervention.
- Ambulatory surgical center expansion:Same-day procedural bundling in United States outpatient facilities is driving volume demand for disposable ocular shields and absorbable suture systems.
- Polymer biocompatibility advances:Medical-grade silicone and absorbable polymer formulations meeting ISO 10993 standards are expanding material options for pressure modulation devices in scleral rupture repair.
Market Restraints
- Gamma irradiation sterilization concentration:Limited contract sterilization capacity in United States Midwest and Northeast regions creates supply bottlenecks for ethylene oxide alternatives.
- EU MDR clinical evidence burdens:Extended notified body scrutiny timelines for biocompatibility documentation are delaying dual-territory registration strategies.
- Intraocular pressure monitoring substitution:Non-invasive tonometry devices are displacing mechanical shield-based pressure modulation in select trauma protocols.
Strategic Opportunities
- Underpenetrated rural trauma networks:United States secondary emergency departments in non-urban counties lack dedicated ocular trauma kits, creating white space for standardized repair system distribution.
- Intravitreal drug delivery convergence:Integration of injection therapy protocols with mechanical protection devices is opening emergency setting applications beyond traditional surgical repair.
- Digital health pre-certification pilots:FDA software-integrated device pathways are enabling diagnostic-therapeutic combination products for trauma workflow optimization.
Industry Challenges
- Notified body capacity scarcity:EU MDR conformity assessment backlogs are extending time-to-market for manufacturers targeting European ophthalmology clinic procurement.
- Polymer formulation IP complexity:Patent thickets around absorbable suture compositions are constraining material sourcing flexibility for mid-scale device producers.
- Legacy sterilization infrastructure reconfiguration:Transition from ethylene oxide to gamma irradiation requires capital-intensive facility upgrades for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Trauma Devices Market |
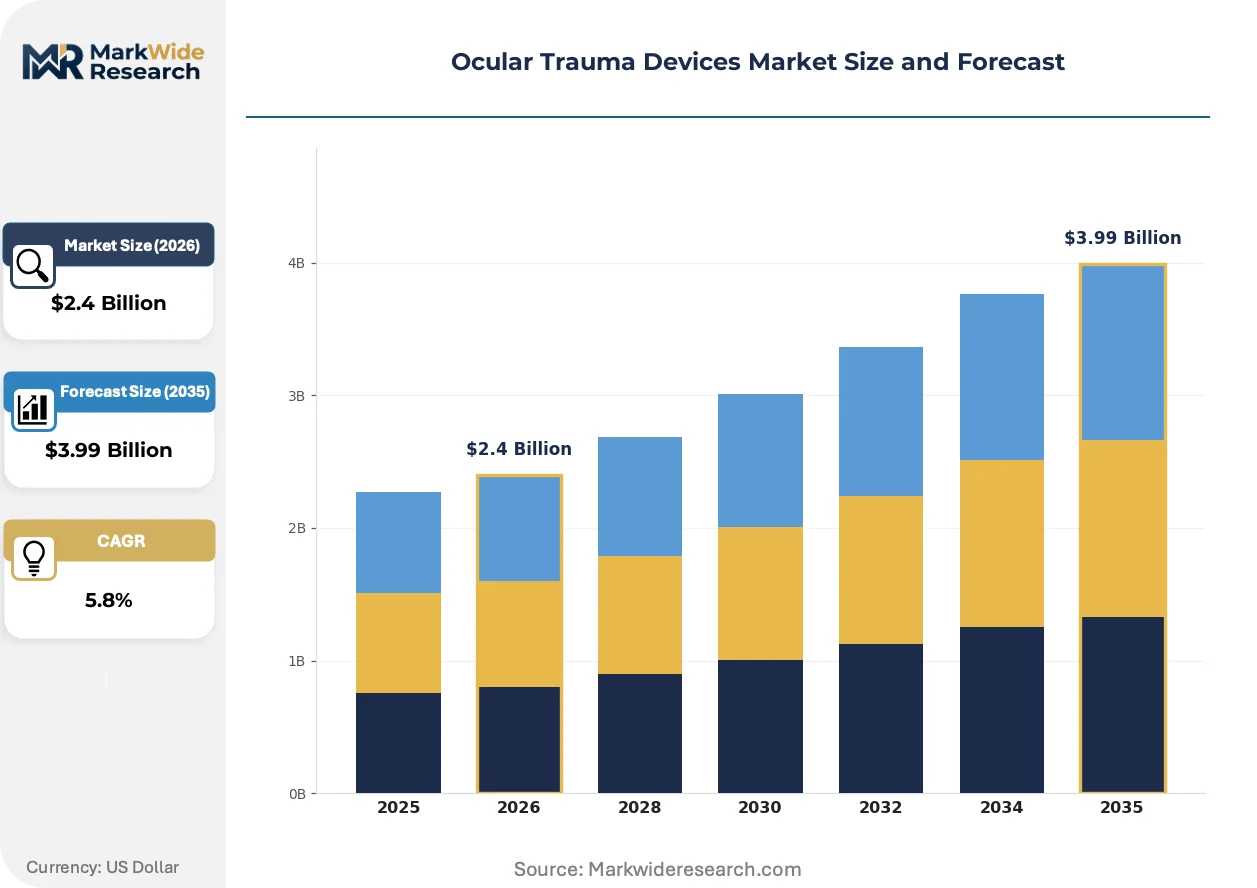
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eye Shields, Bandages, Sutures, Clamps Technology: Laser Therapy, Surgical Repair, Injection Therapy, Cryotherapy End User: Ophthalmology Clinics, Emergency Rooms, Ambulatory Surgical Centers, Home Care Application: Foreign Body Removal, Laceration Repair, Burn Treatment, Intraocular Pressure Management |
| Companies Covered | Johnson & Johnson Vision Care Inc, Glaukos Corporation, Alcon Inc, CooperVision Inc, EssilorLuxottica, Bausch + Lomb Corporation, Topcon Corporation, Haag-Streit Group, Carl Zeiss Meditec AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Trauma Devices Market Strategic Shifts & Innovations
Technology convergence between diagnostic imaging and therapeutic intervention is redefining trauma device specifications, while regulatory frameworks on both sides of the Atlantic are tightening material traceability requirements. These forces are compressing product development cycles and elevating quality management rigor.
Absorbable polymer suture technology is fragmenting traditional nylon-based wound closure dominance in corneal and scleral repair applications. United States trauma centers with dedicated ophthalmology units are adopting these systems at accelerated rates for laceration cases requiring reduced follow-up intervention. The shift is fragmenting procurement categories previously consolidated under monofilament nylon contracts.
EU MDR biocompatibility evaluation standards are extending clinical evidence requirements for ocular trauma devices seeking CE marking. Manufacturers must now submit comprehensive biological evaluation reports under ISO 10993 protocols before notified body assessment. Ophthalmology clinics in Germany and France are prioritizing suppliers with established MDR technical documentation, compressing vendor pools.
Centralized procurement through United States hospital network GPOs is consolidating buying authority for trauma repair kits and shield systems. Independent ambulatory surgical centers are losing direct vendor relationships as supply chain control migrates to integrated delivery networks. This concentration is most visible in California and Texas trauma center clusters where network consolidation has accelerated post-pandemic.
Ocular Trauma Devices Market Segmentation
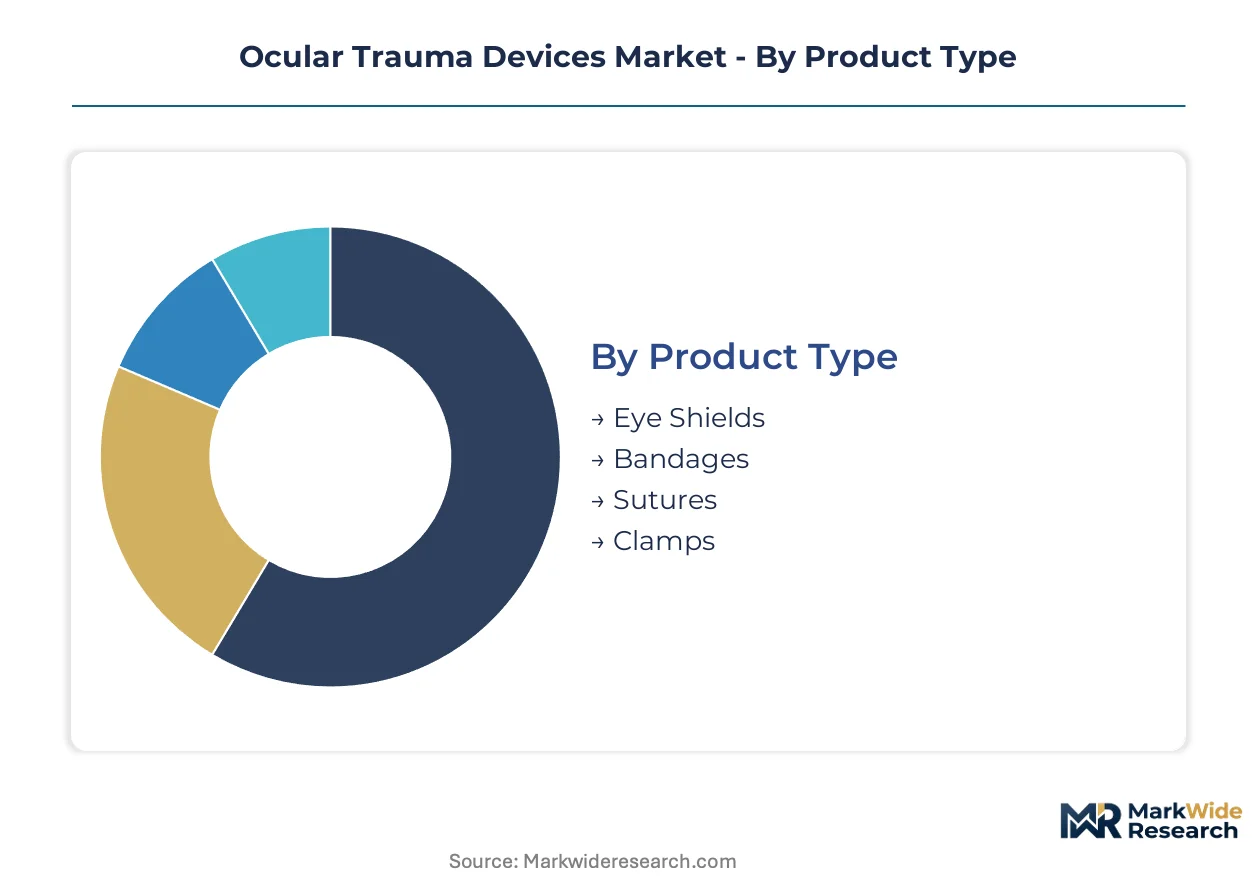
Segmentation in ocular trauma devices reveals distinct procurement patterns across sterile protection, wound closure, and pressure modulation technologies. Trauma centers prioritize disposable shields and absorbable sutures for emergency workflows, while follow-up care drives demand for specialized repair systems in outpatient settings.
Product Type:
Margin pools concentrate in suture systems and sterile shields where FDA 510(k) clearance creates pricing power through regulatory differentiation.
- Sutures:Absorbable polymer and monofilament nylon compositions dominate corneal and scleral laceration repair. United States trauma centers with dedicated ophthalmology units are consolidating procurement under standardized absorbable contracts to reduce follow-up intervention burdens.
- Eye Shields:Medical-grade silicone devices provide mechanical protection and pressure modulation following penetrating injury. Ambulatory surgical centers in California and Texas are driving volume through same-day procedural bundling that includes disposable shield systems.
- Bandages:Hydrogel and collagen-based ocular dressings meet ISO 10993 biocompatibility standards for post-surgical coverage.
- Clamps:Stainless steel and titanium instruments stabilize globe integrity during rupture repair procedures.
Sutures hold installed capacity. Eye Shields is rotating up the share rankings.
Technology:
Volume concentration sits with established surgical modalities, though emergency pharmacological intervention is climbing the fastest.
- Surgical Repair:Microsurgical instrumentation and suturing systems address corneal lacerations, scleral ruptures, and traumatic cataracts. Reimbursement pathways for laceration and rupture intervention anchor procurement in United States hospital networks.
- Injection Therapy:Intravitreal drug delivery protocols deploy anti-VEGF agents and corticosteroids for traumatic macular edema. Emergency departments in urban trauma centers are adopting these systems for same-day intervention beyond traditional surgical repair.
- Laser Therapy:Photocoagulation and photodisruption systems target retinal tears and hemorrhage secondary to blunt trauma.
- Cryotherapy:Trans-scleral freezing applications address retinal detachment prophylaxis in high-risk trauma cases.
Surgical Repair commands the revenue base. Injection Therapy is expanding most quickly in emergency settings.
End User:
Customer type determines contract structure, with integrated delivery networks extracting volume discounts unavailable to independent facilities.
- Ophthalmology Clinics:Scheduled trauma follow-up and elective repair procedures drive procurement of precision suture systems and diagnostic-integrated shields. Germany and France are prioritizing suppliers with established EU MDR technical documentation, compressing vendor pools.
- Emergency Rooms:Acute trauma centers require sterile, ready-to-deploy repair kits for corneal laceration and globe rupture. United States trauma centers in the Midwest and Northeast face sterilization capacity constraints that favor gamma-irradiated disposable systems.
- Ambulatory Surgical Centers:Same-day procedural bundling creates demand for pre-packaged, disposable ocular protection and closure systems.
- Home Care:Post-operative shield maintenance and medication administration support recovery outside institutional settings.
Emergency Rooms anchor volume procurement. Ambulatory Surgical Centers is gaining share fastest through outpatient migration.
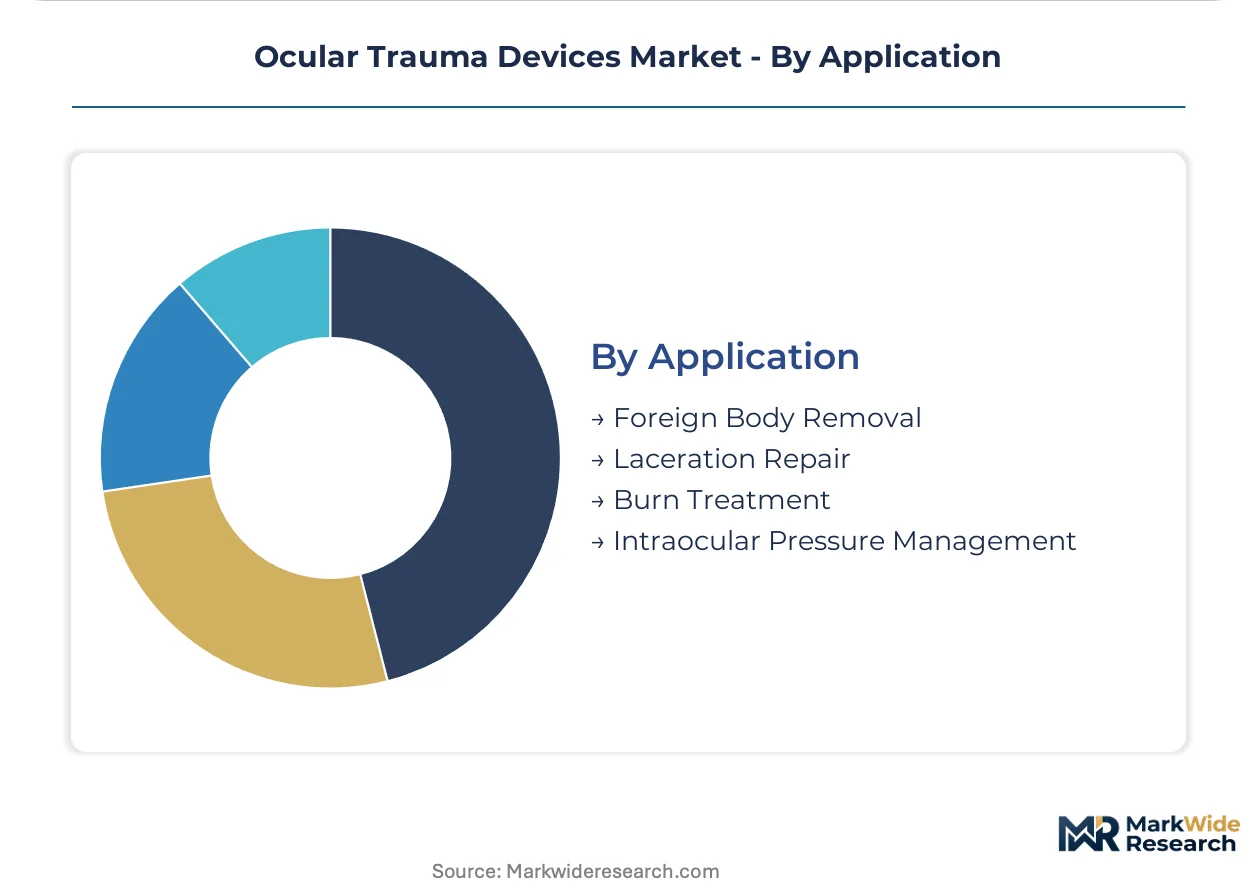
Application:
Clinical indication shapes device specification, with mechanical injury repair commanding premium pricing over medical management.
- Laceration Repair:Corneal and scleral suturing systems address penetrating trauma from sharp objects and projectile impact. United States specialized ocular trauma centers are driving procurement volume for standardized repair kits.
- Foreign Body Removal:Magnetic and non-magnetic extraction instruments paired with protective shields address metallic and organic ocular penetration. Rural emergency departments in non-urban United States counties lack dedicated kits, creating distribution white space.
- Burn Treatment:Amniotic membrane grafts and hydrogel dressings manage chemical and thermal ocular surface injury.
- Intraocular Pressure Management:Mechanical shields and pharmacological agents modulate pressure following traumatic hyphema and angle recession.
Laceration Repair holds the procedural volume base. Foreign Body Removal is climbing the fastest as industrial safety incidents drive emergency demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathway streamlining for Class II ophthalmic devices is accelerating product clearance timelines in the United States, while EU MDR conformity assessment burdens are reshaping vendor access across European markets. Germany and France are prioritizing suppliers with established technical documentation. Japan's PMDA maintains rigorous biocompatibility standards that filter market entry.
United States
Specialized ocular trauma centers in California and Texas drive procurement volume for standardized repair kits. FDA updated premarket notification requirements tighten quality benchmarks for Class II ophthalmic devices. Midwest and Northeast trauma centers face gamma irradiation sterilization capacity constraints that favor disposable shield systems.
Germany
Ophthalmology clinics in Bavaria and Baden-Württemberg prioritize suppliers with established EU MDR technical documentation. EMA oversight extends to biocompatibility evaluation standards under ISO 10993 protocols. The Frankfurt-Rhine-Main medical device cluster concentrates notified body assessment capacity for trauma device registration.
Japan
PMDA maintains stringent biocompatibility standards that extend clinical evidence requirements for ocular trauma devices. METI industrial policy supports precision medical device manufacturing in the Nagoya-Chubu corridor. Tokyo-Kanto trauma centers anchor demand for diagnostic-integrated shield systems in emergency workflows.
United Kingdom
NHS procurement consolidation is compressing vendor access windows for trauma repair kits. MHRA post-Brexit regulatory alignment creates dual documentation burdens for manufacturers. London-Southeast hospital networks are centralizing supply chain authority for sterile ocular protection systems.
India
CDSCO medical device regulations are tightening quality management requirements for imported trauma devices. PLI scheme incentives attract domestic manufacturing investment in ophthalmic sutures and shields. Maharashtra and Gujarat industrial corridors are developing contract sterilization capacity for gamma-irradiated products.
Ocular Trauma Devices Market Key Industry Players
Listed leaders compete with private specialists across regulatory certification dimensions, creating tiered access structures in the Ocular Trauma Devices Market. Vertically integrated ophthalmic manufacturers maintain supply chain control through captive production of silicone and polymer components. Three archetypes dominate: diversified healthcare conglomerates with ophthalmic divisions, pure-play ocular device specialists, and precision optical instrument manufacturers. Competitive moves center on ISO 13485 certification acquisition and notified body relationship cultivation for dual-territory registration.
Among diversified healthcare conglomerates, Johnson & Johnson Vision Care Inc and Alcon Inc exemplify scale-driven positioning through integrated manufacturing footprints. Carl Zeiss Meditec AG represents the precision optical tier, anchoring diagnostic-therapeutic convergence in trauma workflows. These three entities occupy positions across distinct competitive vectors—polymer-based protection systems, suture and shield portfolios, and optical integration—rather than direct segment overlap.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care Inc |
| Glaukos Corporation |
| Alcon Inc |
| CooperVision Inc |
| EssilorLuxottica |
| Bausch + Lomb Corporation |
| Topcon Corporation |
| Haag-Streit Group |
| Carl Zeiss Meditec AG |
| Others |
Cost & Logistics Intelligence
Gamma irradiation sterilization capacity utilization in the United States Midwest and Northeast shapes both supply concentration and price floors for disposable ocular trauma devices. Contract manufacturers with captive sterilization assets command premium positioning through supply security guarantees that smaller competitors cannot match.
Pricing Analysis
Certification level creates the primary spread across the Ocular Trauma Devices Market, with ISO 13485 and FDA 510(k) clearance separating premium tier suppliers from standard contract manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and after-sales service bundling. Cost compression in the standard tier is intensifying because GPOs extract volume discounts from mid-scale producers. Independent ambulatory surgical centers exhibit highest price sensitivity, while specialized ocular trauma centers prioritize supply reliability over unit cost.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for medical-grade silicone and absorbable polymer raw materials sourced from East Asian chemical manufacturers. Supply concentrates in the United States for sterile device finishing, Germany for precision optical components, and Japan for biocompatible polymer formulations. Raw material dependencies include medical-grade silicone, absorbable polyglycolic acid, and gamma-irradiated packaging films. Single-source vulnerability in contract sterilization infrastructure creates supply chain risk. Distribution runs through integrated delivery network GPOs and hospital system central warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement authorities as United States hospital networks centralize supply chain control, fragmenting access for independent vendors.
For Market Incumbents: Compound defensive positioning through backward integration into polymer formulation production and captive gamma irradiation capacity. ISO 13485 certification investments create switching costs against emerging contract manufacturers. Channel control through exclusive GPO contracts locks out substitute technology providers. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for Class II ophthalmic devices offer regulatory entry acceleration. Underpenetrated rural trauma networks in non-urban United States counties represent the most penetrable geography. Direct-to-ASC distribution models bypass consolidated hospital procurement gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision polymer specialists with established biocompatibility documentation. Long-term viability hinges on dual-territory registration capabilities spanning FDA and EU MDR pathways. Acquisition targets should demonstrate notified body relationships and ISO 10993 testing infrastructure. The signal to watch is EU MDR notified body capacity expansion as an inflection indicator for European market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines compress competitive entry windows for trauma repair kits. |
| CE Marking Pathway | EU MDR conformity assessment establishes European ophthalmology clinic procurement eligibility. |
| Hospital System Partnership | Integrated delivery network contracts secure volume commitments through GPO consolidation. |
| Software Companion Development | Diagnostic-therapeutic integration aligns with FDA digital health pre-certification pilots. |
| Reimbursement Strategy | Established coding pathways for laceration and rupture intervention anchor surgical repair demand. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Interviews with trauma center ophthalmologists, biomedical engineers, GPO contracts managers, and sterile processing directors inform demand-side validation. Secondary sources include CMS Medicare reimbursement data, ISO certification registries, and notified body assessment records. Bottom-up product-level modeling triangulates against top-down market sizing.
Segmentation dimensions modeled include product type, technology modality, end-user facility category, and clinical application across the analysis window. CAGRs derive from procedural volume trajectories, reimbursement pathway stability, and material cost curve projections. Forecast inputs incorporate ambulatory surgical center expansion rates and EU MDR implementation timelines.
Underlying assumptions cover sterilization capacity expansion, notified body throughput recovery, and polymer formulation patent expiration schedules, with deviation risk concentrated in regulatory pathway delays and GPO consolidation acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Temperature Sensing Foley Catheter Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Global Tracheostomy Products Market
Medical Devices
Blood Collection Devices Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Artificial Disc Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Ultrasound Biometry Devices Market