
 Temperature Sensing Foley Catheter Market | 2026-2036
Temperature Sensing Foley Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Sensing Foley Catheter Market Analytics
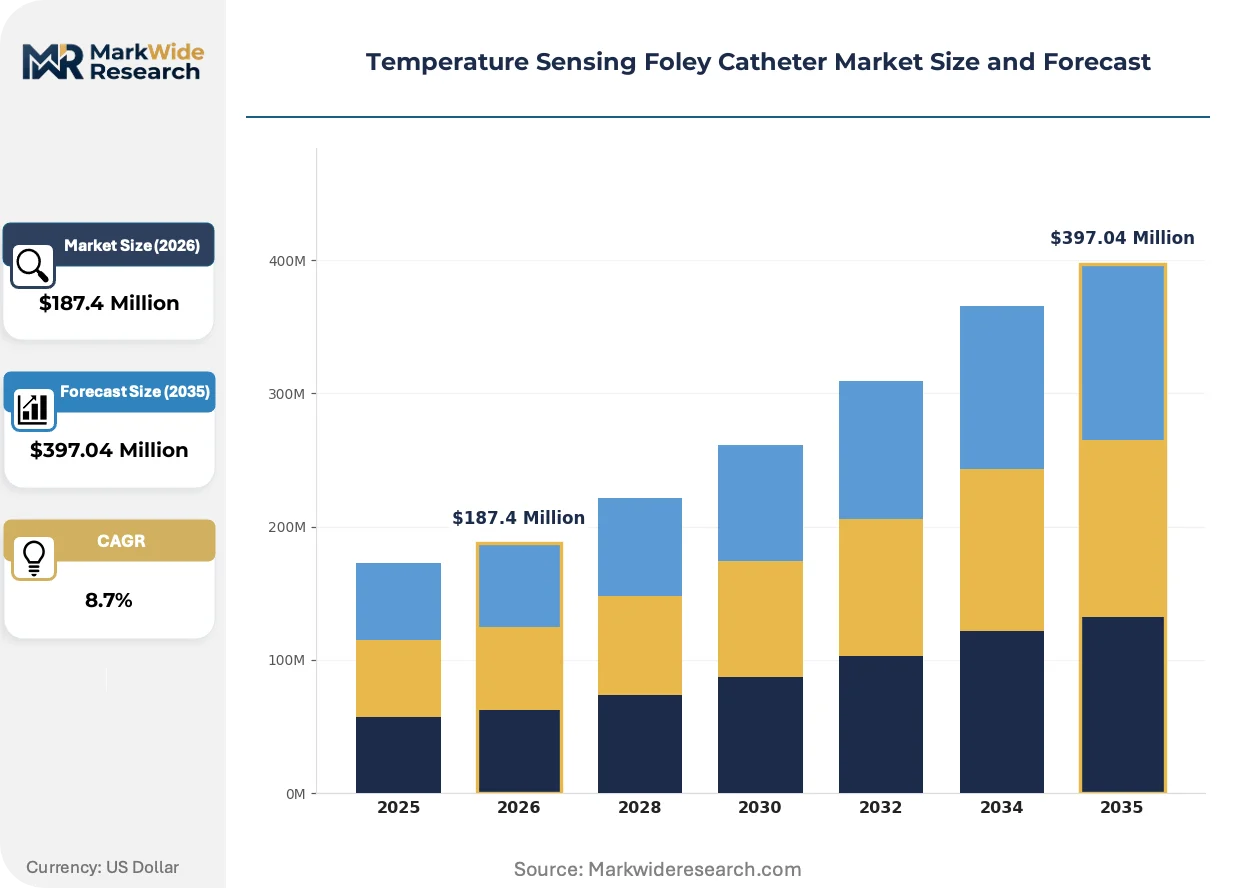
The EU Medical Device Regulation is repositioning temperature-sensing catheter procurement standards across European hospital systems. Medtronic leverages its integrated critical care portfolio to sustain leadership in thermistor-equipped indwelling systems. B. Braun anchors its competitive stance through specialized manufacturing scale in fiber optic sensor assemblies. Teleflex Incorporated differentiates via concentrated R&D intensity in wireless-enabled urology applications.
A temperature sensing Foley catheter incorporates a thermistor, thermocouple, or fiber optic temperature probe within a latex or silicone drainage tube, typically measuring 14-18 French in diameter, designed for continuous core body temperature monitoring during urinary drainage. The device serves primarily in critical care and postsurgical settings where bladder temperature approximates core temperature more accurately than axillary or oral methods. Indwelling catheters with integrated thermistor sensors occupy the dominant revenue position due to established reimbursement pathways and clinician familiarity, while wireless sensor variants represent the fastest-expanding technology segment as hospitals prioritize telemetry-integrated ICU workflows. Fiber optic sensors command premium positioning in pediatric and burn-unit applications where electromagnetic interference immunity proves clinically essential.
The FDA enforces biocompatibility and electrical safety standards under 21 CFR Part 820 quality system regulations, while the EU MDR mandates clinical evidence and post-market surveillance for temperature-monitoring urological devices. ISO 10993 biological evaluation protocols and IEC 60601-1 electrical safety standards govern material selection and sensor performance validation across both jurisdictions. Stakeholders must monitor evolving cybersecurity requirements for wireless-enabled catheters and anticipate reimbursement recalibration as remote patient monitoring codes expand beyond traditional inpatient settings.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around temperature-sensing catheter platforms that integrate with existing telemetry infrastructure, compressing the competitive field toward full-stack critical care suppliers.
Growth Catalysts
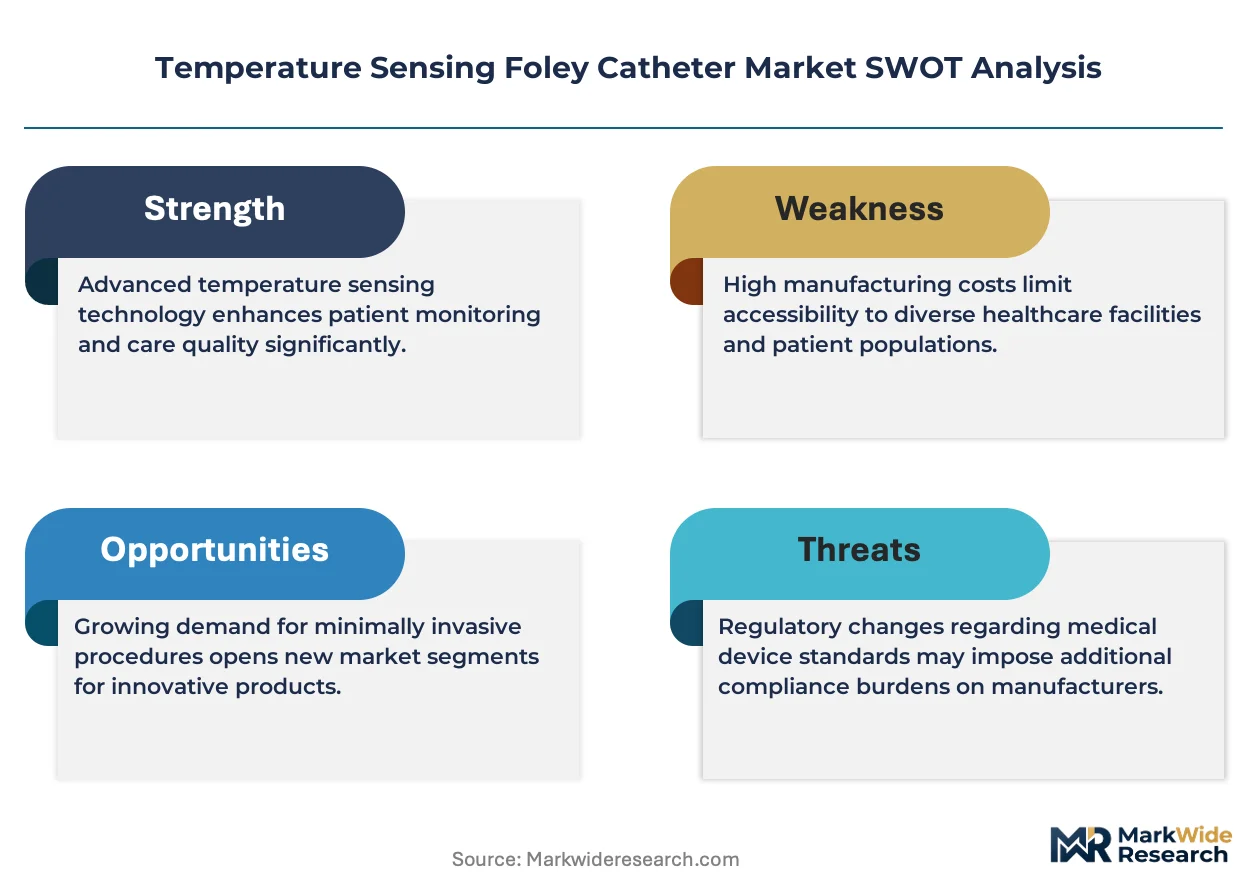
- EU MDR compliance deadlines:European hospital systems are accelerating replacement cycles for legacy temperature-monitoring devices ahead of full regulatory enforcement, creating concentrated demand pull across Germany, France, and Italy.
- ICU capacity expansion:Post-pandemic infrastructure investment in the United States and Japan is driving installed base growth for continuous core temperature monitoring systems in surgical recovery units.
- Fiber optic sensor miniaturization:Advances in biocompatible fiber optic probe manufacturing are reducing unit costs and expanding addressable applications into pediatric and burn care settings.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains concentrate among a limited set of European and Asian chemical suppliers, exposing manufacturers to input cost volatility and allocation constraints.
- Wireless cybersecurity validation:FDA's evolving medical device cybersecurity guidance imposes extended premarket review timelines for Bluetooth-enabled catheter systems, delaying revenue recognition.
- Axillary probe substitution:Non-invasive skin-surface temperature monitoring technologies continue improving accuracy, threatening indwelling catheter utilization in lower-acuity postsurgical wards.
Strategic Opportunities
- Remote patient monitoring reimbursement expansion:CMS and private payors in the United States are establishing new billing codes for continuous temperature telemetry outside traditional inpatient settings, opening ambulatory surgical center demand.
- AI-integrated predictive analytics:Convergence of continuous temperature data streams with machine learning sepsis detection algorithms is creating premium platform opportunities for integrated critical care vendors.
- Direct-to-hospital distribution:Bypassing traditional medical device distributors through specialized critical care sales forces is compressing channel margins and improving vendor data access to utilization patterns.
Industry Challenges
- Biomedical engineering talent scarcity:Shortage of specialists combining urological device design with RF engineering expertise is constraining wireless product development velocity.
- ISO 10993-18 chemical characterization:Updated biological evaluation protocols require extensive extractables and leachables testing, extending certification timelines and inflating regulatory compliance costs.
- Legacy EMR integration complexity:Hospital information system fragmentation forces catheter vendors to maintain multiple HL7 interface configurations, diluting R&D resources across interoperability maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Sensing Foley Catheter Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermittent Catheter, Indwelling Catheter, External Catheter, Specialty Catheter Technology: Wireless Sensors, Fiber Optic Sensors, Thermistor Sensors, Thermocouple Sensors End User: Hospitals, Long-term Care Facilities, Home Healthcare, Urgent Care Centers Application: Urology, Critical Care, Postsurgical Monitoring, Pediatric Care |
| Companies Covered | Medtronic, Teleflex Incorporated, Medline Industries, C.R. Bard, B. Braun, Coloplast, Cardinal Health, Becton, Dickinson and Company, Biomerics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Sensing Foley Catheter Market Evolving Landscape
Wireless telemetry integration is compressing the gap between standalone temperature monitoring and comprehensive critical care data platforms, forcing catheter manufacturers to compete on system architecture rather than sensor accuracy alone.
Silicone-encapsulated thermistor assemblies with embedded microcontrollers are unifying temperature sensing and digital signal processing within the catheter wall itself. Academic medical centers in the United States and university hospitals in Germany are piloting these systems at accelerating rates. This unification is enabling real-time drift compensation and predictive failure alerts that reduce unplanned catheter replacement events.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up data collection for Class IIa temperature-monitoring devices. Manufacturers must now maintain active registries tracking device performance across implantation duration. Pediatric and burn unit applications face the steepest compliance burden due to smaller patient populations and extended monitoring protocols.
Hospital value analysis committees are consolidating purchasing authority previously distributed across urology, critical care, and infection control departments. Integrated delivery networks in the United States are replacing fragmented specialty purchasing with centralized capital equipment decisions that favor multi-parameter monitoring contracts. This concentration is most visible in the Southeast and Midwest regions where health system consolidation has advanced furthest.
Temperature Sensing Foley Catheter Market Segmentation
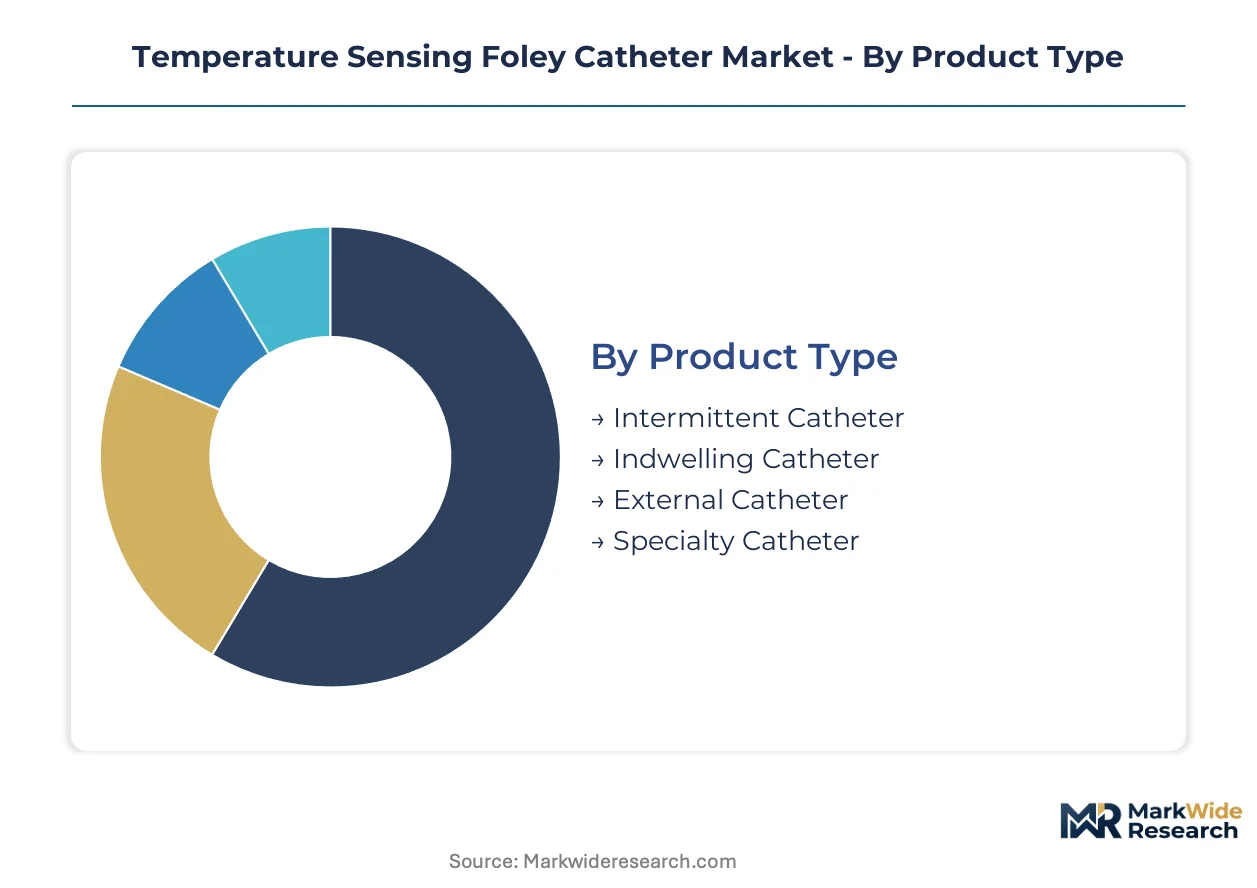
Temperature sensing Foley catheters segment across four distinct dimensions that shape procurement patterns and technology investment priorities. Product type determines reimbursement pathways and clinical workflow integration. Technology choice governs electromagnetic compatibility requirements and manufacturing complexity. End user setting dictates regulatory scrutiny intensity and device durability specifications. Application area influences sensor accuracy demands and patient population safety protocols.
Product Type:
Volume concentration sits with indwelling systems while specialty configurations capture premium pricing through narrow clinical indications.
- Indwelling Catheter:Latex or silicone drainage tubes with integrated thermistor, thermocouple, or fiber optic probes designed for continuous bladder temperature monitoring over extended dwell periods. Hospital procurement departments in the United States and Germany concentrate purchases here for ICU and postsurgical recovery units where reimbursement pathways are established and clinician training is standardized.
- Specialty Catheter:Custom-configured devices incorporating pediatric sizing, burn unit electromagnetic immunity, or neurocritical care specifications. Demand clusters in academic medical centers across Japan and university hospitals in France where specialized patient populations justify premium procurement budgets and extended device validation protocols.
- Intermittent Catheter:Single-use temperature-monitoring devices for short-duration catheterization with disposable sensor assemblies.
- External Catheter:Non-indwelling sheath systems with surface-mounted temperature sensors for ambulatory or postsurgical monitoring.
Today's leader: Indwelling Catheter. Tomorrow's challenger: Specialty Catheter.
Technology:
Established thermistor platforms dominate installed base while wireless architectures reshape competitive differentiation around telemetry integration.
- Thermistor Sensors:Temperature-sensitive semiconductor devices embedded within catheter walls providing continuous resistance-based thermal measurement with established calibration protocols. Critical care departments across the United States and Germany standardize on these systems due to decades of clinical validation, straightforward electrical safety compliance, and direct compatibility with existing patient monitoring infrastructure.
- Wireless Sensors:Bluetooth or proprietary RF-enabled temperature probes transmitting data to centralized telemetry systems without tethered connections. Japanese university hospitals and United States ambulatory surgical centers are expanding pilot programs here as CMS establishes remote patient monitoring reimbursement codes and FDA cybersecurity guidance stabilizes premarket review timelines.
- Fiber Optic Sensors:Biocompatible glass fiber probes immune to electromagnetic interference for pediatric, burn unit, and MRI-compatible applications.
- Thermocouple Sensors:Junction-based temperature measurement devices utilizing dissimilar metal pairs for rapid thermal response in acute monitoring scenarios.
Established infrastructure favors Thermistor Sensors. Steepest expansion trajectory belongs to Wireless Sensors.
End User:
Acute care settings concentrate device utilization while home healthcare represents the frontier for reimbursement expansion and technical simplification.
- Hospitals:Primary deployment environment encompassing surgical recovery units, intensive care departments, and emergency services where continuous core temperature monitoring guides sepsis protocols and hypothermia management. United States health systems and German hospital networks drive procurement volume through centralized value analysis committees that favor multi-parameter monitoring contracts with integrated critical care vendors.
- Home Healthcare:Discharged patient monitoring through simplified catheter systems with wireless telemetry connectivity and caregiver-friendly interfaces. United States Medicare Advantage plans and Japanese long-term care insurance programs are testing coverage expansion here as remote patient monitoring codes mature beyond traditional inpatient settings.
- Long-term Care Facilities:Skilled nursing environments with reduced acuity monitoring requirements and extended dwell time protocols.
- Urgent Care Centers:Rapid assessment settings requiring immediate temperature verification without full critical care infrastructure.
Procurement authority concentrates at Hospitals. Regulatory innovation targets Home Healthcare.
Application:
Critical care commands the highest sensor accuracy specifications while pediatric applications impose the steepest biocompatibility and miniaturization requirements.
- Critical Care:Continuous bladder temperature monitoring in ICU settings where core temperature approximation guides therapeutic hypothermia, fever management, and sepsis detection protocols. German university hospitals and United States academic medical centers anchor demand here through integration with electronic health record systems and machine learning-based predictive analytics platforms.
- Pediatric Care:Size-adapted catheter systems with fiber optic or miniaturized thermistor sensors for neonatal and pediatric populations where electromagnetic immunity and reduced thermal mass prove clinically essential. French pediatric hospitals and Japanese children's medical centers concentrate specialized procurement despite smaller patient volumes and extended regulatory validation timelines.
- Urology:Standard postsurgical monitoring following transurethral procedures and urinary obstruction management.
- Postsurgical Monitoring:Recovery unit temperature surveillance following major abdominal, cardiac, or neurological interventions.
Revenue concentration rests with Critical Care. Technical complexity peaks at Pediatric Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The temperature sensing Foley catheter industry traces its commercial origins to post-war American medical device manufacturing, with subsequent scaling across German precision engineering clusters and Japanese electronics integration corridors. Hospital procurement consolidation and regulatory harmonization have since redistributed competitive gravity toward integrated critical care suppliers with multi-market certification capabilities.
United States
Academic medical centers in Boston and the Research Triangle anchor demand for wireless-enabled telemetry systems as CMS expands remote patient monitoring reimbursement codes. FDA cybersecurity guidance under 21 CFR Part 820 imposes extended premarket review timelines for Bluetooth-integrated devices. The Southeast and Midwest concentrate health system consolidation activity, with integrated delivery networks replacing fragmented specialty purchasing through centralized value analysis committees.
Germany
University hospitals in Bavaria and North Rhine-Westphalia drive procurement volume for fiber optic sensor systems in pediatric and burn unit applications. EU MDR compliance deadlines accelerate replacement cycles for legacy temperature-monitoring devices ahead of full regulatory enforcement. The Baden-Württemberg medical technology cluster sustains specialized manufacturing scale in biocompatible fiber optic probe assemblies.
Japan
Long-term care insurance programs and Medicare-equivalent coverage expansion test ambulatory surgical center demand for simplified wireless telemetry systems. METI standards harmonization with IEC 60601-1 electrical safety protocols governs sensor performance validation. Tokyo and Osaka metropolitan hospital networks pilot AI-integrated predictive analytics platforms combining continuous temperature data with machine learning sepsis detection algorithms.
France
Pediatric hospitals in Paris and Lyon concentrate specialized procurement for miniaturized sensor systems despite smaller patient volumes and extended regulatory validation timelines. ANSM post-market surveillance requirements mandate systematic clinical follow-up data collection for Class IIa temperature-monitoring devices. The Île-de-France region anchors demand for electromagnetic immunity specifications in neurocritical care settings.
United Kingdom
NHS procurement frameworks consolidate purchasing authority previously distributed across urology, critical care, and infection control departments. MHRA alignment with EU MDR transition timelines reshapes product certification requirements for temperature-monitoring urological devices. The Greater Manchester and West Midlands health innovation clusters pilot direct-to-hospital distribution models bypassing traditional medical device distributors.
Temperature Sensing Foley Catheter Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification depth and telemetry integration capabilities. The field compresses toward full-stack critical care suppliers capable of unified temperature sensing and digital signal processing within catheter wall architectures. Three archetypes dominate: diversified medical technology conglomerates with integrated critical care portfolios, specialized urological device manufacturers with fiber optic sensor expertise, and contract manufacturers supplying private-label telemetry components. Consolidation concentrates through multi-parameter monitoring contract awards and strategic partnerships for HL7 interface standardization.
Within the diversified conglomerate tier, Medtronic and B. Braun occupy positions exemplifying integrated critical care platform strategies, while Teleflex Incorporated represents the specialized telemetry integration archetype. Medtronic leverages scale across thermistor-equipped indwelling systems and established reimbursement pathways. B. Braun anchors manufacturing concentration in European precision engineering corridors. Teleflex concentrates R&D intensity in wireless-enabled urology applications, reflecting divergent competitive vectors between sensor miniaturization and system architecture unification.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex Incorporated |
| Medline Industries |
| C.R. Bard |
| B. Braun |
| Coloplast |
| Cardinal Health |
| Becton, Dickinson and Company |
| Biomerics |
| Others |
Value Network & Pricing Analysis
Hospital value analysis committees in the United States and Germany concentrate procurement authority for temperature sensing Foley catheters, compressing vendor margins through multi-parameter monitoring contracts that bundle sensors with telemetry infrastructure. This buyer consolidation enforces contract-based long-term offtake pricing with volume-scaled discounts, while specialty catheter configurations retain premium positioning through pediatric and burn-unit electromagnetic immunity specifications.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs temperature sensing Foley catheter transactions, with premium tiers anchored by fiber optic sensor systems for MRI-compatible applications and economy tiers serving high-volume ICU contracts. Price differentiation rests on FDA cybersecurity certification tier and wireless telemetry integration depth, with Bluetooth-enabled systems commanding 15-30% premiums over thermistor-only platforms. Cost compression in standard-tier thermistor catheters is intensifying because silicone raw material allocation constraints force manufacturers to absorb input volatility. Ambulatory surgical centers exhibit the highest price sensitivity due to nascent remote patient monitoring reimbursement, while academic medical centers in Japan and Germany demonstrate lowest sensitivity given integrated critical care platform budgets.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade silicone feedstock concentrated among German and Japanese chemical suppliers, exposing catheter manufacturers to allocation rationing during polymer production disruptions. Manufacturing draws from precision thermistor fabrication in the United States, fiber optic probe assembly in Germany's Baden-Württemberg cluster, and microcontroller encapsulation in Japanese electronics corridors. Tariff exposure runs through cross-border component flows between these three supply nodes, particularly for wireless RF modules subject to FCC and METI dual certification requirements. Distribution runs through specialized critical care sales forces bypassing traditional medical device distributors, with direct-to-hospital contracts capturing utilization pattern data for vendor forecasting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Temperature sensing Foley catheter demand compounds steadily as post-pandemic ICU capacity expansion across the United States and Japan sustains installed base growth for continuous core temperature monitoring systems.
For Market Incumbents: Deploy backward integration into medical-grade silicone compounding to defend against raw material allocation constraints and input cost volatility. Consolidate telemetry integration capabilities through specialized RF engineering talent acquisition, countering emerging wireless-enabled entrants from consumer electronics crossover. Channel control through direct-to-hospital sales force expansion protects margin structure against distributor disintermediation. For New Entrants and Emerging Players: Ambulatory surgical centers in the United States represent the most penetrable white-space target as CMS reimbursement codes for remote patient monitoring mature beyond traditional inpatient settings. Pediatric fiber optic applications in French and Japanese university hospitals offer second-entry positioning through electromagnetic immunity specialization. A go-to-market angle anchored on AI-integrated predictive analytics partnerships with sepsis detection platforms differentiates against established thermistor-only vendors. For Investors and Strategic Acquirers: Diversified medical technology conglomerates with integrated critical care portfolios are the most active acquirer in this space, seeking telemetry integration capabilities to complete platform unification. Long-term viability frames as a 5-10 year compounder sustained by aging demographics and ICU infrastructure investment cycles. Acquisition target archetype: specialized urological device manufacturers with fiber optic sensor expertise and EU MDR certification completion. The signal to watch is FDA cybersecurity guidance stabilization for Bluetooth-enabled systems, which would unlock ambulatory reimbursement expansion and accelerate wireless sensor revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Submission | Premarket review timelines for Bluetooth-enabled catheters compress as FDA guidance stabilizes post-2024 updates. |
| CE Marking Pathway | EU MDR clinical evidence requirements for Class IIa devices mandate systematic post-market surveillance registries. |
| Hospital System Partnership | Integrated delivery networks in the United States Southeast consolidate purchasing through centralized value analysis committees. |
| Software Companion Development | Machine learning sepsis detection algorithms from Tokyo and Osaka academic centers create premium platform bundling opportunities. |
| Reimbursement Strategy | CMS remote patient monitoring code expansion unlocks ambulatory surgical center demand beyond traditional inpatient settings. |
Research Methodology
Multiple input streams — structured interviews with biomedical engineers and hospital procurement managers, GPO contract database analysis, and FDA 510(k) filing review — were reconciled against secondary validation from CMS reimbursement code updates and EU MDR guidance documents. Primary fieldwork engaged critical care clinicians, infection control specialists, and telemetry integration specialists across academic medical centers in Boston, Bavaria, and Tokyo. Secondary sources encompassed hospital procurement databases, ISO 10993 biological evaluation protocols, and IEC 60601-1 electrical safety standards. Bottom-up unit economics triangulated against top-down market sizing from health system capital expenditure disclosures.
Historical shipment data cross-referenced against panel input from catheter manufacturing executives and silicone supplier planning officers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, sensor technology, end-user setting, and application area, with regional regulatory cluster differentiation for FDA, EU MDR, and METI compliance pathways. CAGRs derived from installed base growth rates, replacement cycle acceleration, and reimbursement expansion trajectories. Industry-specific forecast inputs included ICU capacity expansion pipelines and remote patient monitoring code adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA cybersecurity guidance evolution, silicone supply chain disruption frequency, and wireless telemetry standardization pace. Forecasts reflect documented assumptions regarding reimbursement expansion timing and health system consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Reusable Laparoscopic Instrument Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Soft Tissue Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Bone-Cutting Technologies Market