
 Non-Invasive Biosensors Market | 2026-2036
Non-Invasive Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Biosensors Market Outlook
MDR Article 117 is recalibrating the cost-of-entry calculus for European market access by requiring notified body involvement for devices with measuring functions. Abbott Laboratories leverages its vertically integrated manufacturing footprint to sustain compliance velocity across multiple regulatory jurisdictions. Nemaura Medical specializes in wearable glucose monitoring platforms, while Philips Healthcare anchors its position through hospital-grade monitoring systems with established distribution networks.
Non-invasive biosensors detect physiological markers through external interfaces without breaking skin integrity, typically employing optical spectroscopy, impedance analysis, or thermal gradient measurement with sensitivity thresholds reaching micromolar concentrations. These instruments serve continuous health surveillance in ambulatory and home settings where patient adherence limits invasive alternatives. Wearable devices capture the dominant volume share due to consumer familiarity with wrist-worn form factors, while point-of-care devices retain premium margin pools in clinical environments requiring immediate diagnostic readouts. Optical sensors lead technology adoption in glucose monitoring applications, whereas electrophysiological sensors dominate cardiac rhythm surveillance.
FDA breakthrough device designations compress review timelines for novel biosensor modalities, while EMA's MDR enforcement raises documentation burdens for CE-marked products. Japan's PMDA operates a parallel track for software-as-a-medical-device classifications that encompasses AI-enhanced biosensor analytics. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payer decisions will determine addressable market expansion beyond early-adopter cohorts.
Market Dynamics
MDR Article 117 enforcement is restructuring European market access economics by mandating notified body oversight for measuring-function devices, forcing manufacturers to absorb elevated compliance costs or exit the region entirely.
Growth Catalysts
- FDA Breakthrough Device Pathway:Accelerated review timelines for novel glucose monitoring modalities compress commercialization cycles for optical spectroscopy platforms seeking US market entry.
- Chronic Disease Management Expansion:Hospital systems in the United States, Germany, and Japan are scaling procurement of continuous glucose monitors to reduce readmission penalties and extend care beyond facility walls.
- Optical Spectroscopy Maturation:Sensitivity thresholds reaching micromolar concentrations enable reliable glucose detection without skin penetration, resolving the adherence barriers that limit invasive alternatives.
Market Restraints
- MDR Documentation Burden:CE marking pathways under the European Medical Device Regulation impose substantially higher clinical evidence requirements than the preceding MDD framework, extending timelines and inflating regulatory spend.
- Component Supply Concentration:Specialized photodetectors and narrow-bandwidth light sources concentrate among a limited supplier base in East Asia, creating vulnerability to geographic disruption.
- Clinical Validation Requirements:Demonstrating equivalence to invasive reference standards demands large-scale prospective trials that consume capital without guaranteeing reimbursement approval.
Strategic Opportunities
- Remote Therapeutic Monitoring Codes:Evolving reimbursement frameworks in the United States for continuous physiologic surveillance create addressable market expansion beyond early-adopter cohorts into standard-of-care protocols.
- AI-Enhanced Analytics Convergence:Integration of machine learning algorithms with raw biosensor outputs enables predictive health alerts that differentiate premium offerings from commodity hardware.
- Home Care Channel Penetration:Direct-to-consumer distribution models bypass traditional hospital procurement gatekeepers, capturing margin pools previously allocated to group purchasing organizations.
Industry Challenges
- Multidisciplinary Talent Scarcity:Development teams require simultaneous expertise in optical engineering, signal processing, and clinical regulatory affairs, a combination rarely found in single labor markets.
- Legacy System Integration Friction:Hospital electronic health record architectures lack standardized APIs for continuous biosensor data streams, forcing costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Biosensors Market |
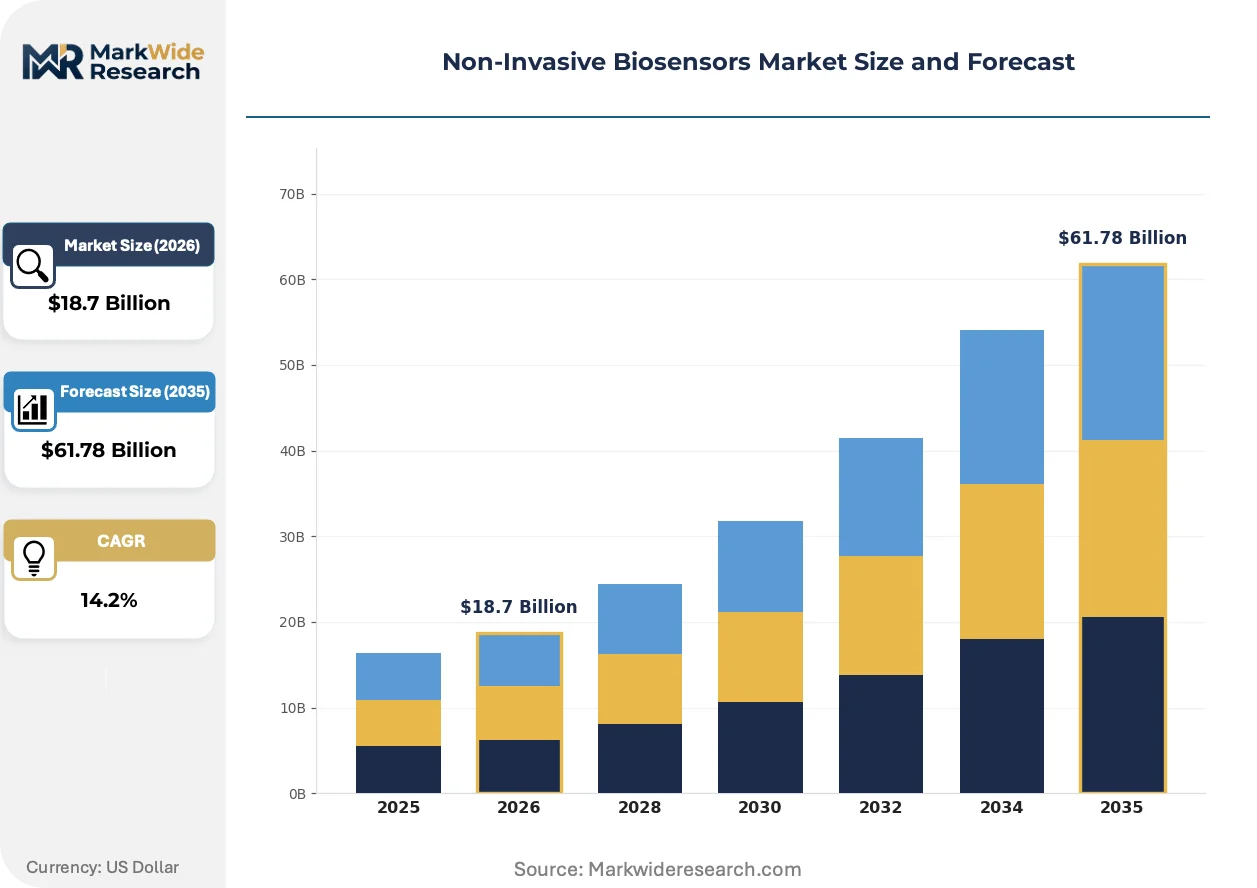
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Sensors, Point-of-Care Devices, Monitoring Systems Technology: Optical Sensors, Electrophysiological Sensors, Chemical Sensors, Thermal Sensors Application: Glucose Monitoring, Sleep Tracking, Heart Rate Monitoring, Fitness Tracking End User: Healthcare Professionals, Athletes, Patients, Researchers |
| Companies Covered | GE Healthcare, Integrity Applications Inc., Abbott Laboratories, MediWise Ltd., OrSense, Medtronic Plc, Nemaura Medical, Inc., Akers Biosciences, Inc., Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Biosensors Market Strategic Shifts
Optical glucose sensing architectures are displacing electrochemical alternatives as the dominant technology platform, while regulatory frameworks simultaneously accelerate in the United States and tighten in Europe.
Raman spectroscopy is rewriting performance expectations for non-invasive glucose quantification by enabling molecular fingerprinting through skin without exogenous contrast agents. Academic medical centers in the United States and Japan are piloting wrist-worn prototypes in type 1 diabetes cohorts. This modality is compressing the accuracy gap between invasive and non-invasive methods from percentage points to single-digit milligrams per deciliter.
Japan's PMDA parallel track for software-as-a-medical-device classifications encompasses AI-enhanced biosensor analytics, creating a regulatory precedent that other jurisdictions are observing. Manufacturers are restructuring quality management systems to accommodate algorithm update protocols as design changes rather than new device submissions. Cardiac rhythm surveillance applications are most affected, where real-time arrhythmia detection models require continuous retraining.
Hospital procurement committees are unbundling device hardware from data analytics subscriptions, treating continuous monitoring as a service rather than capital equipment. This shift displaces traditional durable medical equipment distributors with platform vendors offering per-patient-per-month pricing. The transformation is most visible in German hospital networks, where procurement centralization favors integrated remote patient monitoring contracts over point solutions.
Non-Invasive Biosensors Market Segmentation
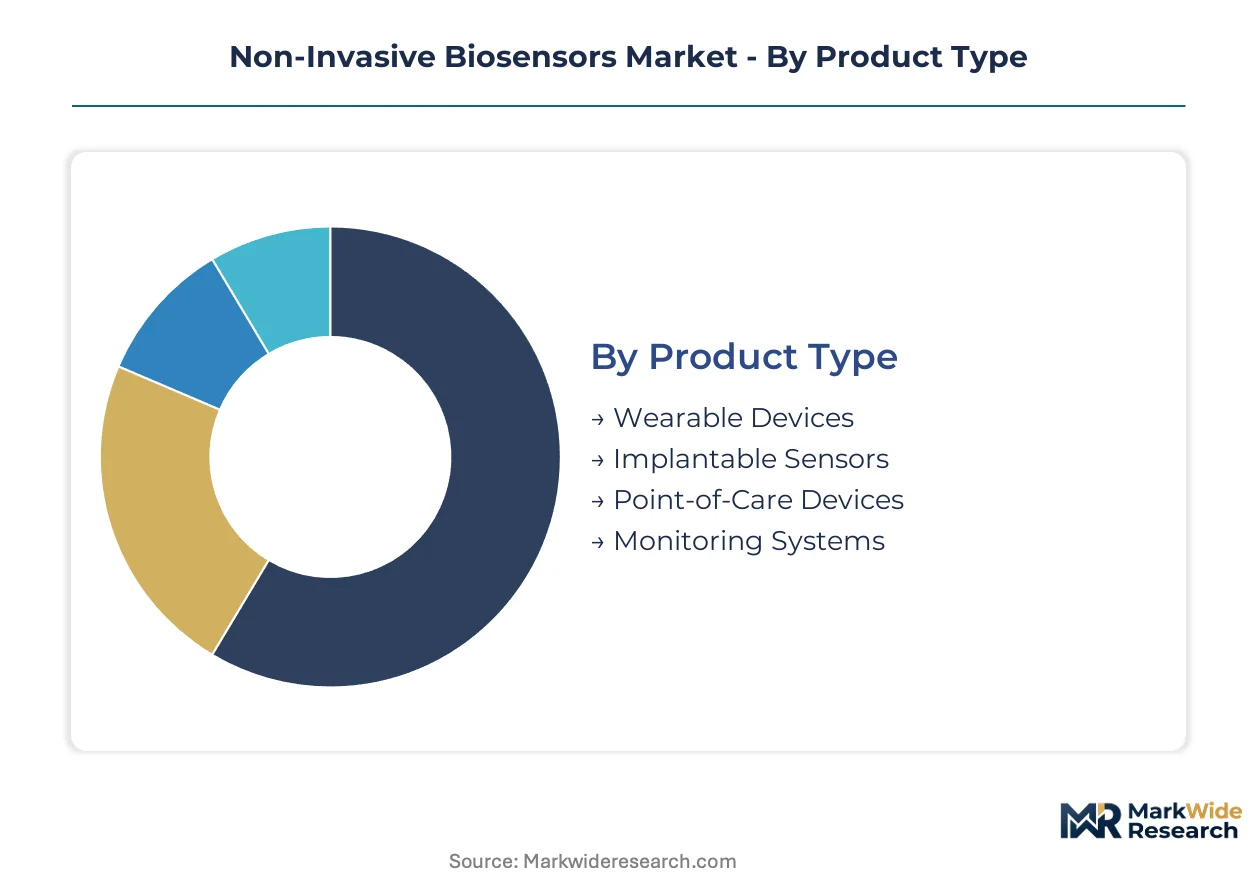
Non-invasive biosensor architectures diverge sharply across use contexts, with form factor and sensing modality determining reimbursement pathways and regulatory burden. Manufacturers configure product lines to match distinct compliance velocities and margin structures across consumer wellness and clinical diagnostic segments.
Product Type:
Supply concentration in specialized photonics and flexible electronics favors vertically integrated manufacturers who control component sourcing for high-volume wearable platforms.
- Wearable Devices:Wrist-worn and patch-based form factors integrate optical spectroscopy and accelerometry for continuous ambulatory monitoring. Hospital systems in the United States and Germany are expanding procurement for remote patient monitoring programs that reduce readmission penalties.
- Point-of-Care Devices:Handheld diagnostic instruments deliver immediate physiological readouts in clinical settings without laboratory infrastructure. These platforms command premium pricing in emergency departments and urgent care facilities where rapid glucose and cardiac marker assessment guides treatment decisions.
- Implantable Sensors:Subcutaneous platforms with wireless telemetry enable long-term metabolic surveillance for intensive diabetes management.
- Monitoring Systems:Hospital-grade centralized platforms aggregate multiple patient data streams for intensive care and step-down unit surveillance.
Today's leader: Wearable Devices. Tomorrow's challenger: Point-of-Care Devices.
Technology:
Cost tier differentiation separates optical platforms targeting consumer wellness from electrophysiological systems certified for clinical arrhythmia detection.
- Optical Sensors:Photoplethysmography and near-infrared spectroscopy dominate glucose and pulse oximetry applications through non-penetrating light-tissue interaction. Sensitivity thresholds reaching micromolar concentrations enable reliable metabolic monitoring without skin integrity compromise.
- Electrophysiological Sensors:Surface electrode arrays capture cardiac electrical activity for rhythm classification and stress testing. FDA breakthrough device designations have accelerated review timelines for novel form factors in this category.
- Chemical Sensors:Sweat and interstitial fluid analysis through ion-selective electrodes provides electrolyte and metabolite quantification.
- Thermal Sensors:Thermopile and thermistor arrays measure skin temperature gradients as proxies for metabolic rate and peripheral perfusion.
Optical Sensors anchor current volume. Electrophysiological Sensors are gaining share fastest through cardiac monitoring reimbursement expansion.
Application:
Volume concentration in glucose management reflects reimbursement code maturity, while sleep and fitness tracking rely on direct-to-consumer purchase decisions.
- Glucose Monitoring:Continuous metabolic surveillance for diabetes management represents the most clinically validated application with established CPT codes for remote therapeutic monitoring. Optical spectroscopy platforms are displacing invasive fingerstick methods as accuracy gaps narrow to single-digit milligrams per deciliter.
- Heart Rate Monitoring:Photoplethysmography-based pulse detection serves both consumer fitness and clinical arrhythmia screening with algorithm-enhanced anomaly flagging.
- Sleep Tracking:Polysomnography proxy metrics including oxygen saturation, movement, and heart rate variability support wellness and clinical sleep disorder screening.
- Fitness Tracking:General physiological surveillance for athletic performance optimization lacks clinical reimbursement but commands substantial consumer expenditure.
Glucose Monitoring drives clinical revenue. Sleep Tracking shows steepest expansion trajectory through employer wellness program adoption.
End User:
Customer type determines pricing architecture, with healthcare professional procurement subject to group purchasing organization negotiation while patient direct purchase bypasses institutional gatekeepers.
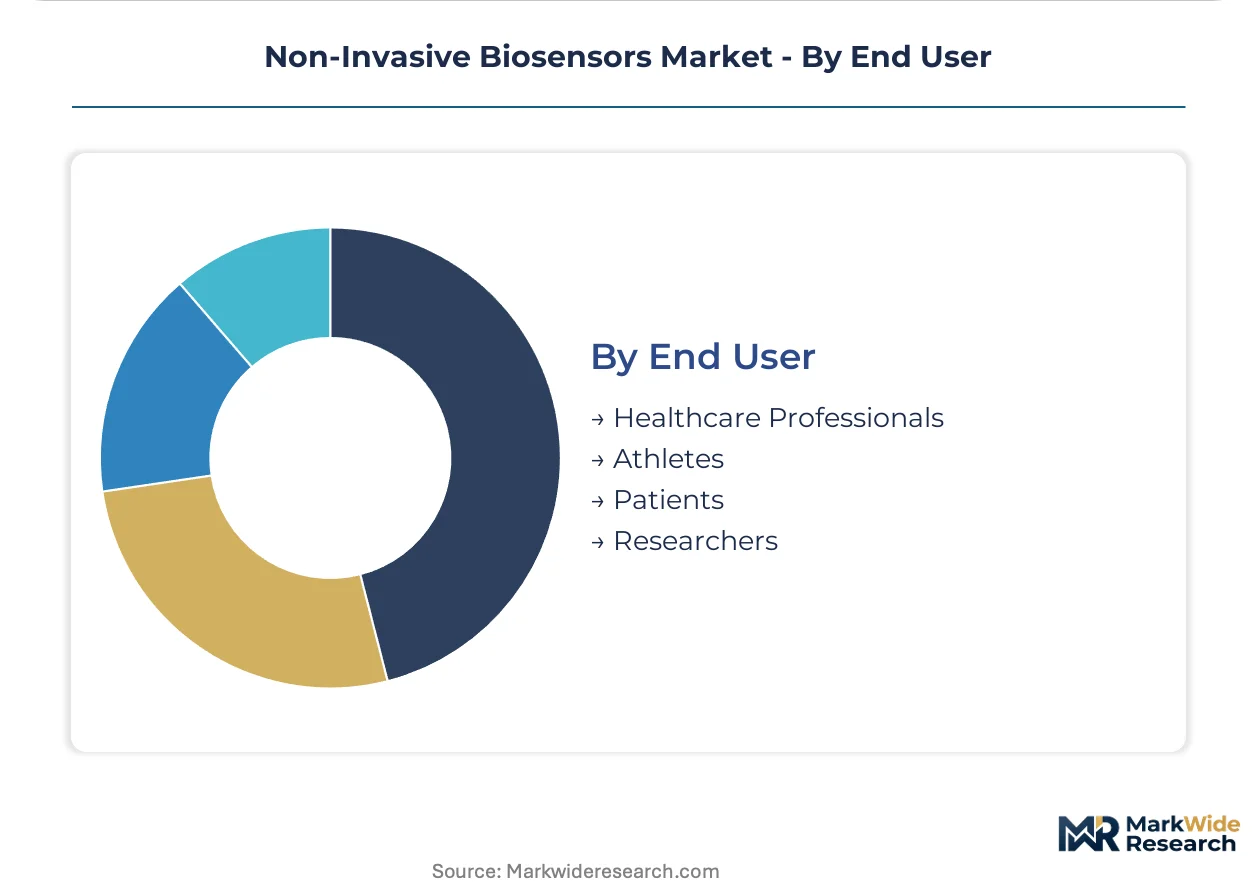
- Healthcare Professionals:Physician and nursing utilization of biosensor data for clinical decision-making requires FDA-cleared devices with documented equivalence to reference standards. Hospital electronic health record integration demands substantial custom interface investment.
- Patients:Direct consumer acquisition of continuous monitoring devices for chronic disease self-management is expanding through pharmacy and online channels.
- Athletes:Performance optimization applications prioritize real-time feedback and training load quantification over clinical accuracy certification.
- Researchers:Academic and pharmaceutical investigation of physiological patterns requires raw data access and configurable sampling protocols.
Healthcare Professionals dominate institutional spend. Patients represent the fastest-climbing segment through direct-to-consumer channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized optical engineers and regulatory affairs specialists concentrate in the United States, Germany, and Japan, anchoring the geographic distribution of non-invasive biosensor development. These talent pools align with reimbursement frameworks that favor remote patient monitoring and accelerate commercial timelines for novel modalities.
United States
Hospital systems in Texas and California are scaling procurement of continuous glucose monitors to reduce readmission penalties under CMS value-based care programs. FDA breakthrough device designations compress review timelines for optical spectroscopy platforms seeking market entry. The Boston-Cambridge corridor hosts dense clusters of photonics startups developing Raman-based glucose sensing prototypes.
Germany
German hospital networks are unbundling device hardware from data analytics subscriptions, treating continuous monitoring as a service rather than capital equipment. MDR Article 117 enforcement mandates notified body involvement for measuring-function devices, elevating compliance costs for CE marking pathways. The Baden-Württemberg region concentrates precision optics manufacturing capabilities serving wearable biosensor supply chains.
Japan
Academic medical centers in Tokyo and Osaka are piloting wrist-worn Raman spectroscopy prototypes in type 1 diabetes cohorts. PMDA operates a parallel track for software-as-a-medical-device classifications encompassing AI-enhanced biosensor analytics. The Kansai region maintains established distribution networks for hospital-grade monitoring systems with deep electronic health record integration experience.
United Kingdom
NHS long-term plan commitments to remote patient monitoring are expanding addressable markets for ambulatory biosensor platforms in England and Scotland. MHRA convergence with MDR requirements is recalibrating cost-of-entry calculus for European market access post-Brexit. The Oxford-Cambridge arc attracts venture capital for glucose monitoring ventures leveraging university photonics research.
India
Pharmaceutical manufacturers in Maharashtra and Karnataka are investigating non-invasive biosensors for clinical trial patient monitoring to reduce site visit burdens. CDSCO medical device rules are evolving to accommodate software-as-medical-device classifications for algorithm-enhanced diagnostics. The Hyderabad medical technology corridor is emerging as a contract development hub for optical sensor miniaturization.
Non-Invasive Biosensors Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across multiple technology vectors in the non-invasive biosensors market. The competitive structure stratifies into three tiers: multinational healthcare conglomerates with vertically integrated manufacturing footprints, mid-cap device specialists with regulatory velocity advantages, and venture-stage technology developers targeting single-modality breakthroughs. Dominant competitive moves include strategic partnerships with hospital systems for remote monitoring pilot programs and technology licensing agreements that accelerate optical spectroscopy maturation.
Among diversified healthcare conglomerates, Abbott Laboratories and Philips Healthcare exemplify archetypes with established distribution networks spanning multiple regulatory jurisdictions. Nemaura Medical occupies a position within the focused specialist tier, representing pure-play concentration on wearable glucose monitoring platforms. Integrity Applications Inc. sits within the technology development segment, anchoring early-stage optical sensing approaches that remain pre-commercial.
| Leading Market Players |
|---|
| GE Healthcare |
| Integrity Applications Inc. |
| Abbott Laboratories |
| MediWise Ltd. |
| OrSense |
| Medtronic Plc |
| Nemaura Medical, Inc. |
| Akers Biosciences, Inc. |
| Philips Healthcare |
| Others |
Value Chain & Pricing Dynamics
Photodetector spot prices in East Asian commodity markets cascade through three distinct pricing tiers for finished biosensor hardware, with specialized narrow-bandwidth light sources commanding premium multiples that compress margins for non-vertically integrated assemblers.
Pricing Analysis
The bundled-vs-unbundled service split separates capital equipment vendors from platform-as-a-service providers. Hospital procurement committees in Germany and the United States increasingly favor per-patient-per-month subscriptions over upfront device purchases, compressing hardware margins while expanding lifetime value capture. Pricing stratifies across FDA-cleared clinical tiers, CE-marked measuring-function tiers, and direct-to-consumer wellness tiers. Cost compression in the consumer wellness segment intensifies because component suppliers concentrate in Taiwan and South Korea. Healthcare professional procurement shows lowest price sensitivity due to reimbursement code insulation, while direct-to-consumer channels exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for wearable biosensors remain underdeveloped, with limited refurbishment infrastructure for optical sensor arrays and battery modules creating end-of-life cost externalities. Component manufacturing concentrates in Taiwan, South Korea, and Japan for photodetectors, flexible printed circuit boards, and precision optics. Finished device assembly draws from Malaysia, Mexico, and Ireland to balance tariff exposure against FDA inspection proximity. Single-source vulnerability in indium gallium arsenide photodetector supply creates concentration risk. Distribution runs through hospital group purchasing organizations in the United States, centralized procurement consortia in Germany, and pharmacy retail chains in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-invasive biosensors market functions as a geographic-arbitrage play where MDR compliance costs in Europe run substantially higher than FDA breakthrough pathway expenses in the United States, creating divergent capital allocation strategies across regulatory jurisdictions.
For Market Incumbents: To counter unbundling pressure from hospital procurement committees, Abbott Laboratories and Philips Healthcare should deepen backward integration into photodetector supply and secure exclusive optical component offtake agreements. Capacity addition in Malaysia and Mexico preserves tariff-advantaged assembly flexibility while maintaining FDA inspection readiness. Certification investment in Japan's PMDA software-as-medical-device parallel track secures algorithm update velocity. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for optical spectroscopy specialists to compress commercialization timelines against European competitors burdened by MDR Article 117 notified body requirements. Sleep tracking through employer wellness programs represents the most penetrable white-space target, with direct-to-consumer pharmacy distribution offering the cleanest go-to-market angle bypassing hospital procurement gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where multidisciplinary talent scarcity intersects with escalating clinical validation costs for equivalence trials. The five-to-ten-year viability window favors acquisition targets with captive optical engineering capabilities and established notified body relationships in Europe. PMDA software-as-medical-device approval velocity serves as the critical inflection signal for algorithm-centric platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 117 compliance unlocks European hospital procurement access for measuring-function devices. |
| Hospital System Partnership | Remote patient monitoring pilots with Texas and California systems reduce CMS readmission penalty exposure. |
| Software Companion Development | PMDA software-as-medical-device classification enables continuous algorithm updates without new submissions. |
| Reimbursement Strategy | CPT code expansion for remote therapeutic monitoring extends addressable market beyond early adopters. |
| Backward Integration | In-house photodetector production insulates against East Asian supply concentration and spot price volatility. |
Study Parameters
Direct dialogue with hospital procurement managers, biomedical engineers, regulatory affairs specialists, and GPO contracts administrators grounded the qualitative foundation, cross-referenced against FDA 510(k) and breakthrough device filings, EMA MDR submission databases, CMS Medicare reimbursement code updates, and Japanese PMDA approval records. Bottom-up and top-down triangulation validated volume estimates across the analysis window.
Bottom-up modeling aggregated unit economics by product type, technology modality, application segment, and end-user channel, while top-down approaches cross-checked against aggregate healthcare expenditure flows and remote patient monitoring adoption curves. CAGRs derived from segmented growth rate blending across optical spectroscopy maturation, cardiac monitoring reimbursement expansion, and direct-to-consumer channel development. Hospital readmission penalty schedules and evolving CPT code coverage served as industry-specific demand inputs.
Revisions become necessary when FDA breakthrough pathway criteria tighten, MDR notified body capacity constraints extend timelines, or East Asian component supply experiences geographic disruption. Practitioners should monitor PMDA software-as-medical-device precedent expansion and CMS remote therapeutic monitoring code updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Point of Care Diagnostics Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market