
 Ophthalmic Devices Market | 2026-2036
Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Devices Market Analysis
The EU Medical Device Regulation is consolidating the cost-of-entry calculus for ophthalmic device manufacturers seeking European market access. Alcon leverages its vertically integrated manufacturing footprint to absorb heightened conformity assessment expenses. Johnson & Johnson Vision Care sustains competitive positioning through R&D intensity in laser-based vision correction platforms. Bausch & Lomb anchors its presence via specialized distribution networks across ambulatory surgical centers.
Ophthalmic devices comprise precision-engineered instruments, implants, and diagnostic systems designed for ocular examination, surgical intervention, and vision correction, typically manufactured under ISO 13485 quality management systems with biocompatibility validation per ISO 10993. Their primary commercial purpose centers on restoring, preserving, or enhancing visual function across acute care and outpatient settings. Diagnostic equipment occupies the most mature margin pool, while intraocular lenses represent the fastest-growing product category driven by premium toric and multifocal material innovations. Laser surgery technology leads procedural volume among technology segments, though non-invasive diagnostics is displacing traditional imaging workflows in early disease detection protocols.
The FDA governs premarket notification and approval pathways for ophthalmic devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations across European member states. These frameworks shape demand by privileging manufacturers with robust quality systems and penalizing entrants lacking notified body relationships or substantial equivalence dossiers. Stakeholders must monitor evolving harmonization efforts between FDA and EU regulatory paradigms to anticipate compliance cost trajectories and portfolio prioritization decisions.
Market Dynamics
The ophthalmic devices market is undergoing structural compression as premium intraocular lens materials reshape surgical economics and FDA premarket review intensification filters manufacturer viability. Tiered clinical evidence requirements now stratify competitive access across implantable and diagnostic categories.
Growth Catalysts
- Aging Demographics:Cataract surgery volumes in hospital settings are climbing across developed economies as patient pools expand. Medicare reimbursement stability in the United States sustains procedure accessibility.
- ISO 13485 Quality Mandates:Biocompatibility validation per ISO 10993 is elevating manufacturing standards industry-wide. This framework privileges established producers with validated quality systems.
- Laser Platform Innovation:Femtosecond laser systems are expanding addressable procedure volumes in refractive correction. Ambulatory surgical centers are accelerating capital deployment for these platforms.
Market Restraints
- Silicone Hydrogel Input Volatility:Raw material concentration among Asian chemical suppliers creates cost pressure for contact lens manufacturers. Supply chain redundancy remains limited.
- EU MDR Conformity Burden:Stricter clinical evidence requirements and post-market surveillance obligations are extending time-to-market for new entrants. Notified body capacity constraints amplify delays.
- Phacoemulsification Equipment Longevity:Extended service life of installed surgical systems compresses replacement cycles. Capital equipment refresh rates lag technology advancement.
Strategic Opportunities
- India's Outpatient Infrastructure:Underpenetrated tier-2 and tier-3 cities present whitespace for diagnostic device deployment. CDSCO regulatory harmonization is simplifying import pathways.
- AI-Integrated Diagnostics:Machine learning algorithms converging with optical coherence tomography are enabling earlier disease detection. Screening protocols in primary care settings are expanding addressable volume.
- Japan's Refractive Surgery Incentives:METI-backed precision medicine initiatives are subsidizing advanced laser platform adoption. Domestic manufacturers are prioritizing R&D localization.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Specialized expertise in ocular biomechanics and materials science is concentrated among a limited workforce. Academic pipeline output trails industry demand.
- FDA 510(k) Substantial Equivalence Complexity:Predicate device identification and clinical comparison studies are extending regulatory timelines. Documentation requirements are intensifying for novel lens geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Devices Market |
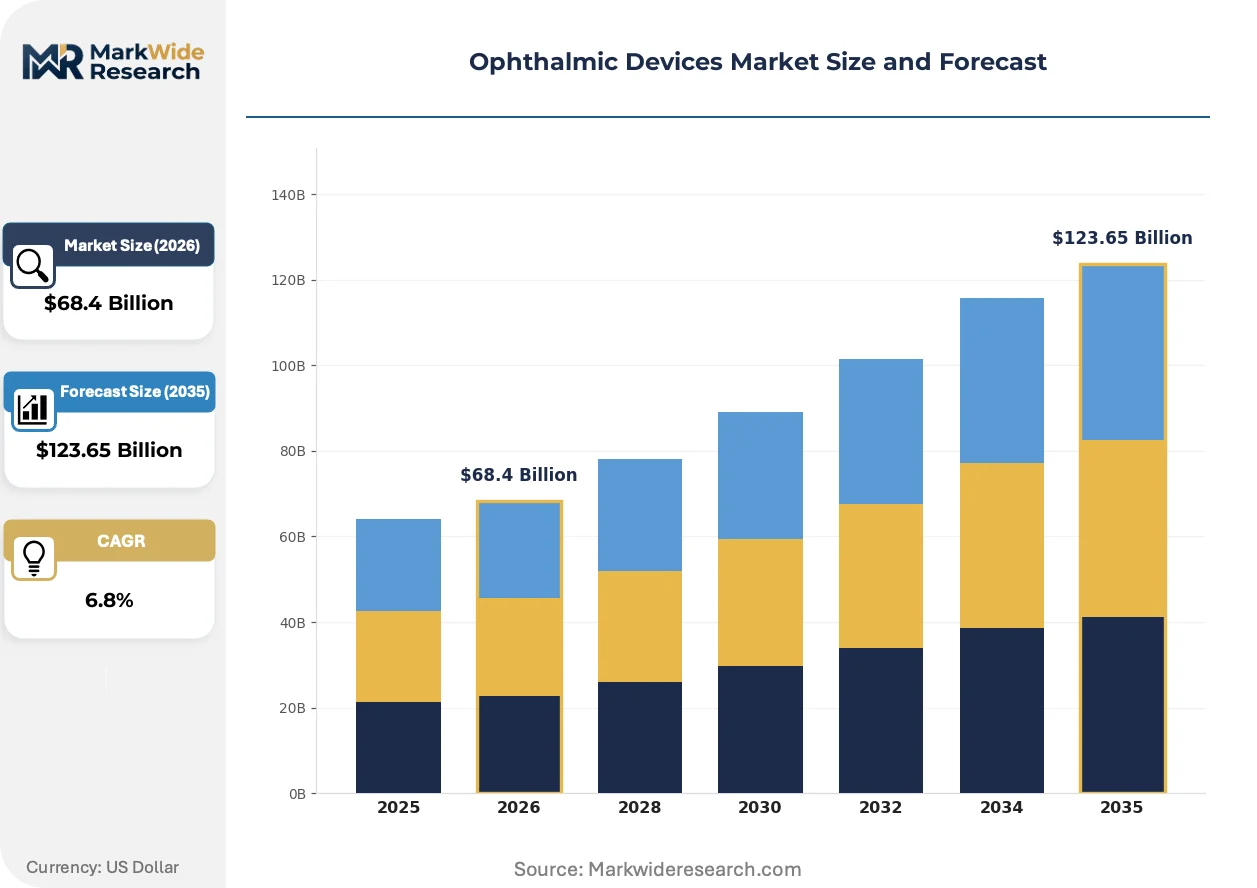
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Lenses, Intraocular Lenses, Surgical Instruments, Diagnostic Equipment End User: Hospitals, Eye Clinics, Surgical Centers, Homecare Technology: Laser Surgery, Phacoemulsification, Optical coherence tomography, Non-invasive Diagnostics Application: Cataract Surgery, Glaucoma Treatment, Retinal Procedures, Vision Correction |
| Companies Covered | Alcon, Johnson & Johnson Vision Care, Bausch & Lomb, Carl Zeiss Meditec, Essilor International, The Cooper Companies, Nidek Co., Ltd., Topcon Corporation, Haag-Streit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Devices Market Emerging Trajectories
Digital diagnostic workflows are displacing traditional imaging protocols across ophthalmology practices, compressing examination duration while expanding screening throughput. Material science advances in hydrophobic acrylics are redefining implant performance benchmarks.
Extended depth-of-focus intraocular lenses are absorbing premium segment demand as presbyopia-correcting alternatives to monofocal implants. Ambulatory surgical centers in the United States are accelerating adoption of these platforms. The technology is absorbing margin compression from commoditized standard lenses by commanding differentiated reimbursement.
EU Medical Device Regulation clinical evidence requirements are reshaping portfolio prioritization decisions for manufacturers seeking European market access. Post-market surveillance obligations now mandate systematic performance tracking across implanted devices. Premium toric and multifocal lens categories face the steepest compliance cost escalation as notified body scrutiny intensifies.
Consolidated provider networks in the United States are compressing vendor rosters and unbundling after-sales service from equipment procurement. Hospital purchasing organizations are centralizing ophthalmic device sourcing decisions. This concentration is most visible in Medicare Advantage plan networks steering volume toward manufacturers with full regulatory dossiers.
Ophthalmic Devices Market Segmentation
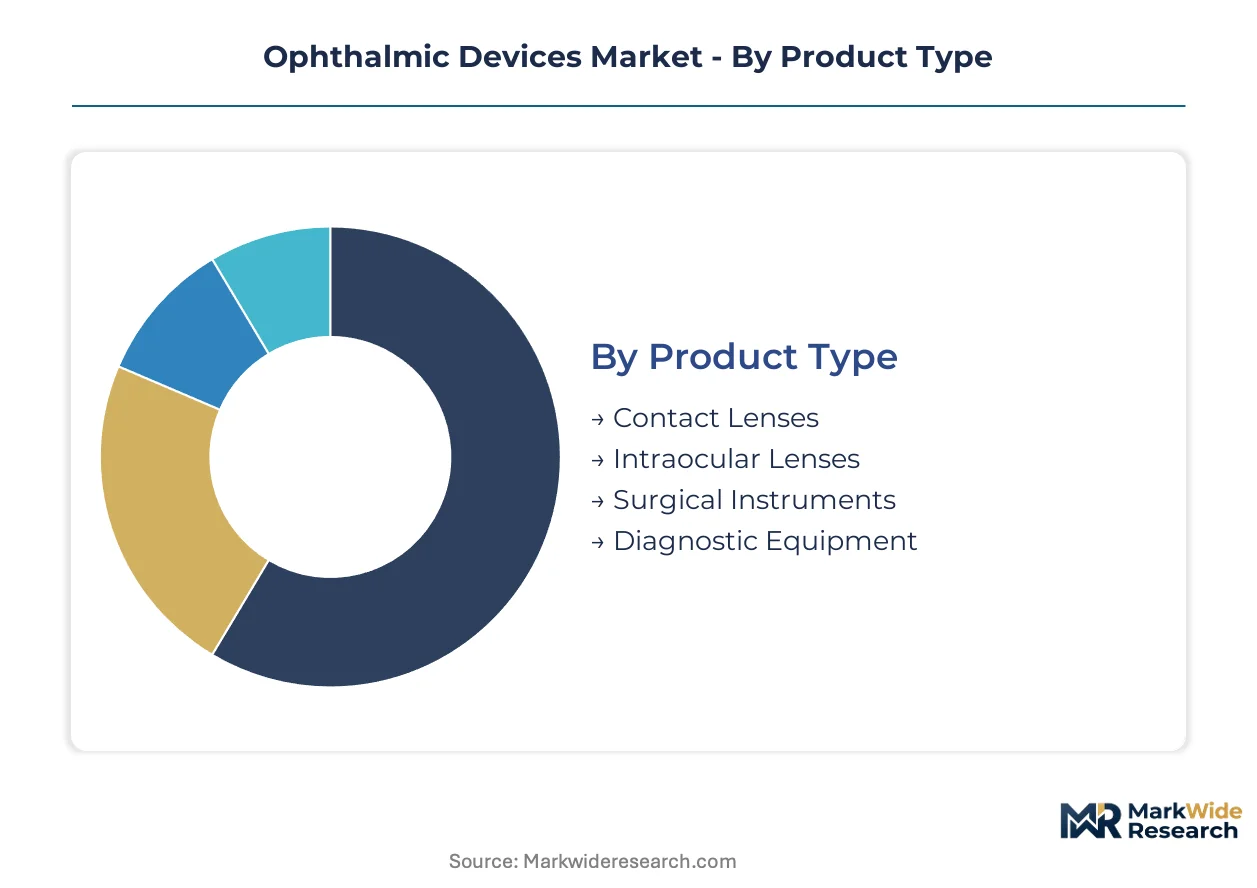
Segmentation in ophthalmic devices reveals how regulatory intensity, reimbursement pathways, and clinical workflow integration stratify commercial opportunity. Manufacturers must align portfolio investments with the specific compliance burdens and procurement dynamics governing each category.
Product Type:
Supply concentration varies sharply across product categories, with implantable devices demanding captive manufacturing capabilities and diagnostic equipment permitting outsourced assembly.
- Intraocular Lenses:Hydrophobic acrylic and silicone platforms with toric and multifocal geometries command premium positioning. Demand concentrates in Medicare Advantage networks across the United States, where reimbursement differentiation favors presbyopia-correcting designs over standard monofocal alternatives.
- Diagnostic Equipment:Optical coherence tomography systems and fundus cameras integrate AI-enabled image analysis for early disease detection. Procurement is accelerating in ambulatory settings across Germany and Japan as screening protocols expand beyond hospital ophthalmology departments.
- Contact Lenses:Silicone hydrogel daily disposables dominate volume, with raw material sourcing concentrated among Asian chemical suppliers.
- Surgical Instruments:Phacoemulsification handpieces and accessory kits follow equipment refresh cycles tied to capital budgets.
Intraocular lenses absorb the bulk of installed capacity; diagnostic equipment is expanding most quickly.
End User:
Procurement authority is fragmenting across settings, with consolidated purchasing organizations in hospital systems contrasting against direct manufacturer relationships in independent surgical centers.
- Surgical Centers:Freestanding ambulatory facilities in the United States deploy femtosecond laser platforms and premium IOL inventory. Volume is climbing fastest in metropolitan markets where Medicare reimbursement stability supports case migration from hospital outpatient departments.
- Hospitals:Integrated delivery networks centralize capital equipment decisions through value analysis committees. Academic medical centers in France and Italy anchor complex retinal procedure volumes.
- Eye Clinics:Private practice settings prioritize diagnostic device leasing arrangements over outright purchase.
- Homecare:Contact lens distribution and low-vision aids serve chronic management outside clinical settings.
Hospitals retain the deepest capital commitment; surgical centers are gaining share fastest.
Technology:
Clinical evidence requirements under FDA and EU MDR are stratifying competitive access, with laser platforms facing predicate device scrutiny and imaging technologies navigating software-as-medical-device classification.
- Laser Surgery:Femtosecond systems for corneal flap creation and lens fragmentation integrate with diagnostic planning software. Deployment is concentrating in Japan under METI-backed precision medicine subsidies and in refractive surgery chains across Spain.
- Optical Coherence Tomography:Spectral-domain and swept-source platforms deliver cross-sectional retinal imaging with micron-level resolution. Adoption is displacing traditional fundus photography in primary care screening networks across the United Kingdom.
- Phacoemulsification:Ultrasound-based cataract extraction remains the procedural standard, with equipment longevity compressing replacement demand.
- Non-invasive Diagnostics:Tear film analyzers and corneal topographers support preoperative planning without tissue contact.
Laser surgery commands the highest capital intensity; optical coherence tomography is penetrating fastest.
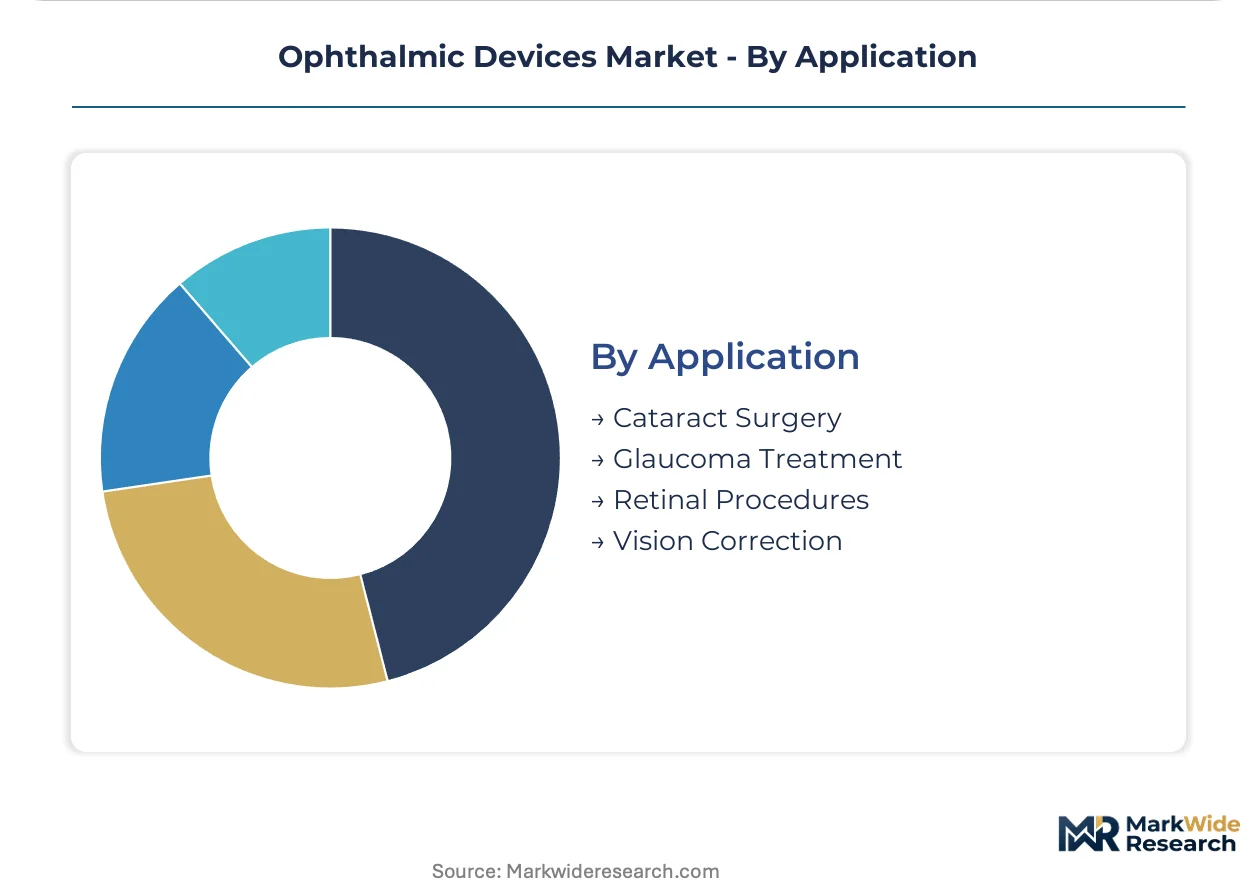
Application:
Procedure economics vary by reimbursement tier, with cataract surgery benefiting from stable Medicare fee schedules and retinal interventions facing prior authorization constraints.
- Cataract Surgery:Phacoemulsification with IOL implantation represents the highest-volume ophthalmic procedure globally. Case volumes are climbing in aging populations across the United States, Germany, and Japan, with premium lens up-sell rates determining profitability.
- Vision Correction:LASIK and PRK procedures using excimer laser platforms serve elective refractive demand. Consumer financing models are expanding access in private clinic networks across Brazil and Mexico.
- Glaucoma Treatment:Minimally invasive surgical devices and sustained-release drug delivery systems address progressive optic nerve damage.
- Retinal Procedures:Vitrectomy systems and membrane peeling instruments serve macular hole and diabetic retinopathy interventions.
Cataract surgery absorbs the dominant share of device utilization; vision correction is recovering fastest from pandemic-era volume disruptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Suzhou concentrate ophthalmic device manufacturing under China's NMPA regulatory framework. These hubs absorb contract assembly for intraocular lens and diagnostic equipment components serving Asia-Pacific distribution networks.
United States
Medicare Advantage networks steer cataract procedure volume toward established manufacturers with full FDA dossiers. The FDA's strengthened 510(k) premarket review pathways extend regulatory timelines for novel intraocular lens geometries. Rochester, New York anchors specialized contact lens production clusters serving consolidated hospital purchasing organizations.
Germany
Optical coherence tomography deployment accelerates in ambulatory settings as screening protocols expand beyond hospital ophthalmology departments. The EU Medical Device Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations across German member state implementation. Jena and Oberkochen concentrate precision optics manufacturing for diagnostic platform assembly.
Japan
METI-backed precision medicine initiatives subsidize advanced femtosecond laser platform adoption for refractive correction procedures. The PMDA governs premarket approval pathways for ophthalmic implants and surgical equipment. Tokyo and Osaka metropolitan areas host domestic manufacturers prioritizing R&D localization under national innovation programs.
India
Underpenetrated tier-2 and tier-3 cities present whitespace for diagnostic device deployment as outpatient infrastructure expands. CDSCO regulatory harmonization simplifies import pathways for multinational manufacturers seeking market access. Hyderabad and Bengaluru clusters concentrate medical device engineering talent for contract research and component fabrication.
Switzerland
Swissmedic maintains stringent quality system requirements for ophthalmic device market authorization within European Free Trade Association alignment. Geneva and Basel regions host precision manufacturing operations for surgical instrument and implant component supply. The country's bilateral mutual recognition agreements with the EU facilitate streamlined conformity assessment for export-oriented producers.
Ophthalmic Devices Market Vendor Landscape
United States and European producers anchor one tier; Japanese specialists hold differentiated positions in precision diagnostic platforms. Market structure consolidates around vertically integrated manufacturers with captive intraocular lens material production and notified body relationships under EU MDR. Three archetypes dominate: diversified medical technology conglomerates with ophthalmic divisions, pure-play vision care specialists, and precision optics houses with medical device extensions. Competitive moves concentrate on regulatory dossier completeness and ambulatory surgical center distribution network penetration.
Among diversified medical technology conglomerates, Alcon and Johnson & Johnson Vision Care occupy positions exemplifying scale-driven regulatory navigation. Bausch & Lomb represents the pure-play vision care archetype with specialized distribution network concentration. These three entities anchor tiered competitive positioning stratified by quality system maturity and European market access capabilities.
| Leading Market Players |
|---|
| Alcon |
| Johnson & Johnson Vision Care |
| Bausch & Lomb |
| Carl Zeiss Meditec |
| Essilor International |
| The Cooper Companies |
| Nidek Co., Ltd. |
| Topcon Corporation |
| Haag-Streit |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up surgical instrument specialists have consolidated phacoemulsification handpiece manufacturing in the United States and Germany, tightening supply discipline while enforcing three-tier pricing structures across premium, standard, and economy levels. This ownership concentration feeds directly into procurement leverage against ambulatory surgical centers and hospital purchasing organizations.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to toric and multifocal intraocular lens orders from ambulatory surgical centers facing urgent surgical schedules, while spot inventory of standard monofocal designs clears at discounted rates. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 quality certification status, with fully-dossiered manufacturers commanding sustained premiums. Cost compression in the silicone hydrogel contact lens tier is intensifying because raw material sourcing concentrates among Asian chemical suppliers. Hospital purchasing organizations exhibit the highest price sensitivity due to centralized value analysis committees, whereas independent refractive surgery chains prioritize technology performance over unit cost.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific chemical suppliers to North American and European manufacturing sites has elevated landed costs for hydrophobic acrylic monomers and silicone hydrogel polymers by double-digit percentages over recent contract cycles. Supply concentrates in China for contact lens raw materials, Germany for precision optics components, and Switzerland for surgical instrument forgings. The network draws from specialized inputs including optical-grade polymers, femtosecond laser crystals, and biocompatible titanium alloys. Single-source vulnerability around notified body capacity under EU MDR creates regulatory chokepoint risk. Distribution runs through manufacturer-direct sales forces to hospital purchasing organizations and specialized surgical distributors serving ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ophthalmic devices market operates under supply-constrained conditions where notified body capacity bottlenecks under EU MDR prop pricing power for manufacturers with established conformity assessment relationships.
For Market Incumbents: Anchor defensive positioning through backward integration into hydrophobic acrylic material production and captive notified body relationships under EU MDR. Expand capacity addition in Jena and Oberkochen precision optics clusters to secure component supply. Prioritize certification investment in AI-enabled diagnostic software modules to preempt software-as-medical-device classification delays.
For New Entrants and Emerging Players: AI-integrated optical coherence tomography platforms offer the most penetrable wedge for new market participants. Target India's tier-2 and tier-3 cities where outpatient infrastructure expansion outpaces established manufacturer distribution reach. Deploy diagnostic device leasing arrangements as the primary go-to-market angle to overcome capital budget constraints in private eye clinic settings.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision optics houses with medical device extensions in German and Swiss manufacturing corridors where quality system investments already satisfy EU MDR and Swissmedic requirements. Long-term viability over a five-to-ten year window rests on regulatory dossier completeness rather than technology differentiation alone. Monitor notified body capacity expansion announcements as the critical inflection signal for new entrant viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortened premarket timelines capture Medicare Advantage network procurement windows before predicate device saturation. |
| CE Marking Pathway Investment | EU MDR conformity assessment relationships unlock ambulatory surgical center demand across German and French markets. |
| Hospital System Partnership | Integrated delivery network contracts centralize ophthalmic device sourcing through value analysis committee endorsement. |
| Software Companion Development | AI-integrated diagnostic planning modules differentiate femtosecond laser platforms in Japanese METI-subsidized installations. |
| Reimbursement Strategy | Medicare Advantage plan network inclusion steers cataract procedure volume toward premium IOL up-sell opportunities. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, biomedical engineers at ambulatory surgical centers, GPO contracts managers, and ophthalmology clinic administrators. Secondary validation drew from FDA 510(k) databases, EU MDR notified body registers, CMS Medicare reimbursement schedules, and ISO certification body records. Bottom-up and top-down triangulation reconciled manufacturer shipment data with procedure volume estimates from hospital discharge databases.
Segment-level granularity modeled intraocular lens geometries, diagnostic equipment modalities, and surgical instrument categories across the projection horizon, with separate treatment of ambulatory surgical center and hospital outpatient department procurement channels. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for regulatory timeline impacts. Forecast inputs incorporated cataract surgery volume projections tied to aging demographic profiles and femtosecond laser platform deployment rates in refractive surgery chains.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR notified body capacity constraints or sudden Medicare reimbursement schedule revisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ocular Inflammation Treatment Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Ocular Inserts Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Neurotrophic Keratitis Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Vision Care Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Leber Congenital Amaurosis Market