
 Earwax Removal Aid Market | 2026-2036
Earwax Removal Aid Market Size, Share, and Industry Trends Forecast 2026-2036
Earwax Removal Aid Market Analytics
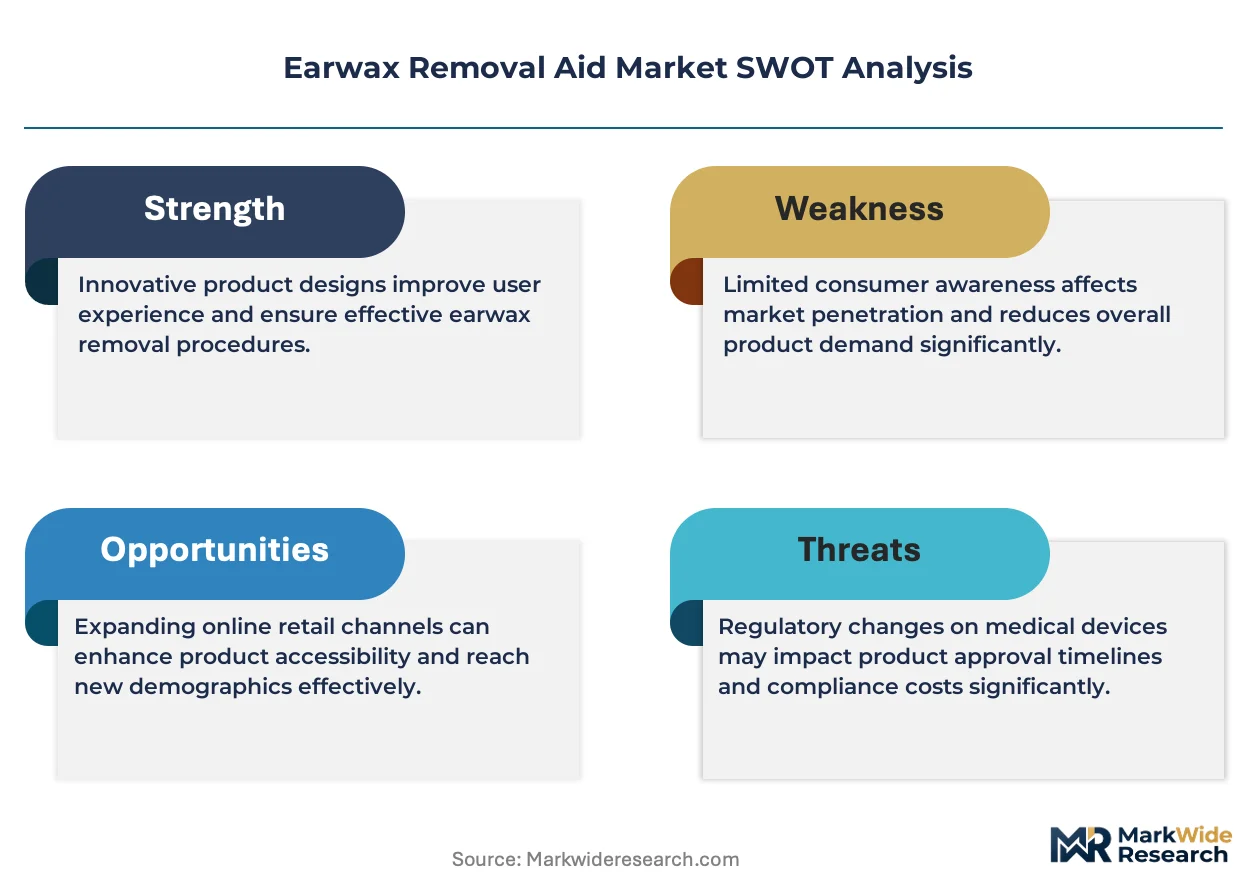
Fragmentation across new buyer channels is repositioning how earwax removal products reach end users. Prestige Consumer Healthcare dominates shelf space in North American drugstores through its established retail relationships. Johnson & Johnson sustains brand trust with consumers seeking familiar over-the-counter solutions. NeilMed Pharmaceuticals specializes in irrigation-based systems that appeal to users preferring mechanical over chemical removal methods.
Earwax removal aids encompass formulations, instruments, and devices designed to soften, dissolve, or physically extract cerumen from the external auditory canal; carbamide peroxide solutions typically operate at concentrations between 6.5% and 10% to achieve keratolytic breakdown of impacted wax within several minutes of instillation. Manual tools and irrigation kits serve users seeking non-pharmacologic intervention, while ear drops capture recurring purchase behavior through repeat consumption patterns. Offline retail channels control the majority of transaction volume for immediate-need purchases, though subscription services are capturing adherent users who schedule recurring deliveries of maintenance formulations.
The FDA classifies cerumenolytic ear drops and manual removal instruments under distinct regulatory pathways, with labeling requirements mandating specific contraindication language regarding perforated tympanic membranes. Health Canada and the European Medicines Agency impose parallel safety standards that manufacturers must navigate for multi-jurisdiction product registration. Stakeholders should monitor how evolving consumer preference for at-home diagnostic tools intersects with regulatory scrutiny of app-connected otoscopes and smart irrigation devices.
Market Dynamics
Pharmacy chains are consolidating shelf space for self-care ear health products while the FDA tightens labeling requirements for Class II cerumenolytic devices, forcing manufacturers to reformulate or exit.
Growth Catalysts
- Direct-to-consumer health spending:United States households allocate disproportionate budgets to otologic self-treatment, creating pull-through for maintenance-formulation subscriptions.
- REACH compliance harmonization:European chemical safety standards for carbamide peroxide concentrations are streamlining multi-jurisdiction product registration, reducing time-to-market for compliant manufacturers.
- Irrigation device miniaturization:Portable battery-powered systems are displacing manual bulb syringes in home-use settings, expanding the addressable user base beyond clinical referrals.
Market Restraints
- Active pharmaceutical ingredient concentration limits:FDA-mandated 6.5-10% carbamide peroxide ceilings cap efficacy differentiation and compress margin potential for premium formulations.
- Retailer concentration risk:CVS Health, Walgreens Boots Alliance, and Walmart control North American shelf access, extracting slotting fees that erode profitability for mid-tier entrants.
- Mechanical substitute threat:Manual curette tools and cotton-tipped applicators persist as zero-cost alternatives in price-sensitive consumer segments, limiting penetration of device-based solutions.
Strategic Opportunities
- App-connected otoscope convergence:Smartphone-integrated visualization tools paired with irrigation systems are creating integrated diagnostic-treatment platforms that command premium positioning.
- Subscription channel expansion:Recurring delivery models for maintenance ear drops are capturing adherent users outside traditional pharmacy replenishment cycles, locking in lifetime value.
- Health Canada Class II pathway:Streamlined medical device licensing for irrigation systems is accelerating market entry for manufacturers with existing FDA 510(k) clearances.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing requirements for polymer irrigation tips extend product development cycles by 12-18 months, delaying revenue recognition.
- Legacy retail system integration:Electronic data interchange compliance with pharmacy chain inventory management platforms demands specialized IT infrastructure that smaller manufacturers lack.
- Audiologist referral dependency:Clinical validation requirements for cerumenolytic efficacy claims necessitate costly third-party studies, raising barriers to marketing differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earwax Removal Aid Market |
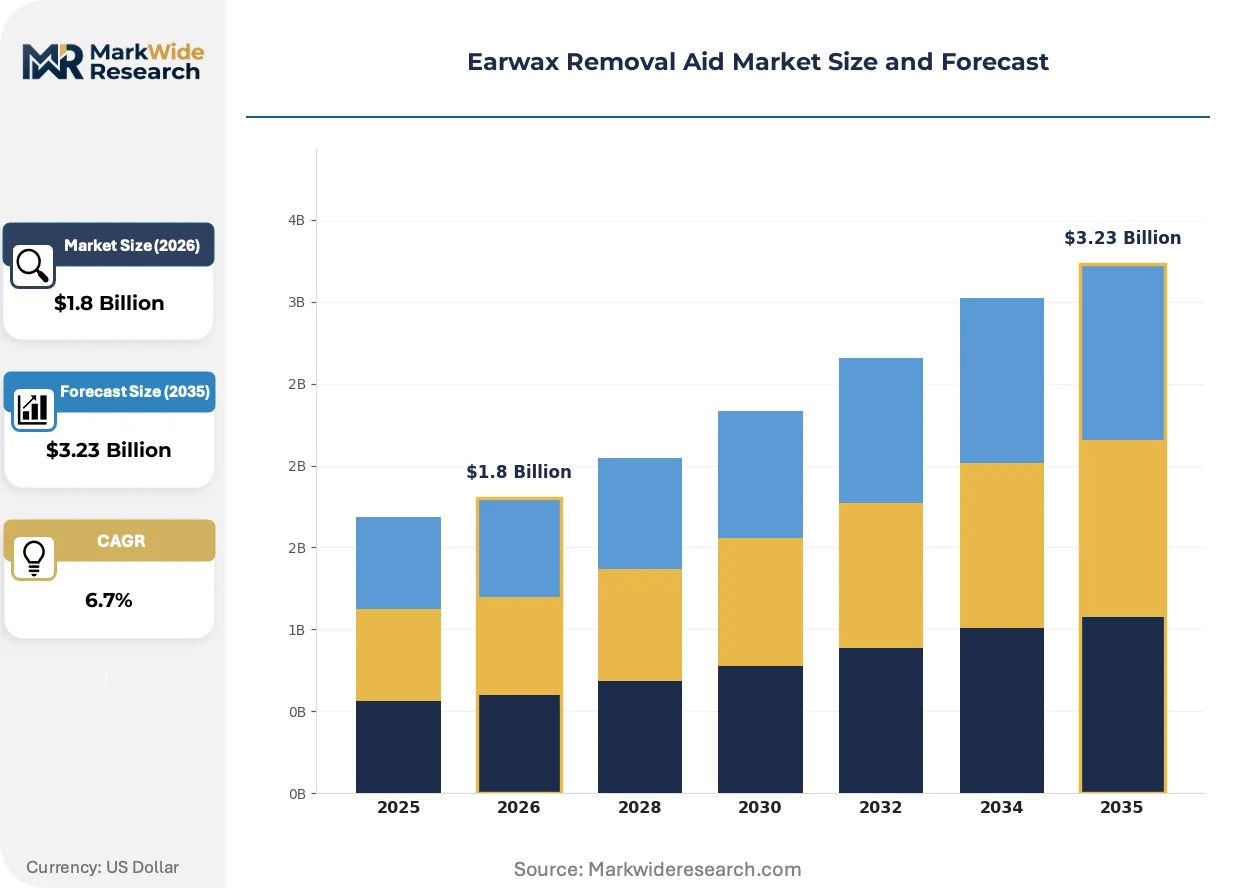
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ear Drops, Manual Tools, Bulb Syringes, Irrigation Kits End User: Consumers, Healthcare Professionals, Pharmacies, Clinics Delivery Mode: Online Retail, Offline Retail, Subscription Services, Custom Orders Packaging Type: Bottles, Tubes, Kits, Single-use Packets |
| Companies Covered | Prestige Consumer Healthcare Inc., Johnson & Johnson, Bausch + Lomb, NeilMed Pharmaceuticals Inc., GlaxoSmithKline, Cipla Ltd., Eosera Inc., SafKan Health, Clearwax Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earwax Removal Aid Market Evolving Landscape
Digital health integration is redefining how consumers diagnose and treat earwax accumulation, blurring boundaries between clinical oversight and autonomous self-care.
Smart irrigation systems equipped with pressure sensors and flow-rate regulators are automating the mechanical extraction process that previously required manual technique. Home users with limited dexterity or anatomical familiarity are adopting these devices fastest, particularly in aging demographics. The technology is automating safety protocols that once depended on professional supervision, reducing liability exposure for manufacturers while expanding permissible use cases.
The FDA's updated guidance on cerumenolytic labeling now mandates explicit contraindication language regarding perforated tympanic membranes, affecting all Class II ear drop formulations. Manufacturers must redesign packaging and patient information leaflets to comply, with non-compliant products facing import detention. Carbamide peroxide solution producers targeting the United States market are responding by adding QR-linked video instructions to supplement printed warnings.
Subscription-based replenishment for maintenance ear drops is displacing episodic pharmacy purchases among chronic cerumen overproducers. Direct-to-consumer platforms are capturing these users through automated refill algorithms tied to usage tracking. This behavioral shift is most pronounced in United States metropolitan markets where same-day delivery infrastructure supports just-in-time inventory models.
Earwax Removal Aid Market Segmentation
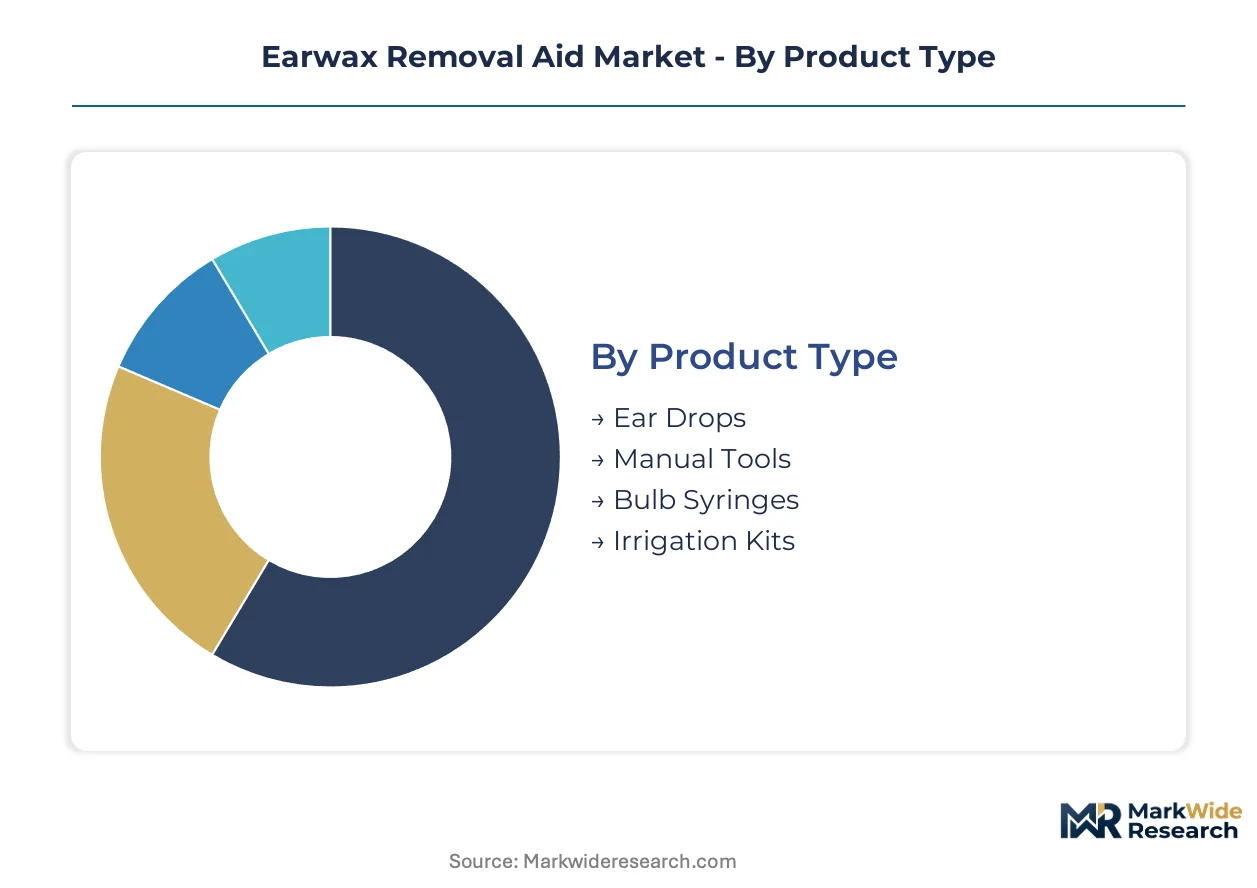
Segmentation in the earwax removal aid market reveals divergent paths between immediate-need purchases and planned maintenance regimens. Product form, user setting, and channel selection each impose distinct regulatory, margin, and loyalty dynamics on manufacturers.
Product Type:
Customization versus standardization tension runs deepest here, with chemical formulations requiring precise concentration compliance while mechanical tools compete on ergonomic differentiation.
- Ear Drops:Carbamide peroxide solutions at 6.5-10% concentration dominate pharmacy shelf space. United States households drive disproportionate volume through repeat purchases of maintenance formulations.
- Manual Tools:Curettes and loop extractors appeal to price-sensitive segments seeking zero-cost alternatives to chemical or powered solutions. Cotton-tipped applicator substitution risk constrains premium positioning.
- Bulb Syringes:Low-cost rubber bulbs remain the entry irrigation method for cost-conscious consumers.
- Irrigation Kits:Battery-powered systems with pressure sensors automate extraction for users with limited dexterity.
Most installed capacity flows through Ear Drops. Expansion is steepest in Irrigation Kits.
End User:
Volume concentration tilts toward self-directed use, yet professional channels anchor clinical validation requirements and premium pricing authority.
- Consumers:Direct-to-user sales capture episodic need and subscription-driven maintenance alike. FDA labeling mandates on perforated tympanic membrane contraindications shape purchase decision support.
- Healthcare Professionals:Audiologists and primary care physicians demand instrument-grade tools with biocompatibility certification. ISO 10993 testing requirements for irrigation tips extend procurement cycles.
- Pharmacies:CVS Health and Walgreens Boots Alliance control North American shelf access through slotting fee structures.
- Clinics:Outpatient otolaryngology settings prioritize single-use packet formats for infection control compliance.
Revenue concentrates in Consumer channels. Professional validation requirements are stiffest for Healthcare Professionals.
Delivery Mode:
Channel selection determines margin capture, with direct subscription models bypassing retailer concentration risk entirely.
- Online Retail:E-commerce platforms aggregate comparison shoppers seeking price transparency on commodity formulations.
- Offline Retail:Immediate-need purchases sustain pharmacy chain dominance despite slotting fee erosion.
- Subscription Services:Automated refill algorithms tied to usage tracking lock in adherent users outside traditional replenishment cycles. United States metropolitan same-day delivery infrastructure supports just-in-time inventory models.
- Custom Orders:Institutional procurement for clinic systems and hospital networks.
Transaction volume runs through Offline Retail. Customer lifetime value peaks in Subscription Services.
Packaging Type:
Format selection reflects use setting sterility requirements and portability demands across home and clinical environments.
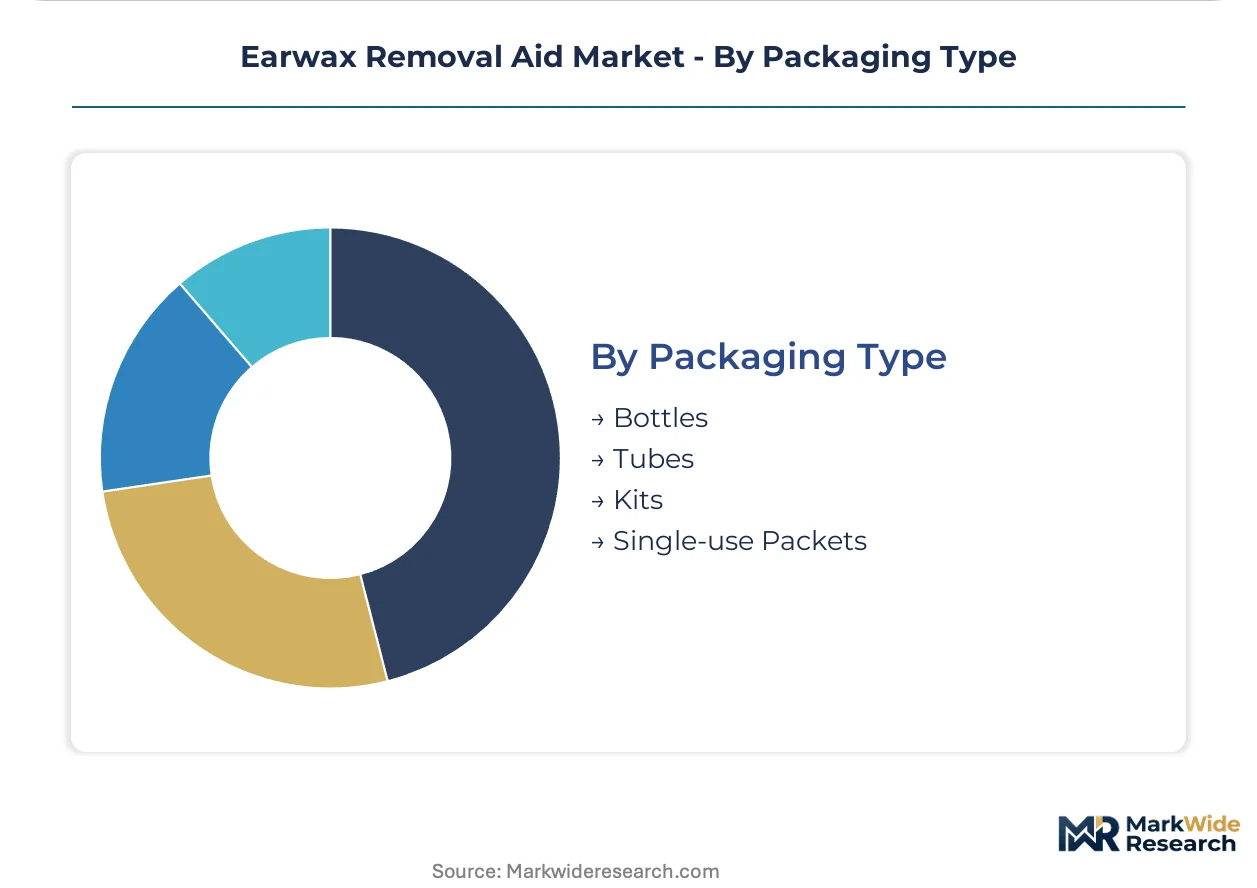
- Bottles:Multi-dose containers dominate maintenance ear drop regimens with cost-per-dose efficiency.
- Tubes:Squeeze formats suit viscous cerumenolytic gels requiring controlled extrusion.
- Kits:Bundled irrigation systems with multiple tip sizes and solution reservoirs command premium positioning.
- Single-use Packets:Unit-dose formats satisfy clinic infection control protocols and travel portability needs.
Manufacturing scale favors Bottles. Margin expansion concentrates in Kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households outspend German consumers on otologic self-treatment by a substantial margin, while Japanese buyers favor irrigation devices over chemical formulations. National regulators shape access patterns through distinct classification schemes for cerumenolytic products.
United States
Direct-to-consumer health expenditure on ear care products exceeds comparable European markets. FDA Class II device regulations mandate specific contraindication language for perforated tympanic membranes on all cerumenolytic packaging. Pharmacy chains in metropolitan markets consolidate shelf space for self-care ear health products.
Germany
Consumers demonstrate strong preference for mechanical removal methods over chemical solutions. ECHA REACH compliance requirements for carbamide peroxide concentrations streamline product registration for multi-jurisdiction manufacturers. Industrial clusters in Baden-Württemberg host precision irrigation device fabricators serving EU distribution networks.
Japan
Aging demographics drive adoption of automated irrigation systems requiring minimal manual dexterity. PMDA medical device classification distinguishes between household-use and professional-grade cerumen removal instruments. Tokyo-based distributors coordinate procurement for clinic networks across the Kanto region.
United Kingdom
NHS cost-containment pressures push patients toward pharmacy-based self-treatment options. MHRA labeling requirements align with FDA standards for cerumenolytic safety warnings. London pharmacy chains expand dedicated ear health aisles in response to reduced GP availability for wax removal procedures.
Canada
Health Canada Class II medical device licensing accelerates market entry for irrigation systems with existing FDA clearances. Cross-border supply chains from US manufacturers dominate retail availability in Ontario and Quebec. Vancouver metropolitan pharmacies report strongest subscription service adoption for maintenance ear drop regimens.
Earwax Removal Aid Market Competitive Landscape
North American producers anchor the mass-market tier; European specialists hold premium positioning through regulatory certification depth. Market structure tilts toward consolidation among pharmacy channel incumbents, with mid-tier entrants facing retailer concentration risk. Three archetypes dominate: diversified healthcare conglomerates with established retail relationships, single-category specialists with irrigation expertise, and pharmaceutical manufacturers with API supply advantages. Competitive moves center on subscription channel expansion and app-connected device convergence.
Among diversified healthcare conglomerates, Johnson & Johnson and GlaxoSmithKline exemplify the formulation-led archetype with established over-the-counter distribution networks. Prestige Consumer Healthcare occupies a position representing retail relationship depth in North American pharmacy chains. NeilMed Pharmaceuticals sits within the irrigation-specialist tier, anchoring mechanical removal system expertise.
| Leading Market Players |
|---|
| Prestige Consumer Healthcare Inc. |
| Johnson & Johnson |
| Bausch + Lomb |
| NeilMed Pharmaceuticals Inc. |
| GlaxoSmithKline |
| Cipla Ltd. |
| Eosera Inc. |
| SafKan Health |
| Clearwax Ltd. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up pharmacy shelf-space incumbents enforce pricing discipline through slotting fee leverage, while contract manufacturers in Asia-Pacific absorb margin compression to retain FDA-registered production lines for carbamide peroxide formulations.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for generic carbamide peroxide API, forcing branded formulation producers toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA Class II certification tier and after-sales clinical support bundling. Pricing pressure intensifies as retailer concentration at CVS Health and Walgreens extracts promotional allowances. Price-sensitive consumers in manual tool segments resist premium irrigation device migration.
Supply Chain Analysis
Dual-sourcing qualification requirements from North American pharmacy chains mandate redundant API suppliers across India and China, with secondary qualification in Germany for REACH-compliant carbamide peroxide. Raw material dependencies center on hydrogen peroxide feedstock, pharmaceutical-grade glycerin, and polymer resins for irrigation tips. Supply chain risk concentrates in single-source vulnerability for battery-powered irrigation motor assemblies. Distribution runs through pharmacy chain EDI networks and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in earwax removal aids hinges on subscription automation reducing customer acquisition costs and smart device premium tiers capturing aging demographic willingness-to-pay.
For Market Incumbents: Extend subscription algorithm capabilities to lock in adherent users before emerging direct-to-consumer entrants capture metropolitan same-day delivery infrastructure. Defend against mechanical substitute erosion by bundling diagnostic otoscope apps with irrigation kit purchases. Reinforce FDA 510(k) clearance moats through biocompatibility certification depth that delays mid-tier competitive entry. For New Entrants and Emerging Players: Enter via Health Canada Class II pathway acceleration for irrigation systems with existing FDA clearances, exploiting regulatory reciprocity gaps. Target audiologist referral channel white space with instrument-grade single-use packet formats. Penetrate German mechanical-preference segments through ECHA REACH-compliant carbamide peroxide alternatives with ergonomic differentiation. For Investors and Strategic Acquirers: Valuations sit cheapest among irrigation-specialist tier with FDA clearance but limited retail shelf access. Five-to-ten-year viability favors manufacturers with backward integration into polymer tip molding and captive API supply. Watch FDA guidance expansion on app-connected otoscope software classification as inflection signal for platform convergence plays.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Channel Expansion | Automated refill algorithms at direct-to-consumer platforms lock lifetime value outside pharmacy replenishment cycles. |
| App-Connected Otoscope Convergence | Smartphone-integrated diagnostic tools paired with irrigation systems command premium positioning in aging demographics. |
| FDA 510(k) Clearance Acceleration | Streamlined device approvals for battery-powered irrigation systems reduce time-to-shelf against manual bulb competitors. |
| Biocompatibility Certification Investment | ISO 10993 testing completion for polymer tips extends procurement cycle barriers protecting incumbent positioning. |
| REACH Compliance Harmonization | European chemical safety standard alignment reduces multi-jurisdiction registration friction for carbamide peroxide producers. |
Research Methodology
Direct dialogue with pharmacy category buyers, biomedical engineers at irrigation device manufacturers, FDA regulatory consultants, and formulary directors at CVS Health and Walgreens Boots Alliance grounded qualitative findings. Secondary validation drew from FDA 510(k) clearance databases, Health Canada medical device licenses, ECHA REACH registration filings, and pharmacy chain annual procurement disclosures. Bottom-up demand modeling triangulated against top-down market sizing from trade customs data.
Segment-level value outputs across product type, end user, delivery mode, and packaging format dimensions were projected throughout the forecast period. CAGRs were derived from regression analysis against demographic aging curves, direct-to-consumer health expenditure trends, and regulatory approval velocity. Industry-specific forecast inputs included carbamide peroxide concentration compliance shifts and smart device penetration rates in metropolitan markets.
Inputs from FDA guidance documents and pharmacy chain shelf-space allocation data were available through the study window; gaps in real-time subscription platform transaction data introduce uncertainty bands around direct-to-consumer channel projections. Deviation in FDA classification of app-connected diagnostic software would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Compression Socks Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Forensic Swabs Market