
 Smart Vision Aids Market | 2026-2036
Smart Vision Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Vision Aids Market Insights
The European Accessibility Act is hardening conformance mandates for digital assistive technologies across EU member states. OrCam Technologies leverages advanced computer vision modules to sustain technology leadership in wearable reading devices. HumanWare Group anchors its position through specialized distribution networks serving rehabilitation centers and educational institutions. Vuzix Corporation competes in augmented reality smart glasses with optical waveguide designs optimized for low-vision enhancement.
Smart vision aids comprise electro-optical systems integrating cameras, processors, and display or audio output mechanisms to translate visual information into perceptible formats for users with impaired sight. These devices typically employ image sensors with resolutions exceeding 8 megapixels coupled with edge-computing chipsets capable of real-time text-to-speech and object recognition at sub-second latency, serving primarily to restore functional independence in daily navigation, reading, and environmental interaction. Smart glasses dominate current revenue contribution due to premium pricing and concentrated R&D investment, while mobile applications represent the fastest-expanding category as smartphone penetration and software-only deployment models reduce patient acquisition costs. AI algorithms command disproportionate margin pools because proprietary training datasets and inference optimization create defensible intellectual property barriers against hardware commoditization.
The FDA in the United States classifies certain smart vision aids as Class II medical devices requiring 510(k) premarket notification, while the EMA and notified bodies under the EU MDR enforce clinical evaluation and post-market surveillance for wearable assistive technologies distributed in Europe. Japan's PMDA maintains distinct pharmaceutical and medical device approval pathways that manufacturers must navigate for reimbursement eligibility under the country's long-term care insurance system. Stakeholders must monitor evolving reimbursement codes and regulatory harmonization initiatives between major markets to anticipate access barriers and prioritize certification investments.
Market Dynamics
Edge AI inference is compressing latency thresholds for real-time visual processing, forcing hardware architectures toward on-device computation and away from cloud-dependent workflows in wearable assistive systems.
Growth Catalysts
- Reimbursement expansion:Germany's statutory health insurance funds now cover prescription smart glasses for low-vision patients, removing out-of-pocket barriers for elderly users with age-related macular degeneration.
- Computer vision maturation:Convolutional neural networks trained on proprietary ophthalmological datasets now deliver sub-200-millisecond text recognition, enabling functional reading speeds for legally blind users.
- European Accessibility Act:The EU mandate requires public-sector digital services to meet EN 301 549 conformance standards by 2025, creating procurement pull for certified assistive display technologies in government rehabilitation programs.
Market Restraints
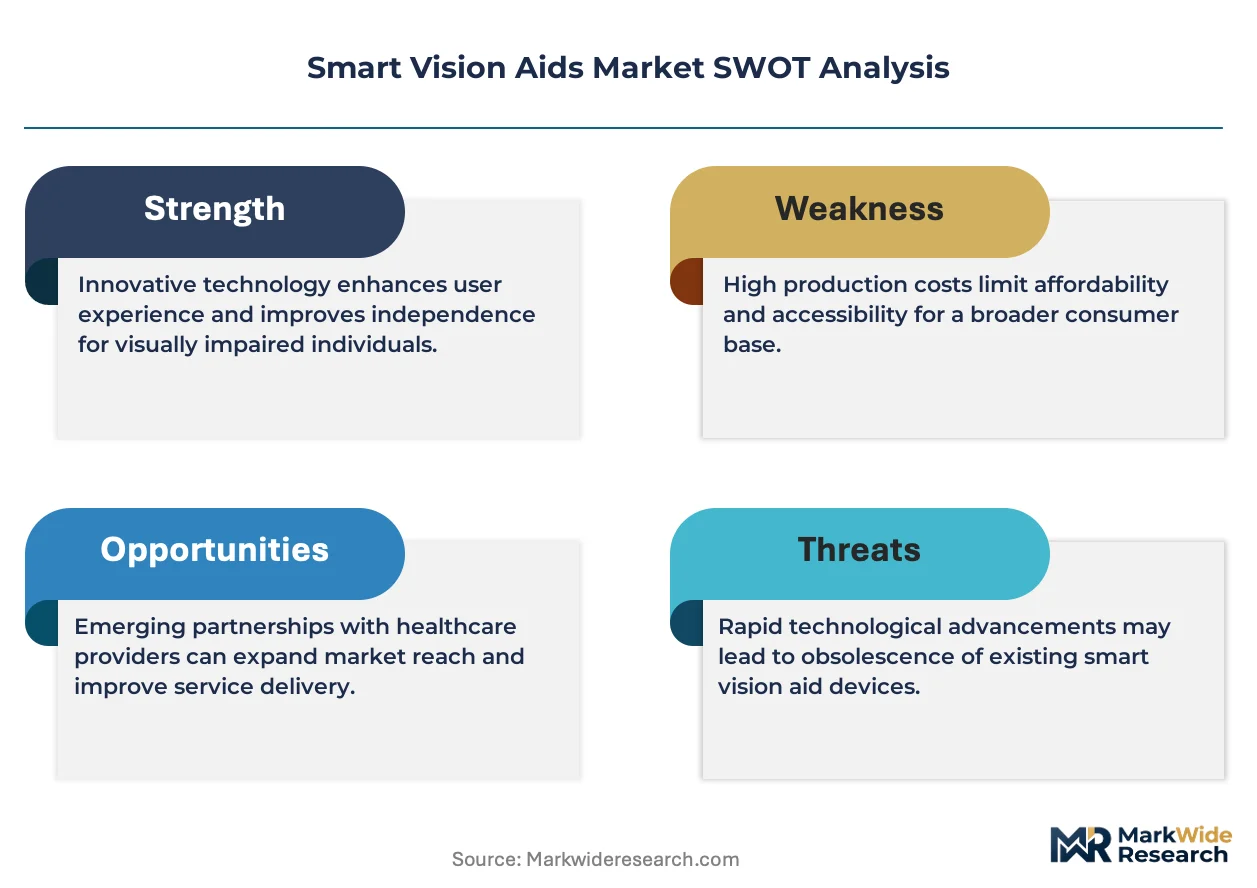
- Optical component concentration:Waveguide manufacturing for augmented reality displays concentrates among specialized foundries in Taiwan and South Korea, exposing supply vulnerability to geopolitical friction.
- Lithium-ion cell volatility:Battery energy density constraints limit continuous operation of camera-heavy wearables to 4-6 hours, forcing trade-offs between device weight and functional autonomy.
- MDR certification timelines:EU Medical Device Regulation clinical evaluation requirements extend approval cycles to 18-24 months for novel electro-optical assistive devices, delaying market entry.
Strategic Opportunities
- India's untapped geriatric base:The country's 60-plus population exceeds 140 million yet penetration of reimbursed low-vision aids remains below 2 percent, presenting first-mover advantage for localized distribution partnerships.
- Voice-first interface convergence:Integration of large language models with spatial audio output is electrifying hands-free environmental description for users with both visual and motor impairments.
- Educational procurement mandates:U.S. Individuals with Disabilities Education Act compliance is driving district-level bulk purchasing of wearable reading devices for K-12 students with print disabilities.
Industry Challenges
- Embedded systems talent scarcity:Shortage of engineers with simultaneous expertise in low-power FPGA design and ophthalmological signal processing is throttling R&D velocity at mid-tier device manufacturers.
- Interoperability fragmentation:Proprietary data formats between smart glasses, smartphone companion apps, and electronic health record systems force redundant integration work for hospital IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Vision Aids Market |
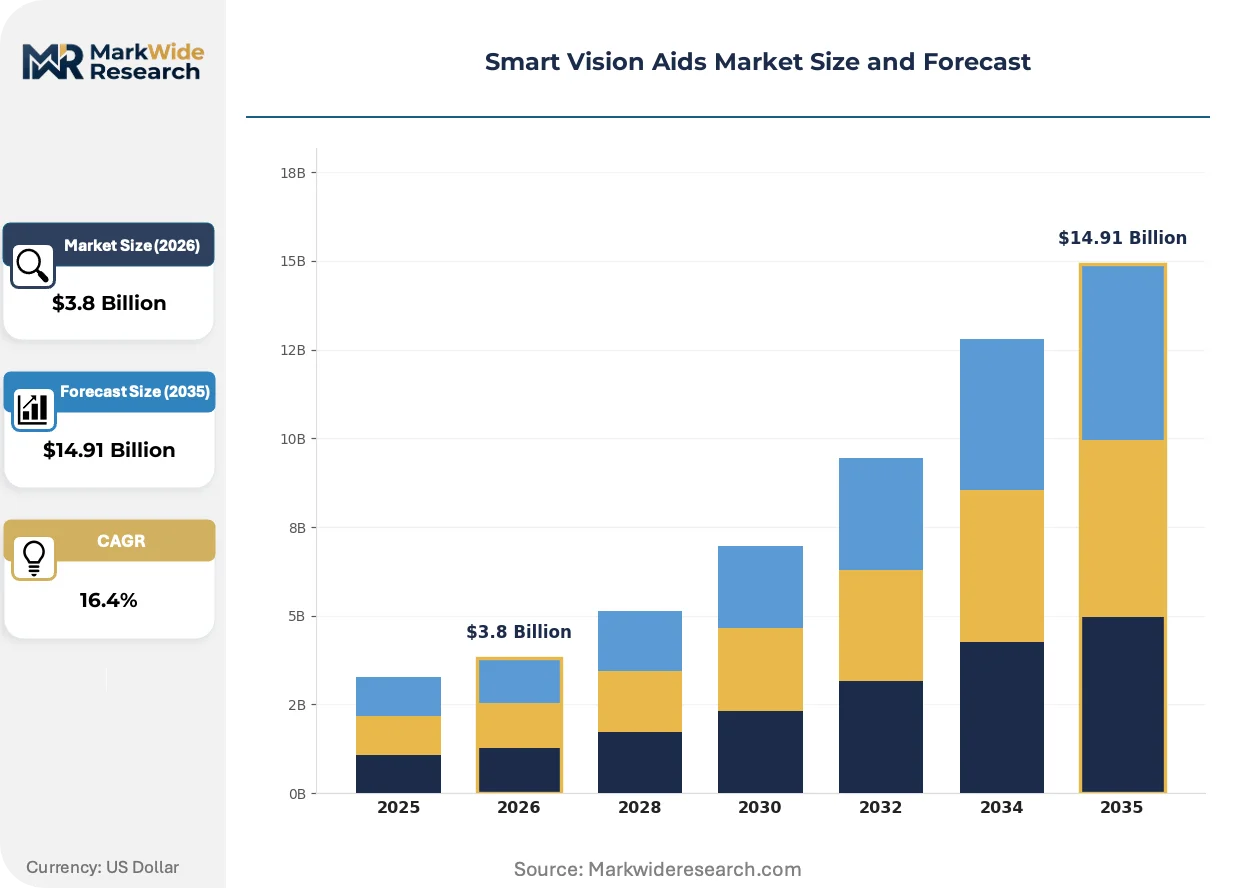
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Wearable Devices, Visual Assistive Tools, Mobile Applications Technology: Augmented Reality, Computer Vision, Image Processing, AI Algorithms End User: Individuals with Visual Impairments, Seniors, Education Sector, Healthcare Providers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Medical Suppliers |
| Companies Covered | OrCam Technologies, HumanWare Group, Freedom Scientific, VFO, HIMS Inc., Dolphin Computer Access Ltd., American Thermoform Corporation, LVI Low Vision International AB, Vuzix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Vision Aids Market Trends and Innovations
Neuromorphic sensing architectures are reshaping power-performance trade-offs in wearable vision systems. Three developments are compressing competitive timelines and redefining user experience benchmarks.
Event-based image sensors from Prophesee and Insightness are electrifying motion-robust scene capture for low-vision aids. These bio-inspired chips output pixel-level brightness changes rather than full frames, slashing bandwidth and compute load by orders of magnitude. Rehabilitation centers in Japan are piloting devices with this technology for patients with severe photophobia. The shift is enabling all-day battery life in sub-50-gram form factors previously impossible with conventional CMOS arrays.
The EU AI Act's risk classification framework is tightening conformity assessment for machine-learning-enabled medical devices. High-risk AI systems must demonstrate bias mitigation and post-market performance monitoring, adding documentation burden but creating competitive moat for vendors with established quality management systems. German notified bodies are prioritizing audit capacity for computer vision aids, compressing approval timelines for prepared submitters while delaying unprepared competitors.
Subscription-based software access is displacing perpetual licensing in institutional procurement channels. Rehabilitation centers and school districts now prefer monthly per-seat models that bundle cloud-based OCR updates and remote technical support, reducing capital expenditure volatility. This preference is most pronounced in U.S. state vocational rehabilitation agencies facing unpredictable federal funding allocations, where operational expenditure flexibility outweighs total cost of ownership considerations.
Smart Vision Aids Market Segmentation
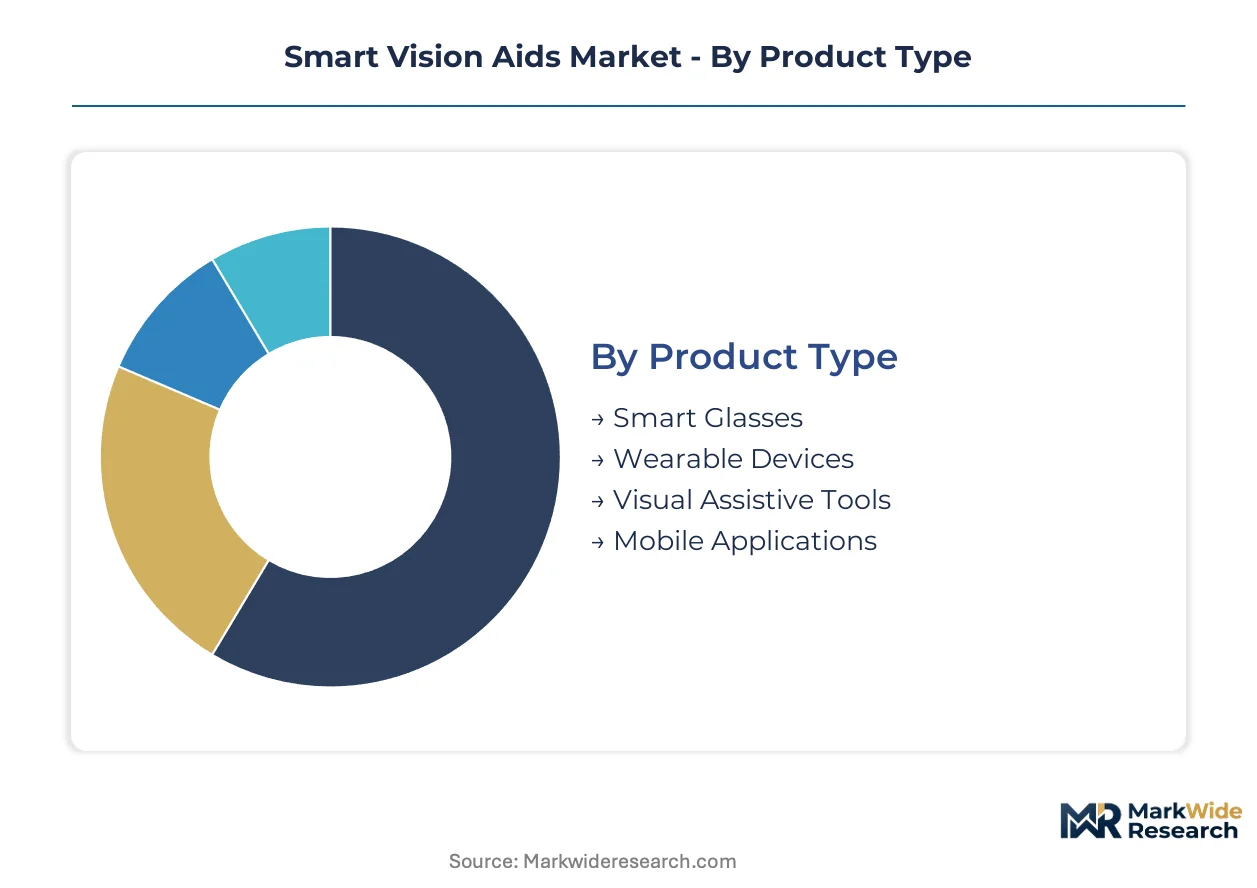
Product architecture determines whether smart vision aids function as standalone wearables or smartphone-tethered systems. Integration depth shapes pricing power, battery autonomy, and regulatory pathway complexity across patient populations.
Product Type:
Standalone wearable systems integrate all processing and output components within a single device, while tethered solutions offload computation to companion devices.
- Smart Glasses:Optical waveguide displays with embedded cameras and edge AI chipsets deliver real-time text-to-speech and object recognition without smartphone dependency. German statutory health insurance reimbursement for prescription smart glasses is accelerating procurement in rehabilitation centers serving age-related macular degeneration patients.
- Wearable Devices:Head-mounted displays and pendant cameras with bone-conduction audio output prioritize all-day comfort for users with concurrent motor impairments. Japan's PMDA approval pathway for long-term care insurance eligibility is concentrating demand among elderly users seeking functional independence.
- Visual Assistive Tools:Handheld electronic magnifiers with high-resolution LCD screens serve cost-sensitive users with residual vision.
- Mobile Applications:Software-only solutions leveraging smartphone cameras and cloud OCR reduce patient acquisition costs through existing device penetration.
Smart glasses lead volumes today; mobile applications are gaining share fastest.
Technology:
Core processing methodologies range from rule-based image enhancement to deep learning inference, with hardware-software coupling intensity varying by approach.
- AI Algorithms:Proprietary convolutional neural networks trained on ophthalmological datasets enable sub-200-millisecond text recognition and contextual scene description. EU AI Act high-risk system classification is creating compliance moats for vendors with established quality management systems while delaying unprepared competitors.
- Computer Vision:Edge-optimized inference engines compress latency for real-time environmental interaction without cloud connectivity. Event-based sensors from Prophesee and Insightness are slashing bandwidth requirements for motion-robust capture in photophobia-sensitive patients.
- Augmented Reality:Optical see-through waveguides overlay enhanced visual information onto residual sight.
- Image Processing:Traditional contrast enhancement and magnification pipelines serve users with moderate vision loss through lower-cost hardware.
Computer vision anchors current deployment; AI algorithms command the steepest expansion trajectory.
End User:
Patient acuity and care setting determine functional requirements, reimbursement access, and device durability specifications.
- Healthcare Providers:Rehabilitation centers and low-vision clinics require enterprise-grade fleet management, remote diagnostics, and institutional warranty terms. U.S. state vocational rehabilitation agencies facing unpredictable federal funding allocations are shifting procurement toward subscription models that bundle cloud OCR updates and technical support.
- Individuals with Visual Impairments:Legally blind users demand sub-second latency for navigation safety and reading independence. India's 140-million-plus geriatric population with below 2 percent penetration of reimbursed aids presents first-mover opportunity for localized distribution partnerships.
- Seniors:Age-related vision loss patients prioritize simplified interfaces and all-day battery reliability.
- Education Sector:K-12 students with print disabilities drive district-level bulk purchasing under U.S. Individuals with Disabilities Education Act compliance mandates.
Healthcare providers dominate institutional procurement; the education sector is expanding most quickly.
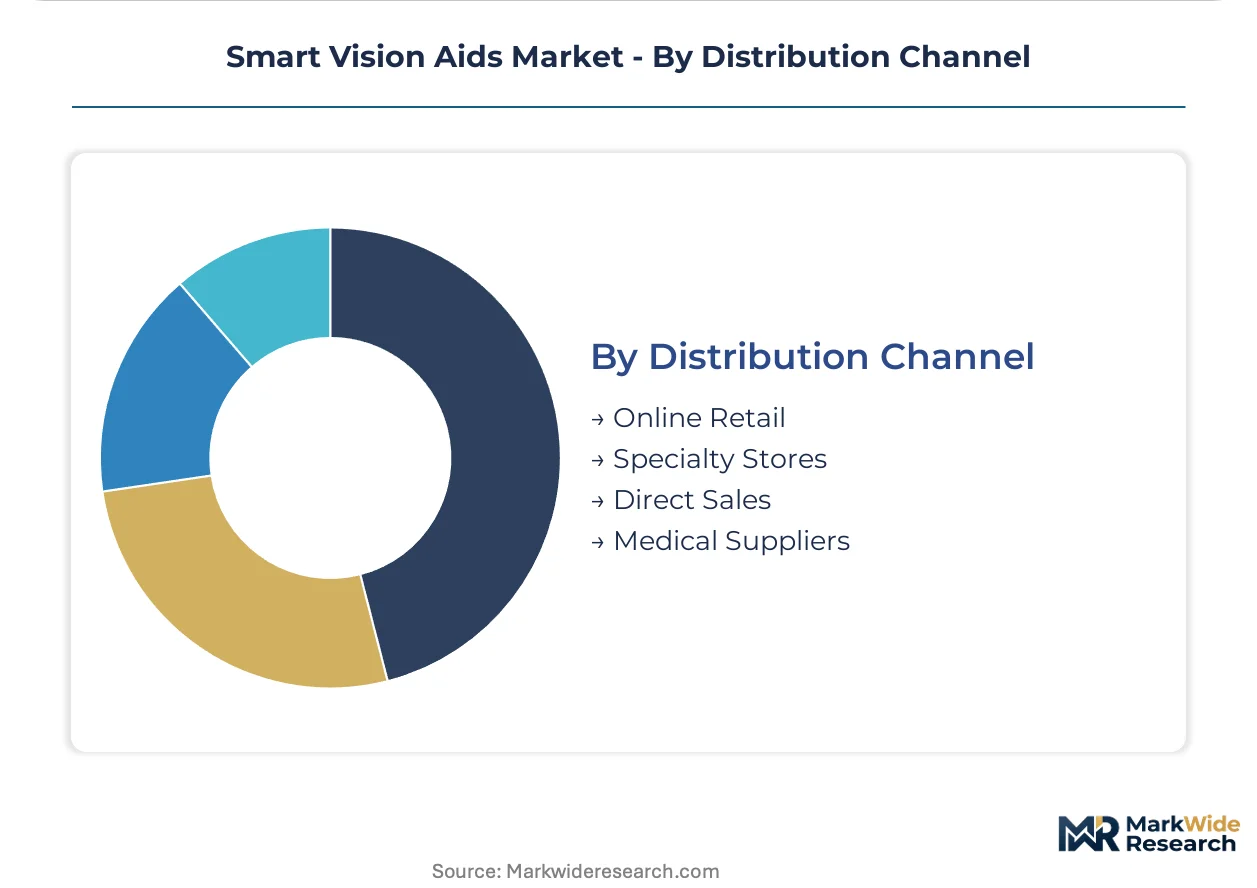
Distribution Channel:
Channel selection shapes patient onboarding support, reimbursement navigation assistance, and post-sale technical service intensity.
- Medical Suppliers:Specialized durable medical equipment distributors maintain relationships with low-vision specialists and navigate complex prior authorization workflows. German statutory health insurance fund contracting concentrates volume through accredited regional suppliers with certified technician networks.
- Direct Sales:Manufacturer-controlled channels capture margin and enable personalized fitting for premium wearable systems. EU MDR clinical evaluation requirements extending approval cycles to 18-24 months favor established vendors with regulatory infrastructure over new market entrants.
- Specialty Stores:Vision care retail chains provide hands-on demonstration for residual-sight users evaluating magnification options.
- Online Retail:E-commerce platforms reduce friction for software-only mobile application distribution and accessory purchases.
Medical suppliers lead channel volumes today; direct sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel pioneered wearable assistive vision technology during the early 2010s, establishing the technical foundations that now diffuse through rehabilitation centers across Germany, the United States, and Japan. This geographic spread reflects both aging demographics and divergent regulatory pathways for electro-optical medical devices.
United States
Reimbursement fragmentation across state Medicaid programs and Medicare Advantage plans creates uneven access to prescription smart glasses. The FDA's 510(k) premarket notification pathway for Class II medical devices accelerates approval for established electro-optical form factors while novel AI-enabled systems face extended review cycles. Boston's cluster of rehabilitation research hospitals pilots subscription-based fleet management models for vocational rehabilitation agencies.
Germany
Statutory health insurance funds now cover prescription smart glasses for low-vision patients with age-related macular degeneration, removing out-of-pocket barriers for elderly users. The EU MDR enforces clinical evaluation and post-market surveillance through German notified bodies, compressing approval timelines for prepared submitters. Munich's low-vision specialist centers concentrate procurement volume through accredited regional medical suppliers.
Japan
Long-term care insurance eligibility drives demand among elderly users seeking functional independence in daily navigation. The PMDA maintains distinct pharmaceutical and medical device approval pathways that manufacturers must navigate for reimbursement access. Tokyo rehabilitation centers pilot event-based sensor devices for patients with severe photophobia, leveraging bio-inspired chips for all-day battery life.
India
The country's 140-million-plus geriatric population with below 2 percent penetration of reimbursed low-vision aids presents first-mover opportunity for localized distribution partnerships. Central Drugs Standard Control Organization regulations for medical device imports create compliance barriers for foreign manufacturers. Bangalore's assistive technology incubators develop smartphone-tethered solutions to bypass hardware cost constraints.
United Kingdom
NHS England's specialized commissioning for low-vision services concentrates procurement decisions through regional clinical networks. The UK Medicines and Healthcare products Regulatory Agency aligns with EU MDR convergence initiatives while maintaining distinct post-market surveillance requirements. London's Moorfields Eye Hospital anchors research partnerships for computer vision algorithm validation in ethnically diverse patient cohorts.
Smart Vision Aids Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the smart vision aids landscape. The market structures around three tiers: integrated wearable system manufacturers, specialized software developers, and institutional distributors with technical service capabilities. Dominant competitive moves include strategic partnerships between optical component foundries and edge AI chipset vendors, plus portfolio diversification into subscription-based software access models that reduce capital expenditure volatility for rehabilitation centers.
Within the integrated system tier, OrCam Technologies and Vuzix Corporation exemplify divergent hardware strategies, while HumanWare Group anchors the specialized distribution archetype through relationships with rehabilitation centers and educational institutions. These three companies represent distinct competitive positions: computer vision module integration, augmented reality optical engineering, and institutional channel control respectively.
| Leading Market Players |
|---|
| OrCam Technologies |
| HumanWare Group |
| Freedom Scientific |
| VFO |
| HIMS Inc. |
| Dolphin Computer Access Ltd. |
| American Thermoform Corporation |
| LVI Low Vision International AB |
| Vuzix Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap optical component specialists in Taiwan and South Korea anchor waveguide manufacturing, creating supply discipline that transmits into premium-tier pricing power for AR-enabled smart glasses while subscription models in institutional channels compress upfront capital barriers.
Pricing Analysis
Three-tier pricing structure across prescription-certified, professional-grade, and consumer-accessible levels stratifies the market, with FDA 510(k) clearance and EU MDR certification commanding substantial premiums over uncertified alternatives. Price differentiation hinges on reimbursement eligibility under Germany's statutory health insurance and edge AI inference latency specifications. Cost compression in the consumer tier is intensifying because smartphone-tethered software solutions bypass hardware manufacturing overhead. Rehabilitation centers exhibit lowest price sensitivity due to bundled subscription preferences, while individual elderly users in cash-pay markets show highest sensitivity.
Supply Chain Analysis
Direct-to-rehabilitation-center channels handle institutional fleet procurement, while accredited medical suppliers manage insurance reimbursement workflows for individual patients. Waveguide manufacturing concentrates in Taiwan and South Korea, with edge AI chip fabrication anchored in the United States and China. Lithium-ion cells, optical-grade polymers, and high-resolution CMOS sensors constitute critical input dependencies. Single-source vulnerability in specialized AR waveguide foundries exposes downstream assemblers to geopolitical friction and capacity allocation constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart vision aids constitute a late-cycle quality story as procurement shifts toward sub-200-millisecond latency specifications and all-day battery reliability in sub-50-gram form factors.
For Market Incumbents: To counter neuromorphic sensor disruption from Prophesee and Insightness, OrCam Technologies and Vuzix Corporation must backward integrate into event-based image sensor supply or secure exclusive foundry allocation agreements. HumanWare Group should deepen channel control through certified technician network expansion in Germany's statutory health insurance reimbursement corridors. For New Entrants and Emerging Players: Enter via India's below-2-percent reimbursed low-vision aid penetration among 140 million geriatric citizens, partnering with Bangalore assistive technology incubators for smartphone-tethered distribution. Voice-first LLM integration for dual sensory impairment represents the most penetrable application white-space. For Investors and Strategic Acquirers: Rehabilitation technology roll-up specialists are the most active acquirer in this space, consolidating regional medical suppliers with certified technician networks. Five-to-ten year viability hinges on EU AI Act high-risk system compliance infrastructure. Watch German notified body audit capacity expansion as inflection signal for prepared versus delayed market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | German notified bodies compress approval timelines for prepared submitters while delaying unprepared competitors. |
| Neuromorphic Sensor Integration | Prophesee and Insightness event-based chips enable all-day battery life in photophobia-sensitive patient segments. |
| Subscription Model Transition | U.S. state vocational rehabilitation agencies prefer operational expenditure flexibility under unpredictable federal funding. |
| India Distribution Partnership | Localized smartphone-tethered solutions bypass CDSCO import compliance barriers for hardware manufacturers. |
| Voice-First LLM Development | Spatial audio output integration electrifies hands-free environmental description for dual visual-motor impairment users. |
Research Methodology
Multiple input streams — rehabilitation center procurement managers, biomedical engineers at low-vision clinics, GPO contracts managers, and edge AI chipset vendors — were reconciled against FDA 510(k) filings, EU MDR notified body audit records, CMS Medicare reimbursement databases, and German statutory health insurance fund contracting disclosures. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were triangulated to validate market sizing.
Data-stream reconciliation across product architecture, technology modality, end-user acuity, and distribution channel dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from patient population growth, reimbursement expansion trajectories, and technology substitution curves. Edge AI inference latency benchmarks and battery energy density improvement curves constituted critical forecast inputs.
Inputs from rehabilitation center fleet managers and notified body audit schedules were available through the study window; gaps in real-time subscription revenue recognition and emerging market reimbursement policy finalization introduce uncertainty bands. Forecasts reflect documented assumptions regarding EU AI Act implementation timing and lithium-ion cell supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Self-Injection Device Market
Medical Devices
Intubation Tubes Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
IV Equipment Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Automated Compounding Systems Market