
 Global Trauma Devices Market | 2026-2036
Global Trauma Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Trauma Devices Market Foresight
A shift from single-source titanium forging contracts toward multi-source additive manufacturing partnerships is rebalancing procurement economics for implant producers. DePuy Synthes leverages captive powder metallurgy capacity to protect margin pools on complex bone plate geometries. Stryker Corporation anchors its trauma portfolio through robotic surgery assistance integration across its navigation systems. Zimmer Biomet Holdings, Inc. differentiates via specialized intramedullary nail designs for geriatric fracture treatment protocols.
Trauma devices comprise metallic and polymer implants engineered to stabilize bone fractures, restore anatomical alignment, and enable osseous healing under physiological load conditions, typically manufactured from ASTM F136 titanium alloy or medical-grade stainless steel through precision forging and CNC machining processes. These devices serve orthopedic surgeons in acute fracture management, reconstructive procedures, and post-traumatic deformity correction across hospital and ambulatory settings. Bone plates and intramedullary nails occupy the largest revenue share within product type segmentation due to their ubiquity in long-bone fracture fixation, while spinal implants command premium pricing through complex regulatory pathways and specialized surgeon training requirements. Minimally invasive tools and navigation systems represent the fastest-expanding technology segments as hospitals prioritize reduced soft-tissue disruption and improved placement accuracy in trauma procedures.
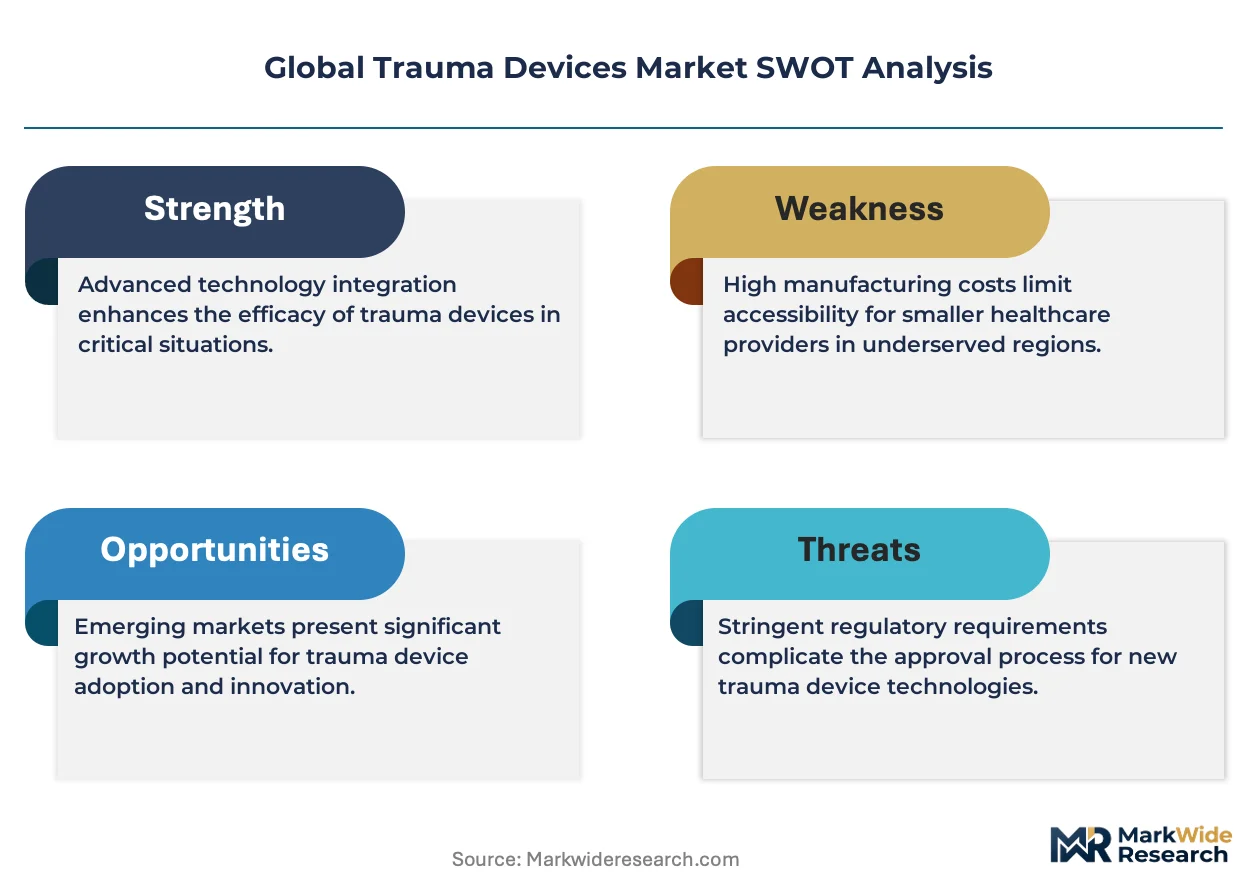
FDA 510(k) and premarket approval pathways govern commercial entry in the United States, while EMA Medical Device Regulation and CE marking requirements shape product standards across European markets, with both frameworks intensifying clinical evidence demands for permanent implantable devices. BIS certification and CDSCO oversight in India are expanding compliance scope for multinational manufacturers targeting government hospital procurement tenders. Stakeholders must monitor evolving cybersecurity requirements for connected surgical navigation platforms and assess whether biodegradable implant portfolios warrant accelerated regulatory investment ahead of standard degradation-cycle validation timelines.
Market Dynamics
Multi-source additive manufacturing partnerships are rebalancing procurement economics away from single-source titanium forging contracts, compressing supplier lead times and fragmenting incumbent margin pools across implant producers.
Growth Catalysts
- FDA 510(k) pathway compression:Accelerated clearance timelines for 3D-printed patient-specific implants are reducing time-to-market for novel fixation geometries.
- Geriatric fracture protocols:Specialized intramedullary nail designs are expanding addressable patient populations in aging demographics across Japan and Germany.
- Robotic surgery integration:Navigation systems with trauma-specific software modules are anchoring hospital capital expenditure decisions.
Market Restraints
- Titanium powder supply concentration:Captive powder metallurgy capacity at major producers limits second-source options for mid-tier manufacturers.
- EMA MDR clinical evidence escalation:Intensified documentation requirements for permanent implantable devices are extending regulatory timelines.
- Biodegradable polymer performance gaps:Degradation-cycle variability in magnesium alloys restricts load-bearing applications.
Strategic Opportunities
- India government hospital procurement:BIS certification and CDSCO oversight expansion is opening tender access for compliant multinationals.
- Cybersecurity-enabled navigation platforms:Connected surgical systems with embedded security protocols command premium positioning.
- Ambulatory surgery center channel development:Minimally invasive tool portfolios are capturing volume migration from inpatient settings.
Industry Challenges
- Surgeon training compression:Navigation system proficiency requirements outpace residency program curriculum updates.
- Legacy ERP integration friction:Connected device data streams conflict with hospital IT infrastructure protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Trauma Devices Market |
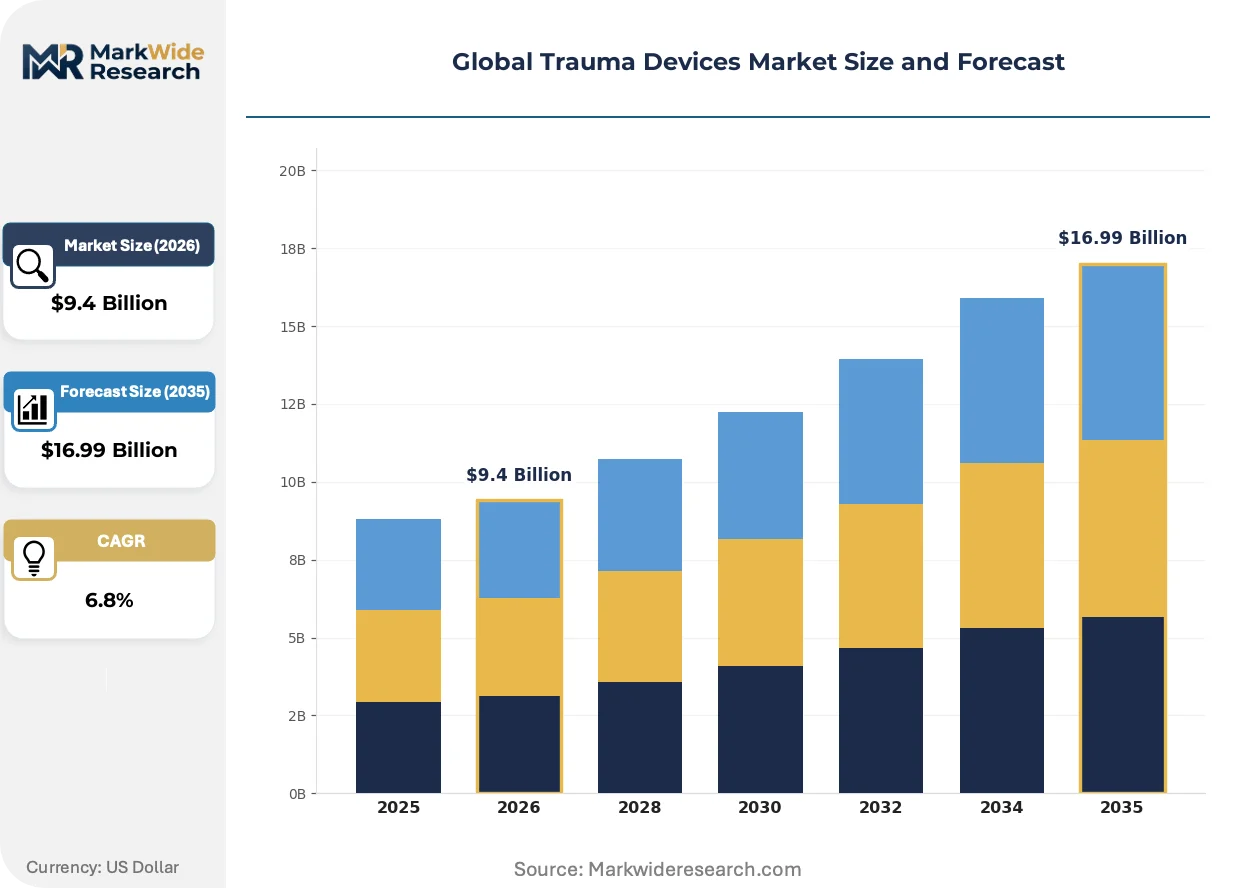
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Fixators, Intramedullary Nails, Bone Plates, Surgical Screws, Spinal Implants Application: Orthopedic Surgery, Sports Injury Repair, Accident Management, Reconstructive Surgery, Geriatric Fracture Treatment End User: Orthopedic Clinics, Trauma Centers, Ambulatory Surgical Centers, Rehabilitation Facilities, Military Medical Units Technology: Biodegradable Implants, 3D Printing, Robotic Surgery Assistance, Navigation Systems, Minimally Invasive Tools |
| Companies Covered | DePuy Synthes, Stryker Corporation, Zimmer Biomet Holdings, Inc., Smith & Nephew plc, B. Braun Melsungen AG, Medtronic plc, Orthofix Medical Inc., Acumed LLC, Arthrex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Trauma Devices Market Shifts & Advancements
Additive manufacturing is actively reshaping implant production economics. Powder bed fusion and directed energy deposition processes are compressing geometric complexity costs that previously required multi-axis CNC machining.
Patient-specific 3D-printed implants are absorbing regulatory investment previously allocated to standardized device families. Academic medical centers in Berlin and Munich are adopting these platforms at accelerated cadence. The technology is absorbing margin pressure from commoditized bone plate segments by enabling premium pricing on complex anatomical reconstructions.
EMA Medical Device Regulation enforcement is intensifying post-market surveillance obligations for permanent implants. Manufacturers must maintain clinical follow-up databases spanning multi-year degradation cycles. Trauma centers in Germany are responding by centralizing procurement through university hospital consortia to distribute compliance costs.
Hospital buying committees are consolidating vendor relationships around integrated navigation-implant portfolios. Independent distributors are losing share to direct manufacturer contracts with IDN procurement officers. This concentration is most visible in United States trauma centers expanding orthopedic surgery capacity.
Global Trauma Devices Market Segmentation
Segmentation in trauma devices reveals how regulatory burden, clinical workflow, and procurement authority fragment across product categories and care settings. Each dimension carries distinct margin profiles and certification pathways that reshape competitive positioning.
Product Type:
FDA 510(k) clearance dominates metallic fixation devices, while EMA MDR intensifies clinical evidence requirements for permanent spinal implants. Bone plates and intramedullary nails face streamlined pathways; biodegradable platforms encounter extended degradation-cycle validation.
- Bone Plates:Manufactured from ASTM F136 titanium alloy through precision forging, these devices stabilize long-bone fractures with anatomically contoured geometries. Trauma centers in the United States are expanding orthopedic surgery capacity to manage complex fracture cases, with university hospitals in Berlin and Munich building dedicated research consortia for patient-specific plate designs.
- Intramedullary Nails:Central intramedullary canal insertion provides load-sharing fixation for femoral and tibial shaft fractures. Specialized designs for geriatric fracture treatment protocols are expanding addressable patient populations in aging demographics across Japan and Germany.
- External Fixators:Pin-based external stabilization systems enable temporary fracture management and limb lengthening procedures.
- Surgical Screws:Cortical and cancellous bone screw variants provide adjunctive fixation across plating and nailing constructs.
- Spinal Implants:Complex regulatory pathways and specialized surgeon training requirements command premium pricing through restricted distribution.
Bone plates sit at the top of the volume ranking, with spinal implants climbing the fastest on premium pricing and restricted competition.
Application:
Reimbursement intensity varies sharply across application segments, with acute trauma commanding episodic payment bundles and geriatric protocols shifting toward value-based episode structures.
- Orthopedic Surgery:Acute fracture management and deformity correction procedures in hospital settings generate the largest procedure volume. Trauma centers in the United States anchor demand through 24/7 operative capacity and fellowship-trained surgeon staffing.
- Geriatric Fracture Treatment:Hip fracture protocols and fragility fracture management address the fastest-expanding patient demographic. Specialized intramedullary nail designs with enhanced rotational stability target osteoporotic bone quality in Japan's super-aged society.
- Sports Injury Repair:Ligament reconstruction and athletic trauma fixation serve younger, commercially insured populations.
- Accident Management:Polytrauma and high-energy fracture stabilization requires integrated implant and critical care coordination.
- Reconstructive Surgery:Post-traumatic deformity correction and limb salvage procedures utilize patient-specific 3D-printed implants.
Orthopedic surgery captures the dominant revenue share, with geriatric fracture treatment expanding most quickly on demographic tailwinds.
End User:
Procurement authority concentrates differently across settings: IDN central offices govern trauma center purchasing, while ambulatory surgical centers operate through GPO contracts with distinct vendor tiering.
- Trauma Centers:Level I and II designated facilities manage complex polytrauma with integrated orthopedic and general surgery teams. Hospital buying committees in the United States are consolidating vendor relationships around integrated navigation-implant portfolios.
- Ambulatory Surgical Centers:Minimally invasive tool portfolios are capturing volume migration from inpatient settings. These facilities prioritize reduced soft-tissue disruption and shorter recovery protocols for eligible fracture patterns.
- Orthopedic Clinics:Office-based fracture care and post-operative monitoring extend the care continuum.
- Rehabilitation Facilities:Post-surgical recovery and functional restoration programs coordinate with implant providers on weight-bearing protocols.
- Military Medical Units:Combat casualty care and field stabilization requirements drive ruggedized external fixation demand.
Trauma centers retain the highest implant consumption per facility, with ambulatory surgical centers gaining share fastest on procedure migration.
Technology:
Capital intensity separates technology segments: navigation systems require hospital infrastructure investment, while 3D printing shifts cost structure toward design software and regulatory dossier preparation.
- 3D Printing:Powder bed fusion processes compress geometric complexity costs for patient-specific implants. FDA clearance pathways for 3D-printed patient-specific implants are compressing time-to-market for novel fixation designs.
- Navigation Systems:Robotic surgery assistance integration anchors hospital capital expenditure decisions. Connected surgical systems with embedded security protocols command premium positioning.
- Minimally Invasive Tools:Percutaneous fixation and limited-access instrumentation reduce soft-tissue disruption.
- Biodegradable Implants:Magnesium alloy and polymer platforms face degradation-cycle variability restricting load-bearing applications.
- Robotic Surgery Assistance:Automated drill guidance and implant positioning enhance placement accuracy.
Navigation systems lead capital expenditure allocation, with 3D printing showing the steepest expansion trajectory on regulatory pathway maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospital consortia in Berlin and Munich anchor trauma device innovation clusters, while regulatory pathway maturation and aging demographics reshape procurement across North America, Europe, and Asia-Pacific.
United States
Level I trauma centers expand 24/7 orthopedic surgery capacity to manage complex polytrauma cases. FDA 510(k) pathway compression accelerates clearance timelines for novel fixation geometries. Hospital buying committees in major metropolitan markets consolidate vendor relationships around integrated navigation-implant portfolios.
Germany
University hospitals in Berlin and Munich build dedicated trauma research consortia for patient-specific 3D-printed implant designs. EMA Medical Device Regulation intensifies post-market surveillance obligations for permanent implants. Centralized procurement through hospital networks distributes compliance costs across integrated delivery systems.
Japan
Super-aged society demographics drive specialized intramedullary nail demand for osteoporotic bone quality. PMDA oversight maintains rigorous clinical evidence standards for load-bearing implants. Metropolitan Tokyo and Osaka medical centers pioneer geriatric fracture protocol standardization.
India
Government hospital procurement tenders expand access for compliant multinationals in tier-1 and tier-2 cities. BIS certification and CDSCO oversight requirements reshape import compliance scope. Maharashtra and Karnataka state health systems drive volume concentration through centralized medical device purchasing.
China
Domestic trauma center network expansion supports rising surgical procedure volumes in provincial capitals. NMPA regulatory harmonization with international standards accelerates market entry for innovative fixation platforms. Yangtze River Delta medical device manufacturing clusters scale precision forging capacity.
Global Trauma Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue patient-specific additive manufacturing niches. The vendor base stratifies across three tiers: integrated conglomerates with captive metallurgy capacity, mid-scale specialists with regional distribution depth, and technology-focused disruptors leveraging 3D printing regulatory pathways. Dominant competitive moves include multi-source additive manufacturing partnerships compressing supplier lead times, and hospital buying committee consolidation favoring integrated navigation-implant portfolios.
Among diversified orthopedic conglomerates, DePuy Synthes, Stryker Corporation, and Zimmer Biomet Holdings, Inc. exemplify distinct strategic archetypes. DePuy Synthes represents captive supply chain integration through in-house powder metallurgy capacity. Stryker Corporation anchors positioning through robotic surgery assistance integration across navigation systems. Zimmer Biomet Holdings, Inc. occupies specialization territory via geriatric-focused intramedullary nail design protocols.
| Leading Market Players |
|---|
| DePuy Synthes |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Smith & Nephew plc |
| B. Braun Melsungen AG |
| Medtronic plc |
| Orthofix Medical Inc. |
| Acumed LLC |
| Arthrex Inc. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap precision forging specialists in Germany and Japan anchor premium-tier pricing discipline through captive ASTM F136 titanium alloy processing, while private-equity-rolled-up distributors in the United States compress margin pools through consolidated GPO contracting.
Pricing Analysis
Input-cost pass-through from titanium powder and precision-forged billet suppliers drives contract renegotiation cycles across implant producers. Pricing stratifies across premium, standard, and economy tiers, with FDA 510(k) certification tier and volume scale serving as primary differentiation drivers. Cost compression in standard bone plate segments intensifies as multi-source additive manufacturing partnerships fragment incumbent margin pools. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement bundles, while Level I trauma centers prioritize placement accuracy over unit cost.
Supply Chain Analysis
Certification and qualification gating through FDA 510(k), EMA MDR, and Japan PMDA concentrates supply authority among incumbent producers with established clinical evidence databases. Manufacturing capacity clusters in Germany, Switzerland, and the United States, with precision forging and powder metallurgy operations drawing from titanium sponge feedstock sourced from Russia and Kazakhstan. Single-source vulnerability in medical-grade titanium powder supply creates exposure to export restriction risk. Distribution runs through integrated delivery network procurement offices and specialized orthopedic distributors serving hospital buying committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EMA MDR compliance costs in Germany and BIS certification pathways in India creates procurement cost differentials exceeding regulatory investment thresholds for compliant multinationals.
For Market Incumbents: Deepen captive powder metallurgy capacity to protect margin pools on complex bone plate geometries threatened by multi-source additive manufacturing partnerships. Expand robotic surgery assistance integration across navigation systems to anchor hospital capital expenditure decisions and consolidate vendor relationships. For New Entrants and Emerging Players: The premium-to-economy price-point gap in geriatric intramedullary nails offers white-space entry through specialized osteoporotic bone designs. Target ambulatory surgical center channel development with minimally invasive tool portfolios capturing volume migration from inpatient settings, leveraging direct manufacturer contracts with IDN procurement officers as the go-to-market angle. For Investors and Strategic Acquirers: Diversified orthopedic conglomerates with captive metallurgy capacity are the most active acquirer in this space, consolidating mid-scale specialists with regional distribution depth. Over a multi-year horizon, acquisition targets with FDA-cleared 3D-printed patient-specific implant platforms offer premium positioning. Watch for EMA MDR enforcement intensity as the inflection indicator for compliance cost redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Compression | Accelerated clearance timelines for 3D-printed implants reduce time-to-market for novel fixation geometries. |
| Multi-Source Additive Manufacturing Partnerships | Supplier lead time compression fragments incumbent margin pools across implant producers. |
| Robotic Surgery Assistance Integration | Navigation systems with trauma-specific software modules anchor hospital capital expenditure decisions. |
| Hospital System Partnership Consolidation | Buying committees concentrate vendor relationships around integrated navigation-implant portfolios. |
| Geriatric Fracture Protocol Specialization | Specialized intramedullary nail designs expand addressable patient populations in Japan and Germany. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baseline through post-regulatory-transition phases anchored the forecast window across the analysis window. Segmentation modeling incorporated product type, application, end user, and technology dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from procedure volume elasticity to demographic shifts and capital expenditure cycles for navigation systems.
Caveats apply where EMA MDR clinical evidence escalation or biodegradable polymer performance gaps could materially shift the outlook. Forecasts reflect assumptions regarding regulatory pathway maturation and surgeon training compression rates. A model refresh is warranted upon material change in FDA clearance timeline compression or titanium powder supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Bone Cement Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Education Microscope Market
Medical Devices
Spinal Implant Market
Medical Devices
Global Concussion Market
Medical Devices
Bone Growth Stimulators Market
Medical Devices
Europe Breast Implant Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Extremity Reconstruction Market
Medical Devices
Low Vision Aids Market
Medical Devices
Sleep Apnea Implants Market