
 Global Electrotherapy System Market | 2026-2036
Global Electrotherapy System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrotherapy System Market Foresight
Germany is reshaping European electrotherapy manufacturing through expanded cleanroom assembly capacity in the Baden-Württemberg medical technology corridor. Medtronic Plc leverages its Dublin operational base to sustain regulatory dossier throughput across EMA member states. DJO Global anchors North American distribution through direct-to-clinic logistics networks. Boston Scientific Corporation specializes in implantable neurostimulation platforms that differentiate from surface-based competitors.
An electrotherapy system delivers controlled electrical impulses through electrodes to modulate nerve activity, stimulate muscle contraction, or promote tissue repair, typically operating at frequencies between 1-150 Hz with pulse widths of 50-400 microseconds for transcutaneous applications. These systems serve clinical rehabilitation, chronic pain management, and dermatological aesthetic procedures across institutional and home settings. Transcutaneous Electrical Nerve Stimulation occupies the largest revenue pool due to broad reimbursement coverage, while wearable technology represents the fastest-expanding deployment category as miniaturized power management enables continuous ambulatory therapy. Home Healthcare leads end-user growth as payors in multiple geographies shift postoperative recovery costs from inpatient facilities to patient-managed settings.
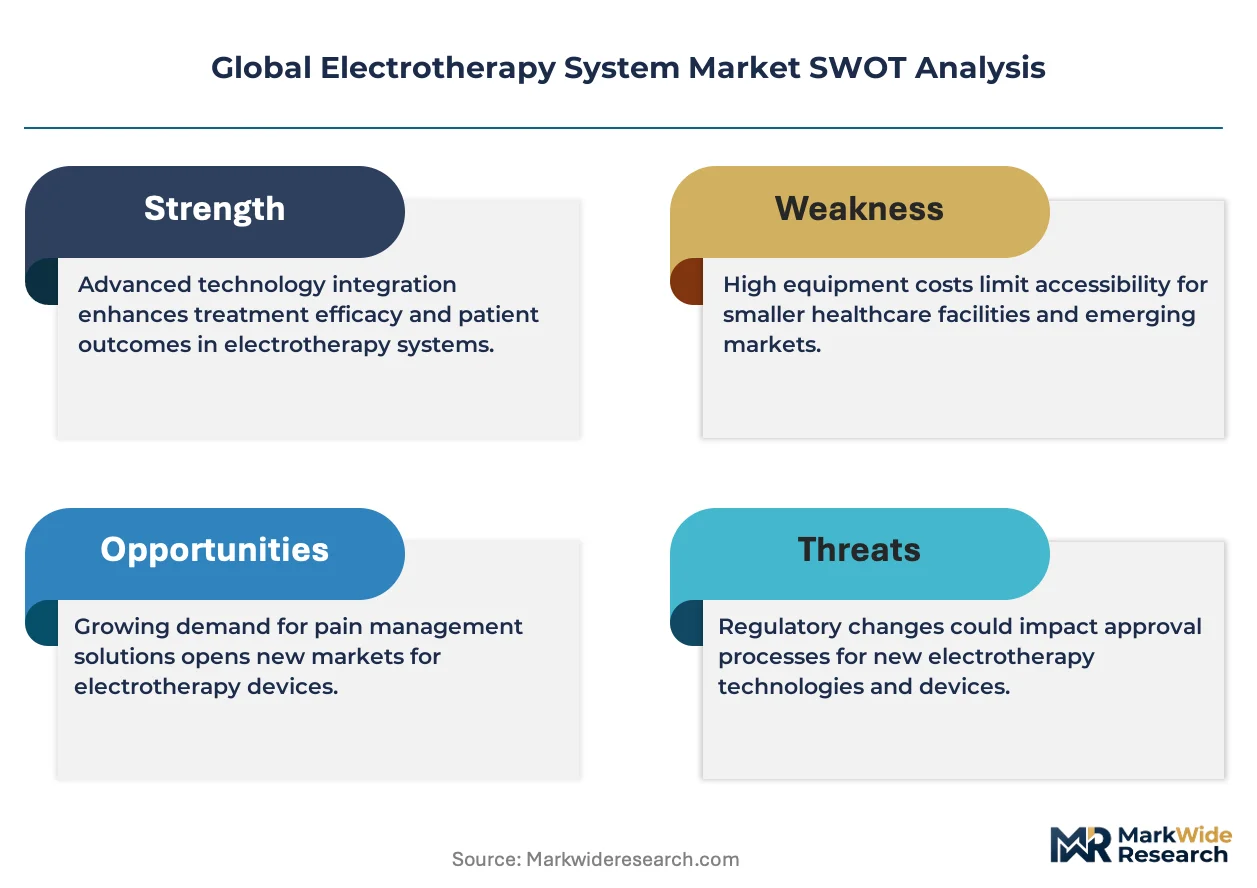
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) impose biocompatibility and electrical safety testing burdens that filter smaller manufacturers from commercialization pathways. EMA vigilance reporting and ISO 13485 quality management standards further constrain market entry for non-compliant suppliers. Stakeholders must monitor evolving MDR notified body capacity bottlenecks and FDA breakthrough device designation trends to calibrate regulatory investment timelines against portfolio expansion priorities.
Market Dynamics
Portable electrotherapy devices are collapsing the traditional boundary between institutional rehabilitation settings and patient-managed home recovery, forcing manufacturers to redesign power management architectures and electrode interfaces for unsupervised use.
Growth Catalysts
- Japan METI reimbursement expansion:Portable TENS units now qualify for home healthcare subsidies under revised long-term care insurance frameworks, accelerating patient-managed deployment.
- Neuromuscular electrical stimulation protocols:Postoperative rehabilitation centers in Germany are integrating these systems into standardized recovery pathways for orthopedic and cardiac procedures.
- Wearable miniaturization:Advances in flexible printed circuit boards and micro-battery chemistry enable continuous ambulatory therapy without tethered power sources.
Market Restraints
- EU MDR notified body congestion:Extended certification timelines for Class IIa electrotherapy devices delay commercialization for manufacturers lacking prior MDD certificates.
- Silver-silver chloride electrode cost volatility:Precious metal price swings compress margins for disposable consumable suppliers.
- Implantable neurostimulation substitution:Boston Scientific and Medtronic surface-based competitors face patient migration toward spinal cord stimulators for refractory chronic pain.
Strategic Opportunities
- India home healthcare penetration:CDSCO streamlined medical device registration creates first-mover advantage for portable TENS manufacturers targeting tier-2 city physiotherapy practices.
- AI-driven adaptive dosing:Machine learning algorithms that adjust pulse parameters in real-time converge with cloud-connected wearable hardware.
- Direct-to-patient subscription channels:Bypassing clinic procurement through telehealth-integrated e-commerce platforms captures recurring electrode revenue.
Industry Challenges
- Biomedical engineer talent scarcity:Specialized expertise in neurophysiology-electronics interface design concentrates in Boston and Basel metropolitan clusters.
- ISO 13485 quality system capex:Small manufacturers face six-figure investments in document control and risk management infrastructure to maintain EMA vigilance compliance.
- Legacy hospital IT integration:Home-use devices must interface with Epic and Cerner electronic health record systems for reimbursement validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrotherapy System Market |
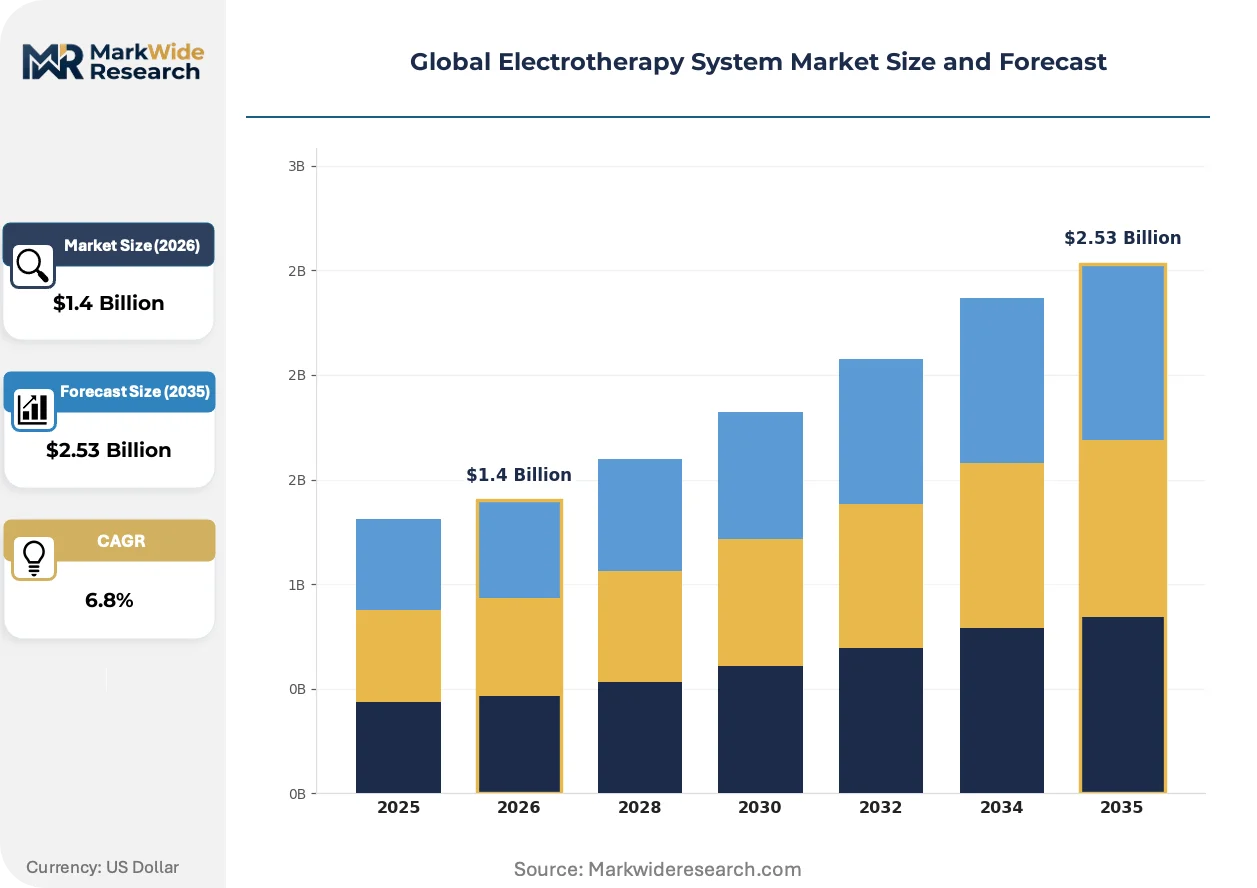
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcutaneous Electrical Nerve Stimulation, Interferential Therapy, Neuromuscular Electrical Stimulation, Microcurrent Therapy, Others Therapy Area: Musculoskeletal Pain, Neurological Disorders, Dermatology Treatments, Sports Injury Rehab, Postoperative Recovery End User: Rehabilitation Centers, Physiotherapy Clinics, Home Healthcare, Sports Medicine Facilities, Pain Management Centers Deployment: Portable Devices, Stationary Units, Wearable Technology, Clinic-Based Systems, Battery Operated |
| Companies Covered | Medtronic Plc, Zynex Medical, DJO Global, Nevro Corporation, BTL Industries, Omron Corporation, Boston Scientific Corporation, Enovis, Cionic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrotherapy System Market Shifts & Advancements
Electrotherapy hardware is undergoing fundamental architectural transformation as semiconductor efficiency gains and regulatory pathway innovations simultaneously reshape product development cycles and commercial access models.
Printed electronics is collapsing the form factor constraints that historically separated clinical-grade from consumer-grade devices. Flexible substrate manufacturing enables electrode arrays that conform to joint topography for targeted neuromuscular activation. Physiotherapy clinics in the Netherlands and Sweden are piloting these systems for sports rehabilitation, compressing the equipment cost differential between hospital and home settings from an order of magnitude to roughly two-fold.
MDR Article 120 transitional provisions are compressing regulatory runway for legacy device manufacturers. The European Commission's 2024 deadline extensions for certain Class IIa devices have triggered accelerated technical documentation remediation across electrotherapy portfolios. German and Irish manufacturers with established quality management systems are absorbing notified body capacity while smaller competitors face market exit pressures.
Clinician purchasing committees are fragmenting procurement authority across hospital value analysis teams, outpatient surgery center administrators, and home health agency supply chains. Traditional distributor relationships with exclusive territory arrangements are yielding to multi-channel sourcing strategies. This pattern is most visible in the United States, where Group Purchasing Organization consolidation intersects with Medicare Advantage plan direct contracting for post-acute durable medical equipment.
Global Electrotherapy System Market Segmentation
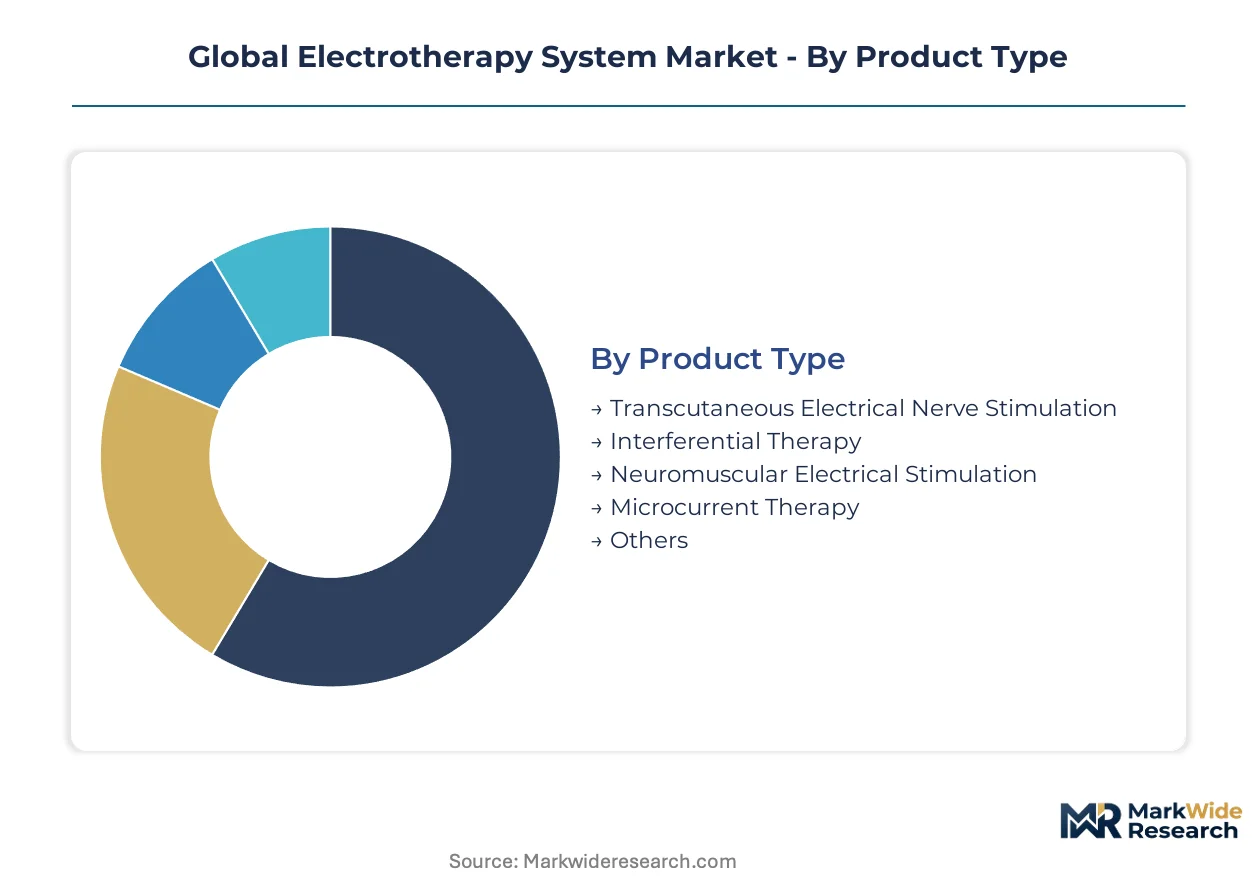
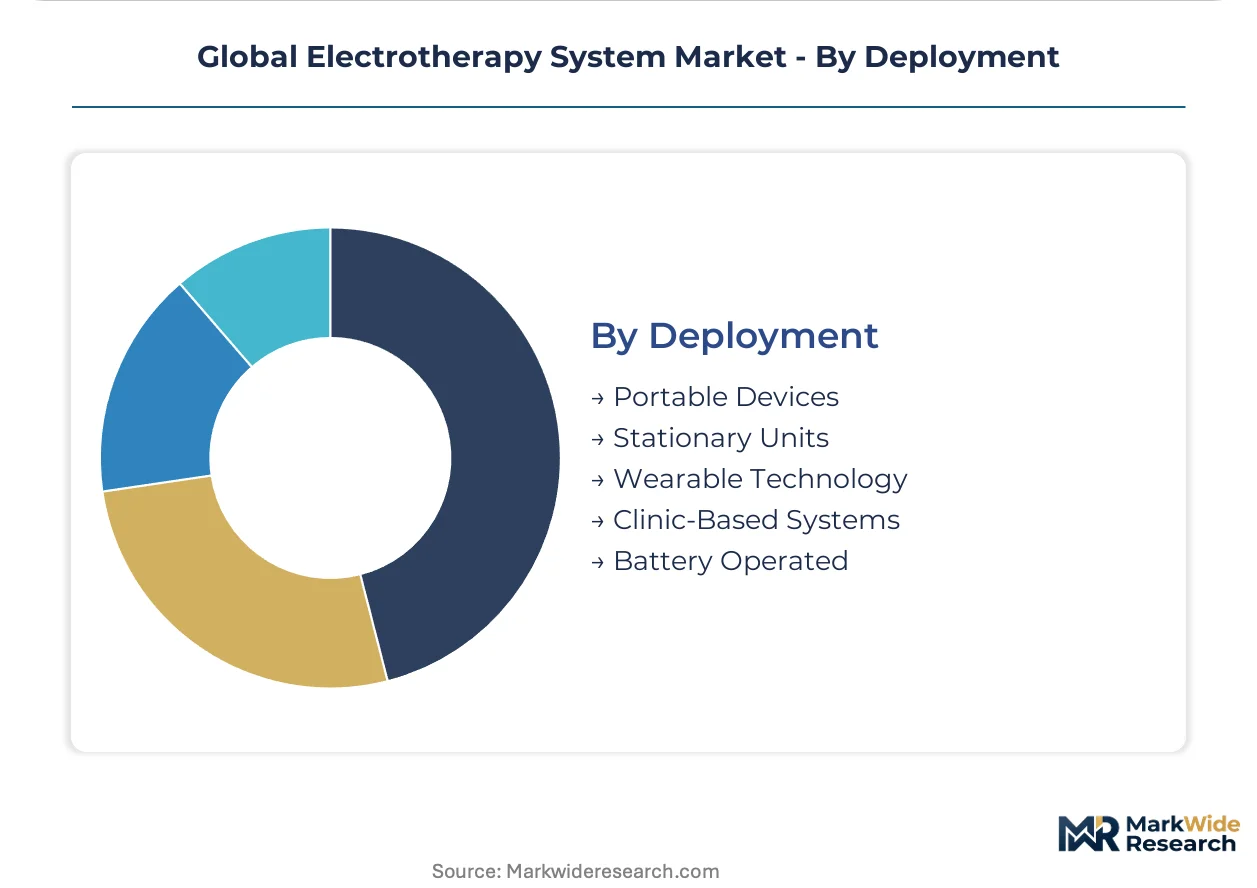
Segmentation in electrotherapy systems reveals divergent service intensity requirements across product architectures. Portable and wearable deployments demand continuous electrode replenishment and remote patient monitoring support, while stationary clinic systems rely on preventive maintenance contracts and software upgrade cycles.
Product Type:
After-sales-service intensity varies sharply across electrical stimulation modalities, with consumable-dependent segments requiring electrode subscription logistics and calibration-dependent platforms needing field engineering networks.
- Transcutaneous Electrical Nerve Stimulation:Surface electrode systems delivering 1-150 Hz pulses through conductive gel pads for nociceptive pain modulation. Demand concentrates in Japanese home healthcare channels where METI reimbursement subsidies offset out-of-pocket electrode costs for elderly patients managing chronic lower back conditions.
- Neuromuscular Electrical Stimulation:Higher-amplitude protocols triggering skeletal muscle contraction for strength preservation and edema reduction. German orthopedic rehabilitation centers in Baden-Württemberg are standardizing these systems into post-total-knee-arthroplasty pathways, driving bundled device-consumable procurement contracts.
- Interferential Therapy:Cross-interference of medium-frequency currents penetrating deeper tissue layers than conventional TENS.
- Microcurrent Therapy:Sub-sensory amplitude applications for wound healing and dermatological collagen stimulation.
- Others:Emerging modalities including cranial electrotherapy stimulation and interferential variants for pelvic floor rehabilitation.
By volume, Transcutaneous Electrical Nerve Stimulation leads. By growth pace, Neuromuscular Electrical Stimulation is ahead.
Therapy Area:
Application-specific regulatory pathways create divergent margin profiles across clinical indications, with aesthetic dermatology commanding premium pricing and postoperative recovery facing bundled reimbursement pressure.
- Musculoskeletal Pain:Lumbar, cervical, and extremity applications targeting osteoarthritis and myofascial dysfunction. Physiotherapy clinics in the Netherlands prioritize multi-channel TENS configurations for sports-related shoulder and knee presentations, integrating surface electromyography feedback for treatment personalization.
- Postoperative Recovery:Early mobilization protocols reducing opioid dependency following joint replacement and cardiac procedures. German hospital value analysis committees are mandating neuromuscular electrical stimulation inclusion in enhanced recovery after surgery bundles for total hip arthroplasty, standardizing device selection across purchasing networks.
- Sports Injury Rehab:Acute phase edema control and return-to-play strength conditioning for athletic populations.
- Neurological Disorders:Spasticity management and motor relearning applications in stroke and multiple sclerosis populations.
- Dermatology Treatments:Aesthetic microcurrent and electroporation applications in medical spa and cosmetic surgery settings.
By patient volume, Musculoskeletal Pain dominates. By margin expansion, Postoperative Recovery is climbing the fastest.
End User:
Customer-type concentration shapes channel economics, with institutional buyers leveraging group purchasing leverage and home healthcare segments requiring direct-to-patient logistics infrastructure.
- Home Healthcare:Patient-managed or caregiver-supervised deployment outside institutional settings. Japan's long-term care insurance expansion is accelerating portable TENS penetration among community-dwelling elderly, with municipal care managers coordinating device procurement and electrode resupply through regional pharmacy networks.
- Rehabilitation Centers:Multi-disciplinary facilities integrating physical therapy, occupational therapy, and speech pathology services. These centers in India's tier-2 cities are adopting entry-level interferential units as CDSCO streamlined registration reduces import lead times for European and Chinese manufacturers.
- Physiotherapy Clinics:Outpatient musculoskeletal practices with high patient throughput and equipment utilization rates.
- Pain Management Centers:Anesthesiologist-led interventional practices combining electrotherapy with injection-based modalities.
- Sports Medicine Facilities:Team-affiliated and independent practices serving competitive and recreational athletes.
By installed base, Rehabilitation Centers lead. By expansion trajectory, Home Healthcare is gaining share fastest.
Deployment:
Form-factor decisions determine power architecture, regulatory classification, and reimbursement eligibility, with battery chemistry and wireless connectivity emerging as critical design variables.
- Wearable Technology:Garment-integrated or adhesive-patch systems enabling continuous ambulatory therapy without activity restriction. Advances in flexible printed circuit substrates and solid-state micro-batteries are enabling 24-hour wear protocols for chronic pain populations in Sweden and the Netherlands, with cloud-connected dose tracking satisfying payer documentation requirements.
- Portable Devices:Handheld or belt-clip units bridging clinical and home settings with programmable parameter libraries. FDA 510(k) clearance timelines for these devices are compressing as the agency accumulates predicate familiarity, accelerating time-to-market for manufacturers with established quality management systems.
- Stationary Units:Cart-based or wall-mounted systems for fixed installation in clinical environments.
- Clinic-Based Systems:Multi-channel platforms with integrated patient data management and billing integration.
- Battery Operated:Discrete power-source category spanning alkaline, lithium-ion, and rechargeable configurations.
By shipment volume, Portable Devices lead. By technology investment intensity, Wearable Technology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics corridor underwrites Benelux distribution efficiency for electrotherapy manufacturers serving northwestern European rehabilitation networks.
United States
Medicare Advantage direct contracting for post-acute durable medical equipment accelerates home healthcare deployment of portable TENS units. FDA 510(k) clearance pathway compression reduces time-to-market for predicate-established wearable devices. The Minneapolis medical technology cluster anchors neuromuscular electrical stimulation R&D through institutional partnerships with orthopedic surgery networks.
Germany
Baden-Württemberg's medical technology corridor expands cleanroom assembly capacity for surface electrode manufacturing. EU MDR notified body capacity absorption by established quality management system holders filters smaller competitors from commercialization pathways. Stuttgart-based physiotherapy equipment networks standardize neuromuscular electrical stimulation into enhanced recovery after surgery bundles for total joint replacement.
Japan
Long-term care insurance subsidy expansion for portable TENS units drives patient-managed deployment among community-dwelling elderly populations. METI reimbursement frameworks favor home healthcare over institutional rehabilitation for chronic pain management. The Osaka-Kobe medical device manufacturing belt concentrates wearable electrotherapy production for domestic and Southeast Asian export markets.
India
CDSCO streamlined medical device registration creates first-mover positioning for European and Chinese portable TENS manufacturers. Tier-2 city physiotherapy practices adopt entry-level interferential units as import lead times compress. The Maharashtra pharmaceutical and medical device corridor near Mumbai anchors distribution infrastructure for western and southern Indian rehabilitation center networks.
Netherlands
Rotterdam-Europoort cold chain logistics enable electrode consumable replenishment cycles across Nordic and Baltic rehabilitation markets. Dutch physiotherapy clinics pilot flexible printed circuit electrode arrays for sports rehabilitation applications. The Eindhoven high-tech systems cluster supplies micro-battery and flexible substrate components to wearable electrotherapy device assemblers.
Global Electrotherapy System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying electrodes, power management modules, and flexible substrate assemblies. The vendor base stratifies across three tiers: multinational medical technology conglomerates with neurostimulation portfolios, mid-cap rehabilitation equipment specialists, and emerging wearable technology entrants. Strategic archetypes include implantable neurostimulation platform holders, surface-based electrotherapy system providers, and consumable-dependent electrode suppliers. Dominant competitive moves encompass M&A absorption of wearable technology startups and backward integration into flexible printed circuit manufacturing.
Within the implantable platform tier, Medtronic Plc and Boston Scientific Corporation occupy positions exemplifying neurostimulation-to-surface competitive tension. Among surface-based specialists, DJO Global anchors North American distribution architecture through direct-to-clinic logistics networks. Zynex Medical represents the emerging wearable electrotherapy archetype with cloud-connected device platforms targeting patient-managed chronic pain segments.
| Leading Market Players |
|---|
| Medtronic Plc |
| Zynex Medical |
| DJO Global |
| Nevro Corporation |
| BTL Industries |
| Omron Corporation |
| Boston Scientific Corporation |
| Enovis |
| Cionic |
| Others |
Supply & Pricing Matrix
Silver-silver chloride electrode manufacturing concentrates in Chinese and German chemical processing corridors, anchoring margin pools in consumable subscription tiers rather than device hardware. Portable TENS unit assemblers face margin compression when precious metal price volatility feeds through to disposable electrode costs, while wearable device makers capture recurring revenue through cloud-connected dosing platforms.
Pricing Analysis
FDA 510(k) clearance tiers and EU MDR conformity assessment levels dictate the pricing structure across premium clinical-grade, standard institutional, and economy direct-to-patient segments. Price differentiation hinges on ISO 13485 certification status and wireless connectivity integration, with cloud-enabled wearables commanding subscription premiums. Pricing pressure intensifies in the electrode consumable tier as silver price volatility compresses disposable supplier margins. Home healthcare buyers exhibit highest price sensitivity, while pain management centers prioritize clinical efficacy over unit economics.
Supply Chain Analysis
Export control restrictions on advanced flexible printed circuit substrate technology limit flows from Dutch and Japanese suppliers to Chinese assemblers, fragmenting component sourcing strategies. Supply concentrates in China for lithium-ion micro-batteries, Germany for precision electrode fabrication, and Japan for wearable sensor modules. Raw material dependencies span silver-silver chloride pastes, polyimide flexible substrates, and solid-state battery electrolytes. Single-source vulnerability in advanced micro-battery chemistry creates procurement risk for 24-hour wearable protocols. Distribution runs through Rotterdam-Europoort cold chain logistics for electrode replenishment cycles across Nordic rehabilitation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrotherapy systems sit in early-cycle expansion as home healthcare reimbursement frameworks in Japan and Germany accelerate patient-managed deployment ahead of clinical setting saturation. Wearable miniaturization and cloud connectivity are compressing the traditional boundary between prescription medical devices and consumer wellness products.
For Market Incumbents: Build regulatory dossier depth as the primary moat against emerging wearable entrants. Accelerate backward integration into flexible printed circuit electrode manufacturing to capture consumable margin pools currently leaking to Asian component suppliers. Absorb notified body capacity through established EU MDR quality management systems before 2024 transitional deadlines filter smaller competitors from certification pathways. Counter implantable neurostimulation substitution threat by embedding surface-based systems into enhanced recovery after surgery bundles.
For New Entrants and Emerging Players: India's tier-2 city physiotherapy practices represent the most penetrable geographic white-space as CDSCO streamlined registration collapses import lead times. Target direct-to-patient subscription channels bypassing clinic procurement committees, capturing recurring electrode revenue through telehealth-integrated e-commerce platforms. Lead with AI-driven adaptive dosing algorithms that adjust pulse parameters in real-time, differentiating from legacy programmable libraries.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap rehabilitation equipment specialists with established GPO contracts and cloud-connected wearable pipelines. Long-term viability across the five-to-ten year window favors platforms integrating hardware, software, and consumable logistics rather than pure device manufacturers. Monitor FDA breakthrough device designation trends as the inflection signal for regulatory pathway compression accelerating time-to-market for predicate-established portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body capacity absorption filters smaller competitors from commercialization pathways. |
| Hospital System Partnership | Enhanced recovery after surgery bundle integration locks in neuromuscular electrical stimulation procurement. |
| Software Companion Development | Cloud-connected dose tracking satisfies Japanese METI reimbursement documentation requirements. |
| Reimbursement Strategy | Medicare Advantage direct contracting accelerates home healthcare TENS deployment in the United States. |
| Backward Integration into Electrodes | In-house silver-silver chloride manufacturing insulates margin pools from precious metal price volatility. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and physiotherapy clinic operators and refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including FDA 510(k) clearance databases, EMA vigilance reports, Japanese METI reimbursement bulletins, and CDSCO medical device registration filings. Bottom-up sizing of electrode consumable volumes and top-down cross-checks against device shipment data established analytical triangulation.
Demand-supply balance modeling across the projection horizon anchored forecast outputs. Segmentation dimensions spanned electrical stimulation modality, therapy area application, end-user facility type, and deployment form-factor architecture. CAGRs were derived from trend extrapolation of reimbursement expansion trajectories and wearable technology adoption curves. Industry-specific inputs included silver price volatility indices and notified body capacity utilization rates.
Practitioners should monitor FDA breakthrough device designation velocity and EU MDR transitional provision deadline extensions for early signals of regulatory pathway compression. Forecasts reflect assumptions of continued METI reimbursement expansion and stable silver-silver chloride supply chains. Material shifts in implantable neurostimulation efficacy data or precious metal commodity spikes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Footwear Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Ablation Devices Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
Thoracolumbar Stabilization Devices Market