
 Global Tracheostomy Products Market | 2026-2036
Global Tracheostomy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tracheostomy Products Market Foresight
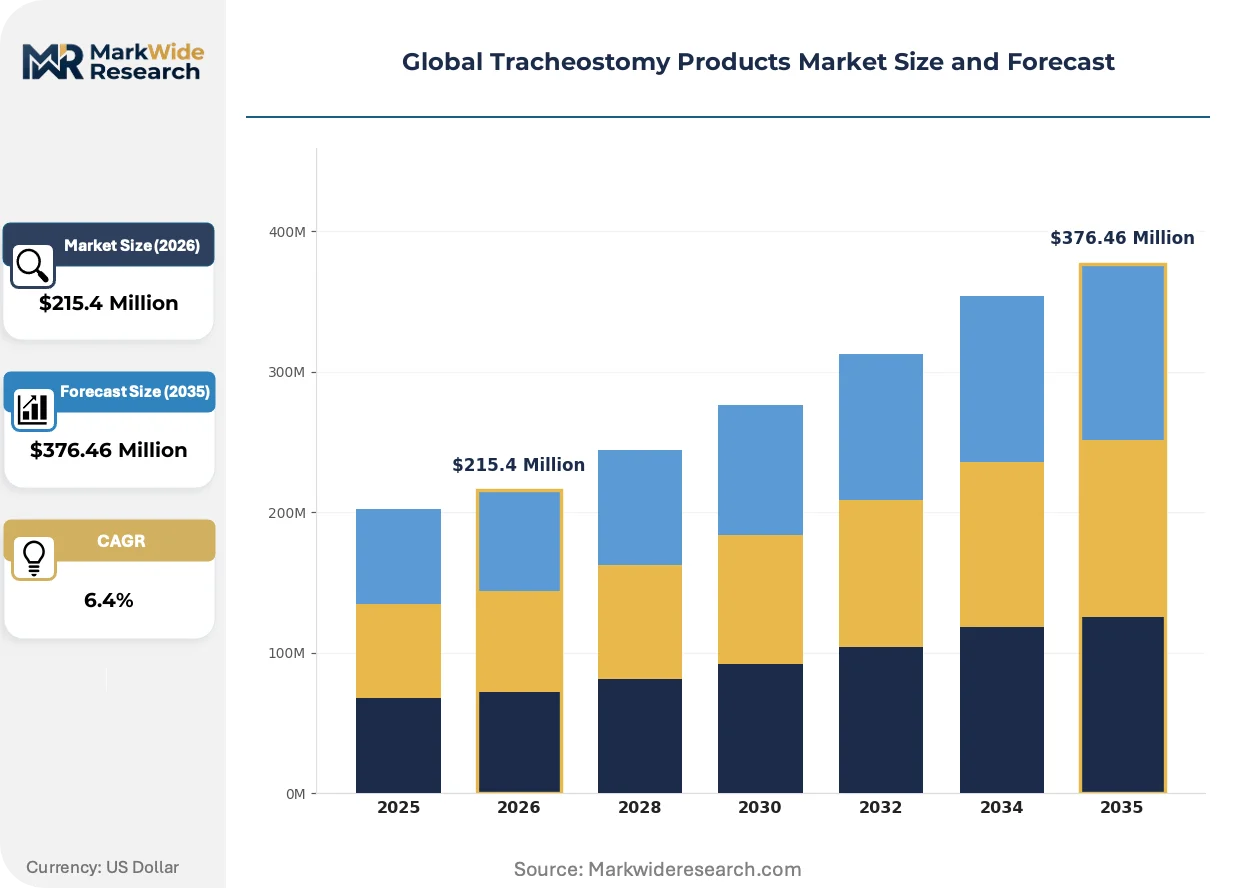
Home care settings is redrawing demand patterns for tracheostomy products as patients and payors push airway management beyond hospital walls. Medtronic leverages its interventional portfolio breadth to sustain institutional contracts across acute and post-acute channels. Smiths Group plc anchors European supply through TRACOE Medical GmbH, which specializes in custom-fit silicone tube designs for pediatric and long-term users. Fisher & Paykel Healthcare Limited dominates humidification-adjacent tracheostomy accessories in Asia-Pacific markets.
Tracheostomy products encompass tubes, cannulas, valves, and fixation devices engineered from silicone, polyvinyl chloride, or semi-rigid polymers to secure artificial airways and enable mechanical ventilation or phonation. These devices must meet biocompatibility ISO 10993 standards, tensile strength specifications for cuff retention, and dimensional tolerances for stoma fit to ensure patient safety across weeks or years of implantation. Tracheostomy tubes in silicone lead material preference due to superior tissue tolerance and extended dwell times, while speaking valves represent the fastest-growing functional segment as ambulatory voice restoration gains clinical priority. Application demand tilts toward long-term respiratory support where margin pools deepen through recurring cannula and filter replacement cycles.
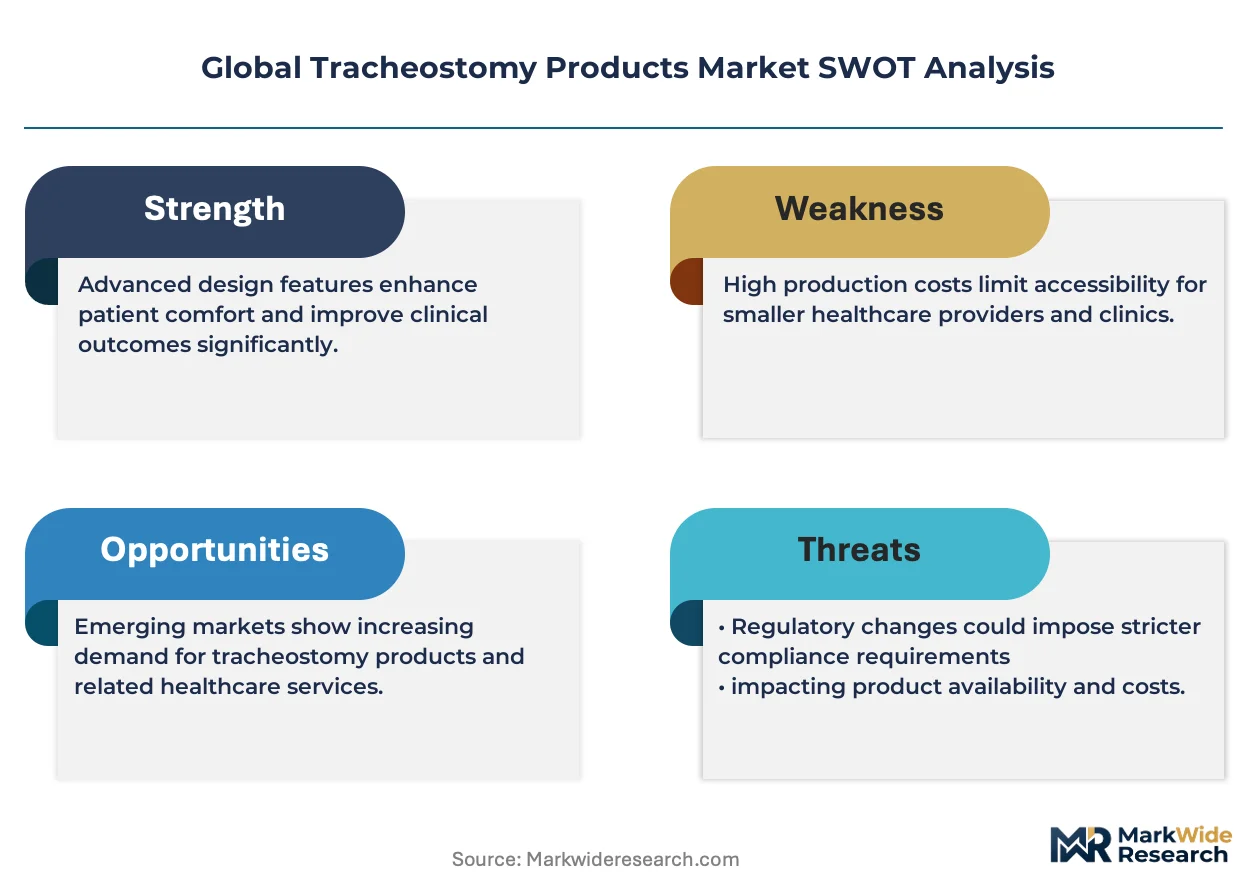
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and market access costs for tracheostomy device manufacturers. ISO 14155 clinical investigation standards and WHO airway safety protocols further constrain design validation and post-market surveillance obligations across major jurisdictions. Stakeholders must monitor evolving home care reimbursement codes and silicone raw material supply concentration to calibrate portfolio and pricing strategies.
Market Dynamics
Home care migration is compressing hospital procurement cycles while extending patient dwell times on tracheostomy devices, forcing manufacturers to reconfigure service models around direct-to-patient logistics and remote monitoring integration rather than institutional contracting alone.
Growth Catalysts
- Silicone material advances:Extended biocompatibility dwell times enable multi-year implantation without tube replacement, reducing surgical revision burden and total cost of care for long-term ventilator-dependent patients.
- Medicare home health reimbursement expansion:US CMS coding updates now cover tracheostomy supply kits for qualified homebound beneficiaries, accelerating discharge planning and durable medical equipment channel development.
- Speaking valve functional prioritization:Ambulatory voice restoration protocols in post-ICU rehabilitation centers drive demand for phonation-enabled cannula systems that integrate with mechanical ventilation circuits.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone polymer supply clusters in Northeast Asian chemical manufacturing zones, exposing device makers to freight volatility and customs processing delays.
- EU MDR conformity assessment backlog:Notified body capacity constraints extend technical documentation review timelines for tracheostomy tube re-certifications, freezing product line extensions.
- Tracheal stenosis complication rates:Cuff pressure management failures in polyvinyl chloride tubes drive substitution toward silicone alternatives, compressing margin on legacy PVC product lines.
Strategic Opportunities
- Pediatric custom-fit segmentation:Germany's TRACOE Medical GmbH demonstrates scalable production of anatomically matched neonatal tubes, opening specialty manufacturing models for rare disease airway anomalies.
- Remote monitoring convergence:Integration of cuff pressure sensors with cloud-based respiratory analytics platforms enables predictive intervention before adverse events trigger emergency department visits.
- Japan's aging-in-place policy mandate:METI-directed home medical equipment subsidies for tracheostomy-dependent elderly patients create reimbursement-aligned demand for portable humidification and suction systems.
Industry Challenges
- ISO 14155 clinical investigation execution:Multi-site airway safety trials require specialized otolaryngology investigators, creating recruitment bottlenecks that delay 510(k) and MDR submission timelines.
- Legacy hospital inventory system integration:Home care distributors must reconcile lot tracking and expiration management across fragmented electronic health record platforms that lack standardized device identifiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tracheostomy Products Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $376.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracheostomy Tubes, Speaking Valves, Cuffed Cannulas, Tube Holders Application: Long-Term Respiratory Support, Acute Airway Management, Emergency Care, Postoperative Care End User: Specialty Clinics, Home Care Settings, Rehabilitation Centers, Surgical Units Technology: Semi-Rigid Materials, Silicone, Polyvinyl Chloride, Custom Fit Designs |
| Companies Covered | Medtronic, Smiths Group plc, Teleflex Incorporated, TRACOE Medical GmbH, Cook Group, ConvaTec Group plc, Fisher & Paykel Healthcare Limited, Boston Medical Products Inc., Pulmodyne, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tracheostomy Products Market Shifts & Advancements
Tracheostomy product development is pivoting from acute-care durability specifications toward ambulatory comfort and voice functionality, with material science and regulatory harmonization serving as the primary vectors of competitive differentiation.
Antimicrobial silicone compounding is fragmenting traditional tube material hierarchies. Silver-ion and chlorhexidine-integrated silicone formulations reduce biofilm colonization in long-term indwelling applications. Home care nurses and respiratory therapists in the United States are adopting these coated tubes for ventilator-dependent patients with recurrent pneumonia histories. The technology is fragmenting procurement decisions away from pure cost-per-unit metrics toward total infection-cost avoidance models that favor premium material specifications.
EU MDR Article 117 device-drug combination rules are reclassifying antimicrobial-coated tracheostomy tubes as higher-risk devices requiring notified body involvement. Manufacturers must now submit clinical data on coating elution profiles and local tissue tolerance. German and French hospital purchasing consortia are consolidating supplier lists to favor MDR-ready portfolios, squeezing smaller tube makers without dedicated regulatory affairs capacity.
Direct-to-patient subscription models are displacing durable medical equipment dealer intermediaries in US tracheostomy supply distribution. Patients or caregivers order replacement cannulas, filters, and speaking valves through manufacturer portals with automated insurance pre-authorization. This channel compression is most visible in California and Texas, where large home health agencies have negotiated preferred supplier status with vertically integrated device makers.
Global Tracheostomy Products Market Segmentation
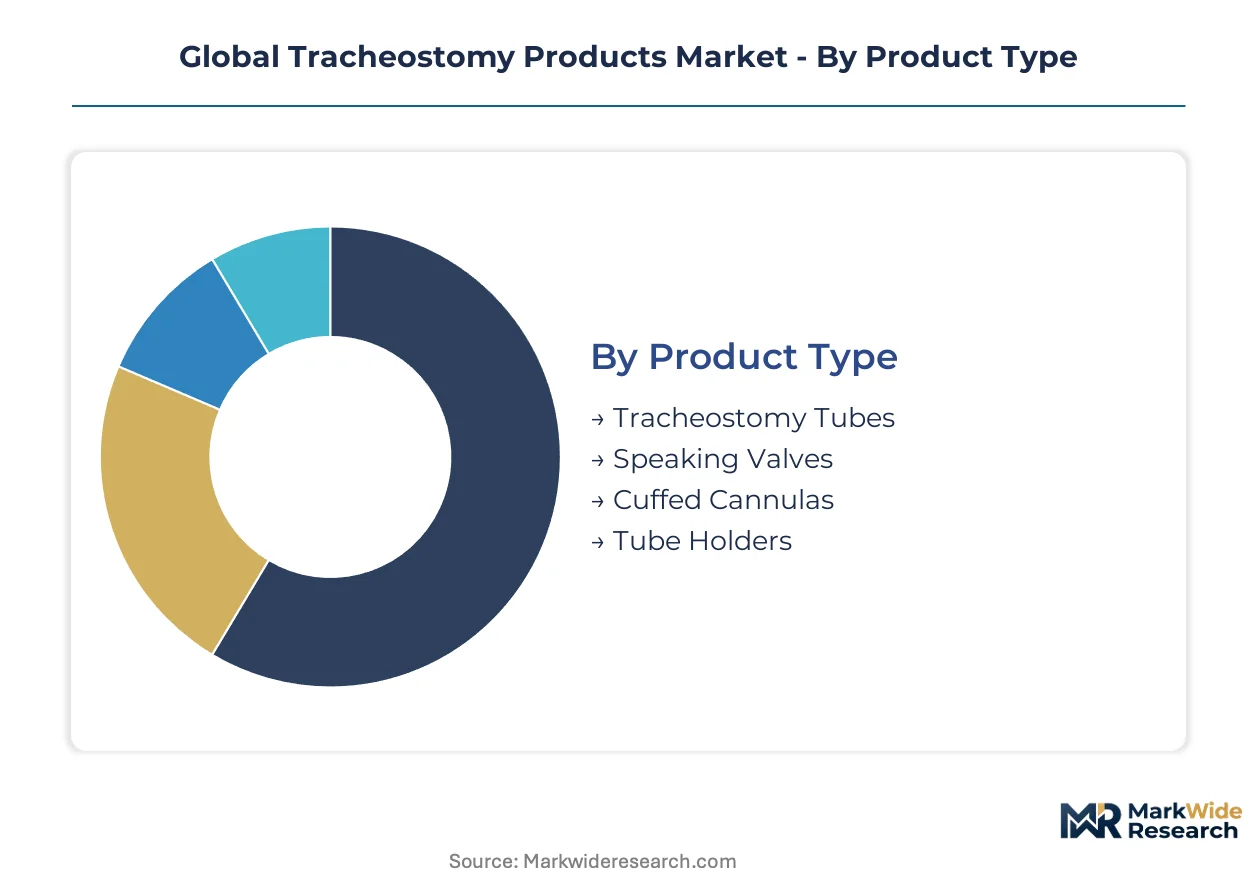
Tracheostomy product segmentation reflects divergent regulatory pathways and reimbursement logic across material technologies and care settings. Manufacturers calibrate portfolio depth against ISO 10993 biocompatibility tiers and jurisdiction-specific home health coding to capture margin pools.
Product Type:
FDA 510(k) clearance complexity varies sharply by functional category, with speaking valves requiring supplemental phonation efficacy data that tubes and holders bypass.
- Tracheostomy Tubes:Silicone and PVC constructions dominate institutional procurement, with cuff retention specifications dictating ISO 14155 validation scope. Demand concentrates in German and Japanese long-term ventilation programs where extended dwell times favor biocompatible silicone formulations over polymer alternatives.
- Speaking Valves:One-way valve mechanisms integrate with mechanical ventilation circuits to restore phonation during ambulatory recovery. Post-ICU rehabilitation centers in the United States drive fastest adoption as voice restoration protocols expand beyond academic medical centers.
- Cuffed Cannulas:Inflatable seal designs prevent aspiration in ventilator-dependent patients.
- Tube Holders:Stabilization devices secure tracheostomy placement during patient mobility.
Established volume favors Tracheostomy Tubes; emerging adoption favors Speaking Valves.
Application:
Reimbursement intensity separates acute episodes from chronic management, with Medicare home health benefits reshaping demand concentration toward sustained respiratory support.
- Long-Term Respiratory Support:Multi-year ventilator dependence in home settings generates recurring revenue through scheduled cannula and filter replacement cycles. US CMS coverage expansion and Japan's METI aging-in-place subsidies concentrate demand in reimbursed domiciliary care.
- Acute Airway Management:Emergency intubation and perioperative stabilization in hospital settings prioritize rapid deployment and standardized sizing over customization.
- Emergency Care:Pre-hospital and trauma applications require rapid-insertion designs.
- Postoperative Care:Surgical recovery units manage temporary tracheostomy weaning protocols.
Margin depth concentrates in Long-Term Respiratory Support; procedural volume concentrates in Acute Airway Management.
End User:
Channel configuration diverges between institutional procurement consortia and direct-to-patient logistics platforms, with inventory management systems dictating manufacturer service model selection.
- Home Care Settings:Domiciliary providers manage ventilator-dependent patients through durable medical equipment channels with automated resupply scheduling. California and Texas home health agencies negotiate preferred supplier status with vertically integrated device makers.
- Specialty Clinics:Otolaryngology and pulmonology practices handle complex airway anomalies and custom-fit requirements.
- Rehabilitation Centers:Post-acute facilities prioritize speaking valve integration for voice restoration therapy.
- Surgical Units:Operating rooms and ICUs source standardized tubes through hospital group purchasing organizations.
Service complexity escalates toward Home Care Settings; standardization dominates Surgical Units.
Technology:
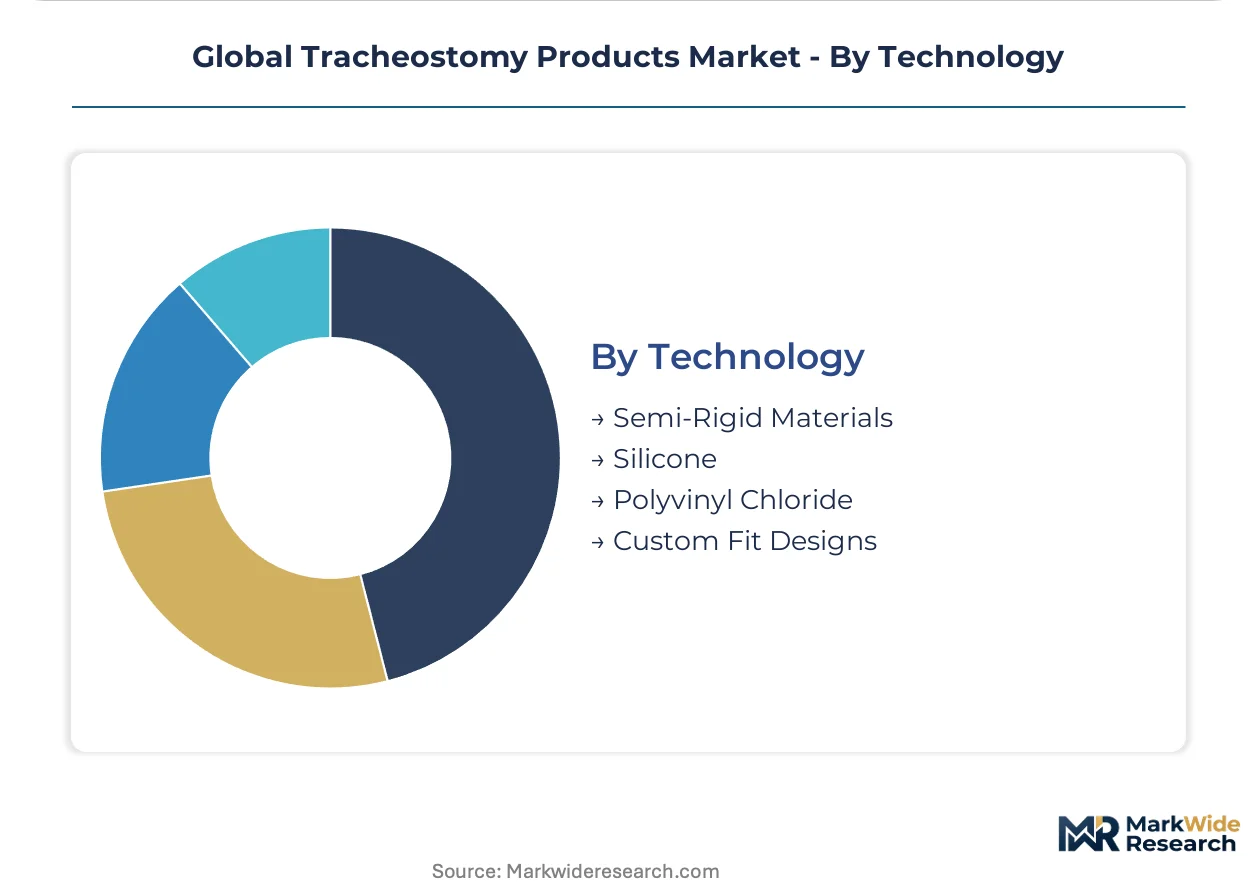
Material science differentiation determines biocompatibility certification burden and dwell time performance, with silicone commanding premium positioning against commodity polymer alternatives.
- Silicone:Medical-grade formulations meet ISO 10993 extended implantation standards with superior tissue tolerance and reduced granulation tissue formation. Silver-ion and chlorhexidine compounding variants command premium positioning in US home care settings with recurrent pneumonia risk profiles.
- Semi-Rigid Materials:Hybrid constructions balance structural integrity with patient comfort for intermediate-duration applications.
- Polyvinyl Chloride:Cost-efficient polymer dominates acute care disposable specifications despite cuff pressure management limitations.
- Custom Fit Designs:Anatomically matched geometries address pediatric and rare disease airway anomalies.
Technology leadership anchors in Silicone; cost containment anchors in Polyvinyl Chloride.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision silicone tracheostomy tubes to US home care distributors, while Japanese suppliers ship humidification accessories to Southeast Asian hospital networks. This trade-flow pattern concentrates regulatory scrutiny on FDA 510(k) and PMDA approval reciprocity.
United States
CMS home health reimbursement expansion and California-Texas home health agency consolidation drive demand for direct-to-patient logistics platforms. FDA 510(k) clearance timelines shape product launch cadences for speaking valve innovations. Minneapolis and Boston medical device clusters anchor institutional contracting negotiations with vertically integrated supply chains.
Germany
EU MDR conformity assessment backlogs and TRACOE Medical GmbH's pediatric custom-fit specialization concentrate high-value tube manufacturing in the Rhineland. EMA device-drug combination rules reclassify antimicrobial-coated products, extending technical documentation requirements. Baden-Württemberg precision polymer processors supply medical-grade silicone compounding to domestic tube fabricators.
Japan
METI aging-in-place subsidies and ventilator-dependent elderly demographics expand home medical equipment channels for portable suction systems. PMDA streamlined approval pathways for designated orphan airway devices accelerate pediatric tube market entry. Osaka-Kobe medical device manufacturing corridor hosts humidification accessory production for Asia-Pacific export.
China
NMPA Class II medical device registration reforms and domestic ventilator manufacturing scale create import substitution pressure on foreign tube suppliers. Yangtze River Delta chemical clusters produce medical-grade silicone raw material, though quality variance limits direct substitution for German and US polymer grades. Shanghai medical device distributors consolidate procurement for tertiary hospital networks.
United Kingdom
NHS long-term ventilation service specifications and community respiratory team expansion shift tracheostomy management from acute trusts to domiciliary settings. MHRA post-Brexit recognition agreements with FDA and PMDA preserve market access for US and Japanese device exporters. London-Southeast procurement consortia negotiate preferred supplier contracts with speaking valve manufacturers.
Global Tracheostomy Products Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with interventional portfolios spanning acute and post-acute channels. Market structure concentrates around institutional contract holders with group purchasing organization relationships and home care distributors with direct-to-patient logistics capabilities. Two strategic archetypes dominate: vertically integrated hospital suppliers with backward polymer sourcing control, and specialty silicone fabricators with pediatric custom-fit capabilities. Competitive moves center on M&A for regulatory affairs capacity and strategic partnerships for remote monitoring platform integration.
Among diversified device conglomerates, Medtronic and Smiths Group plc exemplify the institutional-contracting archetype with breadth across airway management portfolios. Fisher & Paykel Healthcare Limited occupies a position within the humidification-accessory specialization tier, anchoring Asia-Pacific market presence through respiratory care adjacencies. TRACOE Medical GmbH represents the precision-fabrication archetype, sitting within German medical device manufacturing traditions for anatomically matched tube geometries.
| Leading Market Players |
|---|
| Medtronic |
| Smiths Group plc |
| Teleflex Incorporated |
| TRACOE Medical GmbH |
| Cook Group |
| ConvaTec Group plc |
| Fisher & Paykel Healthcare Limited |
| Boston Medical Products Inc. |
| Pulmodyne, Inc. |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance tiers gate both supplier qualification and price differentiation, with antimicrobial-coated silicone tubes commanding premium positioning over standard PVC alternatives while Northeast Asian polymer sourcing concentrates cost structures.
Pricing Analysis
Next-generation antimicrobial silicone formulations carry 40-60% premiums over standard silicone, which itself prices 25-35% above legacy PVC constructions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility certification depth and cuff pressure sensor integration. Cost compression in economy PVC segments is intensifying because German hospital purchasing consortia are consolidating supplier lists toward MDR-ready portfolios. Home care distributors show highest price sensitivity due to Medicare reimbursement caps, while academic medical centers absorb premium tiers for speaking valve phonation efficacy data.
Supply Chain Analysis
Northeast Asian chemical manufacturing zones in China, South Korea, and Japan anchor medical-grade silicone polymer production, exposing device makers to freight volatility and customs processing delays. Raw material sourcing draws from Yangtze River Delta silicone processors, Baden-Württemberg precision polymer compounders, and Osaka-Kobe specialty chemical corridors. Single-source vulnerability concentrates in antimicrobial coating precursors where silver-ion and chlorhexidine suppliers number fewer than five qualified vendors globally. Distribution runs through durable medical equipment dealers in institutional channels and manufacturer-direct portals in consolidated home health markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tracheostomy product economics increasingly hinge on recurring revenue from scheduled cannula and filter replacement cycles, with remote monitoring subscription attach rates expanding faster than hardware unit growth.
For Market Incumbents: Shield market position by securing backward integration into medical-grade silicone compounding to offset Northeast Asian supply concentration risks, and accelerate FDA 510(k) pathway investments for antimicrobial-coated tube portfolios before EU MDR Article 117 reclassifications freeze competitor product lines. Priority rests on defending group purchasing organization contracts against vertically integrated device makers capturing direct-to-patient channels. For New Entrants and Emerging Players: Differentiate on pediatric custom-fit segmentation where TRACOE Medical GmbH's scalable production models demonstrate white-space viability for rare disease airway anomalies. Target Japan's METI-subsidized home medical equipment channel for portable humidification and suction systems, leveraging PMDA streamlined approval pathways for designated orphan devices. Go-to-market angle should emphasize cloud-based respiratory analytics platform integration with cuff pressure sensors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across speaking valve manufacturing as 3D printing and modular valve assembly reduce tooling requirements. Long-term viability favors acquisition targets with dedicated regulatory affairs capacity for EU MDR conformity assessments and established relationships with California-Texas home health agency networks. Signal to watch: CMS coding updates expanding tracheostomy supply kit coverage that would accelerate discharge planning volumes.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates US market entry for antimicrobial-coated tube innovations ahead of MDR reclassification barriers. |
| Hospital System Partnership | Secures preferred supplier status with California-Texas home health agencies consolidating procurement. |
| Software Companion Development | Enables predictive intervention through cloud-based cuff pressure analytics integrated with mechanical ventilation circuits. |
| CE Marking Pathway | Preserves EU market access amid notified body capacity constraints extending technical documentation timelines. |
| Reimbursement Strategy | Aligns product portfolios with Medicare home health coding updates covering tracheostomy supply kits. |
Research Methodology
A standing panel of otolaryngology investigators, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body technical documentation. Bottom-up demand modeling triangulated against top-down market sizing across silicone material grades, functional product categories, and care setting channels.
Consistency checks validated volume and value outputs against external benchmarks including PMDA approval databases, METI home medical equipment subsidy records, and German hospital purchasing consortium contract awards. Segmentation dimensions spanned material technology, functional product type, application setting, and end-user channel across the analysis window. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in long-term respiratory support and speaking valve phonation protocols.
Material uncertainties — silicone raw material supply disruptions, EU MDR conformity assessment backlogs, and CMS reimbursement coding revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway timelines and home care migration rates. Practitioners should keep alternative scenarios live as antimicrobial coating elution profile requirements and Japan's aging-in-place subsidy allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Blood Warmers Market
Medical Devices
Snare Devices Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Global Foley Catheters Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Dermal Allograft Market
Medical Devices
Transport Chairs Market
Medical Devices
Artificial Respirator Market
Medical Devices
Skincare Devices Market
Medical Devices
Critical Care Devices Market
Medical Devices
Global Blood Ketone Meter Market