
 Tissue Sectioning Market | 2026-2036
Tissue Sectioning Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Sectioning Market Intelligence
Procurement strategy is shifting from single-source equipment agreements toward multi-vendor service contracts in academic histopathology cores. Thermo Fisher Scientific leverages its integrated reagent-instrument portfolio to anchor long-term customer relationships. Leica Biosystems Nussloch GmbH sustains dominance in clinical diagnostics through embedded service networks. Sakura Finetek competes aggressively on automated staining-sectioning workflow integration.
Tissue sectioning encompasses mechanical slicing of fixed or frozen biological specimens to produce thin, uniform slices typically ranging from two to ten micrometers for microscopic examination. The process enables pathologists to visualize cellular architecture, diagnose malignancies, and guide therapeutic decisions in oncology and neurology. Automated sectioning technology commands the largest installed base among technology segments, while computer-aided sectioning represents the fastest-expanding category as laboratories pursue reproducibility and digital pathology compatibility. Microtomes retain the dominant product type position due to versatility across paraffin-embedded and frozen specimen protocols, though cryostats capture premium pricing in intraoperative consultation settings.
FDA quality system regulation and CLIA laboratory certification requirements shape equipment validation protocols and service documentation standards for US-based buyers. ISO 15189 medical laboratory accreditation and EU IVDR conformity assessment create parallel compliance obligations for European clinical laboratories. Stakeholders must monitor evolving digital pathology interoperability standards and their implications for sectioning workflow integration.
Market Dynamics
Digital pathology integration is compressing turnaround time requirements and forcing histopathology laboratories to reconfigure sectioning workflows around whole-slide imaging compatibility. This structural pressure elevates automated sectioning platforms while marginalizing manual microtome operations in high-throughput settings.
Growth Catalysts
- National Cancer Institute funding:Sustained federal investment in tissue-based oncology research expands equipment procurement cycles at academic medical centers across the United States.
- EU IVDR conformity assessment:The In Vitro Diagnostic Regulation's quality system mandates accelerate replacement of legacy sectioning equipment in European clinical laboratories seeking accredited status.
- Frozen section protocols:Intraoperative consultation demand from neurosurgical and breast oncology units drives cryostat installations in hospital-based pathology departments.
Market Restraints
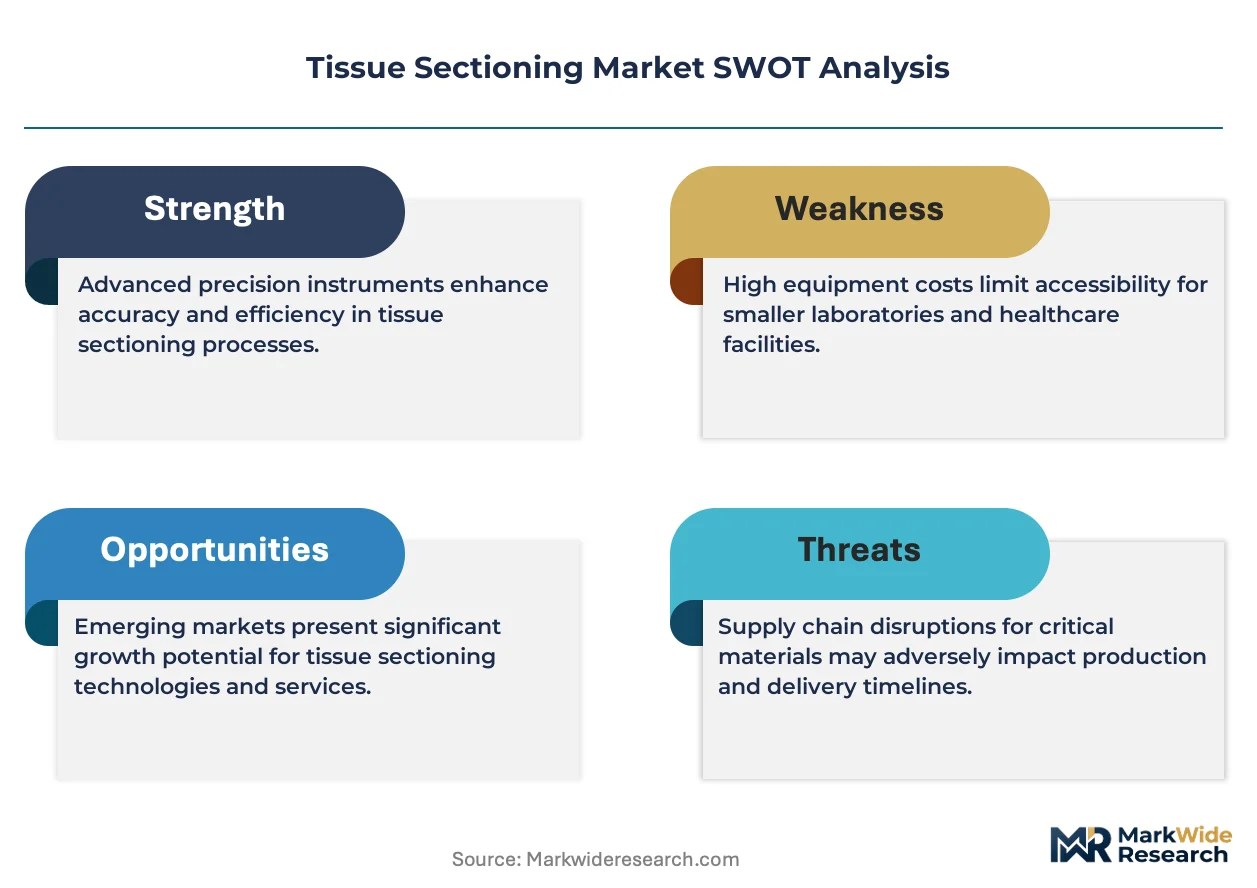
- Helium supply concentration:Cryostat cooling systems depend on helium imports from Qatar and the United States, exposing equipment manufacturers to input cost volatility and allocation constraints.
- Specialized technician scarcity:Histotechnologist training programs in the United States and Germany produce insufficient graduates to operate advanced automated sectioning platforms at scale.
- Paraffin embedding substitution:Alternative fixation technologies including PAXgene tissue systems threaten conventional microtome-dependent workflows in molecular pathology applications.
Strategic Opportunities
- India's diagnostic expansion:The country's PLI scheme for medical devices and rising cancer incidence create installation opportunities for mid-range automated sectioning systems in private hospital chains.
- Artificial intelligence convergence:Machine learning algorithms for section quality assessment are expanding into slide-scanning workflows, opening software-hardware bundling potential for equipment vendors.
- Japan's geriatric pathology demand:METI's healthcare infrastructure investments and aging demographics elevate tissue diagnostic volume in prefectural hospital networks.
Industry Challenges
- CLIA certification timelines:United States laboratories face extended validation periods for automated sectioning platforms, delaying revenue recognition and straining capital deployment schedules.
- Interoperability fragmentation:Proprietary digital image formats from competing whole-slide scanner manufacturers complicate sectioning-to-imaging workflow integration for multi-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Sectioning Market |
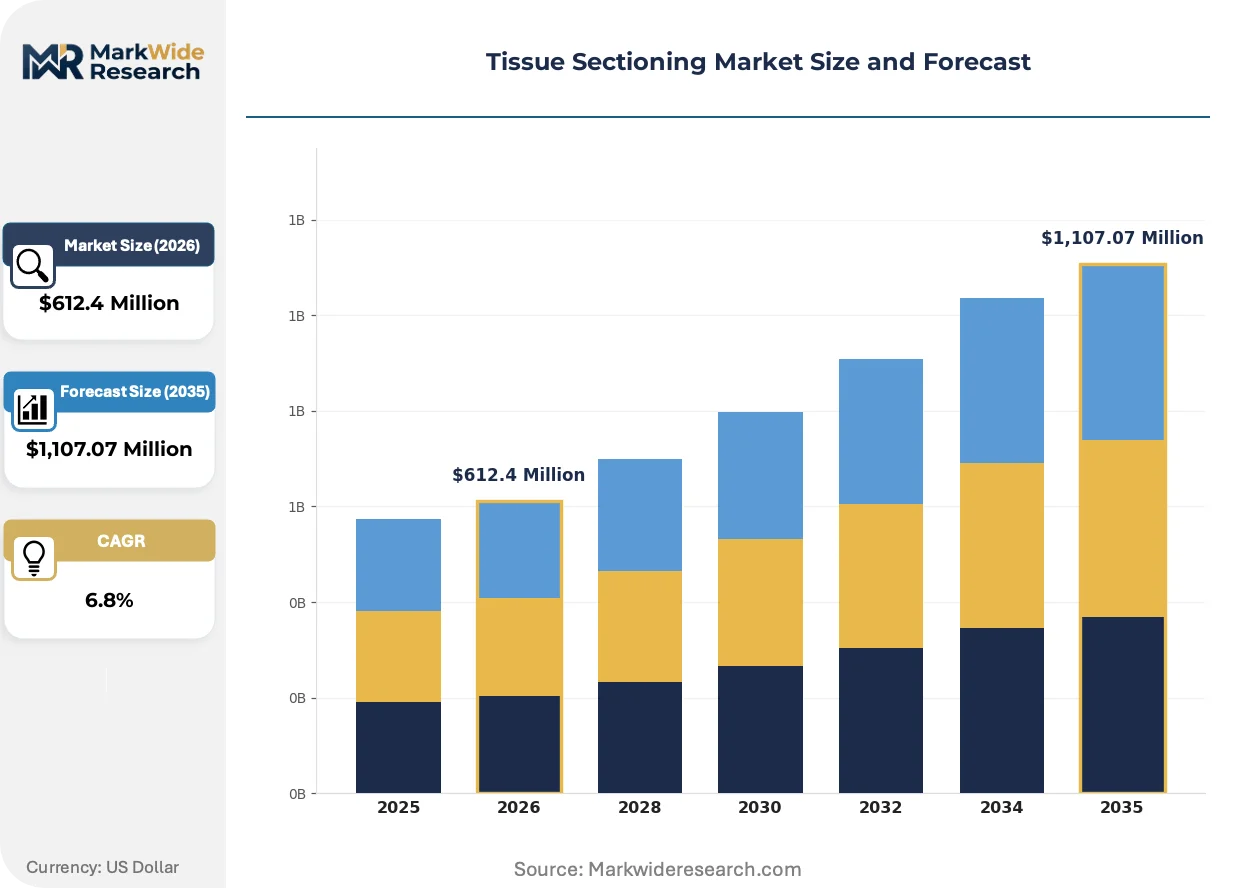
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microtomes, Cryostats, Vibratome, Accessory Equipment End User: Research Laboratories, Clinical Laboratories, Hospitals, Educational Institutions Application: Histopathology, Immunohistochemistry, Cytology, Molecular Biology Technology: Manual Sectioning, Automated Sectioning, Computer-Aided, Thin Sectioning |
| Companies Covered | Thermo Fisher Scientific, Leica Biosystems Nussloch GmbH, Sakura Finetek, LLS ROWIAK LaserLabSolutions GmbH, Diapath S.p.A., AMSBIO, Sakura Finetek Japan Co., Ltd., Slee Medical, Epredia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Sectioning Market Strategic Shifts & Innovations
Computational sectioning assistance is displacing operator-dependent quality control in high-throughput histopathology environments. Three convergent developments are restructuring equipment specifications and service delivery models.
Computer-aided sectioning is expanding into routine diagnostic workflows through real-time thickness monitoring and automated knife advance algorithms. Academic medical centers in the United States and Germany are adopting these platforms fastest, driven by CLIA and ISO 15189 documentation requirements. The technology is expanding into quality assurance protocols previously managed by senior histotechnologists, compressing training-to-competency timelines.
The FDA's quality system regulation for in vitro diagnostic devices is elevating equipment validation documentation and service record retention standards. Manufacturers must now maintain device history files and corrective action logs across twenty-five-year product lifecycles. United States clinical laboratories bear the primary compliance burden, with European notified bodies progressively harmonizing toward similar stringency under MDR Article 10.
Multi-vendor service contracting is displacing single-source equipment agreements in academic histopathology cores. Procurement teams now unbundle instrument acquisition from maintenance, reagent supply, and validation support across competing vendors. This pattern is most visible in National Cancer Institute-designated cancer centers, where budget autonomy and specialized workflow requirements resist vendor lock-in.
Tissue Sectioning Market Segmentation
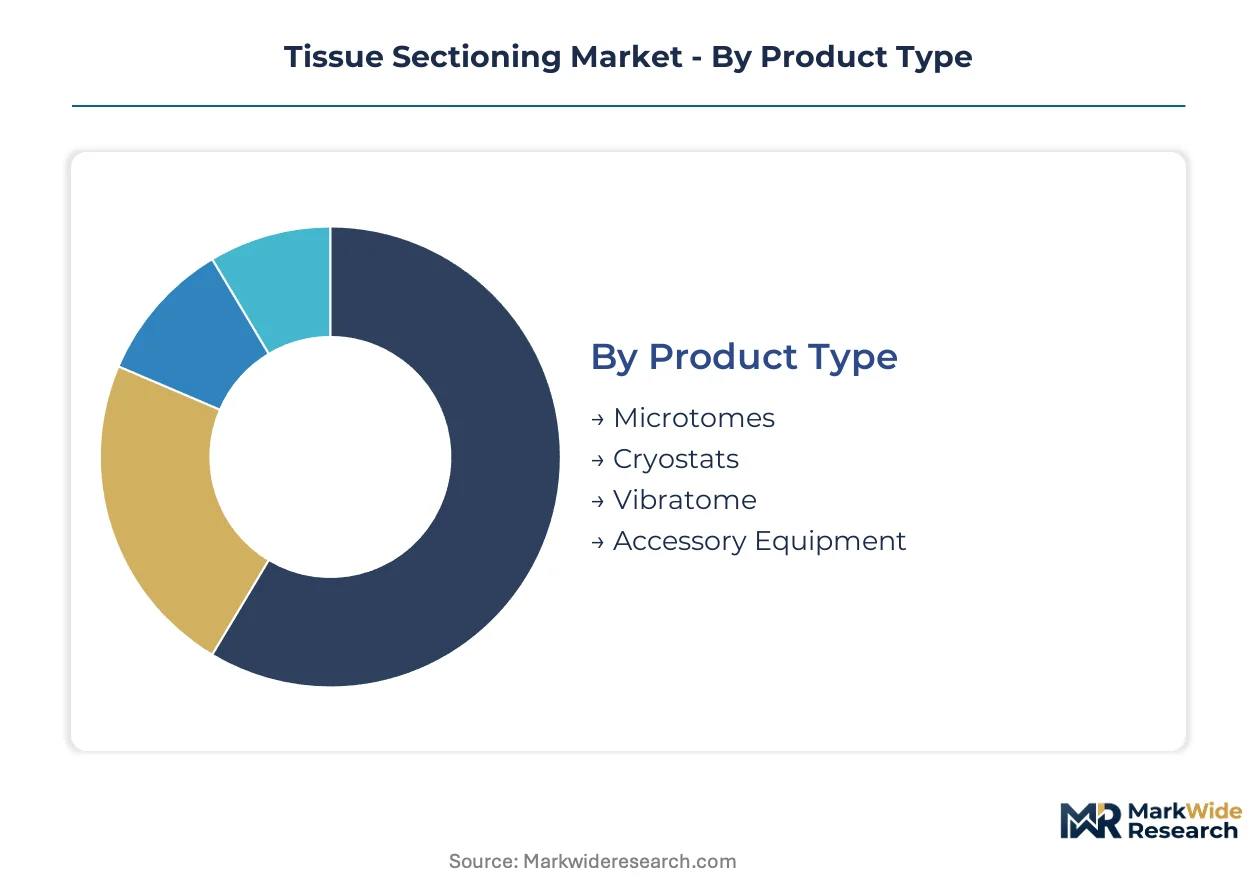
Tissue sectioning equipment exhibits divergent capital requirements across product architectures, with cryostats commanding premium pricing while microtomes scale through volume deployment. Understanding these structural cost tiers enables procurement teams to align capital allocation with workflow throughput and regulatory compliance obligations.
Product Type:
Cryostats demand the heaviest upfront capital commitment due to integrated cooling systems and precision thermal control engineering.
- Microtomes:Mechanical slicing instruments utilizing advancing specimen blocks and steel or disposable blades to produce paraffin-embedded sections. Demand concentrates in high-throughput clinical laboratories across the United States and Germany, where CLIA and ISO 15189 accreditation requirements favor proven reliability over experimental platforms.
- Cryostats:Refrigerated microtomes maintaining specimen temperatures between minus twenty and minus thirty degrees Celsius for frozen section protocols. Neurosurgical and breast oncology units in academic medical centers drive installations, with intraoperative consultation workflows justifying the capital intensity through accelerated diagnostic turnaround.
- Vibratome:Oscillating blade systems preserving tissue integrity for live-cell applications and thick-section fluorescence microscopy.
- Accessory Equipment:Blade holders, specimen clamps, and section transfer systems completing integrated workflow configurations.
Most installed capacity flows through microtomes. Expansion is steepest in cryostats.
End User:
Research laboratories concentrate the highest equipment sophistication, while clinical settings prioritize throughput validation and service responsiveness.
- Research Laboratories:Academic and government facilities pursuing experimental protocols with variable specimen types and non-standardized sectioning parameters. National Cancer Institute-designated cancer centers in the United States anchor demand, with federal funding cycles synchronizing procurement timing.
- Clinical Laboratories:Hospital-based and independent diagnostic facilities processing high-volume routine histopathology under regulatory accreditation. European clinical laboratories accelerate replacement cycles under EU IVDR conformity assessment mandates.
- Hospitals:Pathology departments embedded within acute care institutions requiring rapid frozen section capabilities for surgical consultation.
- Educational Institutions:Medical schools and histotechnology training programs operating entry-level manual equipment for competency development.
Clinical laboratories deploy the greatest aggregate unit volume. Research laboratories drive technology migration fastest.
Application:
Oncology diagnostics generate the most intensive sectioning demand, while molecular biology applications impose the most exacting technical specifications.
- Histopathology:Routine diagnostic examination of tissue morphology for malignancy detection and classification. Hospital-based pathology departments in Japan's prefectural networks process rising geriatric diagnostic volumes under METI infrastructure investments.
- Immunohistochemistry:Antibody-based protein detection requiring precise section thickness consistency for chromogenic signal reliability. Academic medical centers in Germany adopt automated sectioning platforms to satisfy ISO 15189 documentation requirements for reproducible staining protocols.
- Cytology:Cellular specimen preparation from fluid aspirates and exfoliative samples for cancer screening programs.
- Molecular Biology:Nucleic acid preservation and in situ hybridization applications demanding specialized sectioning parameters.
Histopathology commands the largest installed equipment base. Immunohistochemistry is climbing the fastest as companion diagnostic expansion intensifies.
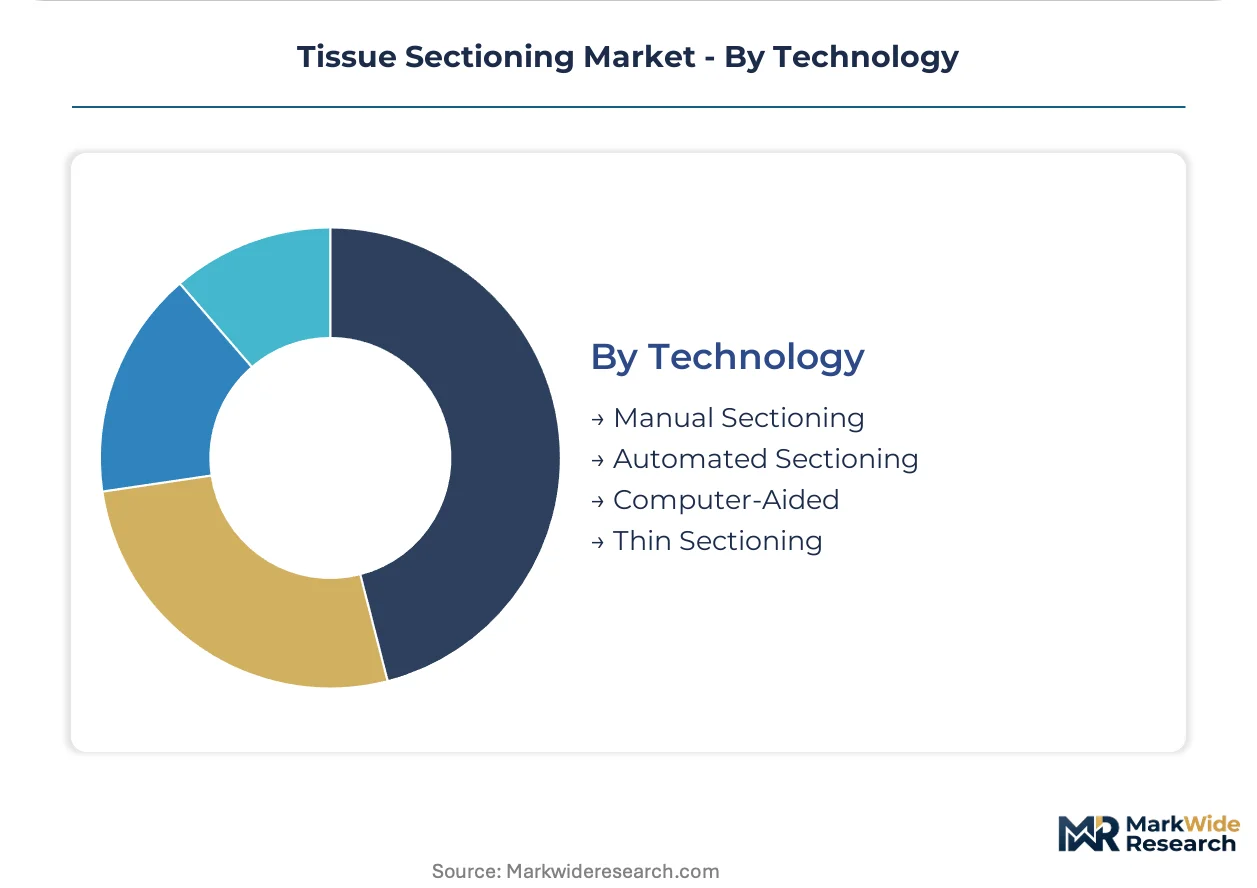
Technology:
Automation depth determines both capital expenditure tiers and operational labor substitution potential.
- Automated Sectioning:Motorized specimen advance and knife positioning with programmable thickness control and batch processing capabilities. High-throughput clinical laboratories in the United States favor these platforms for CLIA-compliant documentation and reduced histotechnologist labor dependence.
- Computer-Aided Sectioning:Real-time thickness monitoring, automated quality assessment, and digital pathology integration interfaces. Academic medical centers in Germany and the United States adopt these systems fastest as whole-slide imaging compatibility becomes mandatory.
- Manual Sectioning:Operator-controlled hand wheels and mechanical feeds for low-volume or specialized specimen applications.
- Thin Sectioning:Sub-micrometer precision systems for electron microscopy and advanced imaging modalities.
Automated sectioning holds the dominant installed position. Computer-aided platforms are gaining share fastest as laboratories pursue digital workflow integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical and Academic Area anchors the densest concentration of automated sectioning installations, with National Cancer Institute-designated cancer centers synchronizing procurement cycles to federal funding timelines. Germany's Heidelberg and Mannheim corridor follows, where ISO 15189 accreditation mandates accelerate technology refresh rates. Japan's prefectural hospital networks under METI infrastructure programs complete the triad of primary demand centers.
United States
National Cancer Institute funding sustains equipment procurement at academic medical centers in Boston, Houston, and Seattle. FDA quality system regulation for in vitro diagnostic devices elevates validation documentation requirements for CLIA-certified laboratories. The Longwood Medical and Academic Area in Boston concentrates the highest automated sectioning density, with Massachusetts General Hospital and Dana-Farber Cancer Institute leading workflow reconfigurations.
Germany
ISO 15189 medical laboratory accreditation and EU IVDR conformity assessment drive replacement of legacy microtome platforms in clinical diagnostics. The country's national pharmaceutical regulator enforces quality system mandates that compress equipment validation timelines. Heidelberg and Mannheim anchor the densest cluster of pathology infrastructure, with University Hospital Heidelberg advancing computer-aided sectioning adoption.
Japan
METI healthcare infrastructure investments and geriatric pathology demand elevate tissue diagnostic volume in prefectural hospital networks. The PMDA maintains alignment with international medical device standards while accelerating digital pathology interoperability guidelines. Osaka and Nagoya prefectures concentrate cryostat installations for intraoperative consultation workflows in neurosurgical units.
India
The PLI scheme for medical devices and rising cancer incidence create installation opportunities for mid-range automated sectioning systems. CDSCO medical device regulations are harmonizing toward international standards, reducing import friction for European and US equipment. Private hospital chains in Mumbai and Delhi-NCR anchor diagnostic expansion, with Tata Memorial Centre and AIIMS Delhi driving technology adoption.
United Kingdom
NHS pathology consolidation and cancer diagnostic backlog reduction programs sustain equipment procurement in regional laboratory networks. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit, creating parallel conformity assessment obligations. London's Imperial College Healthcare and Manchester's Christie NHS Foundation Trust anchor automated sectioning deployments.
Tissue Sectioning Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue computer-aided sectioning and digital pathology integration. The market structures around three maturity tiers: integrated life science conglomerates with reagent-instrument portfolios, specialized histopathology equipment manufacturers with embedded service networks, and regional fabricators competing on price-accessibility. Strategic archetypes include workflow integrators bundling staining-sectioning automation, service-heavy incumbents defending installed base through maintenance contracts, and software-hardware convergents targeting AI-assisted quality control. Dominant competitive moves encompass multi-vendor service contracting unbundling and validation support partnerships accelerating CLIA certification timelines.
Among US-based conglomerates, Thermo Fisher Scientific exemplifies the integrated reagent-instrument archetype. Leica Biosystems Nussloch GmbH represents the embedded service network model, with its German GmbH structure signaling European manufacturing heritage. Sakura Finetek occupies a position exemplifying workflow integration specialization, with its Japan Co., Ltd. affiliate anchoring Asia-Pacific market presence. These three entities collectively represent the competitive spectrum from diversified life science platforms to focused histopathology automation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Leica Biosystems Nussloch GmbH |
| Sakura Finetek |
| LLS ROWIAK LaserLabSolutions GmbH |
| Diapath S.p.A. |
| AMSBIO |
| Sakura Finetek Japan Co., Ltd. |
| Slee Medical |
| Epredia |
| Others |
Cost & Logistics Intelligence
EU IVDR conformity assessment gates qualified supply access and premium-tier pricing power, compressing margins for uncertified equipment while elevating validated platforms in European clinical laboratories. Helium supply concentration from Qatar and the United States further stratifies cryostat pricing tiers, with thermal engineering sophistication determining cost pass-through capacity.
Pricing Analysis
Helium cost pass-through dynamics dominate cryostat pricing structures, with cooling system engineering absorbing volatile input expenses. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated automated platforms from ISO 15189-compliant mid-range systems and entry-level manual microtomes. Price differentiation hinges on CLIA certification documentation depth and embedded service contract duration. Cost compression in economy-tier manual equipment is intensifying because of histotechnologist training program scarcity. Private hospital chains in India exhibit the highest price sensitivity, while National Cancer Institute-designated cancer centers in the United States demonstrate the lowest.
Supply Chain Analysis
Helium supply rests on Qatari liquefaction facilities and United States strategic reserve allocations, tethering cryostat manufacturers to geopolitical allocation protocols. Precision thermal control components draw from German engineering specialists and Japanese sensor fabricators. Steel blade supply sources from Chinese metallurgical producers and Swedish specialty steel mills. Single-source vulnerability concentrates in superconducting magnet assemblies for advanced cryostat cooling systems. Distribution runs through authorized service networks embedding factory-trained engineers within regional hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with digital pathology integration forcing histopathology laboratories toward premium automated sectioning specifications that command sustained pricing power.
For Market Incumbents: Extend validation support partnerships to compress CLIA certification timelines for automated platform deployments. Deepen backward integration into precision blade manufacturing to defend margin position against commodity steel volatility. Computer-aided sectioning entrants threaten installed base stickiness through AI-assisted quality control workflows.
For New Entrants and Emerging Players: AI-powered section quality assessment algorithms offer a technology-first wedge into slide-scanning workflow integration. Target India's private diagnostic expansion under PLI scheme incentives for mid-range automated systems. Pursue software-hardware bundling partnerships with whole-slide scanner manufacturers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators competing on price-accessibility without embedded service networks. Long-term viability favors specialized histopathology equipment manufacturers with twenty-five-year device history file maintenance capabilities. Watch FDA quality system regulation enforcement intensity as the primary inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vendor Service Contracting | Unbundles instrument acquisition from maintenance, reducing vendor lock-in at NCI-designated cancer centers. |
| Computer-Aided Sectioning Development | Integrates real-time thickness monitoring with whole-slide imaging compatibility for CLIA documentation compliance. |
| Helium Supply Diversification | Mitigates cooling system input cost volatility through alternative cryogenic engineering partnerships. |
| Validation Support Partnerships | Accelerates CLIA certification timelines for automated platforms in United States clinical laboratories. |
| India PLI Scheme Localization | Captures diagnostic expansion in private hospital chains through mid-range automated sectioning systems. |
Research Approach
Direct dialogue with histopathology laboratory directors, biomedical equipment procurement managers, histotechnologist training program administrators, and GPO contracts managers grounded qualitative findings. Secondary validation drew from FDA quality system regulation filings, EU IVDR conformity assessment databases, hospital procurement contract disclosures, and National Cancer Institute funding appropriations documentation. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates.
Top-down macroeconomic filtering intersected with bottom-up segment-level modeling across product type, end user, application, and technology dimensions throughout the forecast period. CAGRs derived from regression analysis against NCI funding cycles, EU IVDR replacement mandates, and METI infrastructure investment trajectories. Segment growth rates incorporated digital pathology interoperability adoption curves and frozen section protocol expansion in neurosurgical units.
The model holds under sustained federal research funding and stable helium supply allocation; deviation in FDA enforcement intensity or Qatari export restrictions would shift equipment replacement timelines. Forecasts incorporate documented assumptions regarding CLIA certification duration and ISO 15189 harmonization progress. Regulatory timeline acceleration, alternative fixation technology substitution rates, and histotechnologist workforce expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Intradermal Injections Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Global Disability Devices Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
India Drug Delivery Devices Market