
 Hybrid Grafts Market | 2026-2036
Hybrid Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Grafts Market Foresight
Vascular surgeon training capacity is redrawing competitive boundaries across developed healthcare systems. Terumo Corporation leverages its integrated manufacturing footprint to sustain cost advantages in coronary graft production. W. L. Gore & Associates differentiates through proprietary expanded polytetrafluoroethylene technology that dominates thoracic aortic applications. Medtronic anchors its position via broad hospital contracting relationships and deep clinical trial infrastructure.
Hybrid grafts combine synthetic polymer matrices with biological tissue components to create implantable conduits for arterial reconstruction, typically incorporating expanded polytetrafluoroethylene or polyester scaffolds seeded with autologous or allogeneic cells to improve biocompatibility and long-term patency. Coronary grafts occupy the largest revenue pool due to high procedure frequency, while decellularized technology segments are gaining fastest as tissue-engineering protocols mature and regulatory pathways clarify. Peripheral grafts compete on price in markets where bare-metal stents and balloon angioplasty provide viable alternatives, compressing margins for standard polymer constructs.
FDA premarket approval requirements and EU MDR technical documentation standards are elevating clinical evidence thresholds for new hybrid graft submissions, extending development timelines and favoring established players with regulatory affairs expertise. Japan's PMDA imposes additional quality system inspections that filter out smaller manufacturers lacking dedicated in-country compliance resources. Stakeholders must monitor reimbursement decisions by CMS and Germany's G-BA, as these determine whether premium hybrid technologies achieve sustainable adoption against conventional surgical grafts.
Market Dynamics
EU MDR technical documentation standards and FDA premarket approval pathways are elevating clinical evidence thresholds for implantable vascular devices, extending development timelines and consolidating advantage among manufacturers with established regulatory affairs infrastructure.
Growth Catalysts
- EU MDR conformity assessments:Tightened evidence requirements for implantable vascular devices are filtering out undercapitalized competitors and concentrating procurement relationships among compliant suppliers.
- Cardiovascular surgeons:Hospital-based specialists are expanding utilization of hybrid grafts for complex aortic reconstructions as training protocols mature and long-term patency data accumulates.
- Decellularized technology:Advances in tissue-engineering protocols are clarifying regulatory pathways and accelerating segment expansion as biological scaffolds demonstrate improved biocompatibility profiles.
Market Restraints
- Polymer raw material volatility:Expanded polytetrafluoroethylene and polyester supply chains face input cost pressure from petrochemical feedstock fluctuations, compressing margins for standard constructs.
- Japanese PMDA quality system inspections:Dedicated in-country compliance resource requirements filter out smaller manufacturers lacking localized regulatory infrastructure.
- Bare-metal stent substitution:Peripheral arterial disease treatment alternatives limit pricing power for standard polymer grafts in cost-sensitive healthcare systems.
Strategic Opportunities
- Germany's G-BA reimbursement decisions:Positive technology assessments for premium hybrid constructs would unlock sustainable adoption against conventional surgical grafts in Europe's largest cardiac surgery market.
- Autologous cell seeding convergence:Integration of patient-derived biological components with synthetic scaffolds enables personalized vascular reconstruction protocols with reduced rejection risk.
- Direct-to-hospital contracting channels:Bypassing traditional distributor markups captures margin in concentrated procurement environments where IDN purchasing power is consolidating.
Industry Challenges
- Vascular surgeon training capacity:Limited fellowship positions and proctoring availability constrain procedure volume expansion in developed healthcare systems.
- ISO 14155 clinical investigation compliance:Extended certification timelines for novel hybrid graft submissions delay revenue recognition and strain development budgets.
- Legacy electronic health record integration:Post-implant surveillance data capture requires costly interoperability upgrades for longitudinal patency tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Grafts Market |
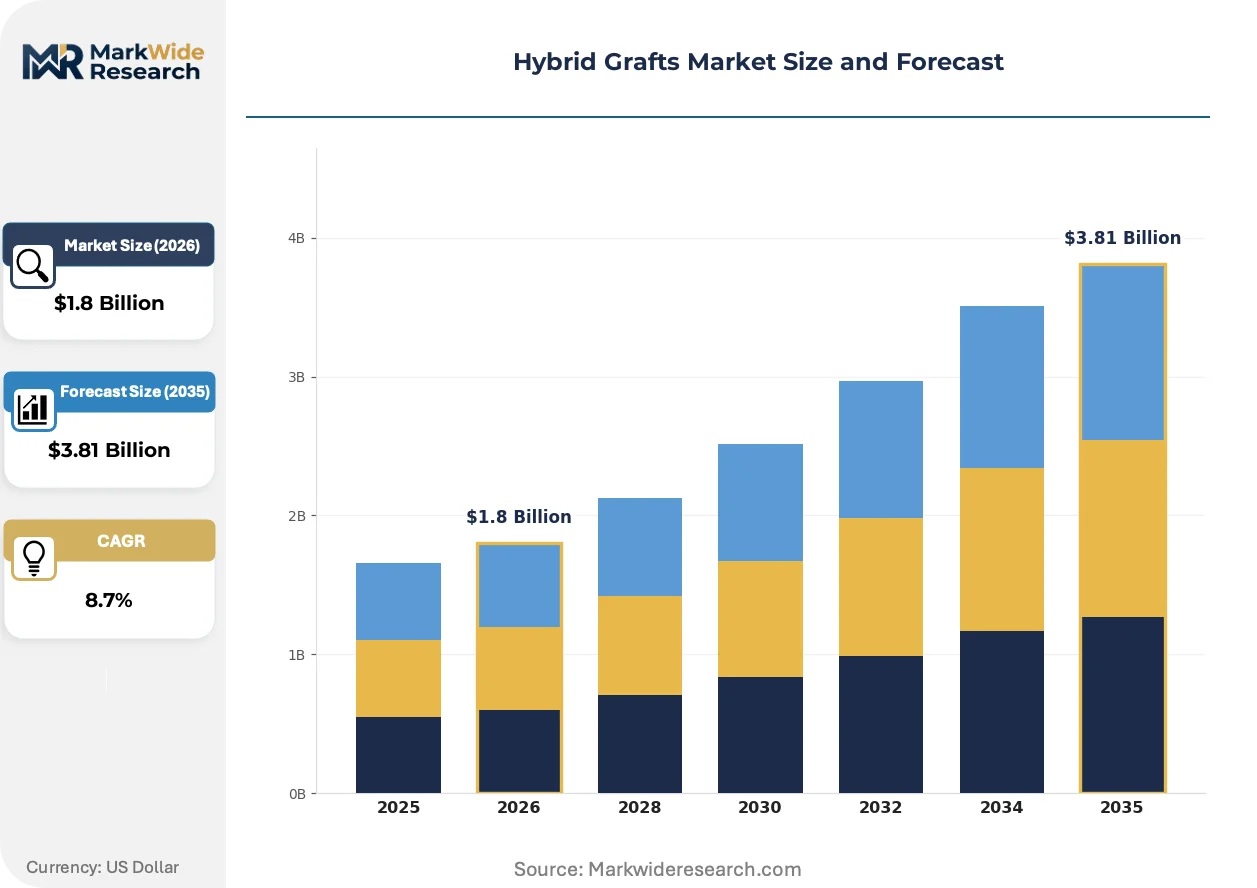
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coronary Grafts, Peripheral Grafts, Abdominal Aortic Grafts, Thoracic Aortic Grafts Technology: Bioengineered, Decellularized, Xenograft, Allograft End User: Hospitals, Specialty Clinics, Rehabilitation Centers, Ambulatory Surgical Centers Material: Polymers, Biomaterials, Metals, Composite Materials |
| Companies Covered | Terumo Corporation, BD Interventional, Getinge AB, Merit Medical Systems, JOTEC GmbH, W. L. Gore & Associates, Artivion, Medtronic, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Grafts Market Shifts & Advancements
Biological-synthetic interface engineering is reshaping vascular reconstruction outcomes. Decellularized tissue matrices are gaining traction as scaffold platforms. Procurement patterns are compressing toward value-validated technologies.
Decellularized xenogeneic scaffolds are decomposing the traditional dichotomy between purely synthetic and autologous graft options. Major academic medical centers in the United States and Germany are piloting these constructs for thoracic aortic reconstructions where synthetic patency rates historically underperform. The technology is decomposing established segment boundaries by enabling off-the-shelf availability with biological remodeling potential.
FDA's evolving premarket approval guidance for combination products is tightening evidentiary standards for cell-seeded hybrid grafts. Manufacturers must now demonstrate sustained biological activity through extended follow-up protocols. Thoracic aortic applications face the steepest compliance burden as these procedures carry the highest mortality risk and thus attract regulatory scrutiny.
Hospital procurement committees are consolidating vendor relationships around suppliers with comprehensive clinical trial infrastructure and established GPO contracts. Cardiovascular service line directors in the United States increasingly require real-world evidence packages supporting patency claims before contract renewal. This concentration is most visible in integrated delivery networks where standardization incentives override individual surgeon preferences.
Hybrid Grafts Market Segmentation
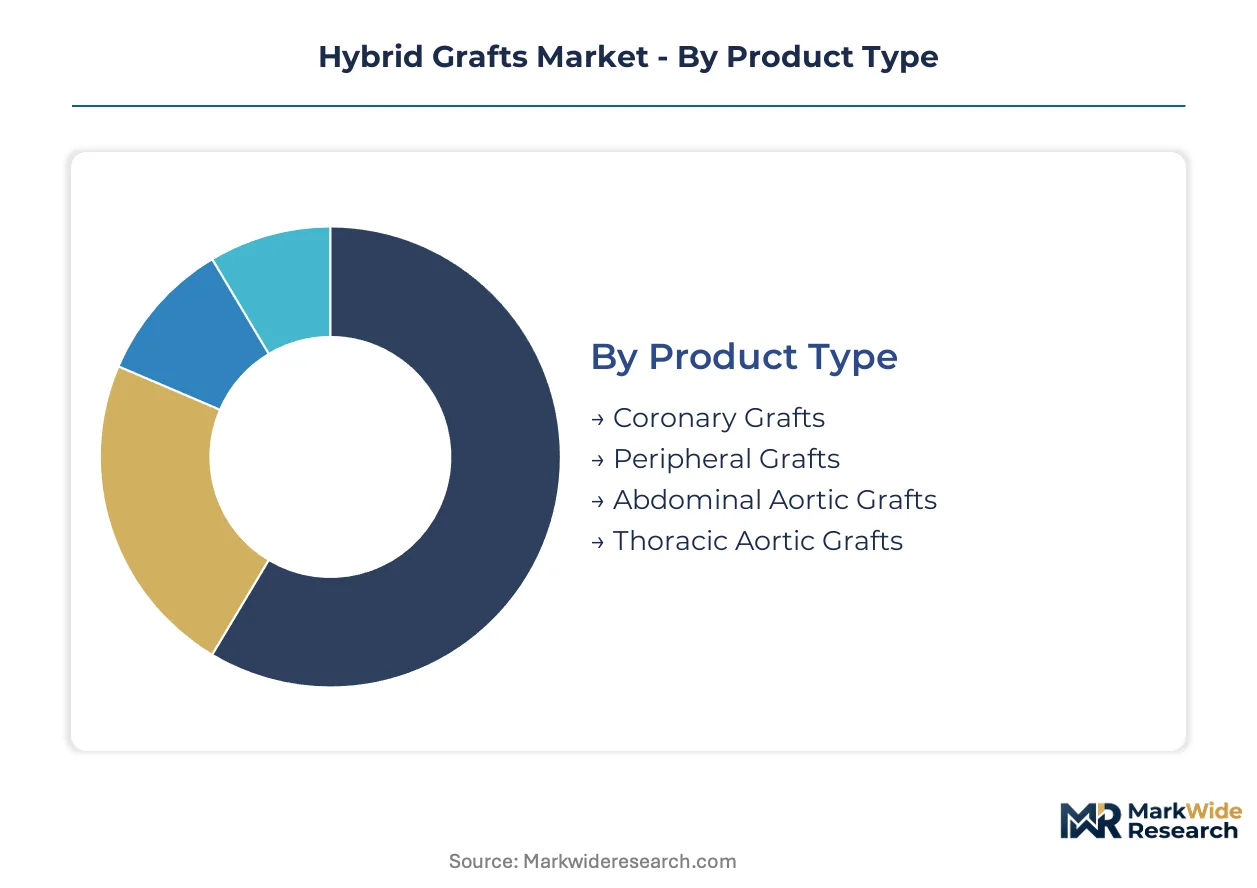
Segmentation in hybrid grafts reveals how clinical application demands, biocompatibility requirements, and procurement channel economics fragment commercial opportunity. Manufacturers must align R&D portfolios with the diverging evidence thresholds and reimbursement logics governing each category.
Product Type:
Coronary graft demand concentrates domestically in cardiac surgery hubs with established bypass programs, while aortic applications increasingly serve export markets seeking advanced reconstruction capabilities.
- Coronary Grafts:Synthetic polymer conduits—typically expanded polytetrafluoroethylene or polyester—engineered for saphenous vein bypass alternatives. Demand clusters in United States hospital systems where high procedural volume supports premium pricing against autologous harvesting costs.
- Peripheral Grafts:Lower-limb arterial reconstruction devices competing against endovascular alternatives. Procurement in Germany's G-BA reimbursement environment favors cost-effective polymer constructs over advanced biological hybrids where patency advantages remain unproven.
- Abdominal Aortic Grafts:Large-diameter conduits for aneurysm repair and occlusive disease.
- Thoracic Aortic Grafts:Complex arch and descending aorta reconstructions requiring specialized sizing.
Coronary grafts command the established base. The steepest expansion runs through thoracic aortic applications as surgical technique advances.
Technology:
Cost tier differentiation separates mature synthetic platforms from premium biological constructs with extended development timelines and elevated clinical evidence burdens.
- Bioengineered:Cell-seeded synthetic scaffolds combining autologous or allogeneic cellular components with polymer matrices. United States academic medical centers drive adoption where FDA premarket approval infrastructure supports lengthy investigation protocols.
- Decellularized:Tissue-derived matrices stripped of cellular material to reduce immunogenicity while preserving extracellular architecture. Japan's PMDA quality system inspections favor established manufacturers with dedicated compliance resources for these sensitive biological products.
- Xenograft:Animal-derived tissue processed for human implantation.
- Allograft:Human donor tissue preserved for vascular reconstruction.
Bioengineered platforms anchor current revenue. Decellularized technology is gaining share fastest as regulatory pathways clarify and remodeling data accumulates.
End User:
Customer type determines contracting complexity, with consolidated hospital procurement contrasting fragmented specialty clinic purchasing power.
- Hospitals:Integrated delivery networks and academic medical centers performing the majority of complex aortic reconstructions. United States cardiovascular service lines increasingly require real-world evidence packages before contract renewal, concentrating vendor relationships around suppliers with comprehensive trial infrastructure.
- Specialty Clinics:Focused vascular surgery centers with limited device formularies. German outpatient vascular clinics operate under distinct reimbursement codes that compress margins for premium hybrid technologies relative to conventional surgical grafts.
- Rehabilitation Centers:Post-operative care facilities with limited implant procurement.
- Ambulatory Surgical Centers:Same-day procedure venues with constrained device budgets.
Hospitals dominate volume concentration. Ambulatory surgical centers represent the most constrained pricing environment.
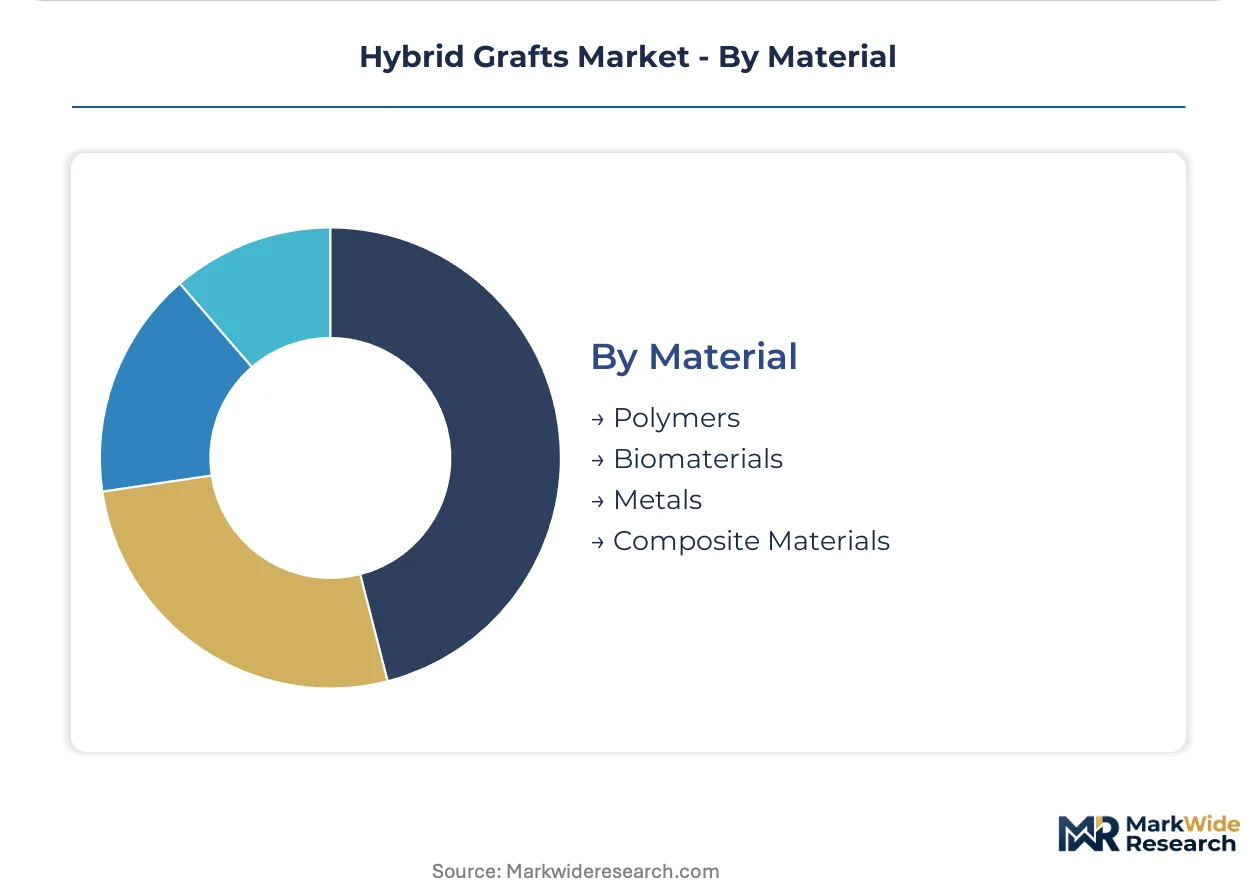
Material:
Supply concentration in petrochemical feedstocks and biological tissue sourcing shapes margin structure across material categories.
- Polymers:Expanded polytetrafluoroethylene and polyester remain the workhorse substrates for synthetic graft production. Raw material volatility in petrochemical supply chains compresses margins for standard constructs in cost-sensitive peripheral applications.
- Biomaterials:Decellularized matrices and tissue-engineered scaffolds requiring specialized processing. Japan's PMDA imposes additional quality system inspections that filter out smaller manufacturers lacking dedicated in-country compliance resources for these sensitive products.
- Metals:Nitinol and stainless steel components for hybrid stent-graft configurations.
- Composite Materials:Multi-layer constructs combining synthetic and biological elements.
Polymers retain volume leadership. Biomaterials are climbing the fastest as tissue-engineering protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac surgeons in the United States deploy hybrid grafts predominantly for complex coronary bypass procedures, whereas German specialists favor these constructs for thoracic aortic reconstructions where synthetic alternatives underperform. Japanese adoption concentrates on decellularized platforms requiring dedicated quality infrastructure. This consumption-mix differential shapes regional competitive positioning.
United States
Academic medical centers in Cleveland and Houston drive demand for bioengineered coronary grafts as saphenous vein harvesting costs escalate. FDA premarket approval pathways favor established manufacturers with clinical trial infrastructure. The Texas Medical Center anchors procurement consolidation through integrated delivery network standardization.
Germany
G-BA reimbursement assessments determine whether premium hybrid technologies achieve sustainable adoption against conventional surgical grafts. EU MDR conformity assessments filter undercapitalized competitors from procurement channels. The Heidelberg-Mannheim medical corridor concentrates thoracic aortic reconstruction expertise and vendor consolidation.
Japan
Aging demographics and established cardiac surgery infrastructure support procedure volume expansion in Tokyo and Osaka metropolitan areas. PMDA quality system inspections impose dedicated in-country compliance resource requirements that exclude smaller manufacturers. The Kanto region dominates decellularized technology adoption.
United Kingdom
NICE technology appraisals shape NHS procurement decisions for peripheral arterial disease interventions. MHRA post-Brexit regulatory divergence creates parallel submission requirements for novel hybrid constructs. The Oxford-Cambridge-London golden triangle concentrates tissue-engineering research and early adoption.
China
NMPA medical device registration reforms accelerate market access for multinational hybrid graft manufacturers with localized manufacturing. Provincial centralized procurement programs compress margins for standard polymer constructs. The Yangtze River Delta medical device cluster around Shanghai anchors import substitution initiatives.
Hybrid Grafts Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in hybrid graft manufacturing. The upper tier commands hospital contracting relationships and regulatory affairs infrastructure that smaller competitors cannot replicate. Mid-scale specialists concentrate on decellularized technology or regional procurement channels. Competitive moves center on strategic partnerships with academic medical centers and backward integration into biological tissue sourcing.
Among Japan-based diversified medical device manufacturers, Terumo Corporation occupies a position reflecting integrated manufacturing scale. Within the proprietary polymer technology tier, W. L. Gore & Associates exemplifies specialization around expanded polytetrafluoroethylene platforms. At the diversified medical technology end, Medtronic anchors a position through broad hospital contracting infrastructure. These three represent distinct competitive archetypes: integrated diversification, materials specialization, and full-line medical technology scale.
| Leading Market Players |
|---|
| Terumo Corporation |
| BD Interventional |
| Getinge AB |
| Merit Medical Systems |
| JOTEC GmbH |
| W. L. Gore & Associates |
| Artivion |
| Medtronic |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Capacity utilization at integrated polymer manufacturing sites in the United States and Germany shapes both supply concentration and minimum viable pricing for standard hybrid graft constructs. Scale economies in expanded polytetrafluoroethylene production anchor cost floors for synthetic scaffolds, while biological tissue processing facilities operate at lower throughput and higher unit economics.
Pricing Analysis
Long-term offtake agreements with integrated delivery networks dominate procurement for coronary and thoracic aortic applications, while spot purchasing persists in peripheral graft segments where bare-metal stents compete aggressively. Three-tier pricing structure across premium bioengineered, standard synthetic, and economy polymer levels reflects FDA certification tier and volume scale. Cost compression in peripheral grafts is intensifying because German G-BA reimbursement assessments favor conventional surgical alternatives. Ambulatory surgical centers exhibit the highest price sensitivity, whereas academic medical centers prioritize patency data over unit cost.
Supply Chain Analysis
Extended sterilization validation lead times for decellularized matrices constrain inventory velocity and necessitate strategic safety stock positioning across regional distribution hubs. Manufacturing concentrates in the United States, Germany, and Japan where PMDA quality infrastructure supports biological scaffold production. Raw material draws from petrochemical feedstocks for polymer substrates and porcine bovine tissue banks for biological components. Single-source vulnerability in specialized decellularization reagents creates procurement risk for smaller manufacturers. Distribution runs through direct-to-hospital contracting channels that bypass traditional distributor markups in consolidated procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States and hospital procurement committee standardization in Germany, fragmenting vendor relationships around suppliers with comprehensive clinical trial infrastructure.
For Market Incumbents: Fortify hospital contracting relationships by embedding real-world evidence generation capabilities that satisfy cardiovascular service line renewal requirements. Deepen backward integration into biological tissue sourcing to secure decellularized scaffold supply against porcine tissue bank volatility. Prioritize EU MDR technical documentation investment to filter undercapitalized competitors from procurement channels.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks provide accelerated premarket approval pathways for novel cell-seeding technologies targeting thoracic aortic applications. White-space opportunity concentrates in decellularized platforms for Japan's Kanto region where PMDA quality system requirements exclude smaller manufacturers lacking localized compliance resources. Target German outpatient vascular clinics through cost-effective polymer constructs aligned with G-BA reimbursement codes.
For Investors and Strategic Acquirers: Decellularized technology specialists with established PMDA inspection track records represent the most defensible acquisition archetype in biological scaffold segments. Long-term viability hinges on demonstrating sustained biological activity through extended follow-up protocols that satisfy FDA combination product guidance. Watch for CMS reimbursement decisions on premium hybrid technologies as the inflection signal for sustainable adoption against conventional surgical grafts.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Extended follow-up protocols for cell-seeded grafts satisfy combination product scrutiny in thoracic aortic applications. |
| EU MDR Conformity Assessment | Technical documentation investment filters undercapitalized competitors from European procurement channels. |
| Hospital System Partnership | Real-world evidence packages embedded in IDN contracts secure cardiovascular service line renewal. |
| Backward Integration into Tissue Sourcing | Captive porcine tissue bank supply secures decellularized scaffold production against biological input volatility. |
| Reimbursement Strategy | G-BA technology assessment alignment unlocks sustainable adoption in Europe's largest cardiac surgery market. |
Research Methodology
A standing panel of cardiovascular surgeons, hospital procurement managers, biomedical engineers, and GPO contracts specialists provided ongoing calibration across primary fieldwork phases. Secondary validation drew from FDA premarket approval filings, EU MDR technical documentation databases, hospital procurement records, and CMS reimbursement decision archives. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates across product type, technology, and end-user segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including clinical application, biocompatibility technology tier, customer contracting complexity, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, pricing elasticity coefficients, and technology substitution curves. Forecast inputs incorporated vascular surgeon training capacity constraints, decellularized platform regulatory pathway maturation, and integrated delivery network procurement consolidation patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA premarket approval infrastructure investment or EU MDR conformity assessment compliance would require recalibration. Forecasts reflect assumptions regarding reimbursement decision trajectories, biological scaffold remodeling data accumulation, and petrochemical feedstock cost stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Cryoablation System Market
Medical Devices
Global Automated External Defibrillators Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
C-Arms Devices Market