
 Artificial Disc Market | 2026-2036
Artificial Disc Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Disc Market Analysis
The capital-intensity gap between established orthopedics conglomerates and emerging spine specialists is collapsing as manufacturing scale requirements for polymer-grade biocompatibility testing escalate. Stryker Corporation leverages its integrated materials science division to sustain captive production of PEEK substrates. Zimmer Biomet anchors its position through dedicated cervical disc foundries in Warsaw, Indiana. Medtronic dominates advanced wear-testing protocols that exceed ISO 18192-1 benchmarks.
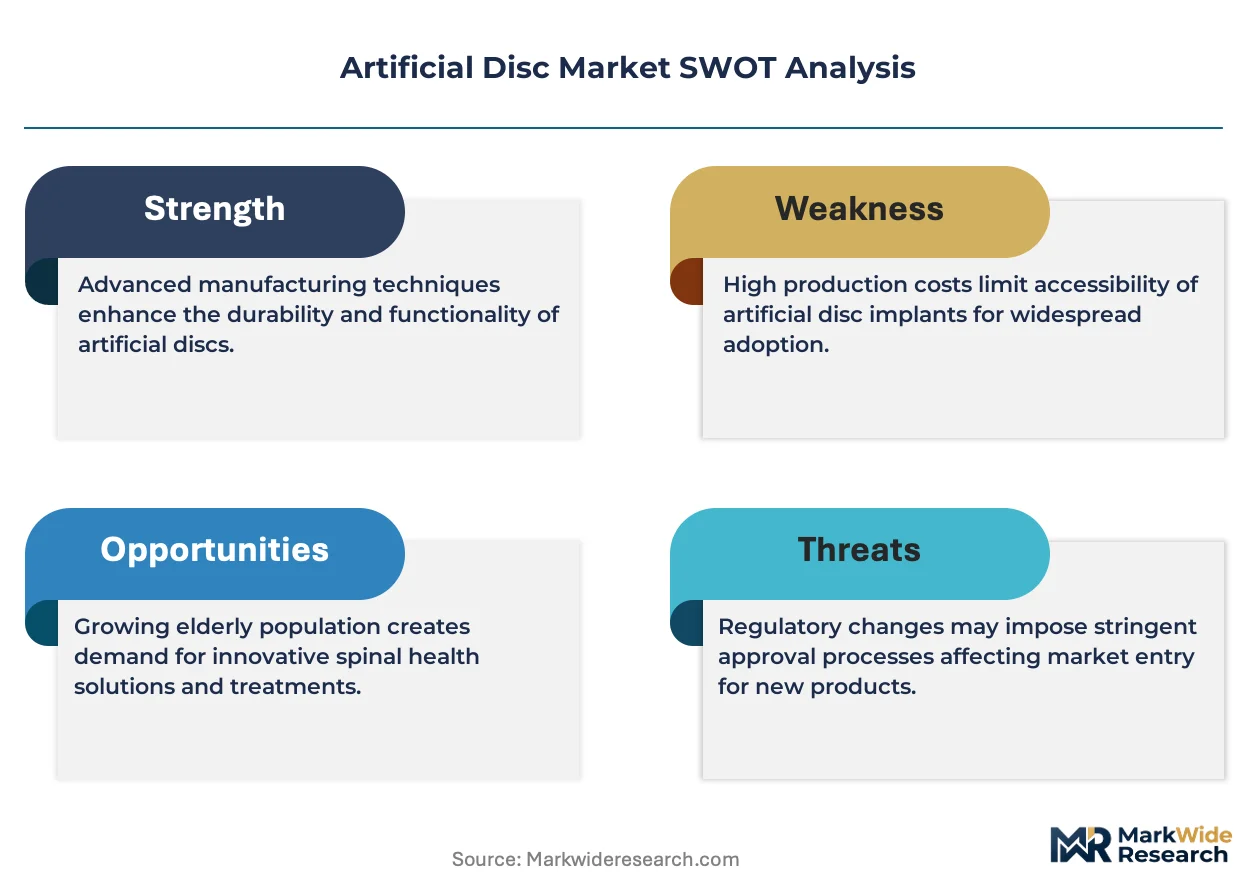
An artificial disc replaces a damaged spinal intervertebral disc with a prosthetic implant designed to preserve motion segment flexibility, typically constructed from cobalt-chromium-molybdenum alloy endplates articulating against a polyethylene or pyrolytic carbon core. Lumbar discs command the largest revenue pool due to higher material volumes and complex instrumentation sets, while cervical discs represent the fastest-expanding application as outpatient anterior cervical discectomy and fusion alternatives gain surgical acceptance. Metal-on-polymer constructs retain the majority position, though composite and bio-ceramic configurations are capturing premium positioning among academic medical centers.
FDA premarket approval (PMA) pathways impose multi-year clinical follow-up requirements that filter market entrants, while the EU MDR transition forces renewed conformity assessments for legacy CE-marked devices. Japan's PMDA maintains distinct biocompatibility testing protocols that delay product harmonization across OECD markets. Stakeholders must monitor evolving CMS reimbursement determinations for cervical total disc replacement as these coding decisions will determine addressable patient volumes regardless of implant innovation trajectories.
Market Dynamics
FDA premarket approval pathways compress competitive timelines as multi-year clinical follow-up requirements filter market entrants before commercial scale becomes viable.
Growth Catalysts
- Outpatient Surgery Migration:Ambulatory surgical centers in the United States expand cervical disc volumes as anterior cervical discectomy and fusion alternatives gain surgical acceptance among younger patient cohorts.
- REACH Compliance Premium:European manufacturers capturing MDR transition momentum secure renewed conformity assessments that legacy CE-marked devices struggle to match.
- PEEK Substrate Advancement:Polymer-grade biocompatibility testing protocols now exceed ISO 18192-1 benchmarks, enabling motion-preserving constructs that reduce adjacent segment disease.
Market Restraints
- Cobalt-Chromium Supply Concentration:Endplate alloy feedstock dependence on specialized foundries in Germany and Japan creates input cost volatility for metal-on-polymer constructs.
- PMDA Harmonization Friction:Japan's distinct biocompatibility testing protocols delay product standardization across OECD markets, forcing duplicate validation expenditure.
- Fusion Surgery Substitute:Mature anterior cervical discectomy and fusion techniques with established reimbursement codes constrain total disc replacement penetration in price-sensitive hospital systems.
Strategic Opportunities
- Bio-Ceramic Convergence:Pyrolytic carbon core technology combined with 3D-printed titanium lattice endplates opens premium positioning among academic medical centers seeking wear-resistant alternatives.
- CMS Coding Tailwind:Reimbursement determinations for cervical total disc replacement at the Centers for Medicare & Medicaid Services level create addressable patient volume expansion regardless of implant innovation trajectories.
- India PLI Capture:Production-linked incentive schemes for medical devices invite contract manufacturing relocation to reduce landed cost for Asia-Pacific distribution.
Industry Challenges
- Polymer Rheology Expertise Gap:Cross-linked polyethylene wear characterization requires specialized tribology talent scarce outside established orthopedics clusters in Warsaw, Indiana and Memphis, Tennessee.
- ISO 18192-1 Certification Timeline:Advanced wear-testing protocol validation extends product development cycles by eighteen to twenty-four months before PMA submission eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Disc Market |
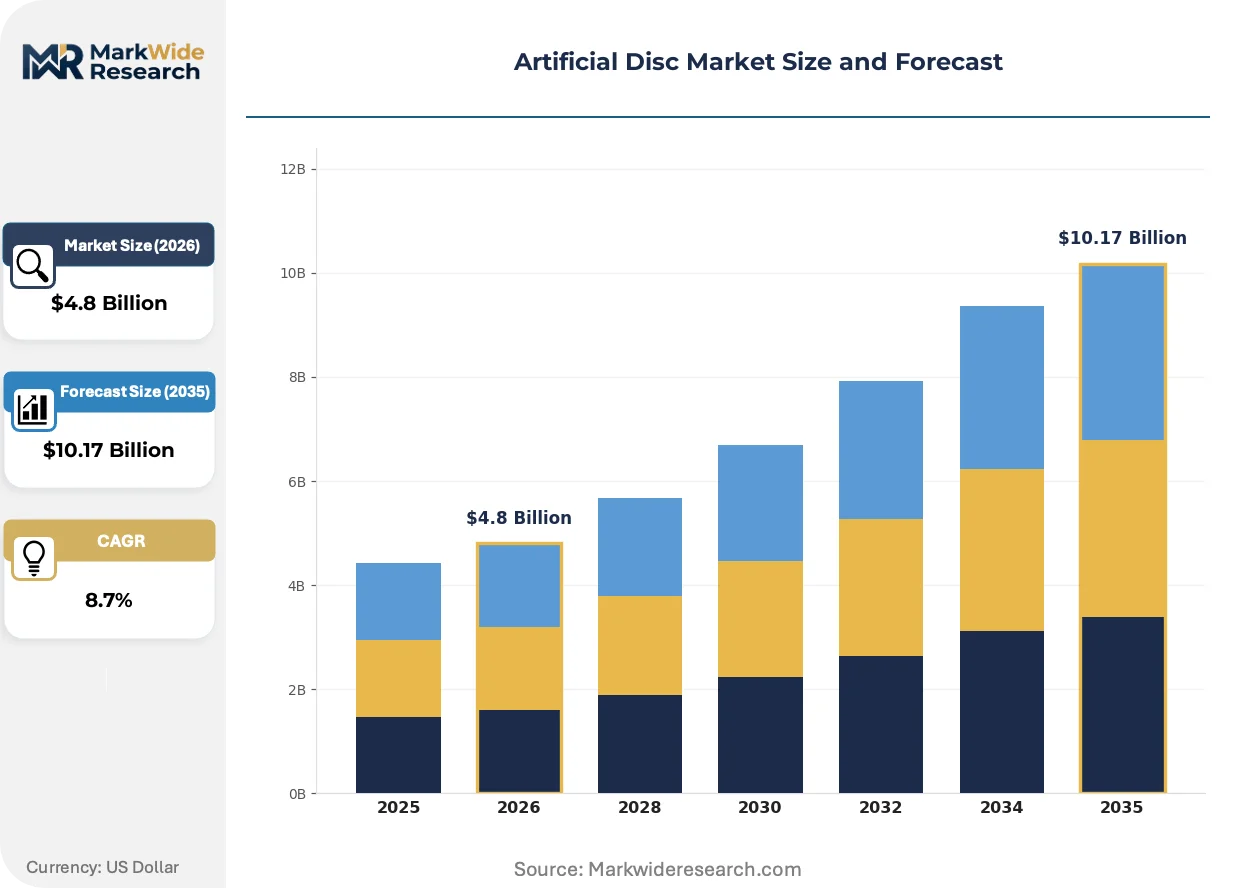
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
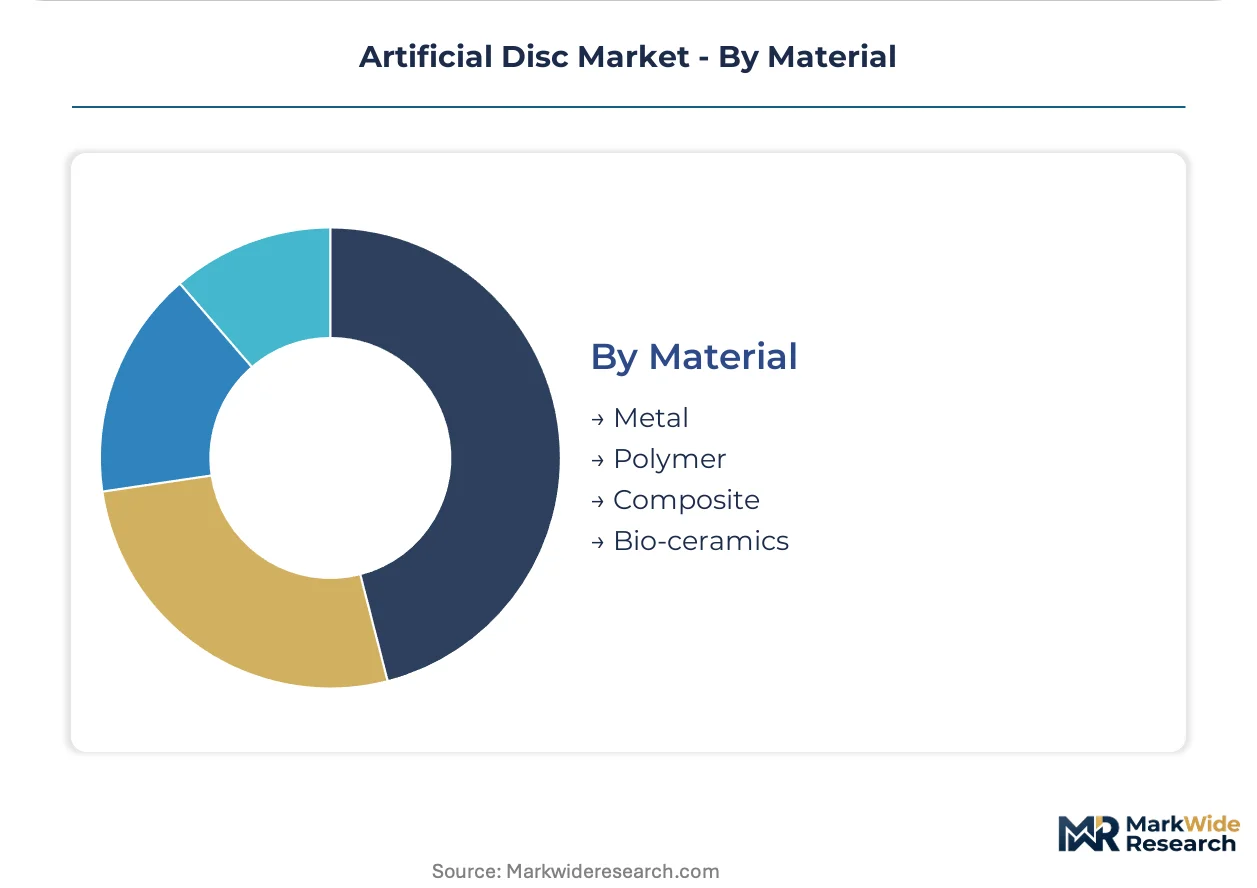
| Segmentation | Product Type: Cervical Discs, Lumbar Discs, Polyether Ether Ketone Discs, Metallic Discs End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Ambulatory Surgical Centers Distribution Channel: Direct Sales, Online Sales, Distributors, Healthcare Institutions Material: Metal, Polymer, Composite, Bio-ceramics |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Medtronic, Johnson & Johnson, Globus Medical, NuVasive, B. Braun Melsungen AG, Centinel Spine, Orthofix Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Disc Market Emerging Trajectories
Motion-preserving implant architectures are fragmenting traditional fusion dominance as material science advances enable biological fixation without segmental rigidity.
Pyrolytic carbon core technology is decomposing the historical metal-on-polymer standard in cervical applications. Academic medical centers in Boston and Rotterdam adopt composite constructs at accelerating pace. This material transition is compressing cobalt-chromium endplate demand while expanding addressable margins for ceramic-qualified manufacturers.
EU MDR transition forces renewed conformity assessments for legacy CE-marked devices that previously operated under directive-era approvals. European notified body capacity constraints extend recertification timelines. Lumbar disc portfolios face the greatest exposure as higher-risk classifications trigger enhanced clinical evidence requirements.
Hospital procurement committees now mandate motion-preserving outcomes data before vendor qualification, displacing traditional surgeon preference-driven selection. Integrated delivery networks in Texas and Florida unbundle implant costs from procedure bundles. This behavioral shift concentrates purchasing power among systems with dedicated spine service lines.
Artificial Disc Market Segmentation
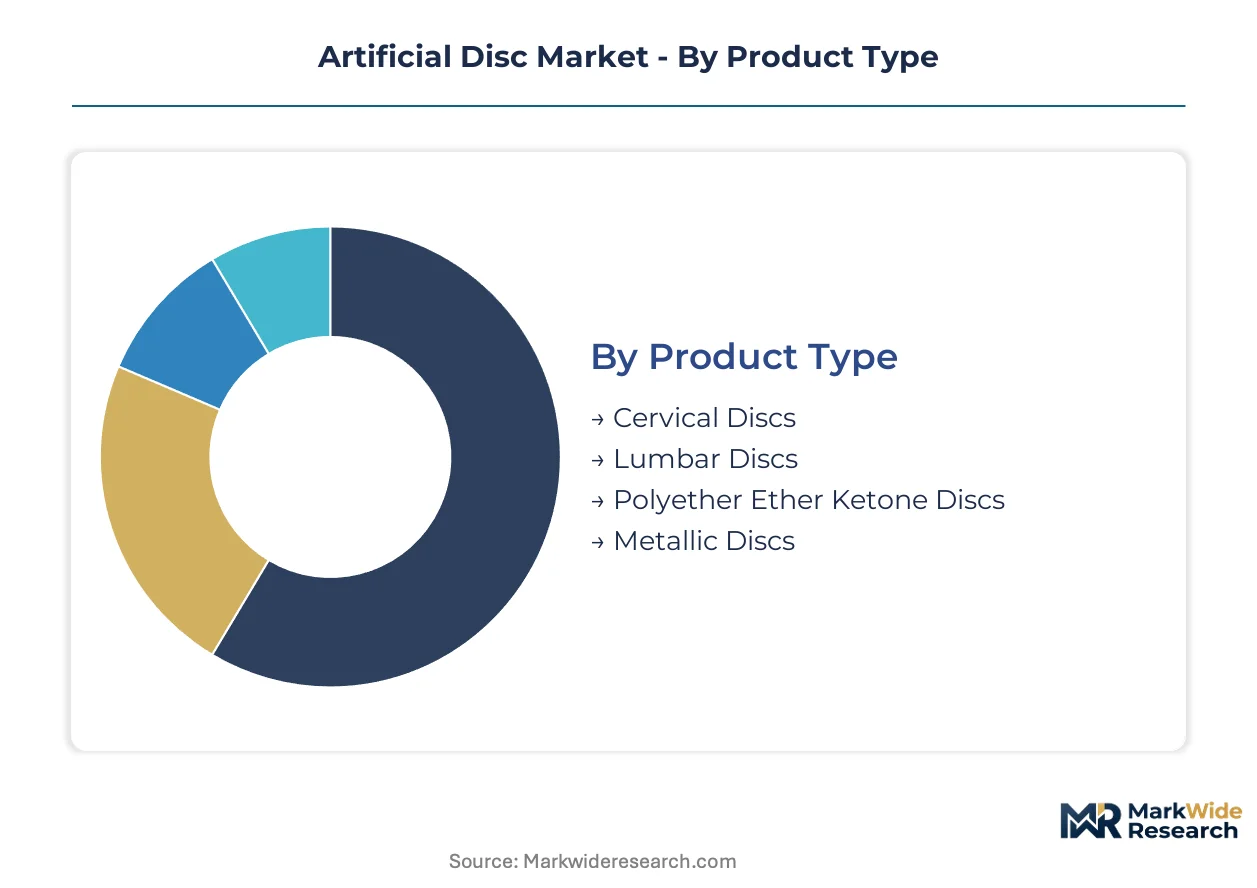
Segmentation in the artificial disc market determines regulatory pathway complexity, reimbursement eligibility, and manufacturing scale requirements. Product type and material composition dictate FDA PMA versus 510(k) routes, while end-user channel selection shapes pricing power and inventory turnover velocity.
Product Type:
FDA premarket approval timelines diverge sharply across anatomical targets, with cervical applications requiring shorter follow-up cohorts than lumbar equivalents.
- Lumbar Discs:These implants address L4-L5 and L5-S1 motion segments with larger device footprints and higher material volumes. Demand concentrates in United States academic medical centers where complex instrumentation sets and extended OR time are absorbable within bundled payment structures.
- Cervical Discs:Anterior cervical constructs enable outpatient migration with reduced adjacent segment disease risk. Ambulatory surgical centers in Florida and Texas drive fastest volume expansion as anterior cervical discectomy and fusion alternatives gain surgical acceptance among younger patient cohorts.
- Polyether Ether Ketone Discs:PEEK substrates exceed ISO 18192-1 biocompatibility benchmarks for motion-preserving constructs.
- Metallic Discs:Cobalt-chromium-molybdenum endplates retain majority position in established hospital supply chains.
Lumbar discs handle the majority of throughput; cervical discs are the fastest mover on share.
End User:
Procurement authority is consolidating toward integrated delivery networks with dedicated spine service lines and outcomes-based vendor qualification protocols.
- Hospitals:Inpatient facilities command procurement volume through bundled payment contracts and surgeon preference item consolidation. United States health systems with Level I trauma designations anchor complex lumbar revision volumes.
- Ambulatory Surgical Centers:Freestanding facilities capture anterior cervical discectomy and fusion alternative volumes with same-day discharge protocols. Texas and Florida certificate-of-need exemptions accelerate site-of-service shift.
- Orthopedic Clinics:Specialist practices influence surgeon training and early adoption curves for novel constructs.
- Rehabilitation Centers:Post-acute settings drive secondary demand for motion-preserving outcomes validation.
Hospitals retain the dominant procurement position; ambulatory surgical centers are expanding most quickly as site-of-service authorization broadens.
Distribution Channel:
Channel selection determines working capital intensity and inventory obsolescence risk across polymer-grade shelf-life constraints.
- Direct Sales:Manufacturer-employed specialists manage consignment inventory and surgeon training. Warsaw, Indiana and Memphis, Tennessee clusters concentrate direct salesforce density.
- Distributors:Independent intermediaries serve mid-tier hospitals with limited spine service line scale.
- Online Sales:Digital procurement platforms gain traction for instrumentation accessories and backup implant sizing.
- Healthcare Institutions:Group purchasing organizations aggregate demand across integrated delivery networks.
Direct sales handles the majority of throughput; online sales is the fastest mover on share.
Material:
Biocompatibility testing protocol selection determines regulatory timeline and geographic market access breadth.
- Metal:Cobalt-chromium-molybdenum alloys dominate endplate construction with established supply chains from German and Japanese specialized foundries.
- Polymer:Cross-linked polyethylene cores require tribology expertise concentrated in Warsaw, Indiana and Memphis, Tennessee orthopedics clusters.
- Composite:Hybrid constructs combine metallic endplates with polymer cores for cost-optimized positioning.
- Bio-ceramics:Pyrolytic carbon technology enables premium positioning among academic medical centers seeking wear-resistant alternatives.
Metal handles the majority of throughput; bio-ceramics is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European benchmarks by margins that reflect CMS reimbursement certainty against EU MDR compliance costs. German and Japanese manufacturers absorb regulatory friction that American competitors bypass through PMA pathway efficiency. Indian contract fabrication is capturing Asia-Pacific volume with production-linked incentive offsets.
United States
Cervical disc volumes concentrate in Florida and Texas ambulatory surgical centers where certificate-of-need exemptions accelerate site-of-service migration. FDA PMA pathway efficiency compresses commercialization timelines relative to OECD peers. Warsaw, Indiana anchors the densest orthopedics manufacturing cluster, with PEEK substrate foundries supplying domestic instrument sets.
Germany
Specialized cobalt-chromium foundries in the Ruhr region supply alloy feedstock for European endplate production. REACH compliance premiums and MDR transition costs filter smaller notified bodies from legacy CE-marked device recertification. Stuttgart-based tribology laboratories exceed ISO 18192-1 wear-testing protocols for motion-preserving constructs.
Japan
PMDA maintains distinct biocompatibility testing protocols that delay product harmonization with FDA and EMA standards. Tokyo academic medical centers drive pyrolytic carbon core adoption for cervical applications. Osaka-Kobe manufacturing corridors concentrate polymer-grade biocompatibility expertise scarce outside domestic orthopedics clusters.
India
Production-linked incentive schemes for medical devices invite contract manufacturing relocation from European and American parent companies. CDSCO regulatory alignment with IMDRF standards accelerates import substitution for spinal implant components. Gujarat and Maharashtra industrial corridors absorb Asia-Pacific distribution cost reduction mandates from multinational OEMs.
Switzerland
Swissmedic maintains premium-tier device approval standards that validate academic medical center procurement specifications across Continental Europe. Basel and Zurich clusters concentrate bio-ceramic research partnerships between implant manufacturers and materials science institutes. Precision machining heritage supports pyrolytic carbon lattice fabrication for next-generation cervical constructs.
Artificial Disc Market Vendor Landscape
Concentration sits with diversified orthopedics conglomerates that leverage captive materials science divisions and dedicated cervical disc foundries. Three strategic archetypes define competitive positioning: integrated materials science conglomerates with backward control over PEEK substrate supply, pure-play spine specialists with tribology expertise concentrated in Indiana and Tennessee clusters, and European precision manufacturers with REACH-compliant alloy foundry relationships. Dominant competitive moves include M&A absorption of wear-testing protocol capabilities and geographic expansion through India PLI scheme capture for Asia-Pacific cost reduction.
Among diversified orthopedics conglomerates, Stryker Corporation, Zimmer Biomet, and Medtronic exemplify archetypes that anchor market structure through distinct capability configurations. Stryker represents integrated materials science positioning with captive polymer-grade production. Zimmer Biomet occupies the dedicated manufacturing foundry tier with concentration in Warsaw, Indiana. Medtronic exemplifies advanced protocol validation positioning through wear-testing capabilities exceeding ISO benchmarks. These three entities collectively illustrate how regulatory pathway efficiency, materials science integration, and geographic manufacturing placement stratify competitive access to hospital procurement committees and ambulatory surgical center networks.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Medtronic |
| Johnson & Johnson |
| Globus Medical |
| NuVasive |
| B. Braun Melsungen AG |
| Centinel Spine |
| Orthofix Medical |
| Others |
Supply Flow & Price Mechanics
FDA premarket approval pathways gate both supply qualification and price differentiation simultaneously, as PMA-certified manufacturers command premium positioning while uncertified competitors remain locked below reimbursement eligibility thresholds. Hospital procurement committees in the United States leverage this regulatory filter to consolidate vendor lists around motion-preserving outcomes data, compressing margin available to standard-tier suppliers.
Pricing Analysis
Configured-to-order pricing for patient-specific sizing and instrumentation sets commands spreads against standard catalog pricing. Three-tier pricing structure across premium, standard, and economy levels reflects FDA PMA tier, ISO 18192-1 wear-testing certification, and geographic delivery cost from Warsaw, Indiana or Memphis, Tennessee manufacturing clusters. Cost compression in the economy tier is intensifying because ambulatory surgical centers unbundle implant costs from procedure bundles. Integrated delivery networks with dedicated spine service lines exhibit lowest price sensitivity; mid-tier hospitals with limited surgeon volume show highest.
Supply Chain Analysis
German and Japanese specialized foundries for cobalt-chromium-molybdenum alloy feedstock create a chokepoint that underwrites endplate cost volatility for metal-on-polymer constructs. Supply draws from the United States for PEEK substrate polymerization, Germany for precision alloy casting, and Japan for pyrolytic carbon core fabrication. Raw material dependencies center on medical-grade polyethylene resin, cobalt-chromium alloy ingots, and titanium powder for 3D-printed lattices. Single-source vulnerability runs through Ruhr region foundry concentration. Distribution runs through direct salesforce consignment inventory managed from Indiana and Tennessee clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial disc replacement sits in early-cycle expansion as anterior cervical discectomy and fusion alternatives gain surgical acceptance among younger patient cohorts seeking motion preservation.
For Market Incumbents: Compound defensive positioning through backward integration into PEEK substrate production and captive wear-testing protocol capabilities exceeding ISO 18192-1 benchmarks. Threat from bio-ceramic convergence at academic medical centers demands accelerated pyrolytic carbon core R&D investment. Priority lever rests on M&A absorption of tribology talent scarce outside established orthopedics clusters. For New Entrants and Emerging Players: Lead with India PLI scheme capture for Asia-Pacific cost reduction and contract manufacturing qualification. Most penetrable white-space sits in cervical disc outpatient migration at Florida and Texas ambulatory surgical centers where certificate-of-need exemptions accelerate site-of-service shift. Go-to-market angle targets integrated delivery network procurement committees with unbundled implant cost transparency. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed spine specialists possessing PMA pathway expertise but lacking materials science integration. Long-term viability frames around five-to-ten year CMS reimbursement determination windows for cervical total disc replacement. Acquisition target archetype includes tribology-capable manufacturers in Warsaw, Indiana or Memphis, Tennessee clusters. Signal to watch is EU MDR recertification timeline compression for legacy CE-marked lumbar disc portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | PMA certification unlocks CMS reimbursement eligibility and hospital vendor list access. |
| CE Marking Recertification | MDR transition compliance preserves European market access for legacy lumbar portfolios. |
| Hospital System Partnership | Integrated delivery network contracts secure consignment inventory placement and surgeon training. |
| Backward Integration into PEEK | Captive polymer-grade substrate production reduces input cost volatility from specialized suppliers. |
| Reimbursement Strategy | CMS coding advocacy expands addressable patient volumes regardless of implant innovation trajectories. |
Methodological Framework
A spread of perspectives from spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions. Primary interviews combined with secondary validation against FDA PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO certification registries. Bottom-up implant volume modeling triangulated against top-down market sizing from industry association data.
Segmentation dimensions modeled include anatomical target, material composition, end-user channel, and geographic regulatory cluster across the analysis window. CAGRs derived from procedure volume trajectories, reimbursement code expansion patterns, and manufacturing capacity buildout timelines. Industry-specific forecast inputs incorporate PEEK substrate supply constraints and EU MDR notified body capacity.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement determination favorability or PMDA harmonization acceleration would require recalibration. Forecasts reflect documented assumptions regarding ambulatory surgical center site-of-service migration velocity and bio-ceramic adoption curves at academic medical centers. Practitioners should keep alternative scenarios live as FDA PMA pathway efficiency and EU MDR transition friction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Positive Airway Pressure Devices Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Prefilled Glass Syringes Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Indonesia Devices Market
Medical Devices
Heating Pads Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Knee Braces Market
Medical Devices
Middle East and Africa Aligner Sheet Market
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Global IV Infusion Pump Accessories Market