
 Implantable Drug Eluting Devices Market | 2026-2036
Implantable Drug Eluting Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Drug Eluting Devices Market Foresight
Remote monitoring subscriptions for implantable drug delivery systems is repositioning how manufacturers capture lifetime value from each device placement. Medtronic leverages its cardiac rhythm management infrastructure to bundle digital follow-on services with drug-eluting implants. Abbott Laboratories anchors its vascular portfolio in next-generation polymer technologies that extend drug release kinetics. Boston Scientific Corporation competes through interventional cardiology specialization across multiple geographies.
Implantable drug eluting devices incorporate biocompatible polymers or metallic substrates engineered to release therapeutic agents at controlled rates over weeks to months, primarily serving localized treatment of coronary artery disease, malignant tumors, and chronic pain conditions. Stents dominate current revenue flows due to established cardiology reimbursement codes and high procedural volumes, while oncology-targeted pumps represent the fastest-expanding margin pool as precision dosing protocols gain clinical traction. Capsule-based neurology applications remain nascent with concentrated R&D investment from specialized players seeking first-mover advantage in blood-brain barrier delivery.
FDA premarket notification requirements, EU MDR technical documentation mandates, and Japan PMDA quality management system inspections collectively elevate barriers for new entrants while reinforcing incumbent compliance infrastructure. These frameworks shape demand by mandating extended follow-up data that favors larger manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving pharmacovigilance expectations for combination products as regulators increasingly scrutinize drug-device interaction profiles beyond traditional device safety endpoints.
Market Dynamics
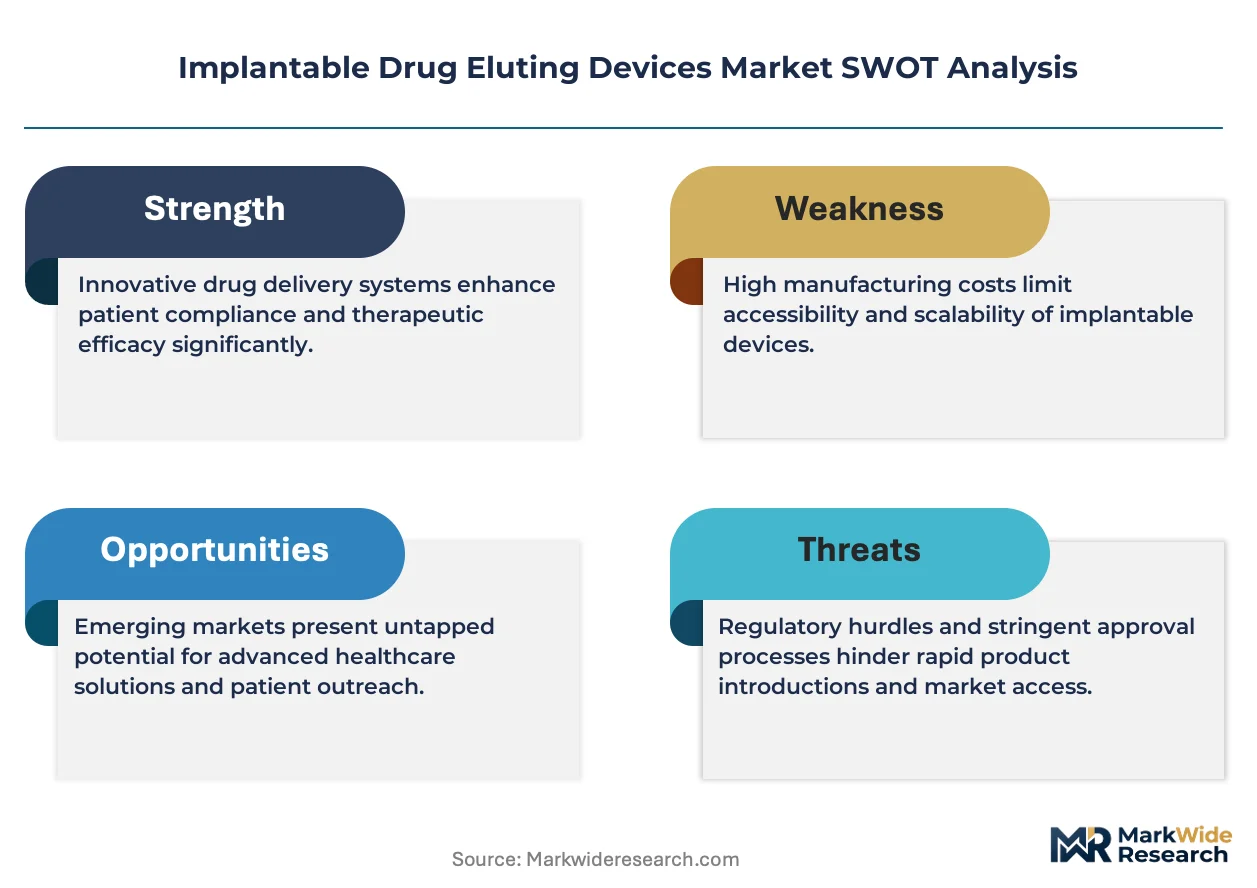
Polymer degradation kinetics engineering is compressing development cycles for sustained-release coatings while simultaneously elevating FDA premarket approval evidence requirements for combination products. This tension between technical capability and regulatory burden defines competitive positioning.
Growth Catalysts
- EU MDR conformity pathways:Streamlined technical documentation for established drug-device combinations accelerates market access for manufacturers with existing quality management infrastructure.
- Cardiology intervention volumes:Hospital procurement of drug-eluting stents expands as aging patient populations in Japan, Germany, and the United States drive procedural demand.
- Bioresorbable polymer platforms:Next-generation materials eliminate permanent implant foreign body response concerns while enabling complete drug payload delivery.
Market Restraints
- Platinum-iridium alloy supply concentration:Stent substrate material sourcing depends on South African and Russian mining operations subject to export volatility.
- Japan PMDA quality management inspections:Extended facility audit timelines delay product registration for manufacturers lacking prior Japanese market presence.
- Systemic chemotherapy protocols:Oncology pump adoption faces competition from intravenous infusion standards entrenched in hospital pharmacy workflows.
Strategic Opportunities
- Blood-brain barrier delivery:Capsule-based neurology applications for Parkinson's and Alzheimer's therapeutics remain underpenetrated with concentrated R&D investment potential.
- Remote monitoring integration:Digital follow-on services bundled with implantable drug delivery systems capture lifetime value beyond device placement.
- Precision dosing protocols:Oncology-targeted pumps gain clinical traction as tumor board protocols incorporate pharmacokinetic modeling.
Industry Challenges
- Combination product pharmacovigilance:Regulators scrutinize drug-device interaction profiles beyond traditional device safety endpoints, requiring specialized post-market surveillance infrastructure.
- Polymer synthesis scale-up:Bench-to-manufacturing translation for novel biodegradable coatings demands capital-intensive cleanroom expansion.
- Cross-functional regulatory expertise:FDA premarket notification preparation requires teams fluent in both pharmaceutical chemistry and medical device engineering standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Drug Eluting Devices Market |
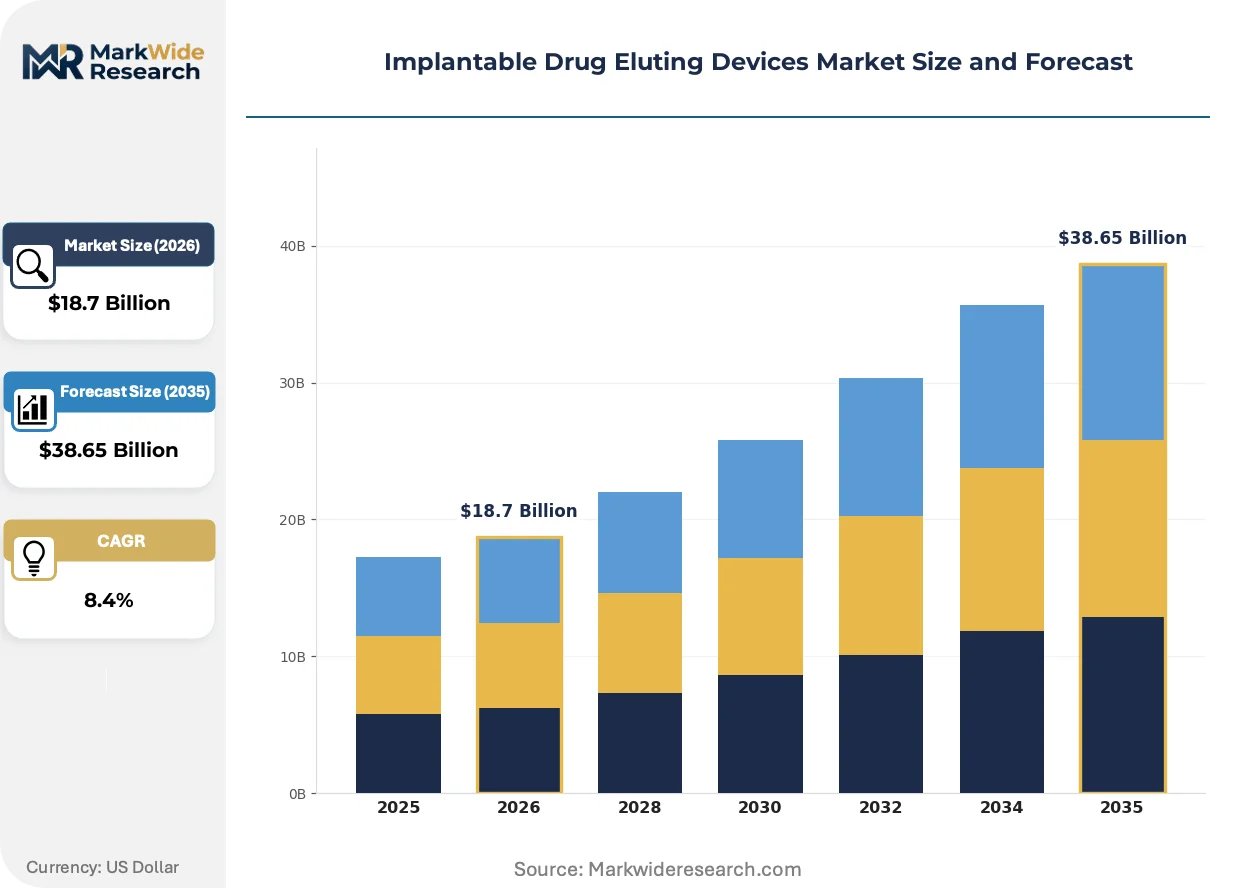
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Scaffolds, Pumps, Capsules Therapy Area: Cardiology, Oncology, Neurology, Orthopedics End User: Hospitals, Clinics, Research Labs, Home Care Delivery Mode: Local Delivery, Systemic Delivery, Intravenous Delivery, Transdermal Delivery |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific Corporation, Johnson & Johnson, Bayer AG, Bausch and Lomb Incorporated, Merck & Co., Inc., Pfizer Inc., BIOTRONIK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Drug Eluting Devices Market Shifts & Advancements
Controlled-release engineering is converging with digital health infrastructure to transform implantable therapeutics from passive delivery vehicles into adaptive treatment systems. This integration is reshaping how manufacturers design clinical evidence and capture recurring revenue.
Electroactive polymer coatings is electrifying the competitive landscape for coronary stent differentiation. These materials enable voltage-triggered drug release synchronized with cardiac electrical activity. Interventional cardiologists in tertiary care centers are piloting this capability for patients with complex lesion morphology. The technology is compressing the timeline for personalized antiproliferative dosing while expanding the addressable patient pool beyond standard DES indications.
EU MDR Article 117 technical documentation mandates now require notified body involvement for all drug-device combination products previously self-certified under the medical device directive. Manufacturers must generate additional clinical performance data or leverage medicinal product marketing authorizations. Cardiology stent portfolios face the steepest compliance burden due to legacy device classifications, with several firms restructuring European distribution to concentrate resources on high-volume SKUs.
Hospital value analysis committees now mandate total cost-of-ownership modeling that incorporates device price, procedure time, readmission risk, and downstream antiplatelet therapy burden. This purchasing behavior is displacing physician preference item autonomy in United States cardiovascular service lines. Integrated delivery networks in Texas and Florida are consolidating vendor contracts to three-year sole-source agreements with performance guarantees on target lesion revascularization rates.
Implantable Drug Eluting Devices Market Segmentation
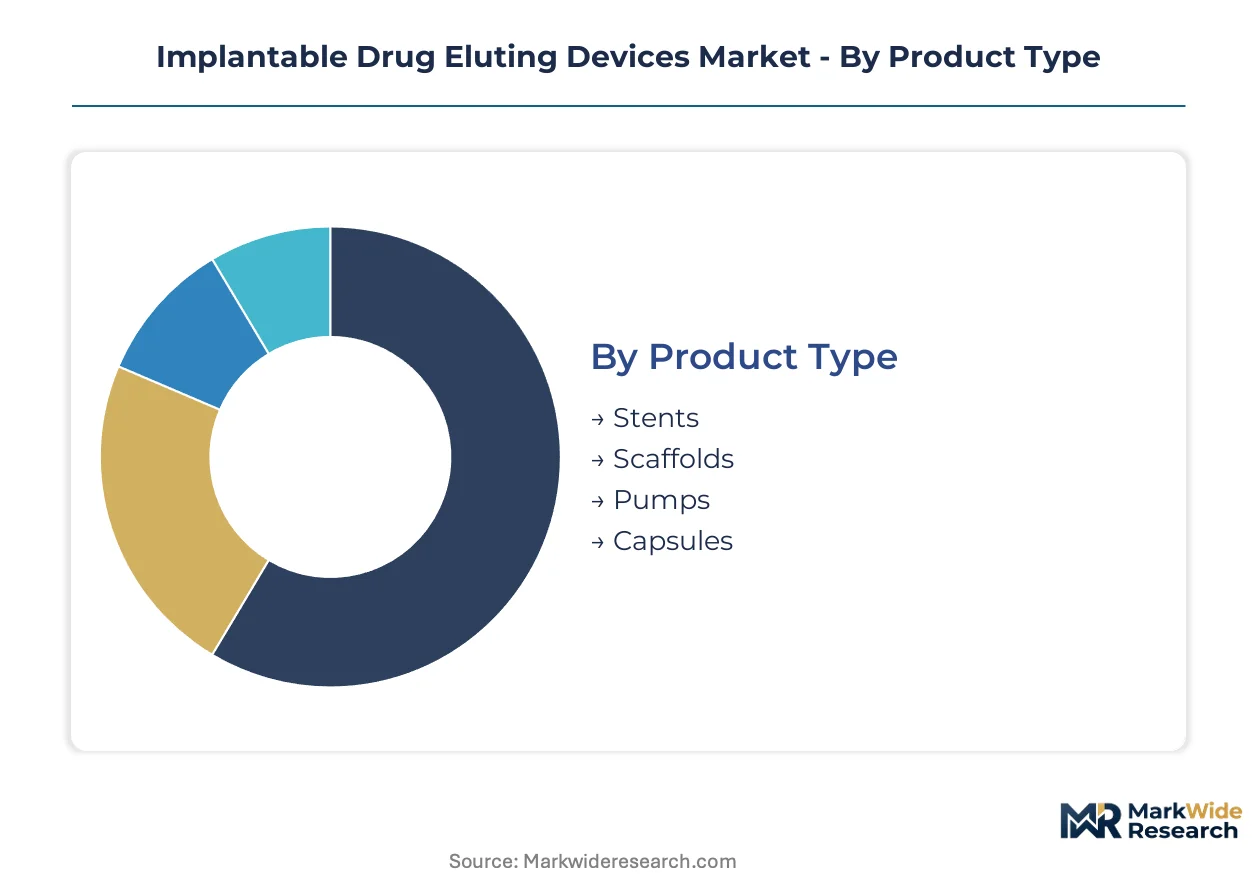
Segmentation in implantable drug eluting devices determines which regulatory pathways apply and where manufacturers must build specialized compliance infrastructure. Product type and therapy area classifications carry distinct FDA premarket approval and EU MDR conformity burdens that shape competitive entry costs.
Product Type:
Stents and scaffolds trigger FDA combination product reviews requiring simultaneous pharmaceutical chemistry and device engineering expertise, while pumps and capsules navigate device-centric pathways with supplemental drug quality documentation.
- Stents:Metallic or polymeric tubular structures with drug-eluting coatings deliver antiproliferative agents directly to coronary lesions. Hospital cath labs in the United States, Germany, and Japan account for the bulk of procurement volume as cardiovascular intervention rates climb among aging populations. FDA premarket approval mandates 12-month angiographic follow-up data that favors established manufacturers with dedicated clinical affairs teams.
- Scaffolds:Bioresorbable vascular platforms eliminate permanent foreign body presence while enabling complete drug payload release. European interventional cardiologists have driven early adoption of Abbott's Absorb platform and competing magnesium-based alternatives. EU MDR Article 117 technical documentation requirements now demand notified body involvement for all drug-device combinations, extending registration timelines for scaffold portfolios previously self-certified under the medical device directive.
- Pumps:Implantable infusion systems enable chronic delivery of oncology therapeutics and pain management agents with programmable dosing profiles.
- Capsules:Miniaturized reservoir devices target blood-brain barrier penetration for neurology applications in Parkinson's and Alzheimer's treatment protocols.
Stents sit at the top of the volume ranking, with scaffolds climbing the fastest as bioresorbable platforms gain European reimbursement traction.
Therapy Area:
Cardiology commands the steepest regulatory evidence requirements due to legacy device classifications, while oncology and neurology segments attract concentrated R&D investment as precision dosing protocols reshape clinical workflows.
- Cardiology:Coronary and peripheral artery disease applications dominate current revenue flows through established reimbursement codes and high procedural volumes. Drug-eluting stents face hospital value analysis committee scrutiny in United States integrated delivery networks, where total cost-of-ownership modeling now supersedes physician preference item autonomy.
- Oncology:Targeted chemotherapeutic delivery via implantable pumps represents the fastest-expanding margin pool as tumor board protocols incorporate pharmacokinetic modeling. Platinum-iridium alloy supply concentration from South African and Russian mining operations constrains substrate sourcing for certain pump architectures.
- Neurology:Blood-brain barrier delivery applications for neurodegenerative diseases remain underpenetrated with first-mover advantage contested by specialized players.
- Orthopedics:Antibiotic-loaded bone cements and joint spacers address surgical site infection prophylaxis in arthroplasty and trauma procedures.
Cardiology maintains volume leadership, though oncology is expanding most quickly as precision dosing gains clinical traction.
End User:
Hospital procurement concentration determines pricing leverage and contract structure complexity, while research labs and home care channels impose divergent technical support and training cost burdens on manufacturers.
- Hospitals:Tertiary cardiovascular centers and oncology institutes drive bulk purchasing through multi-year sole-source agreements with performance guarantees. Texas and Florida integrated delivery networks have consolidated vendor contracts to three-year arrangements with target lesion revascularization rate benchmarks.
- Clinics:Ambulatory surgical centers and specialty interventional suites seek streamlined device portfolios with reduced inventory complexity.
- Research Labs:Academic medical centers and contract research organizations generate clinical trial demand for next-generation polymer platforms and novel drug-device combinations.
- Home Care:Patient-managed infusion systems for chronic pain and palliative care require simplified interfaces and remote monitoring integration.
Hospitals command the volume ranking, with home care gaining share fastest as remote monitoring subscriptions reposition manufacturer revenue capture.
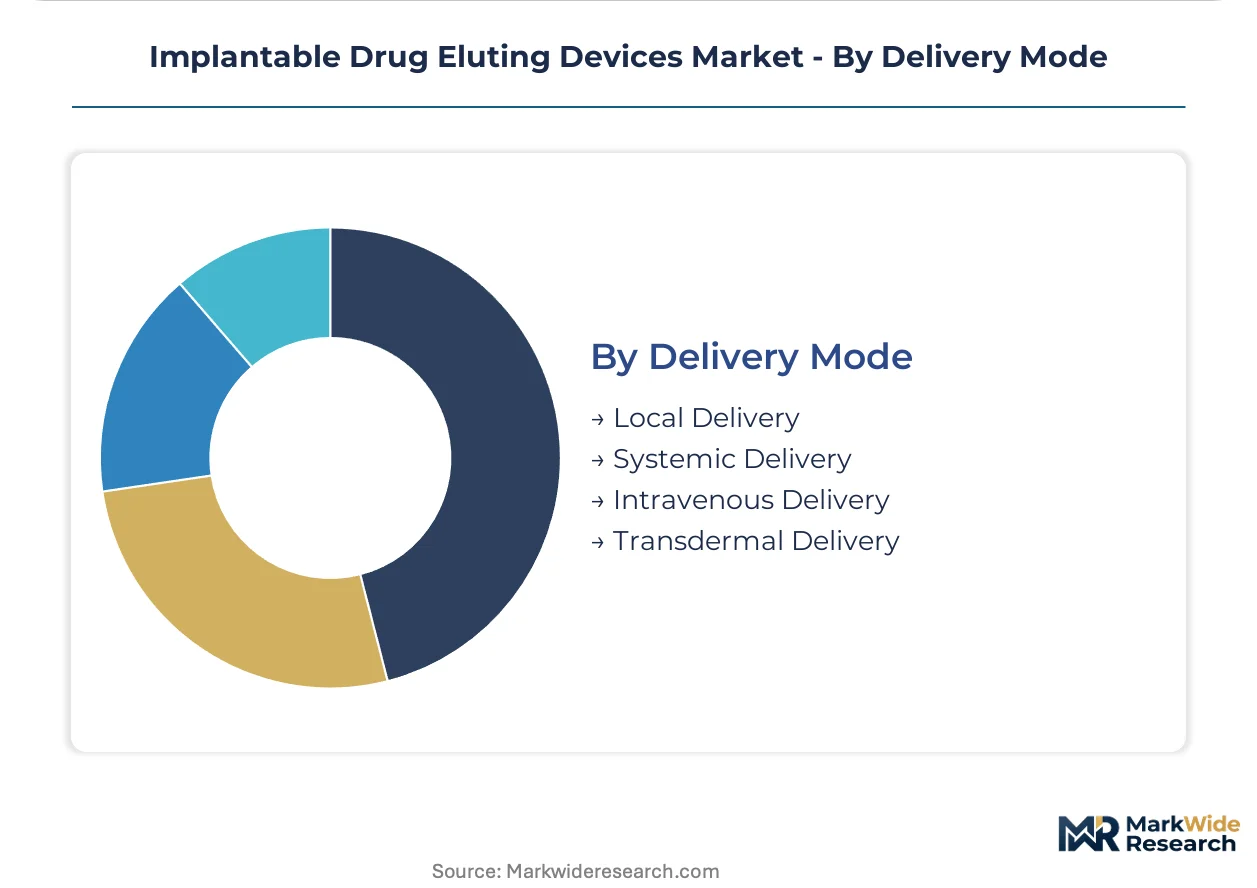
Delivery Mode:
Local delivery architectures align with implantable device value propositions, while systemic and intravenous pathways face competition from established hospital pharmacy workflows that constrain pump adoption.
- Local Delivery:Site-specific therapeutic release minimizes systemic exposure and enables higher local drug concentrations. Coronary stents and orthopedic antibiotic carriers exemplify this approach with established reimbursement pathways in United States, German, and Japanese markets.
- Systemic Delivery:Implantable pumps achieve chronic circulatory access for chemotherapy and analgesic protocols, competing against intravenous infusion standards entrenched in hospital pharmacy operations.
- Intravenous Delivery:Peripherally inserted central catheter alternatives and port systems serve intermediate-duration therapeutic courses.
- Transdermal Delivery:Non-implantable patches and iontophoresis systems address pain management and hormone replacement with lower regulatory barriers.
Local delivery sits at the top of the volume ranking, with systemic delivery climbing the fastest as oncology pump protocols gain tumor board acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States outpaces Japan in drug-eluting stent procedure volumes, yet Germany's integrated care networks achieve faster bioresorbable scaffold adoption curves. Hospital procurement concentration and regulatory clarity determine where manufacturers prioritize market access investments.
United States
Integrated delivery networks in Texas and Florida consolidate vendor contracts to three-year sole-source agreements with performance guarantees on target lesion revascularization rates. FDA premarket approval pathways mandate 12-month angiographic follow-up data that favors established manufacturers with dedicated clinical affairs capacity. The Minneapolis-St. Paul corridor hosts cardiac rhythm management infrastructure that supports remote monitoring subscription bundling.
Germany
EU MDR Article 117 technical documentation requirements now demand notified body involvement for all drug-device combinations, extending registration timelines for scaffold portfolios. Interventional cardiologists in Baden-Württemberg drive early adoption of magnesium-based bioresorbable platforms. The Rhine-Main cluster concentrates quality management infrastructure serving European conformity assessment.
Japan
PMDA quality management system inspections impose extended facility audit timelines that delay product registration for manufacturers lacking prior market presence. Aging demographics in Kanto and Kansai regions drive cardiovascular intervention volume expansion. Tokyo-based procurement committees emphasize total cost-of-ownership modeling incorporating device price and downstream antiplatelet therapy burden.
China
NMPA marketing authorization pathways for combination products require localized clinical trial data that extends registration timelines for multinational firms. Provincial procurement consortia in Jiangsu and Guangdong drive price compression on coronary stent categories. The Yangtze River Delta concentrates polymer synthesis scale-up capabilities for domestic manufacturers.
Switzerland
Swissmedic conformity assessment procedures for drug-device combinations leverage mutual recognition agreements with EU notified bodies while maintaining distinct pharmacovigilance reporting requirements. Basel-area pharmaceutical-device hybrid firms anchor European headquarters functions for global portfolios. The Lake Geneva corridor hosts specialized CRO infrastructure supporting combination product clinical development.
Implantable Drug Eluting Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement concentration favoring integrated portfolios over single-product vendors. The vendor base organizes into three tiers: diversified medtech conglomerates with cardiac rhythm management infrastructure, interventional cardiology pure-plays with polymer engineering capabilities, and pharmaceutical-device hybrids leveraging medicinal product authorizations. Strategic moves center on remote monitoring subscription bundling and EU MDR technical documentation consolidation.
Within the diversified medtech tier, Medtronic, Abbott Laboratories, and Boston Scientific Corporation exemplify positioning built on cardiac rhythm management infrastructure, polymer engineering specialization, and interventional cardiology geographic coverage respectively. These firms anchor competitive dynamics through bundled digital follow-on services, next-generation release kinetics platforms, and multi-regional cath lab penetration.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Bayer AG |
| Bausch and Lomb Incorporated |
| Merck & Co., Inc. |
| Pfizer Inc. |
| BIOTRONIK |
| Others |
Supply & Pricing Matrix
Premium polymer engineering certification against standard metallic substrate tiers bifurcates procurement decisions across United States hospital systems and German cath lab networks, with FDA premarket approval status determining which tier commands three-year sole-source contract eligibility while South African platinum-iridium sourcing constraints filter through to device landed costs.
Pricing Analysis
Capacity additions in Chinese polymer synthesis facilities are reshaping price floors for biodegradable coating substrates, compressing margins for European manufacturers reliant on Rhine-Main cluster production. Pricing stratifies across premium bioresorbable scaffolds, standard drug-eluting stents, and economy metallic bare-metal alternatives, with FDA 510(k) clearance tier and EU MDR notified body certification as primary differentiation drivers. Cost compression in the standard stent tier intensifies as Jiangsu provincial procurement consortia drive tender-based price erosion. Hospital value analysis committees in Texas integrated delivery networks demonstrate highest price sensitivity, while Japanese tertiary cardiovascular centers prioritize total cost-of-ownership modeling over unit price.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital GPOs and German university hospital procurement committees require qualified backup suppliers for all platinum-iridium alloy and bioresorbable polymer inputs, extending vendor qualification timelines. Manufacturing concentrates in United States, Germany, and China, with the Yangtze River Delta anchoring polymer synthesis scale-up and Minneapolis-St. Paul hosting cardiac rhythm management device integration. Raw material dependencies include South African platinum-iridium mining outputs, Chinese poly-lactic acid polymer feedstocks, and Swiss precision machining components. Single-source vulnerability concentrates in platinum-group metal refining capacity. Distribution runs through hospital GPO contracts in North America, regional medical device distributors in Europe, and direct manufacturer-to-hospital arrangements in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Implantable drug eluting devices function as a stable compounder anchored by aging demographic tailwinds in Japan, Germany, and the United States that sustain cardiovascular intervention volume growth regardless of cyclical healthcare spending fluctuations.
For Market Incumbents: Deepen backward integration into polymer synthesis capabilities to secure supply continuity against South African mining volatility, while consolidating EU MDR technical documentation resources onto high-volume stent SKUs to streamline notified body engagement. Cardiology reimbursement code stability provides defensive moat, though emerging bioresorbable scaffold substitutes threaten metallic stent margin pools.
For New Entrants and Emerging Players: Launch via specialized CRO partnerships targeting blood-brain barrier delivery applications for neurology, where regulatory pathways remain less saturated than cardiology. Oncology-targeted pumps for precision chemotherapy protocols represent the most penetrable segment, with tumor board pharmacokinetic modeling adoption creating clinical pull-through opportunity.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance burdens favor manufacturers with dedicated regulatory affairs infrastructure over sub-scale competitors. The five-to-ten year viability window rewards platforms with remote monitoring subscription bundling capabilities. Acquisition targets include pharmaceutical-device hybrids leveraging medicinal product authorizations for streamlined combination product pathways. The signal to watch is Japan PMDA quality management inspection queue length as indicator of market access friction.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 117 compliance unlocks German and Swiss hospital procurement channels. |
| Hospital System Partnership | Texas IDN sole-source agreements with target lesion revascularization guarantees secure volume. |
| Software Companion Development | Remote monitoring subscriptions bundled with cardiac implants capture lifetime value. |
| Reimbursement Strategy | Japanese procedural fee clarity in Kanto and Kansai regions accelerates adoption curves. |
| FDA Submission | Premarket approval with 12-month angiographic data defends against bare-metal competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional cardiologists, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS Medicare procedure volume data, and hospital procurement database records. Bottom-up device placement volume estimates triangulated against top-down market sizing from manufacturer revenue disclosures.
Historical reference periods anchored the projection horizon through procedure volume trend extrapolation and reimbursement code stability assessment. Segmentation dimensions modeled include product type, therapy area, delivery mode, end user channel, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline penetration rates. Forecast inputs incorporated polymer degradation kinetics advancement timelines and digital health infrastructure adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR technical documentation timeline extensions or platinum-iridium export restriction scenarios. Deviation in Japan PMDA inspection queue clearance rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Suction Catheters Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Pocket Ventilation Systems Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
Eye Massage Device Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Surgical Smart Glasses Market
Medical Devices
Global Brachytherapy Devices Market