
 Absorbable Heart Stent Market | 2026-2036
Absorbable Heart Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable Heart Stent Market Analysis
Drug-eluting specification tiers are rotating toward next-generation polymer platforms with controlled degradation profiles. Abbott Laboratories leverages its vascular device heritage to sustain leadership in coronary scaffold development. Biotronik SE & Co. KG anchors its position through specialized expertise in bioabsorbable magnesium systems. Boston Scientific Corporation competes by extending its interventional cardiology portfolio across multiple absorbable material platforms.
An absorbable heart stent is a temporary vascular scaffold fabricated from biodegradable polymers or metals such as polylactic acid or magnesium alloys, engineered to provide luminal support for six months to three years before complete resorption. Its primary purpose is restoring blood flow while eliminating long-term complications associated with permanent metal implants such as late stent thrombosis and vessel restenosis. Polymer-based stents dominate current clinical adoption due to mature manufacturing processes and established safety profiles, while drug-eluting variants capture the fastest growth as antiproliferative coatings enhance target lesion revascularization outcomes. Metal stents occupy a specialized niche where magnesium alloys offer superior radial strength during the acute healing phase.
FDA breakthrough device designation and EMA conditional approval pathways shape market access timelines by compressing clinical validation requirements for novel absorbable platforms. The EU Medical Device Regulation imposes stricter post-market surveillance obligations that elevate documentation burdens for polymer degradation data. Japan's PMDA maintains distinct biocompatibility testing standards that influence regional product registration strategies. Stakeholders must monitor evolving reimbursement thresholds for bioresorbable scaffolds against conventional drug-eluting metal stents as health technology assessment bodies recalibrate value metrics.
Market Dynamics
Polymer degradation science is fragmenting the competitive landscape as manufacturers race to engineer scaffolds with predictable resorption timelines that match vascular healing biology.
Growth Catalysts
- Breakthrough Device Designation:FDA's accelerated pathway compresses clinical validation timelines for novel absorbable platforms, reducing time-to-market by 12-18 months for qualifying coronary scaffolds.
- Coronary Intervention Expansion:Tertiary hospital cardiology departments in the United States, Germany, and Japan are systematically replacing permanent metallic implants with bioresorbable alternatives in complex lesion cases.
- Magnesium Alloy Innovation:Bioabsorbable metal systems deliver superior radial strength during acute healing phases, capturing specialized niches where polymer flexibility proves insufficient.
Market Restraints
- Degradation Data Burden:EU Medical Device Regulation imposes stricter post-market surveillance obligations that elevate documentation requirements for polymer breakdown kinetics.
- Reimbursement Compression:Health technology assessment bodies in Germany and Japan are recalibrating value metrics, forcing bioresorbable scaffolds to demonstrate superior cost-effectiveness against conventional drug-eluting metal stents.
- Manufacturing Scale Constraints:Controlled polymer crystallization processes limit batch consistency, constraining supply expansion for drug-eluting specification tiers.
Strategic Opportunities
- Pediatric Vascular Applications:Absorbable scaffolds eliminate growth-related complications from permanent implants in congenital heart defect repairs, opening pediatric cardiology segments currently served by adult-device off-label use.
- Peripheral Artery Disease:Bioabsorbable platforms for femoropopliteal lesions address vessel remodeling needs absent in coronary anatomy, with Japan's PMDA maintaining distinct testing standards that favor early-mover registration.
- Next-Generation Polymer Platforms:Controlled degradation profiles enable synchronized drug release matching tissue regeneration timelines, creating premium positioning against first-generation polylactic acid systems.
Industry Challenges
- Biocompatibility Testing Complexity:Japan's PMDA maintains distinct standards for inflammatory response assessment, forcing manufacturers to duplicate validation protocols across regulatory jurisdictions.
- Interventional Cardiologist Training:Deployment techniques for absorbable scaffolds differ substantially from metallic stent procedures, requiring dedicated proctoring programs that slow hospital adoption curves.
- Long-Term Residue Characterization:Complete polymer resorption verification demands extended follow-up protocols that strain clinical trial retention rates and regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable Heart Stent Market |
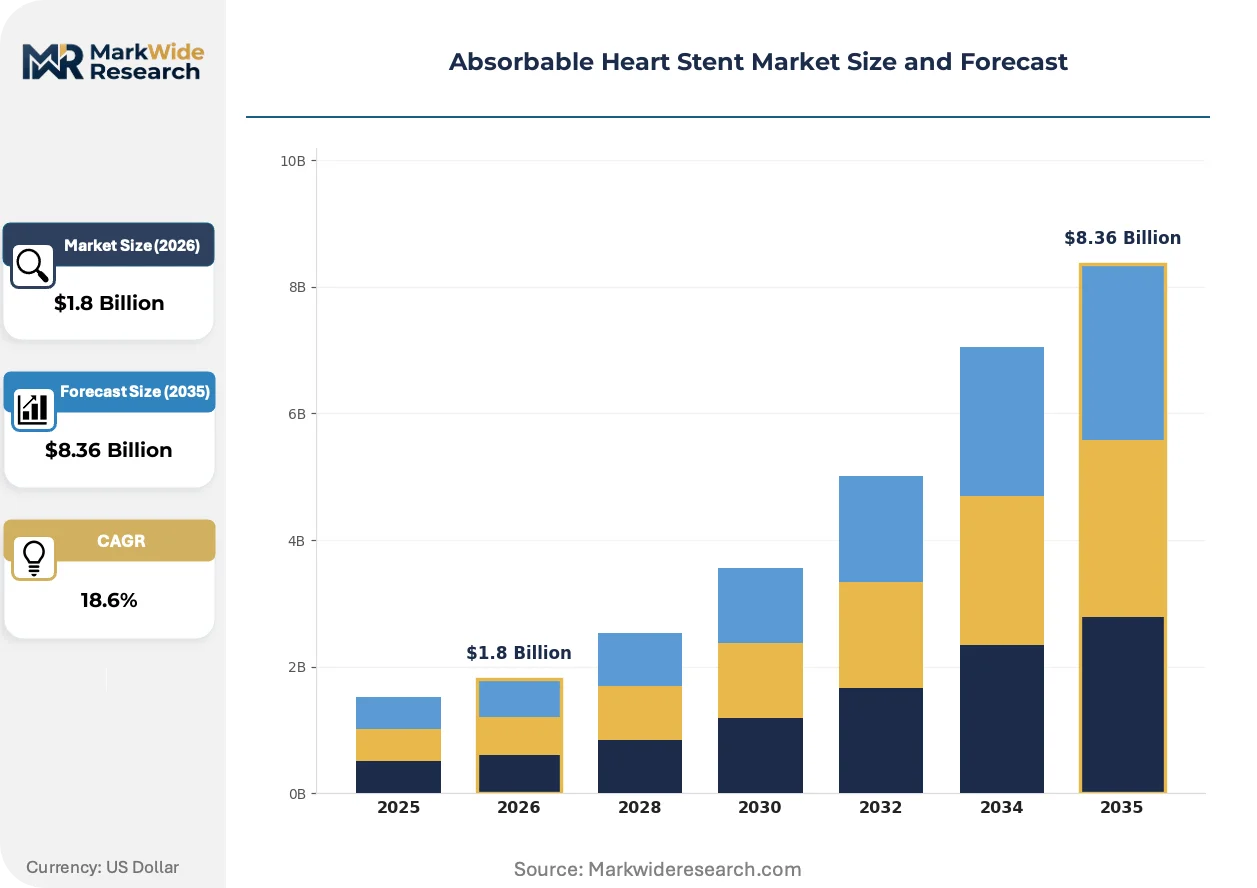
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based Stents, Metal Stents, Hybrid Stents, Drug-Eluting Stents Application: Coronary Intervention, Peripheral Intervention, Vascular Surgery, Electrophysiology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Delivery Mode: Invasive, Minimally Invasive, Percutaneous, Transluminal |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Biotronik SE & Co. KG, Terumo Corporation, MicroPort Scientific Corporation, Elixir Medical Corporation, REVA Medical, LLC, Arterius Ltd., Lepu Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable Heart Stent Market Emerging Trajectories
Active pharmaceutical integration with scaffold matrices is reshaping how antiproliferative therapies synchronize with vascular healing biology.
Drug-polymer matrix engineering is fragmenting the product landscape as manufacturers develop proprietary coating technologies that modulate sirolimus analog release over 90-day to 12-month windows. Tertiary hospital catheterization laboratories in Germany and Japan are piloting these next-generation platforms for diabetic patient cohorts with heightened restenosis risk. The structural consequence is compressing differentiation around degradation kinetics rather than mechanical performance alone.
EU Medical Device Regulation's post-market surveillance requirements are forcing manufacturers to establish real-world evidence registries tracking scaffold performance across diverse lesion morphologies. Industrial consequence includes elevated compliance costs that favor scaled players with existing quality management infrastructure. Drug-eluting polymer platforms face the steepest documentation burdens as degradation-byproduct characterization requirements expand.
Hospital procurement committees are unbundling device selection from physician preference cards, inserting value-analysis teams into stent selection workflows. Interventional cardiology departments at US academic medical centers now face mandatory health technology assessment reviews comparing bioresorbable scaffold total cost of ownership against metallic alternatives. This pattern concentrates most visibly in Medicare-dependent health systems where bundled payment models amplify device cost sensitivity.
Absorbable Heart Stent Market Segmentation
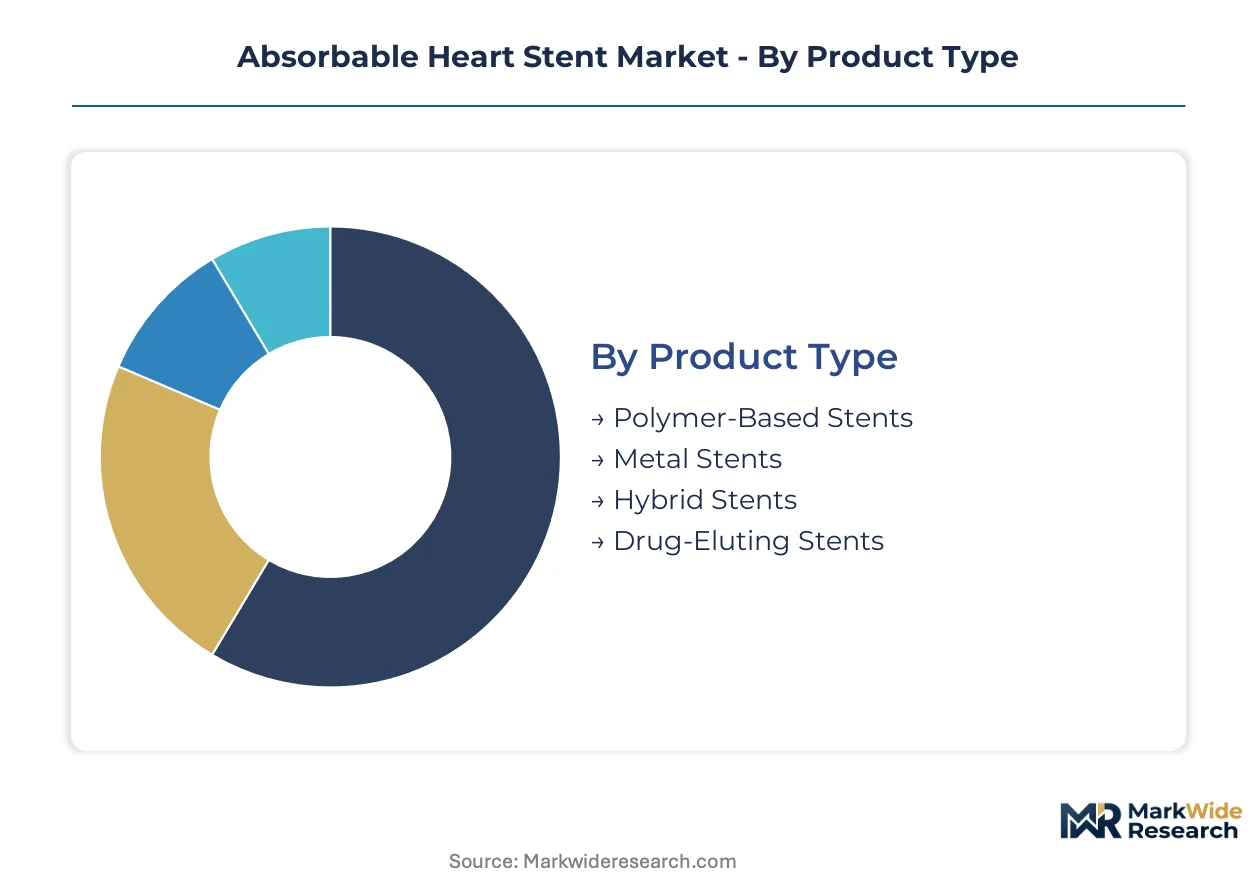
Absorbable heart stent manufacturers configure product portfolios around four intersecting dimensions that determine reimbursement eligibility, regulatory pathway selection, and clinical training requirements. Each segmentation axis carries distinct margin structures and competitive intensity profiles that shape capital allocation decisions.
Product Type:
Domestic production concentrates polymer-based systems in the United States and Germany, while magnesium alloy metal stents flow primarily from Austrian and Japanese manufacturing sites for regional distribution.
- Polymer-Based Stents:Fabricated from polylactic acid or polyglycolic acid matrices with controlled crystallinity to modulate radial strength degradation over 18-24 month resorption windows. Demand clusters in German tertiary hospitals where EMA post-market surveillance registries track long-term biocompatibility outcomes under MDR requirements.
- Drug-Eluting Stents:Integrate sirolimus analogs or paclitaxel within polymer matrices to synchronize antiproliferative release with vascular healing phases. Japanese PMDA breakthrough designations for next-generation coatings are accelerating hospital adoption in Tokyo and Osaka catheterization laboratories.
- Metal Stents:Magnesium alloy scaffolds provide superior acute-phase radial strength for calcified lesions where polymer flexibility proves inadequate. Austrian and Japanese facilities supply these systems primarily to domestic interventional cardiology networks.
- Hybrid Stents:Combine polymer sleeves with metallic cores to balance immediate mechanical support against complete resorption objectives.
Polymer-based stents hold the largest share; momentum sits with drug-eluting variants as antiproliferative coating technologies mature.
Application:
Volume distribution across applications reflects reimbursement coding complexity and lesion morphology specialization requirements.
- Coronary Intervention:Dominates procedural volume with absorbable scaffolds deployed in left anterior descending and circumflex artery lesions where long-term vessel remodeling benefits offset premium device costs. US Medicare bundled payment models in academic medical centers are compressing margins for standard polymer platforms.
- Peripheral Intervention:Addresses femoropopliteal and below-the-knee lesions where vessel diameter variability and mechanical stress demand scaffold designs with extended structural integrity. German hospital procurement committees are piloting bioabsorbable platforms for diabetic patient cohorts with heightened restenosis risk.
- Vascular Surgery:Open surgical implantation of absorbable scaffolds for aortic arch and carotid applications remains investigational with limited commercial reimbursement.
- Electrophysiology:Experimental applications in pulmonary vein isolation procedures leverage resorbable properties to reduce long-term thromboembolic complications.
Coronary intervention commands current revenue concentration; peripheral applications are climbing the fastest as Japan's PMDA maintains distinct testing standards favoring early-mover registration.
End User:
Customer type segmentation determines sales force structure and clinical training investment intensity.
- Hospitals:Tertiary cardiology departments in the United States, Germany, and Japan drive specification tier adoption with dedicated proctoring programs for absorbable scaffold deployment techniques.
- Ambulatory Surgical Centers:Limited penetration due to capital equipment requirements and emergency backup capabilities for procedural complications.
- Specialty Clinics:Concentrated in German outpatient interventional networks where regional reimbursement frameworks support same-day discharge protocols.
- Research Institutes:Academic medical centers in Boston and Heidelberg anchor clinical trial recruitment for next-generation polymer platforms.
Hospitals absorb the dominant procurement volume; specialty clinics are gaining share fastest as German outpatient reimbursement frameworks mature.
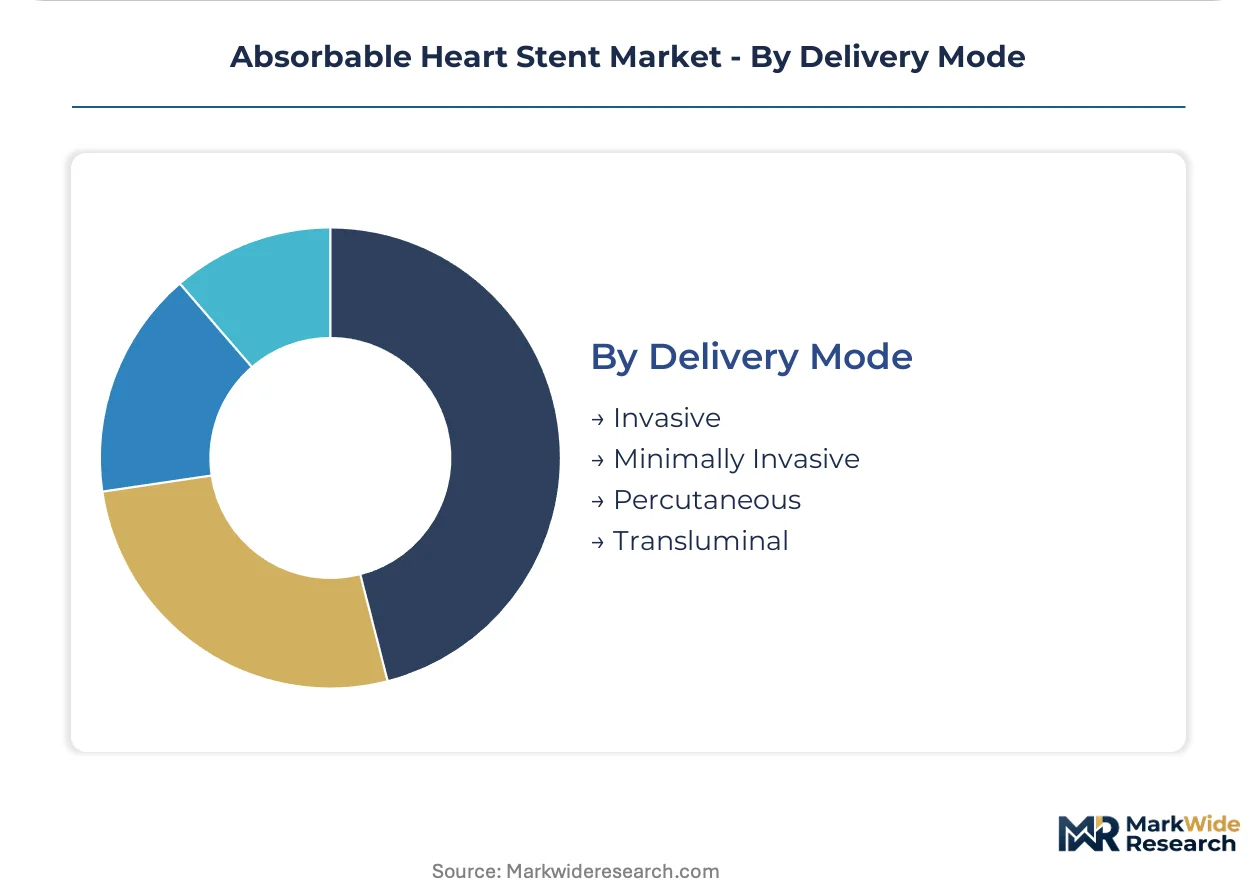
Delivery Mode:
Deployment technique segmentation shapes device engineering specifications and physician training curriculum design.
- Minimally Invasive:Transradial and transfemoral catheter-based delivery dominates commercial volume with 6-French compatible scaffold profiles enabling outpatient procedures.
- Percutaneous:Standard access methodology for coronary applications with dedicated delivery systems engineered for tortuous anatomy navigation.
- Transluminal:Specialized delivery for peripheral artery disease where long lesion lengths demand extended scaffold segments and precise positioning control.
- Invasive:Surgical cutdown approaches reserved for failed percutaneous access or complex aortic interventions with limited absorbable scaffold applicability.
Minimally invasive delivery holds the largest share; transluminal techniques show steepest expansion trajectory as peripheral applications diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Absorbable heart stent trade flows reveal a pronounced import dependency in high-reimbursement markets offset by concentrated manufacturing in polymer science and precision metalworking clusters. Export volumes from German and Austrian production facilities supply tertiary hospitals across Western Europe and selected Asian markets.
United States
Medicare bundled payment models at academic medical centers in Boston and Cleveland drive specification-tier procurement for coronary scaffolds. FDA breakthrough device designations for next-generation polymer platforms compress regulatory timelines by 12-18 months. The Minneapolis-St. Paul corridor anchors domestic manufacturing for drug-eluting specification tiers serving integrated delivery networks.
Germany
EMA post-market surveillance registries under MDR requirements track long-term biocompatibility outcomes from absorbable scaffold deployments. Health technology assessment bodies recalibrate reimbursement thresholds, forcing manufacturers to demonstrate cost-effectiveness against metallic alternatives. The Rhine-Main region around Frankfurt concentrates catheterization laboratory procurement committees piloting bioabsorbable platforms for diabetic patient cohorts.
Japan
PMDA maintains distinct biocompatibility testing standards for inflammatory response assessment that influence regional registration strategies. Tokyo and Osaka catheterization laboratories anchor hospital adoption curves for next-generation drug-eluting coatings. The Kansai industrial corridor supplies magnesium alloy scaffolds with superior radial strength for calcified lesion applications.
China
NMPA regulatory pathways for innovative medical devices accelerate clinical validation timelines for domestic polymer platform developers. Provincial procurement consortiums in Jiangsu and Zhejiang provinces negotiate volume-based pricing for bioresorbable scaffolds. The Yangtze River Delta manufacturing cluster scales controlled crystallization processes for polylactic acid matrices.
Switzerland
Swissmedic maintains streamlined approval pathways for absorbable cardiovascular devices that attract EU-parallel registration strategies. Precision polymer engineering capabilities in the Lake Geneva region supply scaffold components to German and French hospital networks. Basel-area research institutes anchor clinical trial recruitment for pediatric vascular applications.
Absorbable Heart Stent Market Vendor Landscape
Concentration sits with diversified cardiovascular device conglomerates that leverage interventional cardiology heritage across multiple absorbable material platforms. The competitive structure fragments between polymer specialists, metal alloy innovators, and hybrid system developers. Three archetypes dominate: integrated device manufacturers with catheterization laboratory relationships, bioabsorbable metal specialists with magnesium expertise, and emerging polymer platform developers with controlled degradation profiles. M&A activity targets niche coating technologies while strategic partnerships with tertiary hospital networks secure proctoring program commitments.
Among diversified cardiovascular device manufacturers, Abbott Laboratories and Boston Scientific Corporation exemplify scale-driven archetypes with extensive interventional cardiology portfolios, while Biotronik SE & Co. KG occupies a specialized position in bioabsorbable magnesium systems. These three entities anchor competitive positioning through distinct material science approaches rather than overlapping platform strategies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Biotronik SE & Co. KG |
| Terumo Corporation |
| MicroPort Scientific Corporation |
| Elixir Medical Corporation |
| REVA Medical, LLC |
| Arterius Ltd. |
| Lepu Medical |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough device designation gates both supply qualification and price differentiation simultaneously, compressing regulatory timelines for manufacturers while segmenting reimbursement tiers between polymer-based and magnesium alloy platforms across tertiary hospital networks.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers based on drug-eluting coating sophistication and degradation profile precision. Price differentiation rests on FDA breakthrough status and EMA MDR registry participation as certification tiers. Pricing pressure stems from Medicare bundled payment models forcing cost-effectiveness demonstrations against metallic stents. Academic medical centers show lowest price sensitivity; ambulatory surgical centers exhibit highest.
Supply Chain Analysis
Germany and Austria anchor polymer scaffold manufacturing with precision crystallization capabilities, while Japan feeds magnesium alloy production for calcified lesion applications. Raw material dependencies center on pharmaceutical-grade polylactic acid, sirolimus analog APIs, and high-purity magnesium feedstock. Single-source vulnerability concentrates in controlled polymer crystallization equipment. Distribution runs through integrated delivery networks and GPO contracts at tertiary hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where FDA and EMA pathway expertise creates switching costs that lock in hospital procurement relationships and proctoring program commitments.
For Market Incumbents: Consolidate manufacturing scale in the Minneapolis-St. Paul corridor and Rhine-Main region to defend against emerging polymer platform developers. Deepen backward integration into pharmaceutical-grade polylactic acid feedstock to offset API cost volatility. Lock in tertiary hospital proctoring exclusivity before next-generation coating technologies mature.
For New Entrants and Emerging Players: Pediatric vascular applications represent underserved white space where permanent implant complications drive clinical demand for absorbable alternatives. Target congenital heart defect repair segments in Basel-area research networks where Swissmedic pathways accelerate registration. Lead with specialized magnesium alloy formulations for calcified lesions where polymer flexibility fails.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across drug-eluting specification tiers as degradation-byproduct characterization demands expand. Five-to-ten year viability favors scaled players with existing EMA MDR quality infrastructure. Watch for PMDA breakthrough designations in Tokyo and Osaka as early-mover inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures proctoring program commitments at Cleveland Clinic and Heidelberg University Hospital networks. |
| FDA Breakthrough Pathway | Compresses clinical validation timelines by 12-18 months for qualifying coronary scaffold platforms. |
| CE Marking Pathway | Opens EU MDR post-market surveillance registries tracking long-term biocompatibility outcomes. |
| Reimbursement Strategy | Aligns health technology assessment submissions with German and Japanese value metrics recalibration. |
| Backward Integration | Captures pharmaceutical-grade polymer feedstock supply through Minneapolis-St. Paul manufacturing expansion. |
Methodological Framework
Cross-validation between primary interviews with interventional cardiologists, hospital procurement managers, and regulatory affairs directors and secondary sources including FDA 510(k) filings, EMA MDR submissions, and CMS Medicare reimbursement databases anchors the qualitative findings. Bottom-up demand modeling from catheterization laboratory deployment rates triangulates against top-down market sizing from device manufacturer revenue disclosures.
Sensitivity analysis across the projection horizon tests forecast robustness against regulatory pathway delays and reimbursement compression scenarios. Segmentation dimensions span product type, application, end user, and delivery mode with regional regulatory cluster overlays. CAGRs derive from fitted growth curves calibrated to historical adoption rates at tertiary hospitals and projected expansion into peripheral intervention segments.
Underlying assumptions cover sustained FDA breakthrough designation velocity and stable Medicare bundled payment frameworks, with deviation risk concentrated in EMA MDR documentation burden expansion and PMDA biocompatibility standard evolution. Recalibration cycles align with material shifts in reimbursement threshold determinations and next-generation polymer platform clinical readouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Lung Stent Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Canada Cardiovascular Devices Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market