
 South America Fruit and Vegetable Ingredients Market | 2026-2036
South America Fruit and Vegetable Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fruit and Vegetable Ingredients Market Analytics
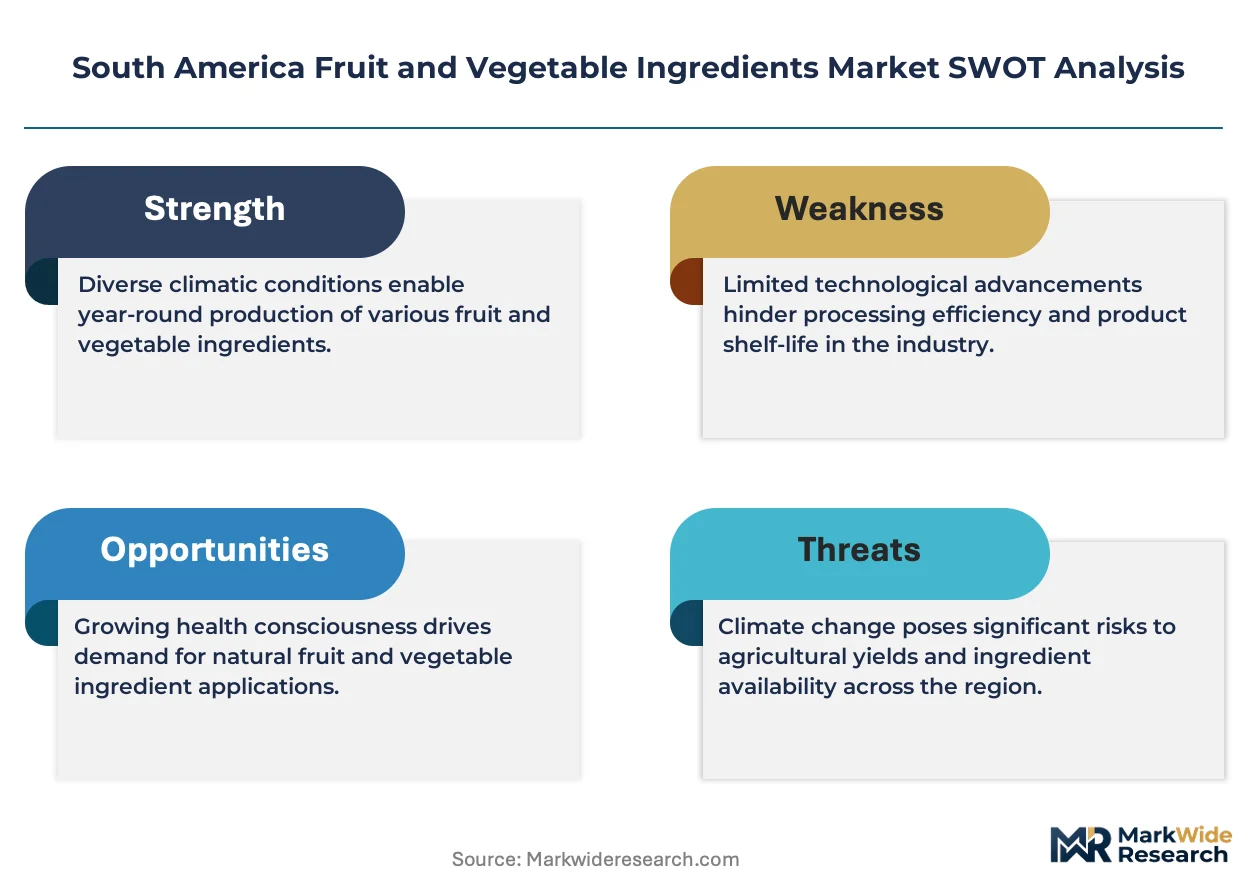
Direct procurement between ingredient processors and beverage manufacturers is reconfiguring traditional wholesale intermediation in South America. Cargill Incorporated leverages its Brazilian citrus processing footprint to secure long-term supply contracts with multinational bottlers. Kerry Group plc anchors its regional position through specialized fruit extract applications targeting clean-label formulations. Citrosuco S.A. dominates orange-derived ingredient supply from its São Paulo processing complex, extending vertical control from grove to concentrate.
Fruit and vegetable ingredients comprise processed or minimally processed plant-derived materials including pulps, purees, concentrates, powders, and dried forms, standardized for brix, acidity, and microbiological parameters to ensure batch consistency in industrial formulations. These inputs serve primarily as flavor carriers, colorants, nutritional fortificants, and texturizing agents across food and beverage manufacturing. Concentrates and purees within the Form dimension command the deepest margin pools due to capital-intensive extraction infrastructure and technical barriers to achieving stable shelf-life without preservative systems. The Nutraceuticals end-use segment exhibits the most rapid expansion trajectory, driven by formulation demand for polyphenol-rich extracts and fiber-enriched vegetable powders in functional food applications across Brazil and Argentina.
ANVISA governs microbiological safety and additive thresholds for processed fruit ingredients entering Brazilian food channels, while Argentina's national food code enforces parallel compositional standards that shape cross-border formulation strategies. The Mercosur technical regulation harmonization process is reducing redundant certification burdens for suppliers operating across member states. Stakeholders must monitor evolving maximum residue limits for agricultural inputs, as tightening phytosanitary protocols in key export destinations will increasingly determine which South American processing facilities retain market access eligibility.
Market Dynamics
Direct procurement between São Paulo citrus processors and multinational beverage formulators is collapsing traditional wholesale intermediation across the Southern Cone. ANVISA's tightened microbiological standards for minimally processed ingredients are forcing capital upgrades that favor integrated processors over fragmented suppliers.
Growth Catalysts
- ANVISA HACCP Mandates:Certification requirements for aseptic purees are consolidating supplier bases toward integrated processors capable of end-to-end cold-chain documentation. Brazilian beverage manufacturers now specify HACCP-certified sources in procurement contracts.
- Nutraceutical Formulation Demand:Polyphenol-rich extracts and fiber-enriched vegetable powders are commanding premium positioning in functional food applications across Brazil and Argentina.
- Mercosur Harmonization:Technical regulation alignment is reducing redundant certification burdens for suppliers operating across member states, accelerating cross-border ingredient flows.
Market Restraints
- Orange Concentrate Supply Concentration:São Paulo state dominates global orange-derived ingredient output, creating geographic vulnerability to climate disruption and phytosanitary events.
- Cold-Pressed Infrastructure Costs:Aseptic extraction equipment and stabilized shelf-life systems require capital intensity that excludes smaller processors from premium concentrate segments.
- Maximum Residue Limit Tightening:Export destination phytosanitary protocols are disqualifying processing facilities with legacy agricultural input practices from market access eligibility.
Strategic Opportunities
- Argentine Vegetable Powder Expansion:Underpenetrated processing capacity for fiber-enriched vegetable ingredients presents white space for regional suppliers targeting domestic nutraceutical formulators.
- Clean-Label Extract Applications:Kerry Group's specialized fruit extract positioning demonstrates viable pathway for regional players to capture margin in preservative-free formulation segments.
- Colombian Andean Fruit Diversification:Tropical fruit varieties outside citrus offer differentiation potential for processors establishing non-commodity ingredient portfolios.
Industry Challenges
- Microbiological Compliance Timeline:ANVISA certification processes for minimally processed ingredients extend facility validation periods, compressing working capital cycles for upgrading processors.
- Aseptic Technician Scarcity:Specialized operators for cold-pressed concentrate systems command premium wages in São Paulo processing clusters, constraining expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fruit and Vegetable Ingredients Market |
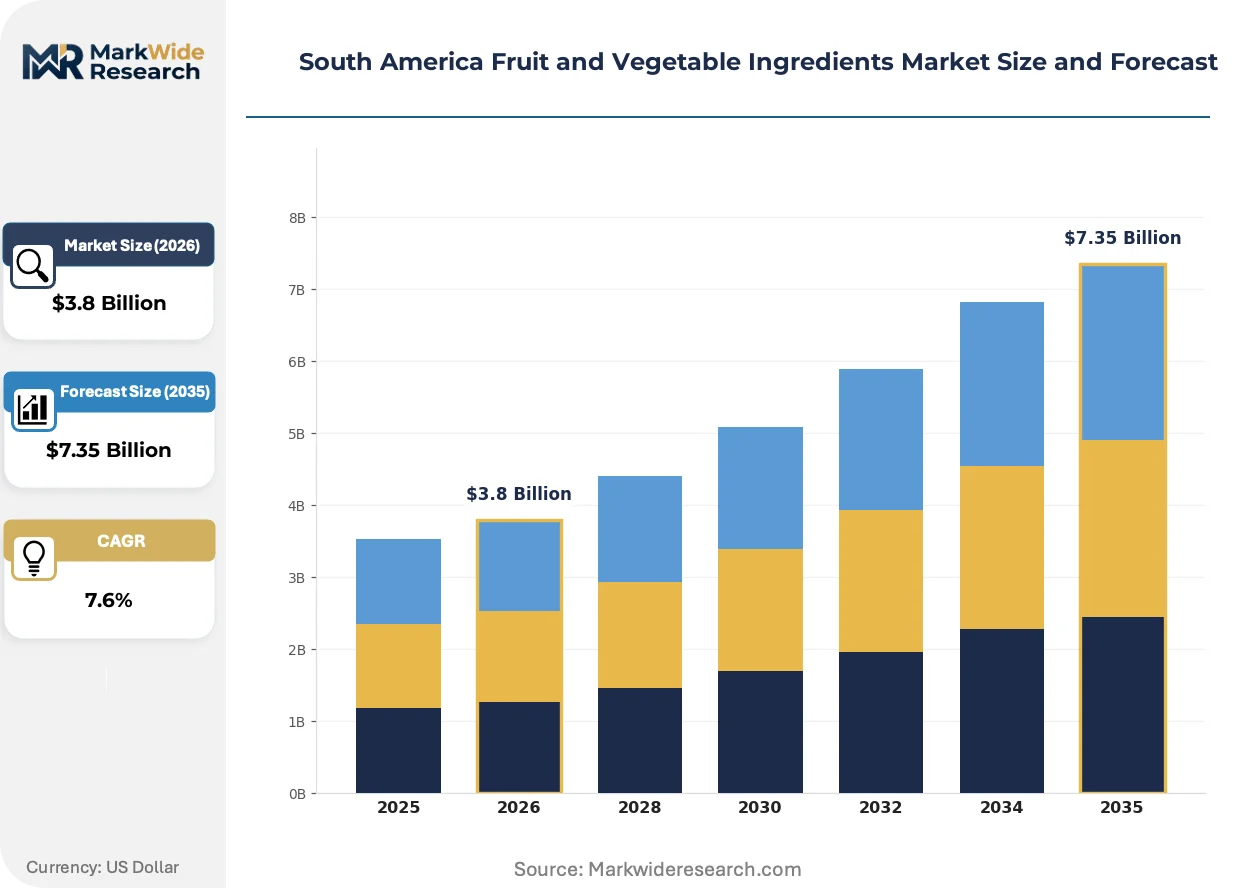
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Dried, Juiced End Use: Food Processing, Beverage Manufacturing, Nutraceuticals, Culinary Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce Form: Pulps, Purees, Concentrates, Powders |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Kerry Group plc, Döhler Group, Sensient Technologies, SVZ International B.V., Citrosuco S.A., Cutrale Group, Frutarom (IFF), Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fruit and Vegetable Ingredients Market Evolving Landscape
Processing technology convergence and procurement model restructuring are redrawing competitive boundaries across South American ingredient supply. Formulator demands for batch consistency and clean-label positioning are accelerating equipment upgrade cycles.
High-pressure processing technology for aseptic puree stabilization is hybridizing traditional thermal pasteurization methods in São Paulo citrus facilities. Brazilian beverage manufacturers are specifying HPP-treated concentrates in premium product lines. This hybridization is compressing margins for processors unable to finance dual-capability infrastructure.
ANVISA's phased implementation of tightened microbiological standards for minimally processed ingredients is forcing facility recertification across Brazilian processing complexes. Compliance timelines are favoring integrated operators with captive laboratory validation capabilities. Cold-pressed concentrate segments face the steepest compliance cost gradients.
Direct contracting between ingredient processors and end-use formulators is displacing traditional wholesale distribution in Brazil's beverage sector. São Paulo-based citrus processors now maintain dedicated account teams for multinational bottlers. Argentina's nutraceutical manufacturers are replicating this procurement structure for polyphenol extract sourcing.
South America Fruit and Vegetable Ingredients Market Segmentation
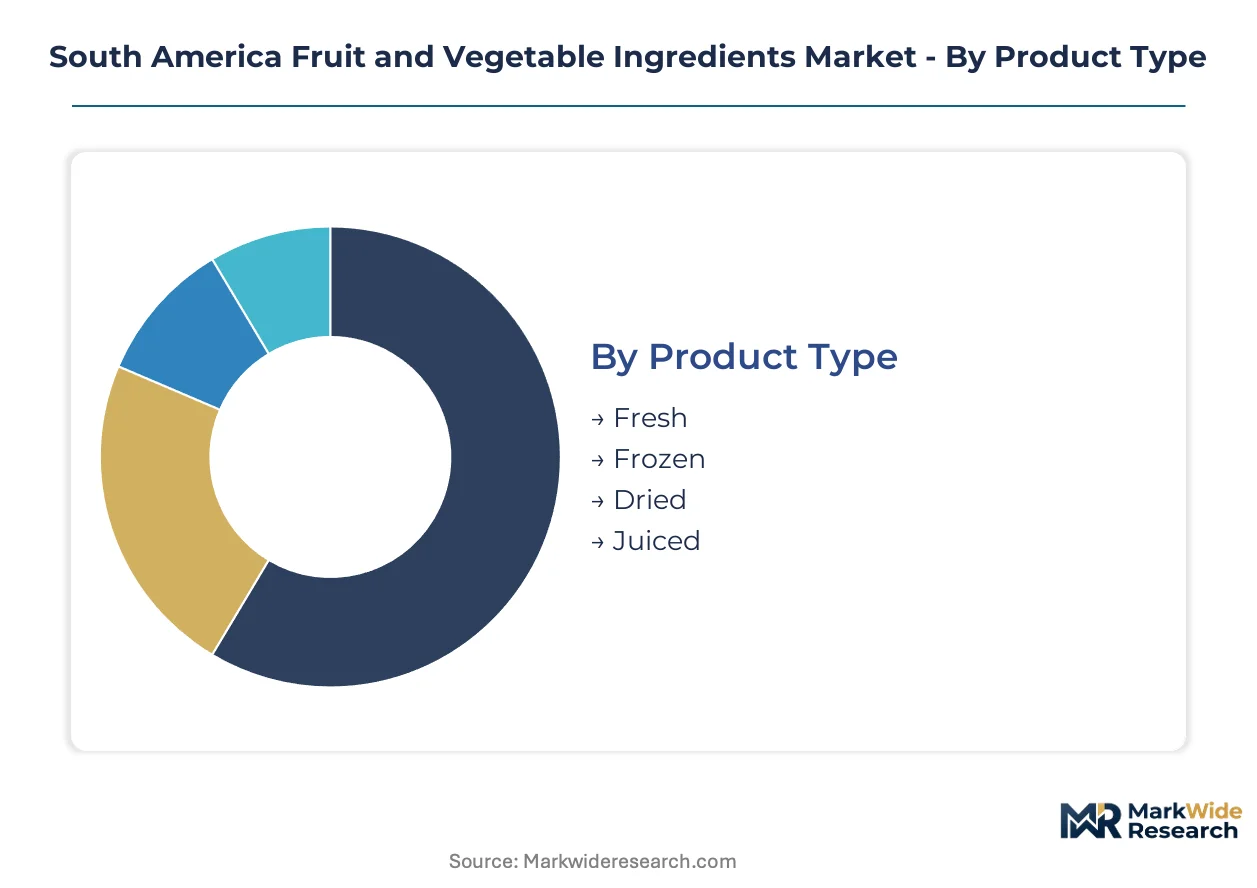
Segmentation reveals how procurement priorities diverge across South American ingredient buyers. Citrus processors in São Paulo state, nutraceutical formulators in Buenos Aires, and Andean fruit exporters each demand distinct specification profiles, shelf-life parameters, and documentation standards.
Product Type:
Inventory velocity varies dramatically across preservation states, with fresh formats turning weekly and dried products sitting for months.
- Fresh:Minimally processed whole fruits and vegetables with 7-14 day shelf-life windows. São Paulo beverage manufacturers contract directly with citrus processors for same-day delivery of Valencia oranges to cold-press facilities.
- Frozen:IQF (individually quick frozen) segments and blast-frozen vegetable cuts. Argentine frozen pea and corn processors supply Buenos Aires ready-meal manufacturers under annual volume contracts with price-adjustment clauses.
- Dried:Dehydrated fruit slices and vegetable flakes with extended ambient stability. Andean blueberry and mango processors in Peru target export nutraceutical buyers seeking polyphenol retention in shelf-stable formats.
- Juiced:Single-strength and concentrated liquid extracts. Brazilian orange juice concentrate exports from São Paulo state remain the dominant revenue pool despite climate vulnerability.
Juiced formats anchor the volume base while dried products gain share at the steepest rate.
End Use:
Margin structure inverts across customer types, with commodity food processors squeezing suppliers and nutraceutical buyers paying premiums for certified extracts.
- Food Processing:Industrial bakeries, confectionery manufacturers, and prepared meal producers requiring standardized brix and acidity specifications. São Paulo-based pasta sauce manufacturers source tomato paste under long-term contracts with Argentine processors.
- Beverage Manufacturing:Soft drink bottlers, juice blenders, and functional drink formulators. Brazilian multinational bottlers specify HACCP-certified aseptic purees from Citrosuco's São Paulo complex.
- Nutraceuticals:Functional food and dietary supplement formulators seeking polyphenol-rich extracts and fiber-enriched powders. Buenos Aires supplement manufacturers drive demand for Argentine pumpkin seed protein isolates.
- Culinary:Restaurant chains, institutional caterers, and foodservice distributors. Colombian foodservice operators source Andean blackberry purees for dessert applications in Bogotá and Medellín.
Beverage manufacturing commands the largest revenue pool while nutraceuticals climb fastest on per-kilogram value metrics.
Distribution Channel:
Channel selection determines working capital intensity and documentation burden, with direct sales requiring captive logistics and e-commerce demanding consumer-packaging compliance.
- Retail:Supermarket chains and specialty food stores carrying consumer-packaged ingredients. Brazilian retail channels favor 200-500 gram pouch formats of açaí pulp in São Paulo's upscale neighborhoods.
- Wholesale:Traditional intermediaries consolidating fragmented supplier output for regional redistribution. Wholesale dominance persists in Argentina's interior provinces where direct processor access remains limited.
- Direct Sales:Processor-to-manufacturer contracting bypassing distribution layers. São Paulo citrus processors now maintain dedicated account teams for multinational bottlers.
- E-commerce:Digital platforms serving small-batch formulators and direct-to-consumer ingredient buyers. Brazilian B2B platforms connect Minas Gerais fruit processors with artisanal jam producers nationwide.
Direct sales are displacing wholesale intermediation fastest while retail maintains the broadest geographic coverage.
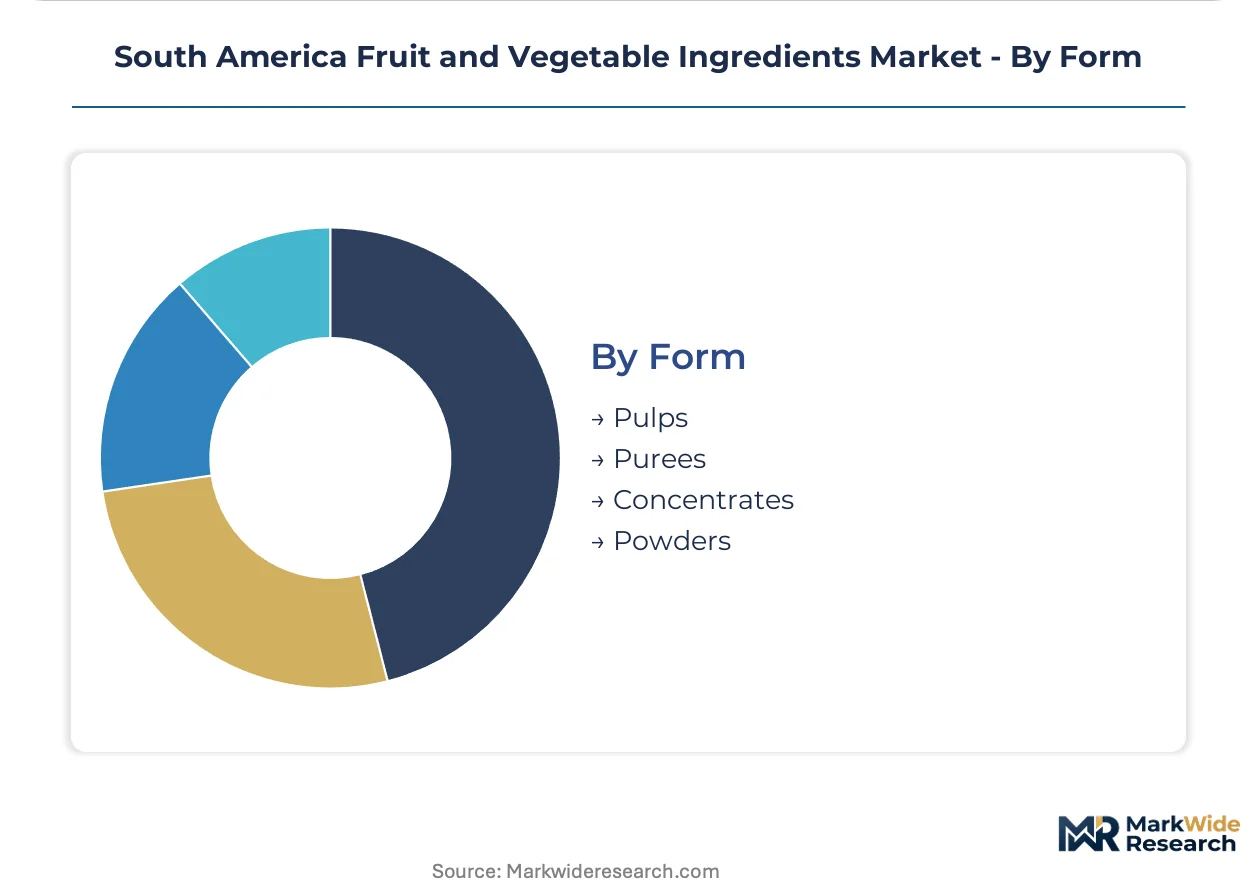
Form:
Capital requirements stratify sharply, with concentrate production demanding aseptic infrastructure and powders requiring spray-drying or freeze-drying investment.
- Pulps:Coarsely processed fruit or vegetable matter retaining fiber and cellular structure. Brazilian açaí pulp production concentrates in Pará state for domestic smoothie bar supply and export.
- Purees:Finely milled, homogenized preparations with standardized particle size. São Paulo processors supply aseptic mango puree to Argentine yogurt manufacturers under ANVISA-certified specifications.
- Concentrates:Solids-reduced extracts with elevated brix for efficient transport and reconstitution. Orange concentrate from São Paulo state remains the reference price setter for global citrus ingredient trade.
- Powders:Dehydrated fine particles including spray-dried fruit juices and freeze-dried vegetable extracts. Argentine pumpkin and sweet potato powder processors target domestic nutraceutical capsule manufacturers.
Concentrates dominate export revenue while powders expand most quickly in functional food applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminal underwrites São Paulo state's dominance in South American fruit ingredient exports, handling concentrated citrus shipments bound for European and Asian beverage manufacturers.
Brazil
Beverage manufacturers in São Paulo state accelerate procurement of aseptic purees and cold-pressed concentrates from local citrus processors. ANVISA's tightened microbiological standards for minimally processed ingredients push suppliers toward HACCP-certified operations with end-to-end cold-chain documentation. São Paulo's processing clusters supply both domestic formulators and export-oriented nutraceutical buyers.
Argentina
Nutraceutical manufacturers in Buenos Aires drive demand for polyphenol-rich extracts and fiber-enriched vegetable powders in functional food applications. Argentina's national food code enforces compositional standards that shape cross-border formulation strategies with Brazilian suppliers. Buenos Aires supplement manufacturers replicate direct procurement structures for pumpkin seed protein isolates and specialty extracts.
Colombia
Foodservice operators in Bogotá and Medellín source Andean blackberry purees for dessert applications and tropical fruit ingredients for beverage innovation. The country's phytosanitary protocols align with Mercosur technical regulation harmonization, reducing redundant certification burdens for cross-border trade. Colombian Andean fruit processors establish non-commodity ingredient portfolios targeting premium export segments.
Chile
Export-oriented processors concentrate in central valley regions, supplying polyphenol-retaining dried blueberry and mango formats to international nutraceutical buyers. Chile's sanitary regulations for processed agricultural exports enforce strict maximum residue limits that determine market access eligibility. Santiago-based ingredient traders coordinate shipments through Valparaíso port to Pacific Rim destinations.
Peru
Andean blueberry processors target export nutraceutical buyers seeking shelf-stable formats with verified polyphenol content. The country's phytosanitary authority enforces tightening agricultural input standards that disqualify facilities with legacy practices from key destination markets. Lima coastal processing zones concentrate spray-drying capacity for fruit powder exports.
South America Fruit and Vegetable Ingredients Market Competitive Landscape
On the supply side, the industry is consolidating toward integrated processors capable of end-to-end cold-chain documentation and captive laboratory validation. Citrus-derived ingredient production concentrates in São Paulo state facilities with aseptic extraction infrastructure. Two strategic archetypes dominate: vertically integrated grove-to-concentrate operators and specialized extract formulators targeting clean-label applications. Competitive dynamics center on HACCP certification acquisition and direct contracting relationships with multinational bottlers.
Within the integrated processor tier, Citrosuco S.A. and Cutrale Group exemplify São Paulo-based operators with grove-to-concentrate control. Kerry Group plc occupies a position among specialized extract formulators targeting preservative-free beverage applications. Cargill Incorporated anchors the multinational ingredient supplier archetype through Brazilian citrus processing assets and long-term supply contracting capabilities.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Döhler Group |
| Sensient Technologies |
| SVZ International B.V. |
| Citrosuco S.A. |
| Cutrale Group |
| Frutarom (IFF) |
| Others |
Value Network & Pricing Analysis
Single-source dependency on São Paulo citrus processors determines both pricing tier spreads and supply chain shape across South American fruit ingredient markets. ANVISA's HACCP certification chokepoint compresses margins for uncertified operators while concentrating pricing power among integrated processors with captive laboratory validation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates HACCP-certified aseptic concentrates from conventional purees and commodity-grade frozen pulps. Price differentiation hinges on certification grade and volume scale, with multinational bottlers locking in annual offtake contracts at 15-20% discounts to spot procurement. Pricing pressure stems from Argentine nutraceutical formulators demanding polyphenol certificates without volume commitments. Commodity food processors exhibit highest price sensitivity; clean-label beverage manufacturers show lowest.
Supply Chain Analysis
Tariff exposure between Brazil and Argentina dominates supply chain risk calculations for cross-border ingredient flows. Geographic supply concentration centers on Brazil, Argentina, and Peru, with São Paulo state anchoring citrus concentrate output and Argentine central provinces supplying vegetable powders. Raw material dependencies include Valencia orange groves, Andean pumpkin seed stocks, and Peruvian blueberry harvests. Distribution runs through direct processor-to-manufacturer contracting that displaces traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ANVISA's certification requirements create switching costs that protect incumbent positions while excluding undercapitalized challengers.
For Market Incumbents: Build regulatory moats through captive ANVISA laboratory accreditation and backward integration into controlled-atmosphere cold storage. Threats from Colombian Andean fruit processors with lower cost structures necessitate capacity addition in Argentine vegetable powder segments. Certification investment represents the critical lever for margin defense. For New Entrants and Emerging Players: Build out Argentine fiber-enriched vegetable powder capacity targeting Buenos Aires nutraceutical formulators. The most penetrable segment sits in domestic pumpkin seed and sweet potato protein isolates where incumbent presence remains thin. Go-to-market positioning should emphasize direct contracting with supplement manufacturers replicating São Paulo's procurement model. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated processors with HACCP certification and grove-to-concentrate control. Long-term viability over the next decade hinges on climate-resilient sourcing diversification. Acquisition targets should display captive laboratory capabilities and established direct bottler relationships. The signal to watch is ANVISA enforcement intensity against legacy facilities.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Investment | ANVISA compliance separates premium processors from commodity competitors in São Paulo clusters. |
| Backward Integration into Cold Storage | Controlled-atmosphere infrastructure secures shelf-life extension for aseptic puree exports. |
| Direct-to-Bottler Contracting | São Paulo citrus processors bypass wholesale layers to capture margin from multinational beverage manufacturers. |
| Argentine Vegetable Powder Expansion | Underpenetrated processing capacity addresses Buenos Aires nutraceutical demand for fiber-enriched ingredients. |
| Andean Fruit Diversification | Colombian blackberry and tropical varieties reduce geographic concentration risk in citrus-dependent portfolios. |
Research Methodology
Desk research of trade databases, regulatory filings, and industry association reports preceded structured interviews with citrus processing plant managers, beverage procurement directors, nutraceutical formulators, and ANVISA compliance officers. Secondary validation drew from ANVISA certification registries, Mercosur technical regulation harmonization documents, and São Paulo state agricultural export statistics. Bottom-up volume estimates from individual processing facilities were triangulated against top-down market sizing from trade flow analysis.
Assumptions held ANVISA enforcement timelines and Mercosur harmonization progress within observed patterns while varying climate disruption frequency and export destination phytosanitary tightening. The analytical framework modeled segmentation across preservation state, end-use application, distribution channel, and ingredient form throughout the forecast period. CAGRs were derived from regression analysis of historical volume trajectories and elasticity estimates from procurement contract structures. Industry-specific inputs included citrus grove yield volatility coefficients and aseptic processing capacity utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive certification acceleration by Brazilian mid-tier processors or sudden Argentine export subsidy programs would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Distillers Corn Oil Market
Ingredients
Hydrolyzed Starch Market
Ingredients
India Soy Protein Market
Ingredients
Meat Extract Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Peanut Flour Market
Ingredients
Non-GMO Oil Market
Ingredients
Soy Hydrolysates Market
Ingredients
Aroma Ingredients Market
Ingredients
Whey Permeate Market
Ingredients
Fresh Yeast Market
Ingredients
Tannin Market
Ingredients
Specialty Yeast Market
Ingredients
United States Wheat Protein Market
Ingredients
Coconut Cream Powder Market
Ingredients
Wheat Protein Concentrates Market