
 Instant Fat Powder Market | 2026-2036
Instant Fat Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Fat Powder Market Foresight
Sports nutrition brands is unwinding the historical procurement dominance of conventional food and beverage manufacturers in instant fat powder allocation. Fonterra Co-operative Group Limited anchors its position through backward integration into dairy cream sourcing across New Zealand and Australia. Kerry Group plc differentiates via customized lipid encapsulation systems for functional beverage applications. Glanbia PLC competes through specialized whey-lipid hybrid powders targeting endurance nutrition segments.
Instant fat powder consists of spray-dried or agglomerated lipid particles, typically containing 50-80% fat content with protein-carbohydrate carrier matrices that enable cold-water dispersibility and extended shelf stability. The material serves primarily as a convenient fat delivery system in powdered beverages, infant formulas, and meal replacement products where liquid oils would compromise flow properties and oxidative stability. Whole powder and MCT powder command the widest formulation penetration, with MCT powder capturing disproportionate margin pools in ketogenic and cognitive health applications. Coconut oil powder grows fastest among plant-derived alternatives as formulators seek non-dairy emulsification pathways, while palm oil powder faces sustainability scrutiny that constrains new customer onboarding in European markets.
FDA food additive regulations and GRAS self-determination frameworks govern lipid powder introductions in the United States, while EFSA novel food assessments and REACH chemical safety obligations shape European market access protocols. Codex Alimentarius standards on infant formula composition create harmonized baseline specifications that facilitate cross-border trade in dairy-derived fat powders. Stakeholders must monitor evolving front-of-pack labeling requirements in major economies and assess how proposed restrictions on saturated fat content claims will redirect R&D investment toward modified lipid structures with altered fatty acid profiles.
Market Dynamics
Sports nutrition brands now compress procurement cycles to twelve-week intervals, forcing suppliers to abandon the eighteen-month qualification timelines that traditional food processors historically tolerated.
Growth Catalysts
- Clean-label emulsification mandates:EFSA novel food assessments in Europe and GRAS self-determination frameworks in the United States accelerate reformulation toward protein-carbohydrate carrier matrices that eliminate synthetic additives.
- Ketogenic dietary protocols:MCT powder captures disproportionate margin pools as cognitive health and endurance nutrition applications expand formulation penetration beyond sports drinks into clinical meal replacements.
- Domestic dairy self-sufficiency programs:China's accelerated local production capacity builds captive spray-drying infrastructure that reduces import dependency for infant formula manufacturers.
Market Restraints
- Palm oil sustainability scrutiny:REACH chemical safety obligations and EU Green Deal deforestation due diligence rules constrain new customer onboarding for palm-derived powders across European markets.
- Coconut oil feedstock volatility:Weather-induced harvest fluctuations in Southeast Asian producing regions create input cost instability that compresses margin predictability for plant-derived alternatives.
- Cold-water dispersibility thresholds:Technical limitations in agglomeration physics prevent fat content exceeding eighty percent from achieving instant solubility without compromising oxidative shelf stability.
Strategic Opportunities
- Modified lipid structure R&D:Proposed FDA restrictions on saturated fat content claims redirect investment toward altered fatty acid profiles that maintain functional performance while meeting front-of-pack labeling requirements.
- Specialized whey-lipid hybrid powders:Technology convergence between dairy protein encapsulation and lipid microencapsulation creates white space in endurance nutrition segments seeking dual macronutrient delivery.
- E-commerce direct procurement:Sports nutrition brands bypass traditional ingredient distributors through platform-based purchasing, enabling smaller batch sizes and faster formulation iteration.
Industry Challenges
- Spray-drying engineering talent scarcity:Specialized expertise in atomization physics and thermal degradation control concentrates among aging cohorts in New Zealand and European dairy processing clusters.
- Dual certification timelines:Simultaneous Codex Alimentarius infant formula compliance and EFSA novel food assessments extend market entry durations by fourteen to eighteen months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Fat Powder Market |
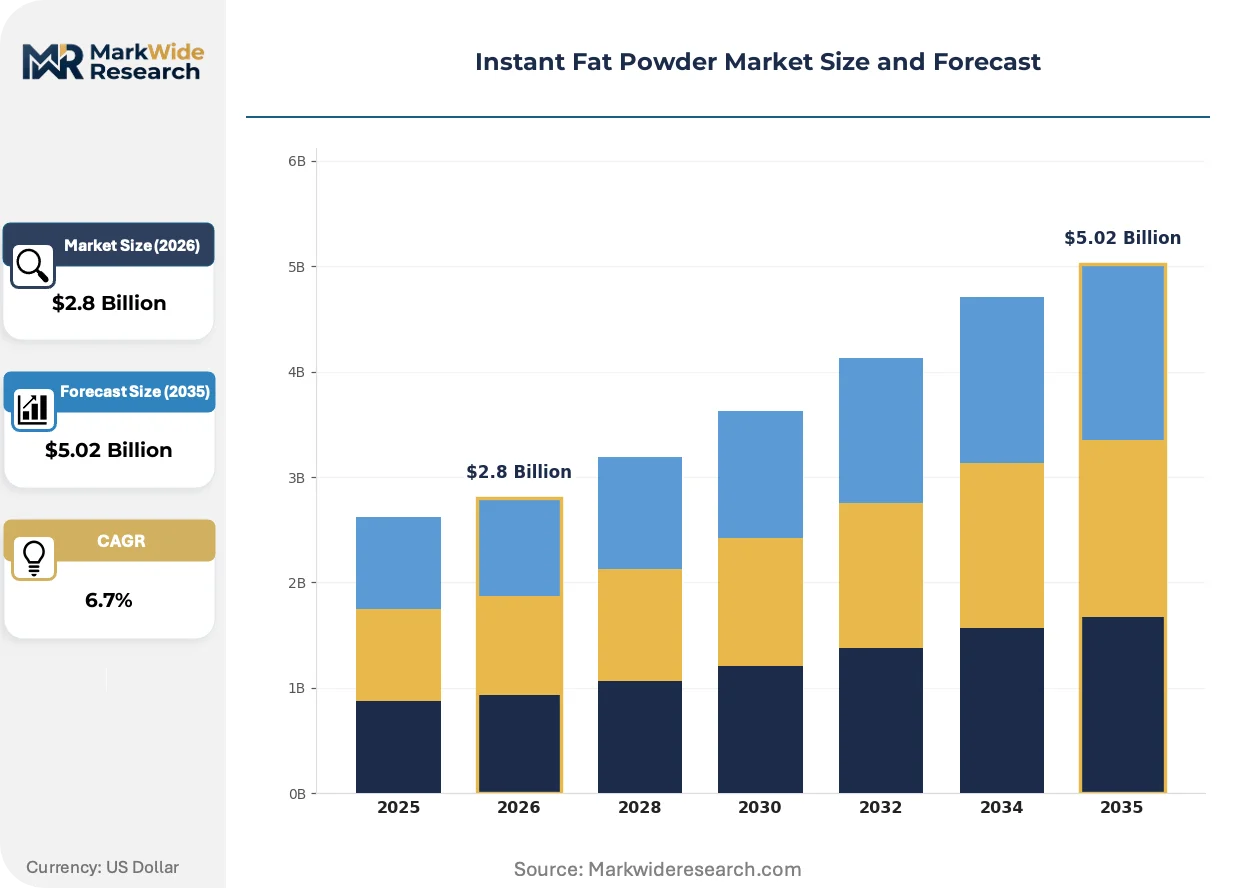
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Powder, Coconut Oil Powder, MCT Powder, Palm Oil Powder End User: Nutritional Supplement Manufacturers, Food & Beverage Industry, Sports Nutrition Brands, Pharmaceutical Companies Form: Powder, Granules, Capsules, Tablets Packaging Type: Bags, Containers, Sachets, Jars |
| Companies Covered | Nestlé S.A., Fonterra Co-operative Group Limited, Arla Foods amba, FrieslandCampina, Vreugdenhil Dairy Foods, Kerry Group plc, Glanbia PLC, Lactalis Ingredients, Alpen Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Fat Powder Market Shifts & Advancements
Reformulation toward non-dairy emulsification pathways and compressed buyer qualification cycles are actively redistributing competitive advantage away from legacy dairy cooperatives toward specialized lipid encapsulation technology providers.
Microencapsulation via complex coacervation is fragmenting the supplier landscape by enabling fat contents above seventy percent with enhanced oxidative protection. Sports nutrition formulators adopt these systems at accelerated pace to differentiate ketogenic and cognitive health products. The technology is fragmenting historical procurement relationships as brands bypass traditional dairy ingredient suppliers for biotechnology-enabled specialists.
EFSA novel food assessments now require comprehensive toxicological dossiers for lipid powders derived from emerging plant sources, extending approval timelines and elevating compliance costs. This regulatory friction disproportionately affects coconut oil powder innovators seeking European market access. Manufacturers respond by front-loading safety studies and engaging early with EFSA pre-submission protocols.
Direct-to-manufacturer platform procurement compresses traditional distributor margins and accelerates formulation feedback loops. Sports nutrition brands in the United States and Germany increasingly source through digital marketplaces that aggregate qualified suppliers and standardize quality documentation. This channel shift concentrates purchasing power among buyers with technical sophistication to evaluate encapsulation performance specifications independently.
Instant Fat Powder Market Segmentation
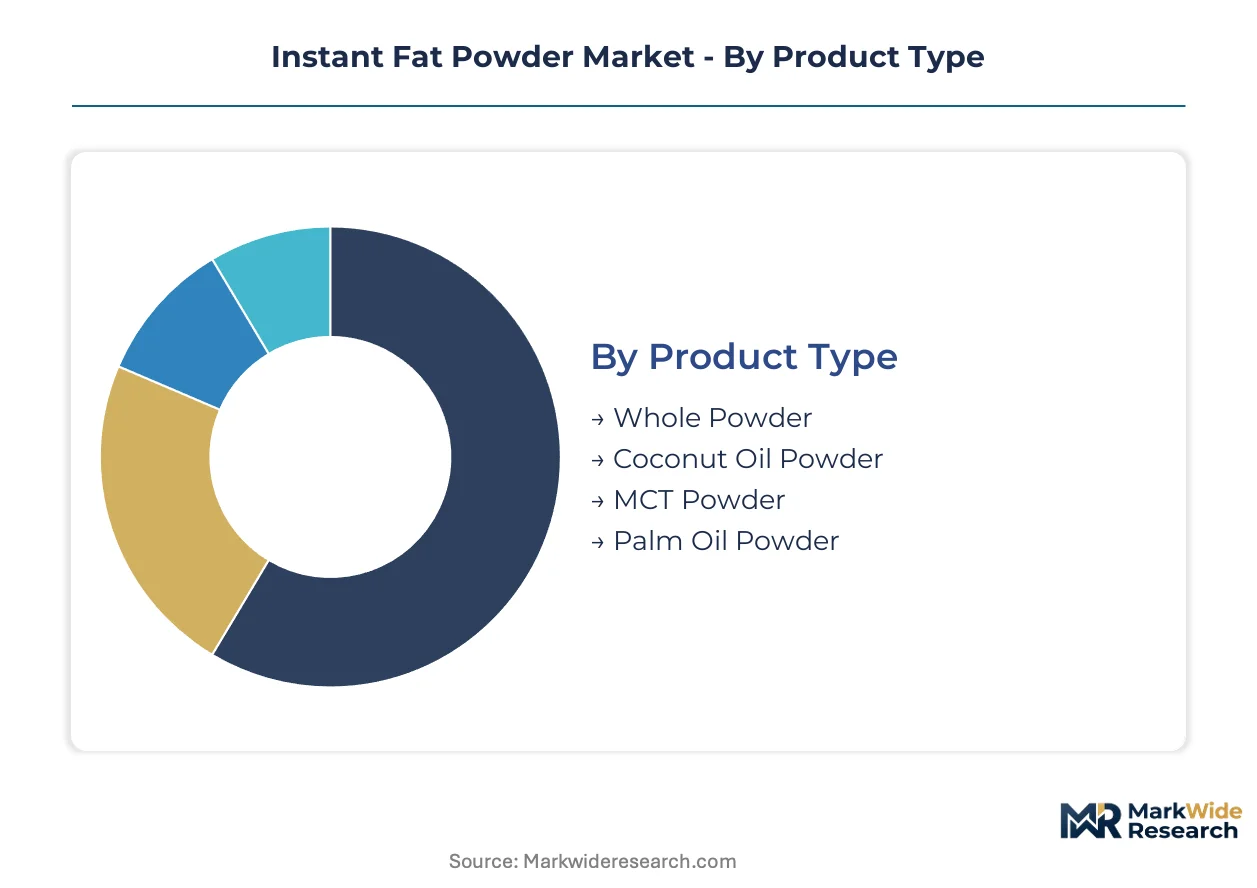
Instant fat powder segmentation reveals divergent supply chain architectures across product categories. Whole powder and MCT powder anchor export-oriented production networks, while coconut oil powder increasingly serves domestic reformulation programs in China and Southeast Asia.
Product Type:
Whole powder and MCT powder concentrate in New Zealand and Australian dairy processing clusters serving export markets. Coconut oil powder production gravitates toward Southeast Asian domestic supply chains responding to regional clean-label mandates.
- Whole Powder:Spray-dried dairy fat particles containing 50-80% milkfat with protein-carbohydrate matrices enable cold-water dispersibility in infant formula applications. Demand concentrates in China where domestic dairy self-sufficiency programs accelerate captive spray-drying infrastructure buildout.
- MCT Powder:Medium-chain triglyceride microencapsulation achieves 70-80% fat content through complex coacervation, delivering rapid ketone metabolism for cognitive health formulations. Sports nutrition brands in the United States and Germany compress procurement cycles to twelve-week intervals for this premium segment.
- Coconut Oil Powder:Plant-derived emulsification pathway bypasses dairy allergen labeling requirements.
- Palm Oil Powder:REACH chemical safety obligations and EU Green Deal deforestation due diligence rules constrain European market access.
Whole powder holds the largest share; momentum sits with MCT powder.
End User:
Cost tier stratification separates premium encapsulation technology buyers from commodity procurement patterns. Sports nutrition brands pay formulation premiums for rapid dispersibility specifications that traditional food processors rarely demand.
- Nutritional Supplement Manufacturers:Ketogenic and clinical meal replacement formulations drive specialized whey-lipid hybrid powder procurement with dual macronutrient delivery requirements.
- Food & Beverage Industry:Powdered beverage applications prioritize oxidative shelf stability over cold-water dispersibility thresholds.
- Sports Nutrition Brands:Platform-based direct procurement bypasses traditional ingredient distributors, enabling smaller batch sizes and faster formulation iteration cycles in the United States and German markets.
- Pharmaceutical Companies:Codex Alimentarius infant formula compliance and EFSA novel food assessments extend qualification timelines to fourteen-eighteen months.
Sports nutrition brands command premium pricing tiers; pharmaceutical compliance costs favor established dairy cooperatives.
Form:
Volume concentration in powder format reflects spray-drying infrastructure scale economies. Granule and tablet formats serve niche clinical applications with specialized stability requirements.
- Powder:Atomized lipid particles with 50-80% fat content dominate production throughput across New Zealand and European dairy processing clusters.
- Granules:Agglomerated structures improve flow properties for high-speed packaging lines in nutritional supplement manufacturing.
- Capsules:Pre-measured unit dosing serves clinical trial protocols and precision ketogenic dietary interventions.
- Tablets:Compression-formed lipid delivery encounters technical limitations above twenty percent fat content without compromising structural integrity.
Powder captures production volume leadership; capsules gain share fastest in clinical nutrition segments.
Packaging Type:
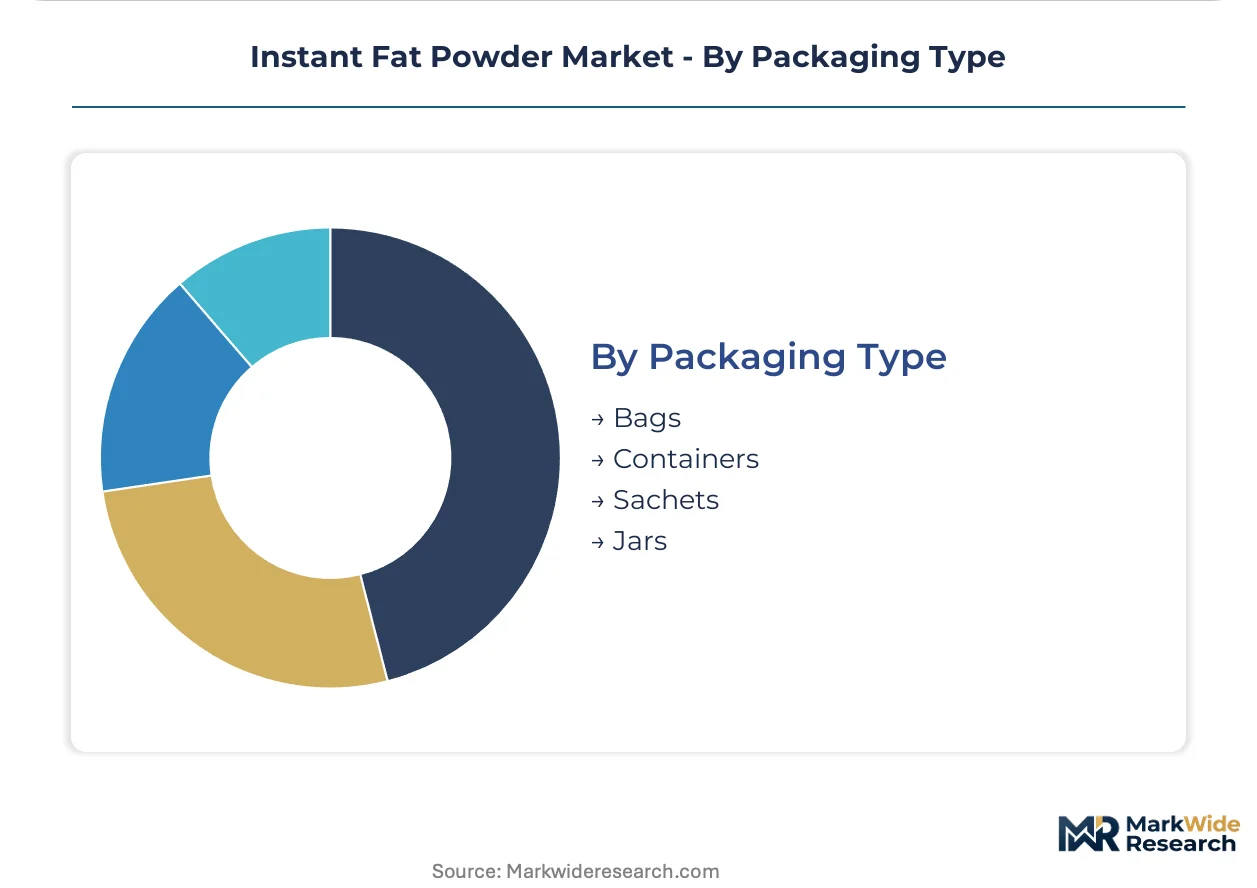
Customer type segmentation separates bulk industrial procurement from branded consumer channels. Institutional buyers favor bag and container formats; direct-to-consumer sports nutrition brands drive sachet innovation.
- Bags:Multi-wall industrial packaging serves twenty-five kilogram bulk shipments to food and beverage manufacturers.
- Containers:Rigid packaging preserves oxidative stability during extended storage in humid climates.
- Sachets:Single-serve units enable trial-sized distribution through e-commerce direct procurement platforms.
- Jars:Premium positioning supports front-of-pack labeling claims in retail ketogenic supplement channels.
Bags dominate procurement tonnage; sachets expand most quickly through digital marketplace channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand dairy processors supply spray-dried fat powders to Chinese infant formula manufacturers through long-term offtake agreements. Australian exporters capture sports nutrition demand in Germany and the United States via specialized MCT powder shipments.
China
Domestic dairy self-sufficiency programs accelerate captive spray-drying infrastructure buildout in Heilongjiang and Inner Mongolia. SAMR infant formula registration requirements tighten import specifications for foreign fat powder suppliers. Yangtze River Delta processing clusters absorb technology transfer from New Zealand dairy cooperatives to localize emulsification expertise.
United States
Sports nutrition brands in California and Texas compress procurement cycles to twelve-week intervals for ketogenic formulation inputs. FDA GRAS self-determination frameworks govern lipid powder introductions while front-of-pack labeling proposals redirect R&D investment toward modified fatty acid profiles. Midwest dairy processing hubs in Wisconsin and Minnesota retain whole powder production for infant nutrition applications.
Germany
EFSA novel food assessments extend approval timelines for coconut oil powder innovators seeking European market access. REACH chemical safety obligations and EU Green Deal deforestation due diligence rules constrain palm-derived powder onboarding. Bavarian encapsulation technology specialists supply complex coacervation systems to domestic functional beverage manufacturers.
New Zealand
Fonterra Co-operative Group Limited anchors export volumes through backward integration into dairy cream sourcing across Waikato and Canterbury processing clusters. MPI dairy export certification protocols maintain Codex Alimentarius alignment for cross-border trade in infant formula ingredients. Auckland-based R&D facilities concentrate atomization physics expertise for high-fat-content agglomeration.
Australia
Victorian dairy processors develop specialized whey-lipid hybrid powders targeting endurance nutrition segments in North American and German markets. FSANZ food standards code revisions accommodate clean-label emulsification system approvals. Murray-Darling Basin feedstock supply chains support cost-competitive whole powder production for Asian export markets.
Instant Fat Powder Market Competitive Landscape
Player mix skews toward dairy cooperative conglomerates with captive upstream milkfat supply. Market structure concentrates around three to five integrated processors controlling spray-drying infrastructure scale economies. Strategic archetypes separate backward-integrated dairy giants from specialized lipid encapsulation technology providers and regional plant-derived powder innovators. Dominant competitive moves include capacity expansion in Southeast Asian coconut oil feedstock zones and technology licensing partnerships for complex coacervation microencapsulation.
Among dairy cooperative conglomerates, Fonterra Co-operative Group Limited and Kerry Group plc exemplify divergent strategic positioning within the supplier base. Fonterra represents the backward-integrated archetype with captive cream sourcing across Oceania. Kerry Group plc occupies a position as a specialized encapsulation technology provider with customized lipid system capabilities. Glanbia PLC anchors the whey-lipid hybrid powder segment serving endurance nutrition applications. These three entities collectively illustrate the competitive tension between commodity-scale dairy processing and premium functional ingredient specialization.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Fonterra Co-operative Group Limited |
| Arla Foods amba |
| FrieslandCampina |
| Vreugdenhil Dairy Foods |
| Kerry Group plc |
| Glanbia PLC |
| Lactalis Ingredients |
| Alpen Food Group |
| Others |
Supply & Pricing Matrix
Spray-drying infrastructure scale economies in New Zealand and Australian dairy processing clusters concentrate production capacity among three to five integrated processors, establishing price floors that smaller regional competitors cannot undercut without sacrificing emulsification performance specifications or oxidative shelf stability guarantees demanded by infant formula manufacturers and sports nutrition brands.
Pricing Analysis
Prior-generation whole powder formulations trade at commodity benchmarks against current-generation MCT powder premiums anchored by complex coacervation technology and next-generation modified lipid structures commanding formulation premiums for altered fatty acid profiles. Three-tier pricing structure across premium, standard, and economy levels separates sports nutrition brands seeking rapid dispersibility specifications from food and beverage manufacturers prioritizing oxidative stability over cold-water performance. Pricing pressure stems from coconut oil feedstock volatility in Southeast Asian producing regions compressing margin predictability for plant-derived alternatives. Sports nutrition brands exhibit lowest price sensitivity due to compressed twelve-week procurement cycles and formulation premium tolerance, while traditional food processors demonstrate highest sensitivity to input cost fluctuations.
Supply Chain Analysis
Port congestion at Auckland and Melbourne export terminals and container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for spray-dried fat powders bound for Chinese infant formula manufacturers. Geographic supply concentrates in New Zealand, Australia, and emerging Southeast Asian coconut oil processing zones in Indonesia and the Philippines. Raw material dependencies rest on dairy cream streams, medium-chain triglyceride feedstocks, and coconut oil supplies. Single-source vulnerability from Fonterra's backward integration into Oceania dairy cream sourcing creates concentration risk for global infant formula supply chains. Distribution runs through long-term offtake agreements with Chinese state-owned dairy processors and platform-based direct procurement channels serving United States and German sports nutrition brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulation technology licensing and formulation support services attach recurring revenue layers expanding faster than commodity powder production, as sports nutrition brands demand faster iteration cycles and technical consultation beyond standard ingredient supply.
For Market Incumbents: Secure captive spray-drying capacity expansion in Heilongjiang and Inner Mongolia processing clusters to defend against Chinese domestic dairy self-sufficiency programs eroding export market share. Deepen backward integration into dairy cream sourcing across Canterbury and Waikato to maintain cost position against emerging plant-derived powder innovators. Lock in Codex Alimentarius certification investments to extend qualification timeline advantages over new entrants seeking simultaneous EFSA novel food assessments.
For New Entrants and Emerging Players: EFSA pre-submission protocol engagement offers fastest certification pathway for coconut oil powder innovators seeking European market access despite extended toxicological dossier requirements. Target sports nutrition brand direct procurement platforms in California and Texas as most penetrable segment given compressed qualification tolerance and premium pricing acceptance. Pursue specialized whey-lipid hybrid powder white space in endurance nutrition applications where Glanbia PLC's incumbent position remains concentrated rather than dominant.
For Investors and Strategic Acquirers: Complex coacervation technology specialists with proprietary microencapsulation IP represent prime acquisition targets as reformulation trends fragment historical procurement relationships away from legacy dairy cooperatives. Long-term viability over the next decade hinges on regulatory navigation capabilities across FDA GRAS self-determination and EFSA novel food assessment frameworks. Monitor SAMR infant formula registration requirement tightening as inflection indicator for import dependency reduction and local production capacity absorption rates in Chinese processing clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Cream Sourcing | Fonterra's captive supply control across Oceania anchors cost position against feedstock volatility. |
| Complex Coacervation Technology Licensing | Kerry Group's lipid encapsulation partnerships fragment traditional dairy procurement relationships. |
| Domestic Spray-Drying Capacity Buildout | Chinese self-sufficiency programs in Heilongjiang reduce import dependency for infant formula. |
| EFSA Novel Food Pre-Submission Engagement | Front-loaded safety studies accelerate coconut oil powder market access despite regulatory friction. |
| Platform-Based Direct Procurement Launch | Sports nutrition brands in Germany and the United States bypass distributor margins through digital marketplaces. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed dairy processors, EFSA novel food assessment registers, and Codex Alimentarius standard documentation. Primary interviews engaged spray-drying engineering directors at New Zealand and Australian dairy cooperatives, procurement leads at United States and German sports nutrition brands, regulatory affairs specialists navigating FDA GRAS and EFSA approval pathways, and infant formula manufacturing executives at Chinese state-owned dairy processors. Bottom-up volume triangulation across product type, end user, and regional production clusters was cross-validated against top-down value estimates derived from export trade flows and capacity utilization benchmarks.
Segmentation dimensions modeled include product type stratification across whole powder, MCT powder, coconut oil powder, and palm oil powder; end user differentiation between sports nutrition brands, nutritional supplement manufacturers, food and beverage processors, and pharmaceutical companies; and regional production concentration across New Zealand, Australia, China, the United States, and Germany. CAGRs were derived from trend extrapolation of procurement cycle compression rates, domestic capacity buildout trajectories, and reformulation adoption curves across clean-label emulsification systems. Industry-specific forecast inputs incorporated spray-drying infrastructure investment pipelines and EFSA novel food assessment approval velocity.
The analysis sits within stated boundaries; outcomes outside sustained sports nutrition brand procurement acceleration, Chinese domestic self-sufficiency program execution, or EFSA regulatory timeline stability would require recalibration. Forecasts reflect documented assumptions around emulsification technology substitution rates and feedstock cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Japan Anti-Caking Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Middle East and Africa Food Starch Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market