
 Octadecanedioic Acid (ODDA) Market | 2026-2036
Octadecanedioic Acid (ODDA) Market Size, Share, and Industry Trends Forecast 2026-2036
Octadecanedioic Acid (ODDA) Market Intelligence
Specialty cosmetics formulators is redrawing procurement priorities across the long-chain diacid value chain, pulling volume away from conventional plastics compounders toward high-purity pharmaceutical and personal care grades. Cathay Biotech Inc. leverages its microbial fermentation platform to anchor supply security for biodegradable polymer feedstocks. BASF competes through integrated oleochemistry operations that sustain backward control over C18 dicarboxylic acid precursors. Croda International Plc. specializes in cosmetic-grade ester derivatives, occupying premium positions among European and Asia-Pacific fragrance houses.
Octadecanedioic acid is an 18-carbon straight-chain dicarboxylic acid with the molecular formula HOOC(CH2)16COOH, produced via petrochemical oxidation of oleic acid or through microbial fermentation of plant oils, and serves primarily as a building block for polyamides, polyesters, and specialty esters used in high-performance polymers and personal care formulations. The cosmetics application segment leads value capture due to formulation premiums for skin-conditioning diacids in anti-aging and moisturizing products, while biodegradable polymers represents the fastest-growing structural pocket as packaging regulations tighten across multiple jurisdictions. Surfactants maintains mature volume throughput in industrial cleaning and textile processing, though margin pools are compressing amid feedstock volatility.
EPA bio-based chemical classifications under the Toxic Substances Control Act and REACH registration requirements administered by ECHA are elevating analytical burden and documentation costs for producers seeking multi-jurisdiction market access, with China's GB standards for industrial chemicals adding a third compliance layer for export-oriented manufacturers. FDA oversight of cosmetic ingredient safety through the Modernization of Cosmetics Regulation Act introduces new substantiation requirements that favor suppliers with validated toxicological dossiers. Stakeholders must monitor regulatory divergence between bio-based preference schemes and conventional petrochemical equivalency standards to calibrate capital allocation across fermentation and synthetic process routes.
Market Dynamics
Fermentation-based production platforms are redrawing competitive boundaries between petrochemical and bio-based supply chains, forcing compounders to requalify feedstock sources against tightening pharmaceutical-grade specifications.
Growth Catalysts
- REACH registration tiering:ECHA's elevated documentation requirements for polymer-grade diacids favor suppliers with validated toxicological dossiers, accelerating consolidation among compliant producers.
- Specialty cosmetics formulators:Premium personal care brands are pulling volume toward high-purity ester derivatives for skin-conditioning applications, creating dedicated supply lanes separate from industrial grades.
- China's dual carbon goals:Beijing's fermentation capacity expansion targets are scaling domestic bio-based diacid output to serve regional surfactant and lubricant compounders.
Market Restraints
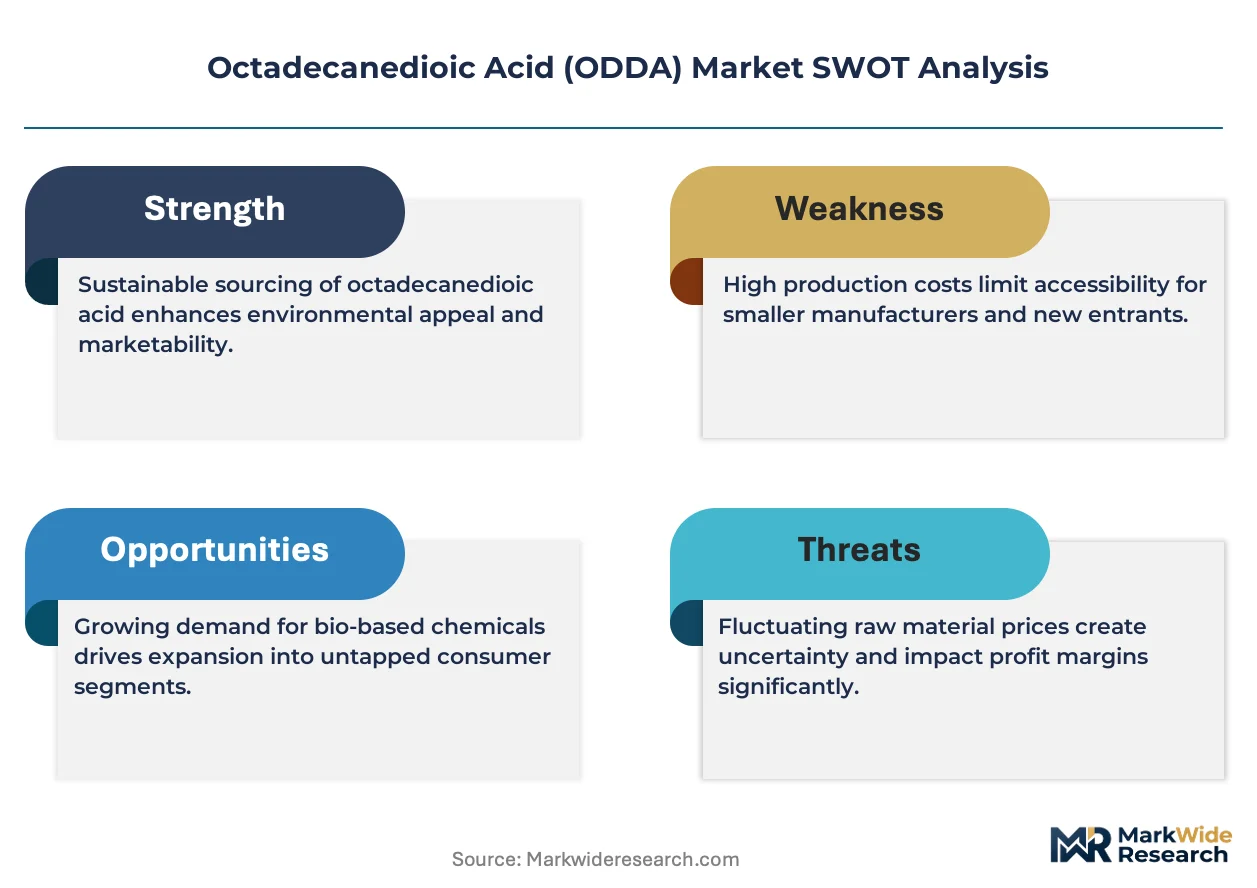
- Plant oil feedstock volatility:Oleic acid price swings transmit directly into fermentation economics, compressing margin predictability for bio-based producers.
- Technical limitation in purity thresholds:Polymer-grade specifications above 99.5% purity remain difficult to achieve consistently at commercial scale via microbial routes.
- Substitution threat from sebacic acid:Shorter-chain C10 diacids offer comparable performance in certain polyamide applications at lower cost positions.
Strategic Opportunities
- Underpenetrated biodegradable packaging:France's extended producer responsibility mandates are creating dedicated demand pockets for compostable polymer feedstocks.
- Technology convergence:CRISPR-edited yeast strains combined with continuous fermentation systems are opening yield improvements previously unattainable with batch processes.
- Regulatory tailwind from EPA bio-based preference:USDA BioPreferred program procurement quotas are directing federal purchasing toward certified bio-based diacid derivatives.
Industry Challenges
- Skill scarcity in fermentation scale-up:Industrial microbiology talent capable of translating lab yields to commercial bioreactor performance commands premium compensation.
- Certification timeline compression:FDA Modernization of Cosmetics Regulation Act substantiation requirements are extending new ingredient approval cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octadecanedioic Acid (ODDA) Market |
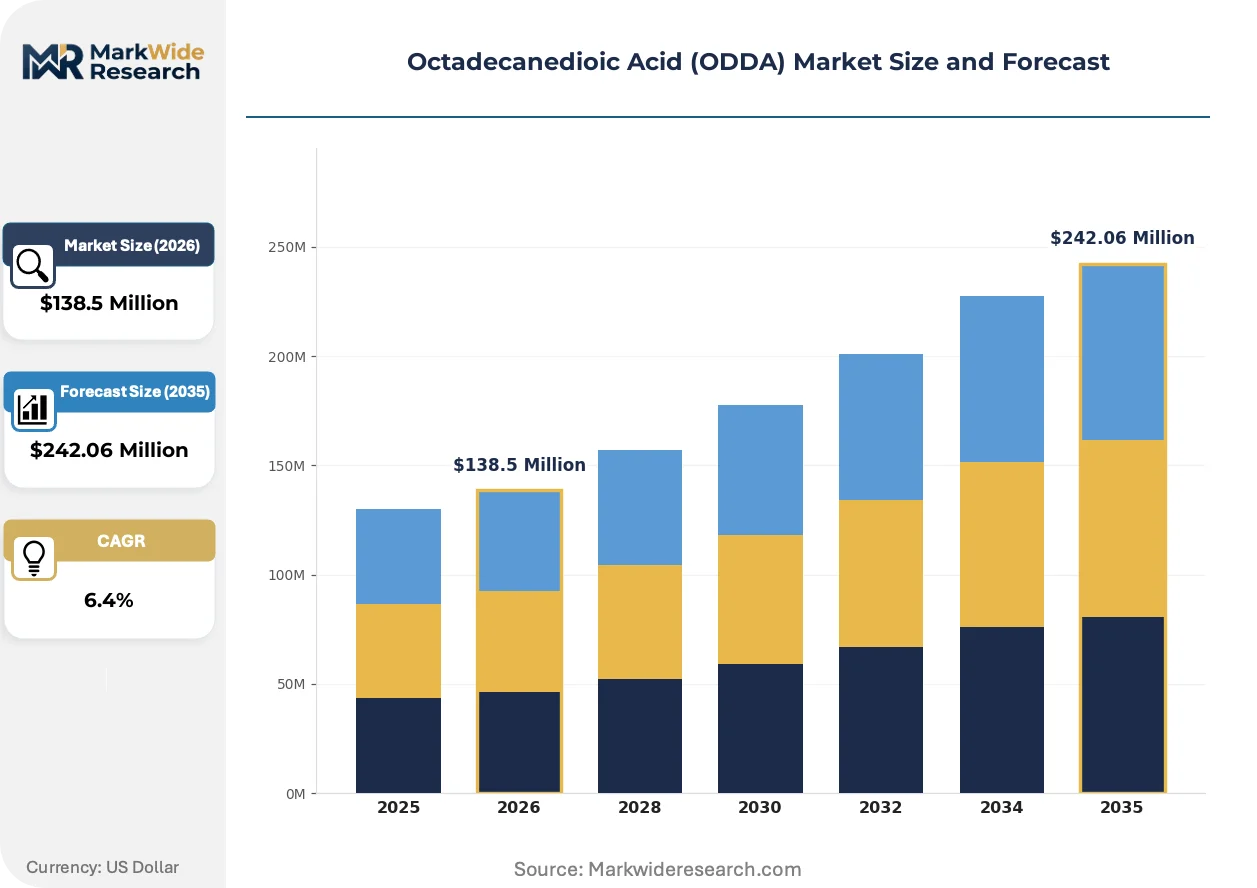
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $242.06 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Polymers, Coatings, Surfactants, Lubricants Application: Cosmetics, Food Additives, Plastics, Pharmaceuticals End User: Manufacturers, Distributors, Retailers, Research Institutions Packaging Type: Drums, Bags, Canisters, Bulk Containers |
| Companies Covered | Elevance Renewable Sciences, Inc., Cathay Biotech Inc., TCI Chemicals (India) Pvt. Ltd., Hunan HuaTeng Pharmaceutical Co., Ltd., XIAMEN SINOPEG BIOTECH CO., LTD., Nanjing Chemlin Chemical Industry Co., Ltd., BASF, Croda International Plc., Larodan AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octadecanedioic Acid (ODDA) Market Strategic Shifts & Innovations
Process intensification and regulatory fragmentation are simultaneously compressing production economics and expanding compliance burdens across the long-chain diacid value chain.
Precision fermentation using CRISPR-edited Yarrowia lipolytica strains is miniaturizing the gap between laboratory yields and commercial-scale titers. Specialty polymer compounders in Germany and Japan are adopting these biocatalysts ahead of pharmaceutical-grade specifications. The technology is miniaturizing capital requirements for entry-level producers, enabling regional supply nodes that bypass concentrated petrochemical hubs.
REACH authorization procedures under ECHA's sunset clause timeline are forcing early re-registration of existing diacid substances ahead of 2026 deadlines. This regulatory pressure is diverting technical resources toward dossier compilation rather than product innovation. European cosmetic ingredient suppliers are responding by segregating pharmaceutical-grade production lines from industrial material to isolate compliance risk.
Direct long-term contracting between fermentation operators and specialty cosmetics houses is displacing traditional distributor intermediaries in high-purity segments. This channel compression is most visible in South Korea and France, where fragrance houses seek traceability assurances for clean beauty certifications. The shift is compressing working capital cycles for qualified producers while stranding inventory-heavy traders in commoditized industrial grades.
Octadecanedioic Acid (ODDA) Market Segmentation
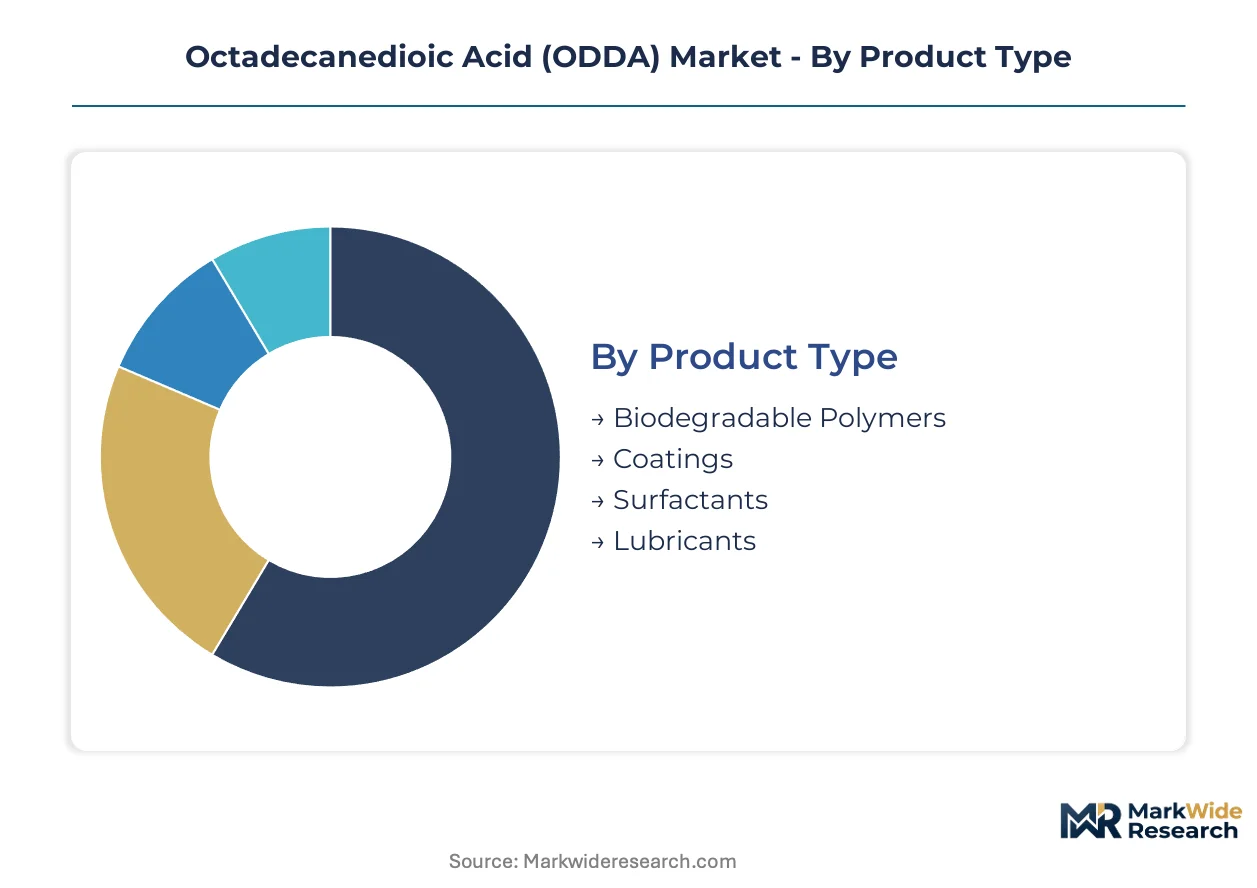
ODDA segmentation reveals divergent purity requirements across end-use verticals, with pharmaceutical and cosmetic grades commanding premium positions while industrial applications absorb volume at lower specifications. Procurement patterns fragment sharply between domestic fermentation-based supply in China and export-oriented specialty chemical distributors serving European fragrance houses.
Product Type:
Domestic consumption concentrates in biodegradable polymers and surfactants across Chinese and Indian compounding facilities, while coatings and lubricants flow disproportionately through export channels into German automotive and Japanese precision manufacturing supply chains.
- Biodegradable Polymers:Polyamide and polyester precursors requiring polymer-grade purity above 99.5% serve compostable packaging mandates in France and extended producer responsibility schemes across the European Union. Chinese fermentation capacity expansion targets this segment for regional surfactant and lubricant compounders seeking bio-based feedstock security.
- Surfactants:Long-chain diacid derivatives function as emulsifiers and wetting agents in industrial cleaning formulations and textile processing applications. Mature volume throughput characterizes this segment, though margin pools compress amid oleic acid feedstock volatility transmitting directly into fermentation economics.
- Coatings:Corrosion-resistant polyester resins and powder coating applications absorb technical-grade material at moderate purity thresholds.
- Lubricants:Synthetic ester base stocks for high-performance automotive and aviation fluids require thermal stability specifications.
Surfactants commands the established base. The steepest expansion runs through biodegradable polymers.
Application:
Cost tier stratification separates pharmaceutical-grade certification requirements from industrial material, with cosmetics and food additives absorbing compliance documentation burdens that plastics compounders avoid.
- Cosmetics:Skin-conditioning diacids in anti-aging and moisturizing formulations capture formulation premiums through high-purity ester derivatives. South Korean and French fragrance houses are compressing distribution channels through direct long-term contracting with fermentation operators to secure traceability assurances for clean beauty certifications.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications demand validated toxicological dossiers under FDA Modernization of Cosmetics Regulation Act substantiation requirements. ECHA REACH registration tiering favors suppliers with existing documentation, accelerating consolidation among compliant producers serving this segment.
- Plastics:Engineering polymer feedstocks for automotive and electrical components compete against shorter-chain C10 diacid substitutes.
- Food Additives:Lubricant and release agent applications in food processing equipment face evolving EPA bio-based chemical classifications.
Cosmetics holds the premium pricing position. Pharmaceuticals is climbing the fastest on regulatory tailwinds.
End User:
Volume concentration sits with manufacturers integrating backward into fermentation capacity, while research institutions drive specification evolution for emerging CRISPR-edited yeast strain applications.
- Manufacturers:Polymer compounders and specialty chemical producers constitute the core demand base, with Cathay Biotech and BASF anchoring supply security through captive fermentation platforms and integrated oleochemistry operations respectively.
- Distributors:Traditional intermediaries face channel compression as qualified producers bypass inventory-heavy traders in high-purity segments.
- Retailers:Minimal direct engagement; indirect exposure through private-label cosmetic and personal care product lines.
- Research Institutions:CRISPR-edited Yarrowia lipolytica strain development and continuous fermentation system optimization.
Manufacturers absorb the dominant share. Research institutions are gaining influence fastest on technology convergence.
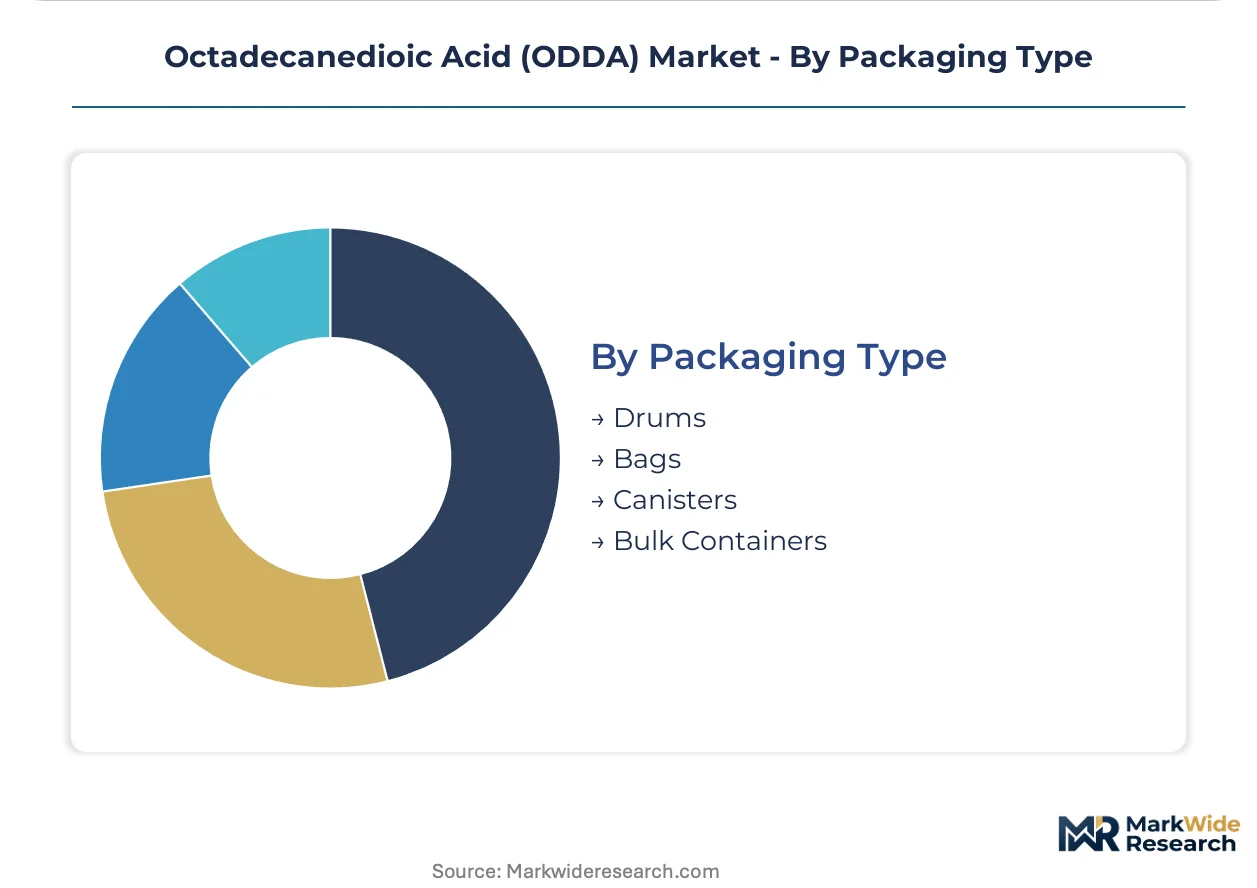
Packaging Type:
Customer type differentiation separates bulk container procurement by polymer compounders from drum and canister specifications serving pharmaceutical and cosmetic formulators requiring contamination control.
- Bulk Containers:Tanker and ISO-tank deliveries serve high-volume biodegradable polymer and surfactant producers with dedicated logistics infrastructure.
- Drums:Standard 200-liter specifications dominate mid-scale coatings and lubricant applications with established handling protocols.
- Bags:Powder and flake formulations for food additive and select pharmaceutical powder handling requirements.
- Canisters:Sealed containment for high-purity cosmetic and pharmaceutical grades requiring moisture and oxygen exclusion.
Bulk containers handle the volume base. Canisters are expanding most quickly on purity grade proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deep Water Port anchors Asia-Pacific logistics for fermentation-derived diacid feedstocks, while Rotterdam's Maasvlakte terminals handle European polymer-grade material flows. These maritime nodes concentrate customs clearance expertise for REACH-registered and GB-certified chemical classifications.
China
Fermentation capacity expansion in Shandong Province serves domestic surfactant compounders and lubricant blenders. MIIT's dual carbon goals accelerate bio-based chemical subsidies for C18 diacid producers. Qingdao's chemical industrial park clusters bioreactor operations supplying regional polyamide manufacturers.
Germany
Specialty polymer compounders in North Rhine-Westphalia absorb technical-grade material for automotive underhood applications. ECHA REACH authorization timelines force early re-registration of existing diacid substances ahead of sunset clause deadlines. Leverkusen's integrated chemical parks sustain backward control over oleochemistry precursors through captive cracking units.
United States
USDA BioPreferred program procurement quotas direct federal purchasing toward certified bio-based diacid derivatives for packaging applications. EPA bio-based chemical classifications under TSCA elevate documentation burdens for import shipments. Houston's petrochemical corridor maintains oxidation-based production of polymer-grade material for Gulf Coast polyamide plants.
South Korea
Cosmetic formulators in Seoul Capital Area compress distribution channels through direct long-term contracting with fermentation operators. MFDS cosmetic ingredient safety requirements align with clean beauty certification trends among fragrance houses. Incheon's free economic zone concentrates customs processing for high-purity pharmaceutical-grade imports.
France
Extended producer responsibility mandates for compostable packaging create dedicated demand pockets in Île-de-France. ANSM oversight of cosmetic ingredient safety intersects with EU Green Deal bio-based preference schemes. Lyon-Saint-Exupéry's air cargo hub handles temperature-controlled canister shipments for pharmaceutical-grade specifications.
Octadecanedioic Acid (ODDA) Market Key Industry Players
Concentration sits with integrated oleochemistry operators and microbial fermentation platforms that have achieved polymer-grade purity thresholds. The supplier base stratifies into three tiers: multinational chemical conglomerates with backward integration into plant oil feedstocks, mid-cap biotech specialists leveraging CRISPR-edited yeast strains, and regional distributors facing channel compression in high-purity segments. Dominant competitive moves include capacity expansion in Chinese fermentation hubs and strategic partnerships between biotech platforms and specialty cosmetics houses seeking traceability assurances.
Among Asia-Pacific fermentation specialists, Cathay Biotech Inc. exemplifies the biotech platform archetype through its microbial production infrastructure. BASF occupies a position within the integrated oleochemistry tier, leveraging captive control over C18 dicarboxylic acid precursors. Croda International Plc. represents the specialty ester derivative segment, serving premium positions among European fragrance houses requiring validated toxicological dossiers.
| Leading Market Players |
|---|
| Elevance Renewable Sciences, Inc. |
| Cathay Biotech Inc. |
| TCI Chemicals (India) Pvt. Ltd. |
| Hunan HuaTeng Pharmaceutical Co., Ltd. |
| XIAMEN SINOPEG BIOTECH CO., LTD. |
| Nanjing Chemlin Chemical Industry Co., Ltd. |
| BASF |
| Croda International Plc. |
| Larodan AB |
| Others |
Cost & Logistics Intelligence
Sebacic acid substitution in polyamide applications simultaneously redraws supply geography toward C10 diacid producers in China and compresses pricing economics for C18 material across European compounding facilities. This displacement dynamic forces ODDA suppliers to defend premium positions through purity differentiation while fermentation operators absorb oleic acid volatility in their feedstock cost structures.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade canister shipments from bulk container deliveries to polymer compounders, with pricing stratifies across premium cosmetic certification, standard industrial grade, and economy surfactant tiers. Price differentiation hinges on REACH registration completeness and FDA cosmetic ingredient substantiation status, with certified bio-based material commanding position above petrochemical equivalents. Cost compression in industrial grades intensifies as Chinese fermentation capacity scales toward regional self-sufficiency. Surfactant compounders exhibit highest price sensitivity due to commoditized end-markets, while fragrance houses in South Korea and France absorb premiums for validated toxicological dossiers.
Supply Chain Analysis
Strategic stockpile preferences dominate among European cosmetic formulators facing REACH sunset clause deadlines, while just-in-time procurement characterizes Chinese surfactant compounders with domestic fermentation feedstock security. Geographic supply concentration centers on Shandong Province bioreactor clusters, Rotterdam polymer-grade import terminals, and Houston oxidation-based production corridors. Raw material dependencies draw from oleic acid plant oil streams, CRISPR-edited Yarrowia lipolytica biocatalyst strains, and C18 dicarboxylic acid precursor oleochemistry. Single-source vulnerability runs through concentrated fermentation microbiology talent pools capable of commercial scale-up. Distribution runs through direct long-term contracting channels displacing traditional distributor intermediaries in high-purity segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent ODDA producers face a substitution defense imperative against sebacic acid encroachment in polyamide applications, requiring strategic repositioning toward purity-tiered segments where C10 diacids cannot replicate performance.
For Market Incumbents: Compound supply security through backward integration into plant oil feedstock processing or captive fermentation infrastructure in Shandong Province chemical parks. Deepen certification moats by accelerating FDA cosmetic ingredient substantiation ahead of Modernization of Cosmetics Regulation Act enforcement timelines. Isolate compliance risk through segregated pharmaceutical-grade production lines distinct from industrial material flows.
For New Entrants and Emerging Players: Anchor in underpenetrated biodegradable packaging demand pockets created by French extended producer responsibility mandates for compostable polymer feedstocks. Target white-space capture through CRISPR-edited yeast strain licensing to regional fermentation operators lacking internal R&D capabilities. Pursue direct supply relationships with Seoul Capital Area fragrance houses seeking traceability assurances for clean beauty certifications.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap biotech platforms with validated polymer-grade purity thresholds and existing REACH registration dossiers rather than greenfield fermentation projects facing 18-24 month approval cycles. Long-term viability across the projection horizon rests on regulatory divergence between bio-based preference schemes and petrochemical equivalency standards. The signal to watch is ECHA authorization timeline compression for existing diacid substances ahead of sunset clause deadlines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemistry | BASF's captive C18 precursor control insulates margin from oleic acid volatility. |
| CRISPR Strain Licensing Partnership | Technology convergence enables yield improvements unattainable with batch fermentation. |
| REACH Registration Acceleration | ECHA tiering favors suppliers with validated toxicological dossiers ahead of deadlines. |
| Direct Long-term Supply Contracting | Channel compression with South Korean fragrance houses bypasses inventory-heavy traders. |
| Pharmaceutical-Grade Line Segregation | Isolated production isolates compliance risk from industrial material contamination. |
Research Approach
A spread of perspectives from fermentation plant managers, specialty cosmetics procurement leads, polymer compounder technical directors, and ECHA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC chemical company filings, and MIIT bio-based chemical subsidy disclosures. Bottom-up triangulation across production capacity announcements and top-down demand modeling across end-use verticals anchored volume and value estimates.
Segmentation dimensions modeled include purity grade tier, end-use industry application, packaging format specification, and regional production hub concentration across the analysis window. CAGRs were derived from weighted average growth trajectories calibrated against historical capacity utilization patterns and announced expansion timelines. Industry-specific forecast inputs incorporated oleic acid price elasticity coefficients and REACH registration completion rates for polymer-grade material.
Decision-makers should treat outputs as directional under assumptions of sustained dual carbon policy support in China and stable ECHA authorization timelines; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding fermentation yield improvements from CRISPR-edited strains and continued bio-based preference scheme expansion. Revision becomes warranted when sebacic acid substitution rates in polyamide applications cross thresholds that compress C18 diacid pricing premiums below fermentation cost floors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Amaranth (E123) Market