
 Ph Adjuster Market | 2026-2036
Ph Adjuster Market Size, Share, and Industry Trends Forecast 2026-2036
Ph Adjuster Market Analytics
Organic acid buffers derived from citric and lactic acid feedstocks is broadening the addressable market for food-grade pH adjusters as clean-label formulation requirements intensify. BASF leverages its integrated fermentation capabilities to secure captive supply of bio-based acids across European personal care and beverage accounts. Kemira anchors Nordic water treatment demand through long-term municipal contracts and proprietary polymer-activated buffer systems. Evonik Industries specializes in high-purity amine-based adjusters for pharmaceutical injectable formulations, commanding premium positioning in GMP-certified supply chains.
A pH adjuster is a chemical additive or formulated system designed to modify hydrogen ion concentration in aqueous solutions, typically expressed through titratable acidity, buffer capacity, or target pH setpoint measured to 0.01 precision. These substances function through neutralization, buffering, or redox-mediated proton transfer mechanisms to stabilize process conditions across industrial, agricultural, and consumer applications. The chemicals component dominates volume throughput in agricultural lime and sulfuric acid applications where commodity scale offsets thin margins. Pharmaceutical-grade solutions command the highest value per kilogram due to USP-NF and EP monograph compliance burdens and validated manufacturing documentation. Water treatment represents the fastest-growing application vector as stricter effluent standards force retrofit of continuous monitoring and automated dosing infrastructure across municipal and industrial facilities.
EPA effluent limitation guidelines under the Clean Water Act shape product formulation requirements for industrial discharge compliance in US manufacturing zones. REACH registration obligations and the EU Green Deal chemical sustainability framework constrain import and production of certain mineral acid categories across European member states. FDA 21 CFR Part 173 and FCC monographs govern food-grade adjuster purity specifications, creating dual-track certification requirements for suppliers serving multiple end-use verticals. Stakeholders must monitor evolving PFAS restrictions and perchlorate limits, as these contaminants increasingly appear in source water supplies and threaten buffer system integrity in precision applications.
Market Dynamics
Automated dosing infrastructure is restructuring competitive positioning across municipal and industrial water treatment, as facilities retrofit continuous monitoring systems to meet tightening effluent mandates from EPA and Central Pollution Control Board authorities.
Growth Catalysts
- Clean Water Act effluent guidelines:EPA discharge limits are compelling US manufacturing zones to install automated pH control systems, expanding addressable demand for precision buffer formulations.
- Bio-based acid fermentation:Food-grade citric and lactic acid buffers are capturing clean-label formulation requirements in European beverage and personal care verticals.
- Shanghai industrial corridor concentration:Semiconductor fabs and chemical complexes in China's Yangtze River Delta are driving ultrapure pH adjuster procurement for process-critical applications.
Market Restraints
- Sulfuric acid feedstock volatility:Agricultural lime and mineral acid applications face margin compression from energy-intensive sulfur processing costs.
- REACH registration burdens:ECHA compliance obligations constrain import flexibility for certain mineral acid categories across European member states.
- High-purity amine substitution limits:Pharmaceutical-grade applications lack technically viable alternatives to validated USP-NF and EP monograph systems.
Strategic Opportunities
- India municipal water infrastructure:Central Pollution Control Board enforcement gaps in tier-2 cities create first-mover positioning for automated dosing system providers.
- Polymer-activated buffer convergence:Integration of synthetic polymer chemistry with bio-based acid platforms enables next-generation municipal water treatment formulations.
- CE marking pathway acceleration:EU Green Deal chemical sustainability frameworks are redirecting R&D investment toward fermentation-derived buffer systems.
Industry Challenges
- Validated manufacturing documentation:GMP-certified supply chains for pharmaceutical injectable formulations require 18-24 month qualification timelines that delay product commercialization.
- Legacy SCADA integration:Municipal water treatment facilities face protocol incompatibility when retrofitting continuous pH monitoring onto decades-old distributed control architectures.
- PFAS contamination detection:Perfluoroalkyl substance interference in source water supplies threatens buffer system integrity and requires reformulation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ph Adjuster Market |
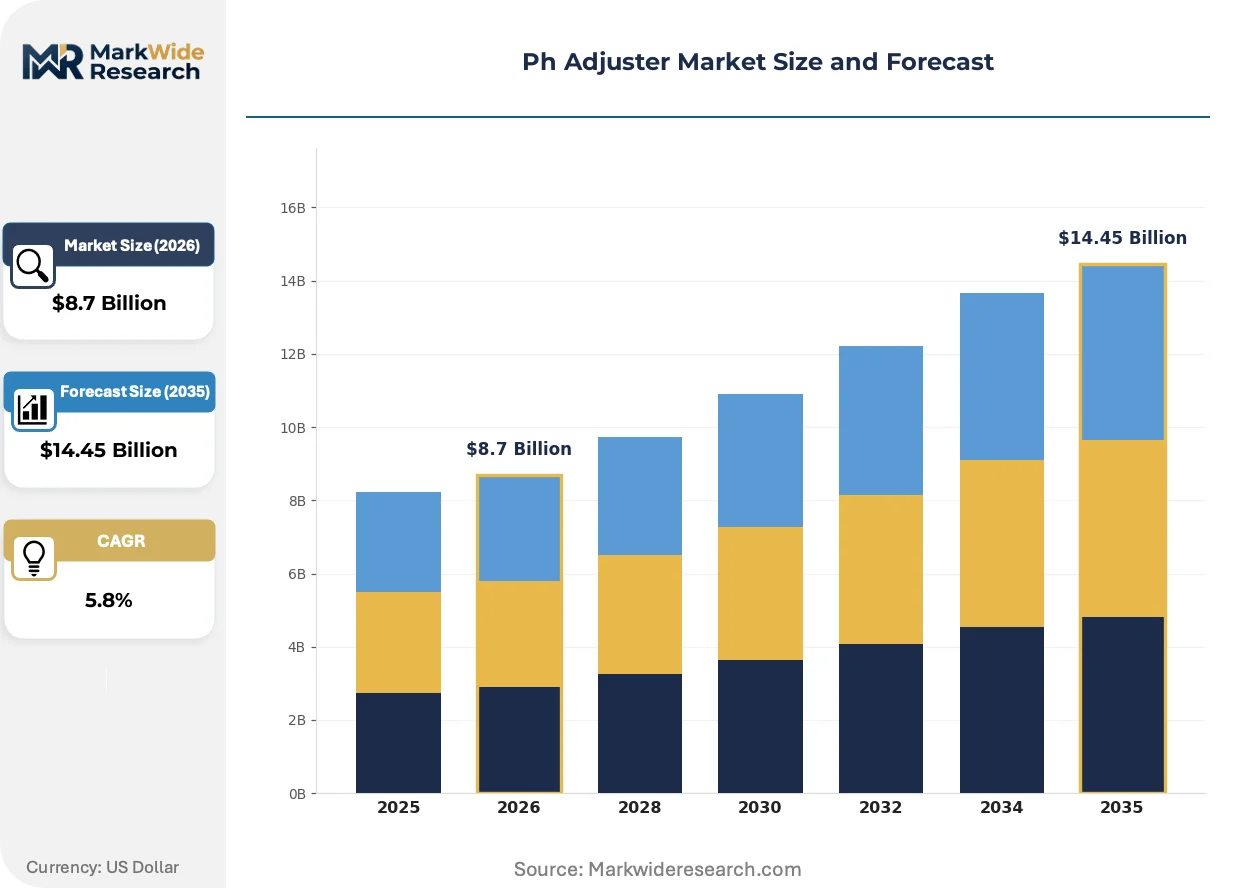
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Chemicals, Solutions, Forms, Tablets Application: Agricultural, Water Treatment, Food Processing, Pharmaceuticals End User: Agriculture, Municipalities, Industrial Facilities, Laboratories Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | BASF, DowDuPont, Evonik Industries, AkzoNobel, Ashland, Air Products and Chemicals, Solvay, Eastman Chemical Company, Kemira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ph Adjuster Market Evolving Landscape
Digitalization of process control is compressing specification cycles across water treatment and pharmaceutical manufacturing, while bio-based feedstock innovation and regulatory chemical sustainability mandates are redrawing formulation roadmaps.
Microfluidic pH sensing platforms are modularizing quality control architectures in semiconductor manufacturing and pharmaceutical production. Taiwan Semiconductor Manufacturing and Samsung Foundry fabs are deploying chip-scale titration systems for real-time bath monitoring. This technology is modularizing previously centralized laboratory workflows into distributed process nodes, reducing sampling latency from hours to seconds.
EU Green Deal chemical sustainability frameworks are constraining mineral acid production permits across German and Dutch chemical corridors. REACH registration obligations now require lifecycle carbon disclosure for buffer system imports. Pharmaceutical and food-grade suppliers are responding by accelerating fermentation-derived citric acid capacity expansion to maintain European market access.
Specification-driven procurement is consolidating vendor relationships in municipal water treatment as facilities seek single-source accountability for automated dosing infrastructure. German municipalities are bundling pH adjuster supply with sensor calibration and predictive maintenance contracts. This pattern is most visible in Nordic markets where Kemira anchors long-term service agreements combining chemical supply with digital monitoring platforms.
Ph Adjuster Market Segmentation
pH adjuster procurement patterns diverge sharply between bulk commodity applications and precision-controlled environments, with integration depth determining whether buyers specify standalone chemicals or complete buffered systems with automated dosing infrastructure.
Component:
Chemicals function as standalone inputs in agricultural and heavy industrial settings, while solutions, forms, and tablets embed into integrated process control architectures with sensor feedback loops.
- Chemicals:Sulfuric acid, hydrochloric acid, and sodium hydroxide constitute high-volume commodity inputs for agricultural lime applications and municipal water treatment basins. Demand concentrates in China's Yangtze River Delta industrial corridor, where sulfur processing costs and energy intensity compress margins for mineral acid suppliers.
- Solutions:Pre-formulated buffer systems with defined titratable acidity and documented stability profiles serve pharmaceutical injectable manufacturing and semiconductor wafer processing. German municipalities are bundling solution supply with predictive maintenance contracts under long-term service agreements that consolidate vendor relationships.
- Forms:Encapsulated or solid-state adjusters enable controlled-release applications in remote agricultural settings and field-deployed water treatment units where liquid handling infrastructure is absent.
- Tablets:Unit-dose formats support laboratory calibration workflows and small-scale food processing operations requiring precise, contamination-free dispensing without liquid measurement equipment.
Chemicals lead volumes today; solutions are gaining share fastest.
Application:
Cost tier stratification separates thin-margin bulk treatment from premium-certified segments where documentation burden and purity specifications multiply value per kilogram.
- Water Treatment:Continuous monitoring and automated dosing infrastructure retrofits across US manufacturing zones and Indian tier-2 cities are expanding procurement of precision buffer formulations. EPA effluent limitation guidelines and Central Pollution Control Board enforcement gaps create divergent compliance timelines across geographies.
- Pharmaceuticals:USP-NF and EP monograph compliance requirements for injectable formulations impose 18-24 month GMP qualification timelines that delay commercialization and sustain premium positioning for validated suppliers.
- Food Processing:Clean-label formulation requirements in European beverage and personal care verticals are displacing mineral acids with fermentation-derived citric and lactic acid buffers.
- Agricultural:Lime and sulfur-based soil amendments operate at commodity scale with minimal specification differentiation, leaving suppliers exposed to energy-intensive feedstock volatility.
Water treatment commands the steepest expansion trajectory; agricultural applications anchor baseline volume throughput.
End User:
Customer type determines whether procurement flows through centralized municipal contracting, fragmented industrial spot purchasing, or specialized laboratory supply channels.
- Municipalities:German and Indian water treatment facilities are scaling automated pH dosing system procurement as discharge mandates tighten, with Nordic markets consolidating around bundled chemical-plus-digital service agreements.
- Industrial Facilities:Semiconductor fabs in Shanghai and chemical complexes require ultrapure pH control with real-time bath monitoring, driving specification-driven vendor consolidation.
- Agriculture:Lime application for soil pH management operates through distributed dealer networks with minimal technical service attachment.
- Laboratories:Calibration-standard buffers and reference materials demand documented traceability and certified stability data for analytical method validation.
Municipalities lead contract value today; industrial facilities are climbing the fastest on ultrapure specification premiums.
Distribution Channel:
Supply concentration in bulk chemicals favors wholesale and direct sales, while technical formulations fragment across distributor networks with service capabilities.
- Distributors:Regional chemical distributors with technical service capabilities capture formulated solutions and specialty buffers requiring storage condition management and application engineering support.
- Direct Sales:Large-volume municipal and industrial accounts negotiate direct supply agreements for commodity acids and bases with dedicated logistics arrangements.
- Wholesale:Agricultural lime and bulk mineral acids flow through cooperative purchasing arrangements and commodity trading channels with minimal value-added services.
- Online Retail:Laboratory-grade tablets and calibration buffers for small-scale users and research institutions migrate to specialized scientific supply platforms with documented certificate of analysis availability.
Direct sales lead volume concentration today; distributor channels are expanding most quickly on service-integrated solution sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta industrial corridor anchors pH adjuster procurement intensity, with semiconductor fabs and chemical complexes driving ultrapure specification demand. Municipal water treatment retrofits across Germany and India are accelerating automated dosing system deployment. Regulatory divergence between EPA effluent guidelines and Central Pollution Control Board enforcement timelines is creating geographically staggered compliance windows.
United States
EPA effluent limitation guidelines under the Clean Water Act are compelling manufacturing zones across Texas and Louisiana to install continuous pH monitoring infrastructure. The agency's tightening discharge limits for heavy metals and acidity are expanding procurement of precision buffer formulations. Houston's petrochemical corridor represents the densest concentration of retrofit activity, with facilities automating previously manual dosing basins.
Germany
The EU Green Deal chemical sustainability framework is constraining mineral acid production permits across the Rhine-Ruhr and Ludwigshafen chemical corridors. ECHA REACH registration obligations now require lifecycle carbon disclosure for buffer system imports. Bavarian municipalities are bundling pH adjuster supply with predictive maintenance contracts under long-term service agreements that consolidate vendor relationships around single-source accountability.
China
MEE discharge standards for semiconductor manufacturing effluent are tightening proton concentration limits in wafer fabrication facilities. Dual carbon goals are redirecting investment toward fermentation-derived acid capacity in Jiangsu and Zhejiang provinces. The Yangtze River Delta surrounding Shanghai maintains the highest density of ultrapure pH control procurement, with SMIC and Hua Hong Semiconductor fabs requiring real-time bath monitoring systems.
India
Central Pollution Control Board enforcement gaps in tier-2 cities are creating first-mover positioning for automated dosing system providers ahead of mandate alignment. The PLI scheme for specialty chemicals is incentivizing domestic buffer formulation capacity in Gujarat and Maharashtra. Mumbai-Pune industrial belt chemical complexes are piloting continuous monitoring retrofits as discharge standards tighten for pharmaceutical manufacturing effluent.
Ph Adjuster Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation-derived bio-acid platforms displace mineral acid capacity. The vendor base organizes around three tiers: integrated chemical conglomerates with captive fermentation assets, water treatment specialists bundling chemical supply with digital monitoring platforms, and pharmaceutical-grade pure-play suppliers commanding GMP-certified premiums. Strategic archetypes include backward-integrated fermentation operators, specification-driven municipal contractors, and validated injectable-grade specialists. M&A activity concentrates on bio-based buffer technology acquisition, while geographic expansion targets Indian municipal infrastructure gaps.
Among European integrated chemical producers, BASF leverages captive fermentation capabilities across personal care and beverage accounts. Kemira anchors Nordic municipal water treatment demand through long-term service agreements combining chemical supply with digital monitoring platforms. Evonik Industries occupies the pharmaceutical-grade tier, specializing in high-purity amine-based adjusters for injectable formulations where USP-NF and EP monograph compliance sustains premium positioning.
| Leading Market Players |
|---|
| BASF |
| DowDuPont |
| Evonik Industries |
| AkzoNobel |
| Ashland |
| Air Products and Chemicals |
| Solvay |
| Eastman Chemical Company |
| Kemira |
| Others |
Value Network & Pricing Analysis
German municipal water treatment authorities anchor the most consolidated buyer concentration, locking in long-term service agreements that bundle chemical supply with predictive maintenance and shift procurement from transactional spot purchasing toward outcome-based contracting models.
Pricing Analysis
Energy-intensive sulfur processing costs pass through directly to agricultural lime and mineral acid tiers, compressing margins for commodity-grade suppliers. Three-tier pricing structure across pharmaceutical-grade, industrial-certified, and commodity-economy levels separates USP-NF compliant injectable formulations from municipal water treatment basins. Cost compression in mineral acid feedstocks is intensifying because European energy pricing volatility and carbon border adjustment mechanisms. Agricultural applications exhibit highest price sensitivity due to undifferentiated product specifications and dealer network fragmentation, while pharmaceutical-grade buyers accept premium positioning for validated GMP documentation.
Supply Chain Analysis
India's PLI scheme for specialty chemicals and China's dual carbon goals are reshaping sourcing patterns through domestic-content mandates that redirect fermentation-derived acid capacity toward local manufacturing. Supply concentrates in Germany's Ludwigshafen corridor, China's Jiangsu province, and India's Gujarat chemical belt. Production draws from citric acid fermentation biomass, sulfur-based mineral acid feedstocks, and high-purity amine precursors. Single-source vulnerability around pharmaceutical-grade amine suppliers threatens buffer system integrity. Distribution runs through direct sales channels for municipal and industrial accounts, with regional distributors capturing formulated solutions requiring technical service attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pH adjuster market reads as a late-cycle quality story where semiconductor fabs and pharmaceutical injectable manufacturers are forcing specification upgrades toward ultrapure and GMP-certified grades.
For Market Incumbents: Deploy captive fermentation asset expansion to defend against bio-based acid substitution threats from European clean-label formulation mandates. BASF and Kemira are anchoring Nordic and German municipal accounts through backward integration into polymer-activated buffer systems. Incumbents must accelerate CE marking pathways under EU Green Deal frameworks to maintain European market access as REACH registration obligations tighten. For New Entrants and Emerging Players: Launch via specification-driven service bundling in Indian tier-2 cities where Central Pollution Control Board enforcement gaps create first-mover windows for automated dosing infrastructure. The most penetrable white-space sits in polymer-activated buffer convergence platforms that integrate synthetic polymer chemistry with fermentation-derived acid bases. Target semiconductor fabs in China's Yangtze River Delta through ultrapure certification partnerships with SMIC and Hua Hong Semiconductor. For Investors and Strategic Acquirers: Water treatment specialists with digital monitoring platforms are the most active acquirer in this space, consolidating fragmented municipal service contracts into integrated chemical-plus-software offerings. The long-term viability window favors validated GMP-certified suppliers over commodity mineral acid operators exposed to energy feedstock volatility. Watch PFAS contamination detection thresholds in source water supplies as the critical inflection signal requiring buffer reformulation investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Assets | BASF secures captive citric acid supply for European beverage and personal care clean-label formulations. |
| Automated Dosing Infrastructure Deployment | Kemira anchors Nordic municipal contracts through bundled chemical supply with predictive maintenance platforms. |
| Pharmaceutical-Grade GMP Certification | Evonik Industries commands premium positioning for USP-NF compliant amine-based injectable adjusters. |
| Polymer-Activated Buffer Convergence | Integration of synthetic polymer chemistry with bio-acid platforms enables next-generation municipal water treatment. |
| CE Marking Pathway Acceleration | EU Green Deal chemical sustainability frameworks redirect R&D toward fermentation-derived buffer systems. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with municipal procurement officers, semiconductor fab process engineers, pharmaceutical regulatory affairs leads, and agricultural dealer network managers with secondary validation through EPA effluent filings, ECHA REACH registration databases, Central Pollution Control Board discharge records, and SEC 10-K chemical segment disclosures.
Historical trendline analysis across titratable acidity demand curves and buffer capacity installation rates informs the projection framework. Segmentation dimensions span component type, application vertical, end-user category, and distribution channel, with grade-tier purity specifications and regional regulatory cluster as industry-specific cross-cuts. CAGRs derive from slope analysis of normalized volume trajectories, incorporating semiconductor wafer fab capacity expansion schedules and municipal water treatment retrofit pipelines as primary forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sulfur feedstock price spikes, PFAS contamination detection threshold revisions, or REACH registration obligation scope expansions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Brazil Food Ingredient Market
Food Additives and Ingredients
Filling Fat Market