
 North America Food Stabilizers Market | 2026-2036
North America Food Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Stabilizers Market Analytics
Food formulation chemistry talent is collapsing across the US Midwest, constraining innovation pipelines for clean-label stabilizer development. Cargill Incorporated leverages its integrated supply chain from modified starch to finished hydrocolloid blends, sustaining R&D throughput despite labor scarcity. Tate & Lyle PLC anchors its North American position through specialty texturant expertise in bakery and dairy systems. Kerry Group competes by extending its taste and nutrition platform into customized stabilizer solutions for quick-service restaurant chains.
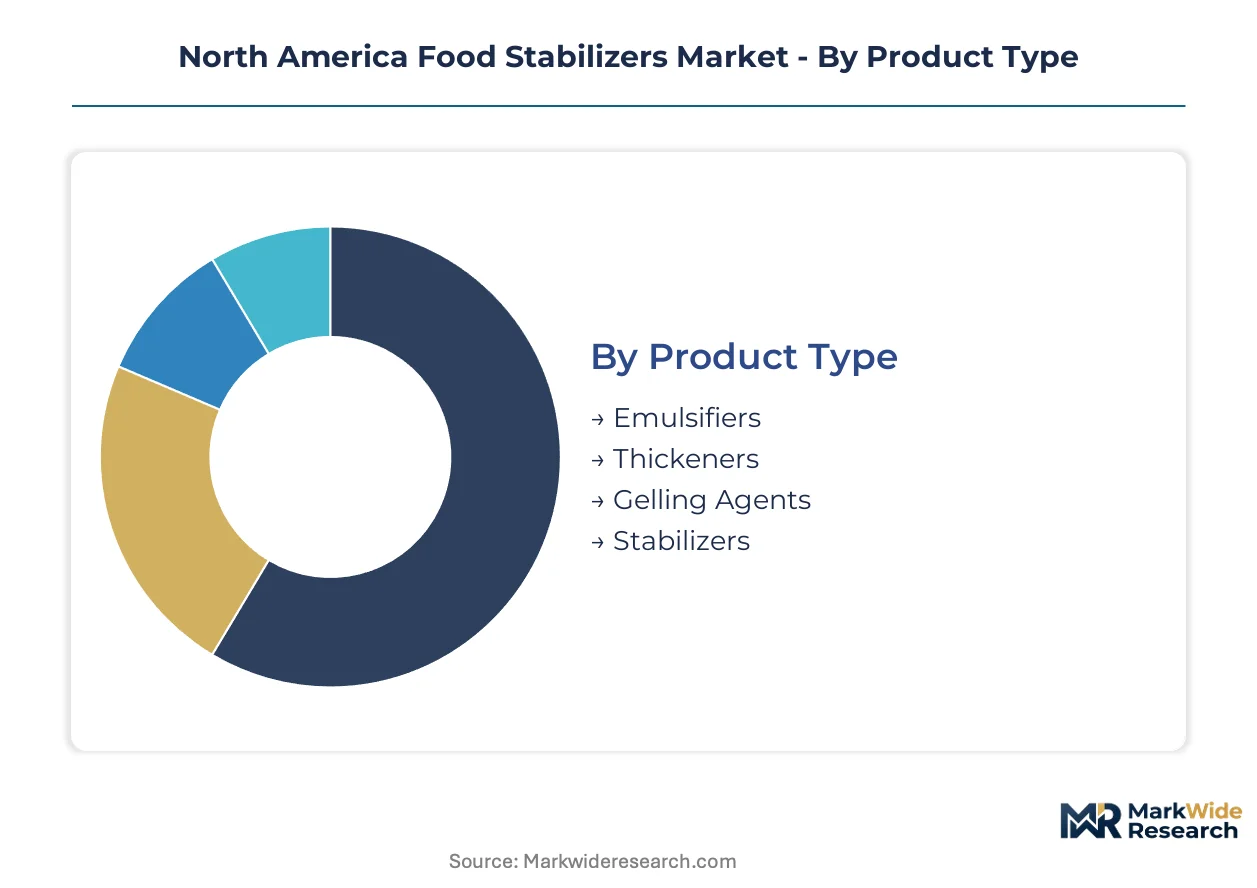
Food stabilizers comprise hydrocolloids, proteins, and modified starches that control water mobility, viscosity, and shelf stability through interfacial and gel-network mechanisms, typically functioning at concentrations below two percent by weight in finished formulations. Their primary commercial purpose is to maintain texture integrity through freeze-thaw cycles, thermal processing, and extended distribution. Thickeners occupy the largest volume position across North American food manufacturing, while gelling agents command premium positioning in plant-based dairy alternatives where calcium-reactive systems replace conventional casein networks. Emulsifiers sustain the fastest reformulation activity as bakery and confectionery producers phase out partially hydrogenated oils under FDA enforcement.
The FDA governs stabilizer safety through GRAS self-affirmation and food additive petition pathways, while the USDA sets grade standards for stabilizer-containing meat and poultry products through its Food Safety and Inspection Service. Health Canada and the Canadian Food Inspection Agency impose distinct approval requirements for novel hydrocolloids entering cross-border trade, creating dual compliance burdens for suppliers serving integrated North American accounts. Stakeholders must monitor evolving state-level clean-label legislation in California and New York, where pending disclosure mandates for processing aids could force rapid portfolio restructuring ahead of federal alignment.
Market Dynamics
The FDA's updated GRAS notification process is compressing ingredient approval timelines and forcing reformulation cycles that outpace traditional R&D cadences across Midwest dairy processing clusters.
Growth Catalysts
- Clean-label mandates:California and New York state disclosure legislation for processing aids is accelerating bakery sector reformulation toward natural hydrocolloid systems.
- Plant-based dairy expansion:Calcium-reactive gelling agents are capturing volume as oat and almond milk processors replace conventional casein networks in shelf-stable formulations.
- US Midwest processing concentration:Large-scale dairy clusters in Wisconsin and Minnesota generate procurement pull for customized stabilizer blends at industrial scale.
Market Restraints
- Modified starch input volatility:Corn and tapioca feedstock price swings destabilize cost structures for hydrocolloid blenders serving price-sensitive bakery accounts.
- Cross-border compliance friction:Health Canada and CFIA novel hydrocolloid requirements impose dual certification burdens on suppliers serving integrated US-Canada accounts.
- Partially hydrogenated oil phase-out:FDA enforcement against synthetic emulsifiers limits formulation flexibility in legacy confectionery systems.
Strategic Opportunities
- Quick-service restaurant channel:Customized stabilizer solutions for extended holding-time sauces and dressings represent underpenetrated specification growth.
- Fermentation-derived proteins:Precision fermentation texturants are opening clean-label positioning in premium plant-based dairy alternatives.
- USDA FSIS grade standard alignment:Stabilizer-containing meat and poultry product certifications offer pathway into processed protein segments.
Industry Challenges
- Food formulation chemistry scarcity:Talent collapse across the US Midwest constrains clean-label stabilizer development pipelines despite sustained demand.
- Freeze-thaw stability certification:Extended distribution testing protocols delay commercialization timelines for novel hydrocolloid systems.
- Legacy dairy equipment integration:New calcium-reactive gelling agents require retrofitting of standard pasteurization and homogenization lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Stabilizers Market |
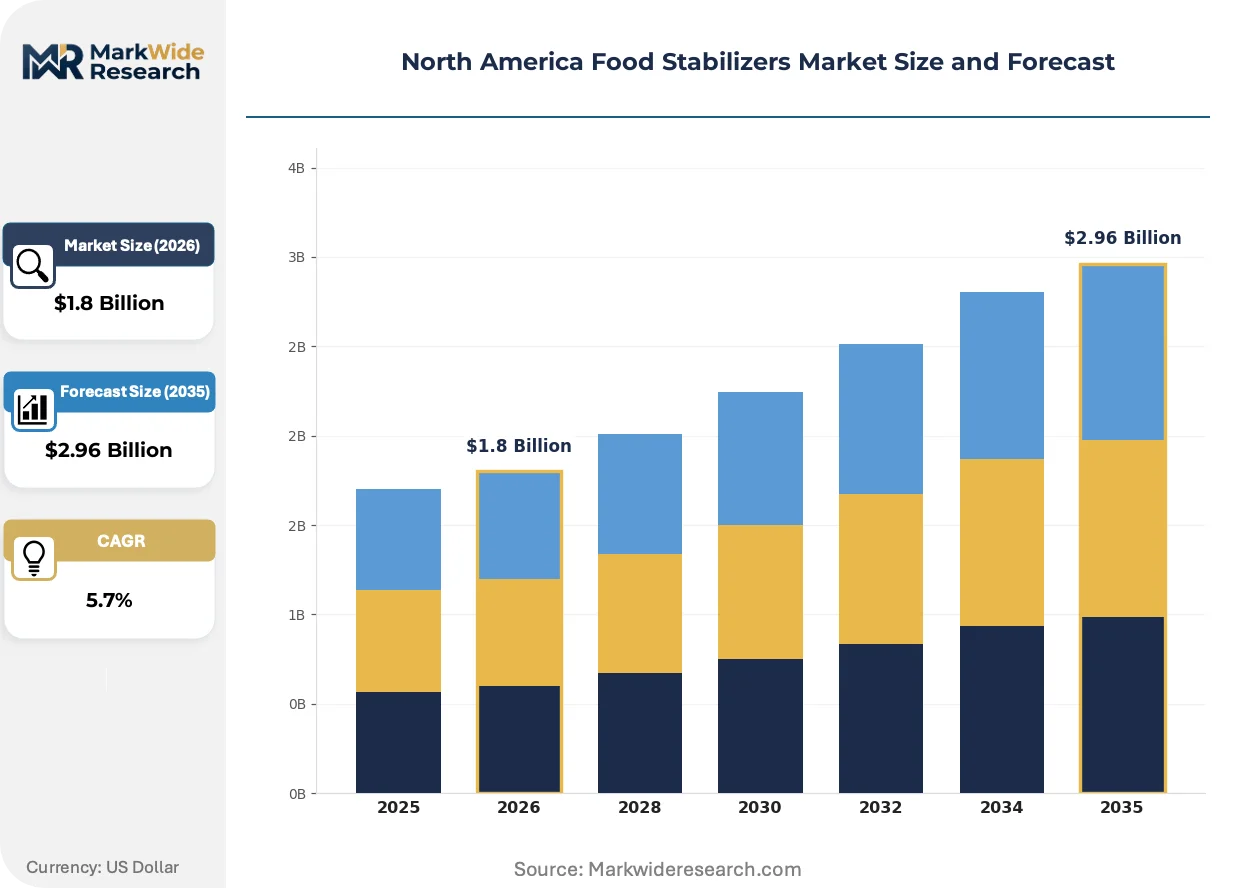
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Thickeners, Gelling Agents, Stabilizers Application: Dairy Products, Bakery Goods, Confectionery, Sauces End User: Food Manufacturers, Food Service Providers, Retailers, Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Cargill Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Ashland Inc, Kerry Group, Advanced Food Systems Inc, Nexira SAS, Palsgaard A/S, CP Kelco, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Stabilizers Market Evolving Landscape
Reformulation chemistry is pivoting toward bio-based texturants as synthetic additive exclusions reshape competitive specifications across North American food manufacturing.
Precision fermentation-derived hydrocolloids are supplanting conventional plant-extracted gums in premium plant-based dairy applications. Oat milk processors in the US Midwest and Pacific Northwest are adopting these proteins for superior calcium reactivity and mouthfeel consistency. This substitution is compressing price premiums for traditional locust bean and guar gum suppliers.
California's pending clean-label disclosure mandates for processing aids are forcing rapid portfolio restructuring ahead of federal alignment. Bakery and confectionery manufacturers are pre-emptively removing synthetic stabilizers from formulations to avoid state-level labeling complexity. The regulatory patchwork is advantaging suppliers with dual US-Canada certification capabilities.
Direct specification relationships between stabilizer blenders and quick-service restaurant chains are displacing traditional distributor-mediated procurement. Large-scale dairy processors in Wisconsin and Minnesota now negotiate customized hydrocolloid systems for extended shelf-life requirements. This channel compression is visible most acutely in the US Midwest where processing concentration enables volume-based technical collaboration.
North America Food Stabilizers Market Segmentation
Food stabilizer procurement patterns diverge sharply across product chemistry and end-use specifications, with FDA GRAS pathways and USDA FSIS grade standards creating distinct compliance burdens for each segment. Understanding these structural divisions reveals where formulation investments concentrate and where margin compression threatens supplier viability.
Product Type:
FDA enforcement against partially hydrogenated oils and Health Canada novel hydrocolloid requirements create divergent regulatory pathways for each chemistry class.
- Emulsifiers:Surface-active agents reduce interfacial tension between immiscible phases, typically functioning at 0.1-0.5% concentration. Bakery and confectionery producers in the US Midwest are accelerating reformulation away from synthetic lecithin alternatives under FDA pressure, though legacy equipment compatibility constraints slow adoption of bio-based replacements.
- Thickeners:Hydrocolloid and starch-based systems control viscosity through water-binding and network formation mechanisms. Wisconsin and Minnesota dairy processing clusters anchor regional demand for customized modified starch and xanthan gum blends serving extended shelf-life milk and yogurt applications.
- Gelling Agents:Calcium-reactive systems enabling plant-based dairy texture.
- Stabilizers:Multi-functional blends combining emulsification, thickening, and suspension properties.
Established volume favors Thickeners; emerging adoption favors Emulsifiers.
Application:
End-use specifications determine hydrocolloid selection based on thermal processing severity and freeze-thaw cycling requirements.
- Dairy Products:Milk, yogurt, and ice cream formulations requiring cold-chain stability. Oat and almond milk processors in the Pacific Northwest and US Midwest are capturing the steepest expansion trajectory for calcium-reactive gelling agents as they replace conventional casein networks in shelf-stable formulations.
- Bakery Goods:Bread, cake, and pastry systems demanding moisture retention and crumb structure control. California clean-label disclosure mandates are forcing rapid removal of synthetic stabilizers from commercial bakery portfolios ahead of potential federal alignment.
- Confectionery:Chocolate and candy applications dependent on fat crystallization control.
- Sauces:Pourable and spoonable dressings requiring emulsion stability across temperature fluctuations.
Procurement scale concentrates in Dairy Products; reformulation velocity peaks in Bakery Goods.
End User:
Customer technical capabilities determine whether stabilizer procurement flows through specification-direct relationships or distributor-mediated channels.
- Food Manufacturers:Large-scale processors with in-house formulation chemistry and direct blender relationships. National dairy cooperatives in Wisconsin negotiate customized hydrocolloid systems for extended holding-time applications, bypassing traditional ingredient distribution.
- Food Service Providers:Quick-service restaurant chains and institutional feeding operations. Chains operating across US-Canada border regions face dual certification burdens from Health Canada novel hydrocolloid requirements that complicate standardized menu deployment.
- Retailers:Private-label product development teams.
- Consumers:Direct-to-home baking and cooking ingredient purchasers.
Technical collaboration concentrates with Food Manufacturers; standardization pressure weighs on Food Service Providers.
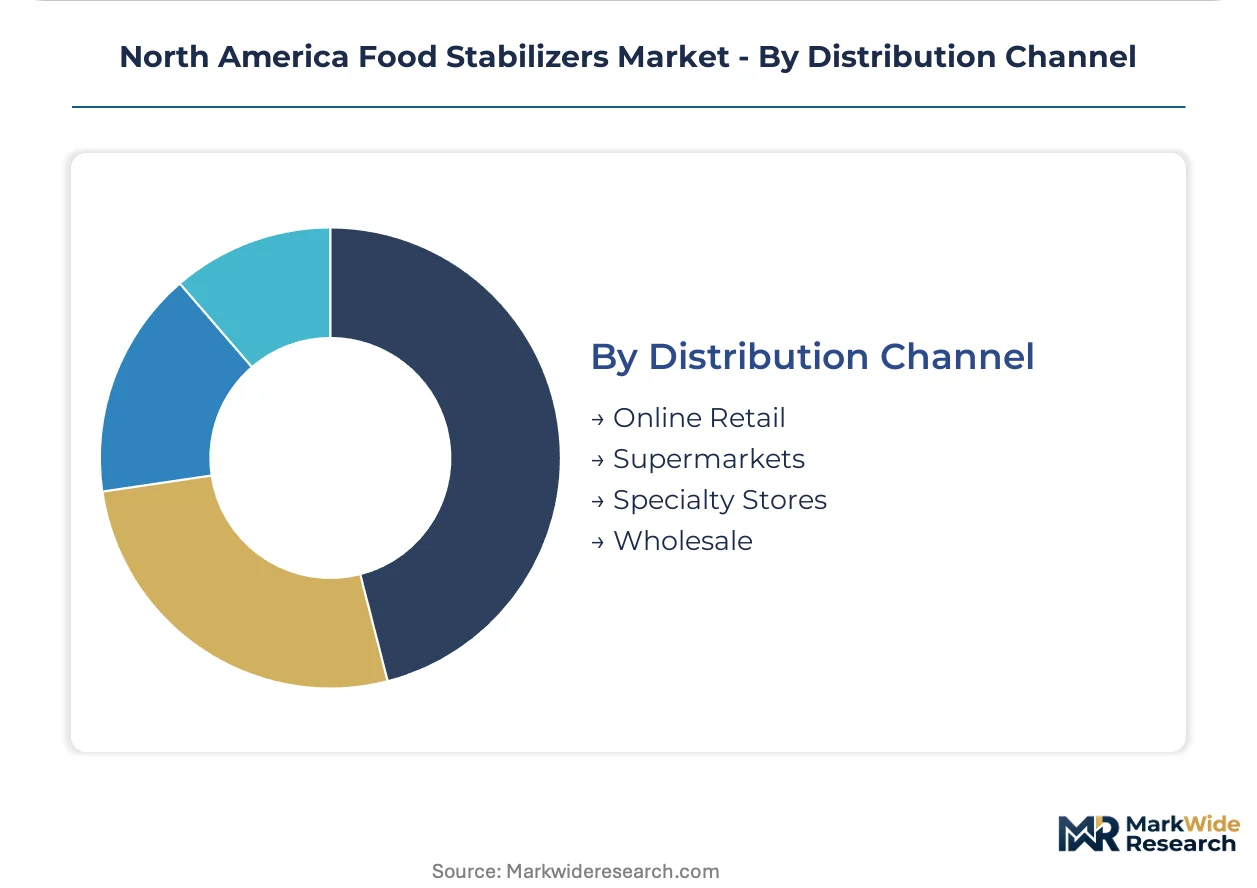
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic concentration of processing assets.
- Online Retail:E-commerce platforms serving small-batch food manufacturers and consumer segments. Specialty hydrocolloid suppliers leverage digital channels to reach craft bakery and fermentation-derived protein startups outside traditional Midwest dairy procurement clusters.
- Supermarkets:Mass-market retail for consumer-packaged stabilizer products.
- Specialty Stores:Professional ingredient suppliers serving artisan food producers.
- Wholesale:Bulk distribution to large-scale food manufacturers. Minnesota and Wisconsin dairy processors rely on wholesale channel relationships for just-in-time hydrocolloid blend delivery synchronized to pasteurization line schedules.
Volume flows through Wholesale; specification flexibility concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes food stabilizers predominantly through large-scale dairy processing, while Canada and Mexico exhibit divergent application mixes weighted toward bakery systems and cross-border ingredient trade respectively.
United States
Wisconsin and Minnesota dairy clusters anchor stabilizer procurement for extended shelf-life milk and yogurt formulations. The FDA's updated GRAS notification process compresses approval timelines for novel hydrocolloids entering interstate commerce. Pacific Northwest oat milk processors in Oregon and Washington are capturing steep expansion trajectories for calcium-reactive gelling agents replacing conventional casein networks.
Canada
Cross-border integrated accounts drive dual certification demand for hydrocolloid suppliers serving US-Canada bakery and dairy chains. Health Canada and CFIA impose distinct novel hydrocolloid requirements that complicate standardized product deployment. Ontario's food manufacturing corridor concentrates procurement for clean-label reformulation projects targeting California-aligned disclosure standards.
Mexico
Bakery sector reformulation toward natural hydrocolloid systems accelerates as exporters adapt to California and New York state disclosure mandates. The national food safety regulator enforces additive labeling requirements that diverge from US FDA frameworks. Central Mexico's industrial baking clusters generate procurement pull for emulsifier-thickener blends serving extended distribution networks.
California
Pending clean-label disclosure mandates for processing aids force rapid portfolio restructuring ahead of potential federal alignment. State-level legislation accelerates bakery sector removal of synthetic stabilizers from commercial formulations. Sacramento's regulatory proximity enables food manufacturers to anticipate compliance requirements affecting North American specification standards.
New York Metro
Quick-service restaurant chain headquarters drive customized stabilizer specifications for extended holding-time sauces and dressings. State disclosure legislation for processing aids parallels California's regulatory trajectory. The metropolitan food service manufacturing base generates technical collaboration demand with Midwest hydrocolloid blenders.
North America Food Stabilizers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale blenders occupying intermediate positions based on formulation chemistry capabilities and distribution reach. The upper tier commands specification-direct relationships with dairy cooperatives and quick-service chains, while specialists compete through customized solutions for clean-label reformulation. Three archetypes dominate: integrated agricultural processors with captive starch supply, specialty texturant houses with dairy systems expertise, and taste-nutrition platforms extending into stabilizer customization. Capacity expansion and strategic partnerships represent the dominant competitive vectors as labor scarcity constrains organic R&D growth.
Within the integrated processor tier, Cargill Incorporated exemplifies upstream control from modified starch through finished hydrocolloid blends, sustaining throughput despite Midwest formulation chemistry scarcity. Tate & Lyle PLC occupies a position representing specialty texturant expertise anchored in bakery and dairy systems. Kerry Group sits within the taste-nutrition extension archetype, competing through customized stabilizer solutions for quick-service restaurant chains. These three anchors illustrate how competitive positioning flows from supply chain configuration and technical service depth rather than product differentiation alone.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Ashland Inc |
| Kerry Group |
| Advanced Food Systems Inc |
| Nexira SAS |
| Palsgaard A/S |
| CP Kelco |
| Others |
Value Network & Pricing Analysis
FDA GRAS self-affirmation tiers gate both supplier qualification and price differentiation simultaneously, with novel hydrocolloid petition pathways commanding substantial premia over conventional GRAS-affirmed ingredients. The regulatory stratification creates parallel supply tracks where certification investment directly translates to pricing power across Midwest dairy procurement clusters.
Pricing Analysis
Long-term offtake contracts dominate procurement for large-scale dairy processors in Wisconsin and Minnesota, locking in volume commitments for modified starch and xanthan gum blends. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived precision proteins from conventional plant-extracted hydrocolloids and commodity starches. Cost compression in the economy tier is intensifying because corn and tapioca feedstock volatility destabilizes blenders serving price-sensitive bakery accounts. Food manufacturers with direct specification relationships exhibit lowest price sensitivity, while quick-service restaurant chains negotiating through distributor channels face highest cost pressure.
Supply Chain Analysis
Midwest corn belt processing concentration creates a chokepoint where modified starch supply concentrates in Iowa, Illinois, and Nebraska before downstream blending. Hydrocolloid blenders draw from tapioca starch originating in Southeast Asia, guar gum from India, and locust bean gum from Mediterranean cultivation regions. Single-source vulnerability runs through the India-Pakistan guar gum corridor where monsoon-dependent harvests create annual supply uncertainty. Distribution runs through wholesale bulk channels synchronized to pasteurization line schedules for dairy processors, with specialty hydrocolloids diverting through direct technical service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for formulation chemistry support are expanding faster than base ingredient sales, creating recurring revenue layers that stabilize margin profiles amid input volatility. This service-attach dynamic repositions stabilizer supply from commodity transaction to embedded partnership.
For Market Incumbents: Compound defensive moats through captive fermentation capacity for precision-derived texturants and exclusive quick-service restaurant specification relationships. The precision fermentation entrant archetype threatens conventional plant-extracted gum positioning, making backward integration into bio-based texturant production the critical lever for margin defense. Lock in multi-year offtake agreements with Midwest dairy cooperatives before talent scarcity constrains rival technical service capacity.
For New Entrants and Emerging Players: Differentiate on rapid clean-label certification turnaround for California and New York disclosure mandates, targeting bakery sector reformulation velocity as the most penetrable white-space. The quick-service restaurant channel offers specification-direct entry where incumbent distributor relationships have weakened. Lead with fermentation-derived protein positioning in Pacific Northwest oat milk processing clusters where calcium-reactive system demand outpaces incumbent supply.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation texturant sub-segments as equipment modularization reduces facility-scale requirements. Five-to-ten year viability favors blenders with dual US-Canada certification capabilities and embedded formulation chemistry teams. Target acquisition archetypes include Midwest-based specialty texturant houses with dairy systems expertise and established GRAS notification track records. The signal to watch is Health Canada novel hydrocolloid approval velocity as a proxy for cross-border expansion optionality.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Fermentation-derived proteins unlock clean-label positioning in premium oat milk formulations. |
| Dual Certification Investment | Simultaneous FDA GRAS and Health Canada approvals reduce friction for integrated US-Canada accounts. |
| Technical Service Team Expansion | Embedded formulation chemists offset Midwest talent scarcity and deepen customer retention. |
| Quick-Service Restaurant Direct Specification | Bypassing distributor channels captures extended holding-time sauce and dressing applications. |
| Modified Starch Backward Integration | Captive corn and tapioca processing insulates margin from agricultural commodity volatility. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS notification filings, USDA FSIS grade standard documentation, and trade flow databases. Interviews with food formulation chemists, dairy processing procurement leads, hydrocolloid blender technical directors, and quick-service restaurant supply chain managers informed demand-side validation. Secondary sources include customs records for hydrocolloid imports, SEC filings for integrated agricultural processors, and state-level clean-label legislative tracking. Bottom-up volume modeling triangulates against top-down market sizing across product chemistry and application segments.
Segmentation dimensions modeled span emulsifier-thickener-gelling agent-stabilizer chemistry classes, dairy-bakery-confectionery-sauce applications, and food manufacturer-food service-retailer end-user channels. Volume projections incorporate industrial processing capacity expansion in Wisconsin and Minnesota, oat milk processor adoption curves for calcium-reactive systems, and regulatory enforcement timelines for partially hydrogenated oil phase-outs. CAGRs derive from regression analysis of historical procurement patterns and elasticity estimates for clean-label premium absorption.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement commitment or accelerated Health Canada novel hydrocolloid harmonization would require recalibration. Forecasts embed assumptions regarding Midwest dairy processing concentration stability and Pacific Northwest plant-based dairy expansion trajectories. Practitioners should keep alternative scenarios live as California and New York disclosure mandate implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Asia-Pacific Food Enzymes Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
France Feed Additives Market
Food Additives and Ingredients
India Food Color Industry Market