
 Russia Food Preservatives Market | 2026-2036
Russia Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Food Preservatives Market Analytics
Modular preservative blends is shifting buyer choice across Russia's food manufacturing base. Cargill Russia leverages its local formulation expertise to supply customized antioxidant systems for meat processors. BASF SE anchors the synthetic preservative segment with established sorbate and benzoate production networks. Chr. Hansen Holding A/S differentiates through its bioprotective culture portfolios targeting dairy applications.
Food preservatives comprise antimicrobial agents, antioxidants, and chelating compounds that inhibit microbial spoilage and oxidative rancidity in packaged foods, typically dosed at 0.01–0.3% by weight depending on substrate pH and water activity. Their primary commercial purpose is extending shelf stability while maintaining sensory and nutritional integrity across distribution chains. Antimicrobial agents dominate value contribution in meat and dairy applications where pathogen control carries the highest failure cost. Natural preservatives represent the fastest-expanding product type as Russian retailers impose clean-label requirements on supplier portfolios. Chemical preservatives retain volume leadership in beverage and bakery segments where cost thresholds remain restrictive.
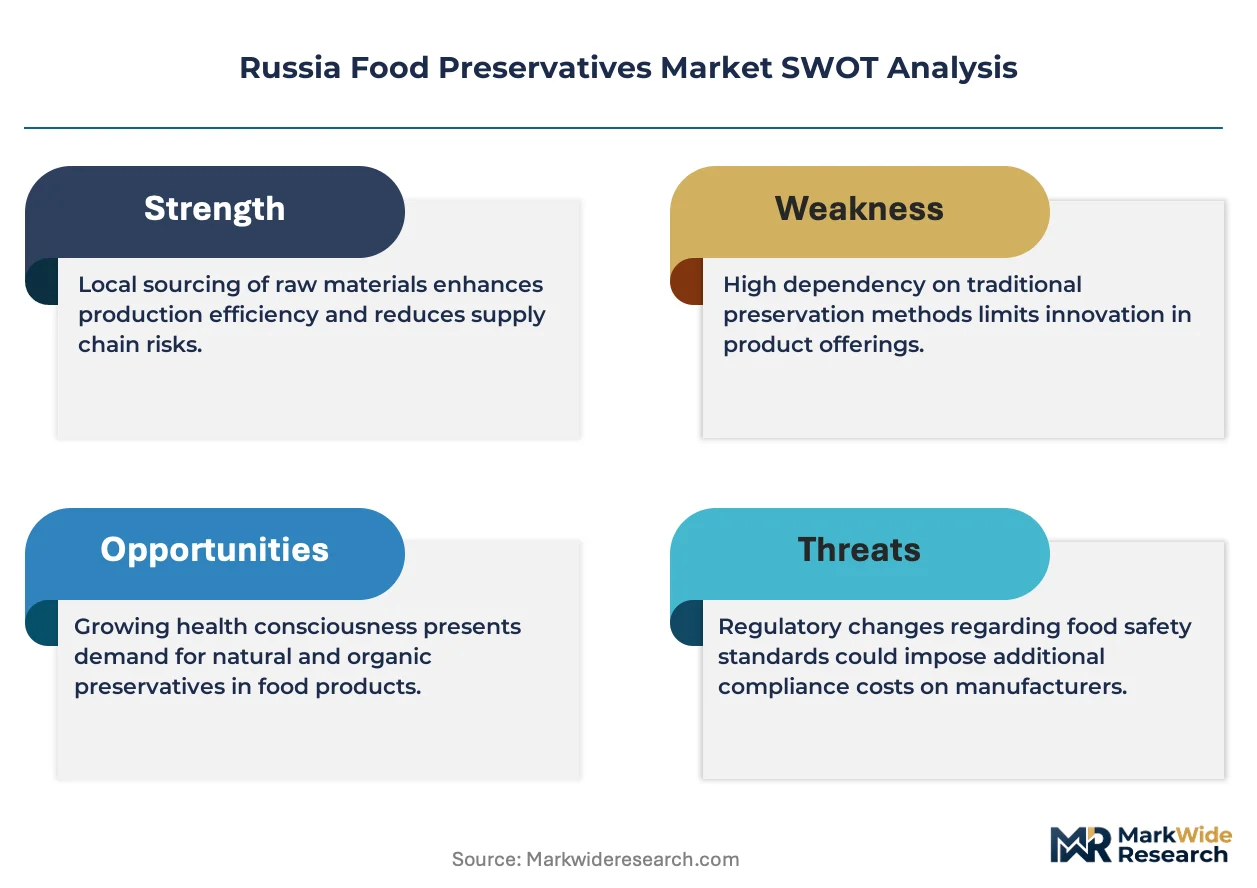
Russia's Federal Service for Surveillance on Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces TR TS 021/2011 and TR TS 029/2012, which govern preservative maximum limits and labeling transparency across the EAEU customs territory. The country's national standardization body (GOST R) maintains additive purity specifications that exceed baseline Codex Alimentarius thresholds for several antioxidant classes. Stakeholders must monitor pending amendments to Russia's organic food law and evolving retailer private-label standards that restrict synthetic additive use in premium-positioned product lines.
Market Dynamics
Russia's food preservatives sector is compressing around TR TS 021/2011 disclosure mandates and retailer clean-label procurement policies that now disqualify synthetic additive portfolios from premium private-label contracts.
Growth Catalysts
- Processed meat sector expansion:Large-scale meat processors in the Central Federal District are retrofitting production lines to accommodate antioxidant systems that extend shelf life without synthetic label declarations.
- TR TS 029/2012 additive harmonization:EAEU-wide standardization of maximum permitted limits is eliminating interstate regulatory friction for preservatives crossing Russian-Belarusian-Kazakhstani borders.
- Moscow retail consolidation:X5 Retail Group and Magnit are imposing unified supplier qualification protocols that accelerate clean-label preservative adoption across their combined national footprint.
Market Restraints
- Feedstock cost volatility:Sorbic acid and benzoic acid precursor chemicals face price instability tied to petrochemical feedstock fluctuations, compressing formulation margins for domestic blenders.
- Import dependency in natural extracts:Rosemary extract and green tea catechin supply concentrates in Chinese and Indian extraction facilities, exposing Russian formulators to currency and logistics risk.
- Technical limitation in beverage applications:Natural antimicrobial alternatives demonstrate insufficient efficacy below pH 3.5 in carbonated soft drinks, preserving synthetic dominance in this segment.
Strategic Opportunities
- Siberian and Far Eastern underpenetration:Food manufacturing clusters in Novosibirsk and Vladivostok operate with lower clean-label compliance rates than Central Russia, creating first-mover positioning for natural preservative suppliers.
- Bioprotective culture convergence:Combining bacteriocin-producing cultures with modified atmosphere packaging is opening dairy applications previously reserved for chemical preservatives.
- Organic food law amendments:Pending revisions to Russia's organic certification framework will mandate additive-free or naturally preserved status for premium tier products, generating regulatory tailwind for clean-label portfolios.
Industry Challenges
- Formulation chemist scarcity:Russian technical universities produce insufficient graduates trained in natural preservative synergy optimization, forcing manufacturers to recruit from biotechnology rather than food chemistry pipelines.
- GOST R certification timelines:Novel natural preservative approvals require 18-24 month evaluation periods against evolving purity specifications, delaying product launches relative to EAEU competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Food Preservatives Market |
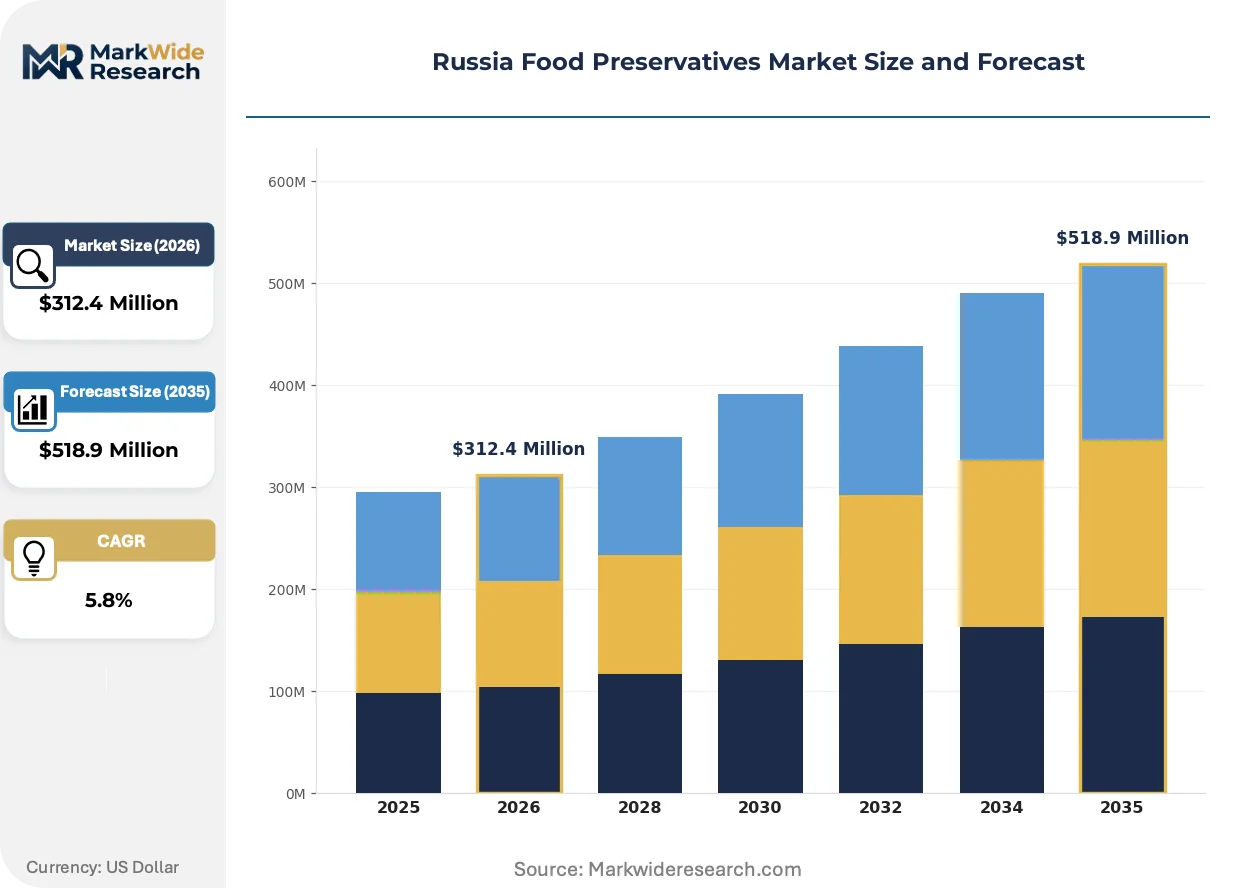
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial Agents, Antioxidants, Natural Preservatives, Chemical Preservatives Application: Meat Products, Dairy Products, Bakery Products, Beverages End User: Food Manufacturers, Retail Chains, Restaurants, Home Consumers Packaging Type: Aseptic Packaging, Glass Bottles, Plastic Containers, Metal Cans |
| Companies Covered | Biesterfeld AG, BASF SE, Corbion N.V., Cargill Russia, Jungbunzlauer AG, Kerry Group, Chr. Hansen Holding A/S, Kemin Industries Russia, Koninklijke DSM N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Food Preservatives Market Evolving Landscape
Clean-label reformulation is rewriting technical specifications across Russia's processed food base, with antimicrobial efficacy testing and consumer perception research now preceding rather than following product development cycles.
Encapsulated essential oil systems is rewriting how plant-derived antimicrobials deploy in high-moisture applications. Meat processors in the Moscow region are piloting microencapsulated thyme and oregano oil blends at commercial scale. This technology is rewriting shelf-life extension economics by enabling natural preservatives to match synthetic cost-per-unit-protection in emulsified products.
Rospotrebnadzor is intensifying TR TS 021/2011 enforcement through unannounced facility audits and expanded additive residue testing protocols. Medium-sized dairy cooperatives face disproportionate compliance costs relative to integrated multinationals. The Volga Federal District is responding fastest, with regional industry associations organizing pooled testing laboratories to distribute analytical expenses.
Retail buyer concentration is compressing supplier negotiation leverage. National retail chains now mandate quarterly preservative portfolio reviews and reserve contract termination rights for synthetic additive discoveries in nominally clean-label products. This behavioral shift is most visible in bakery and confectionery procurement, where private-label specifications now exceed baseline regulatory requirements by 30-40% on permitted additive categories.
Russia Food Preservatives Market Segmentation
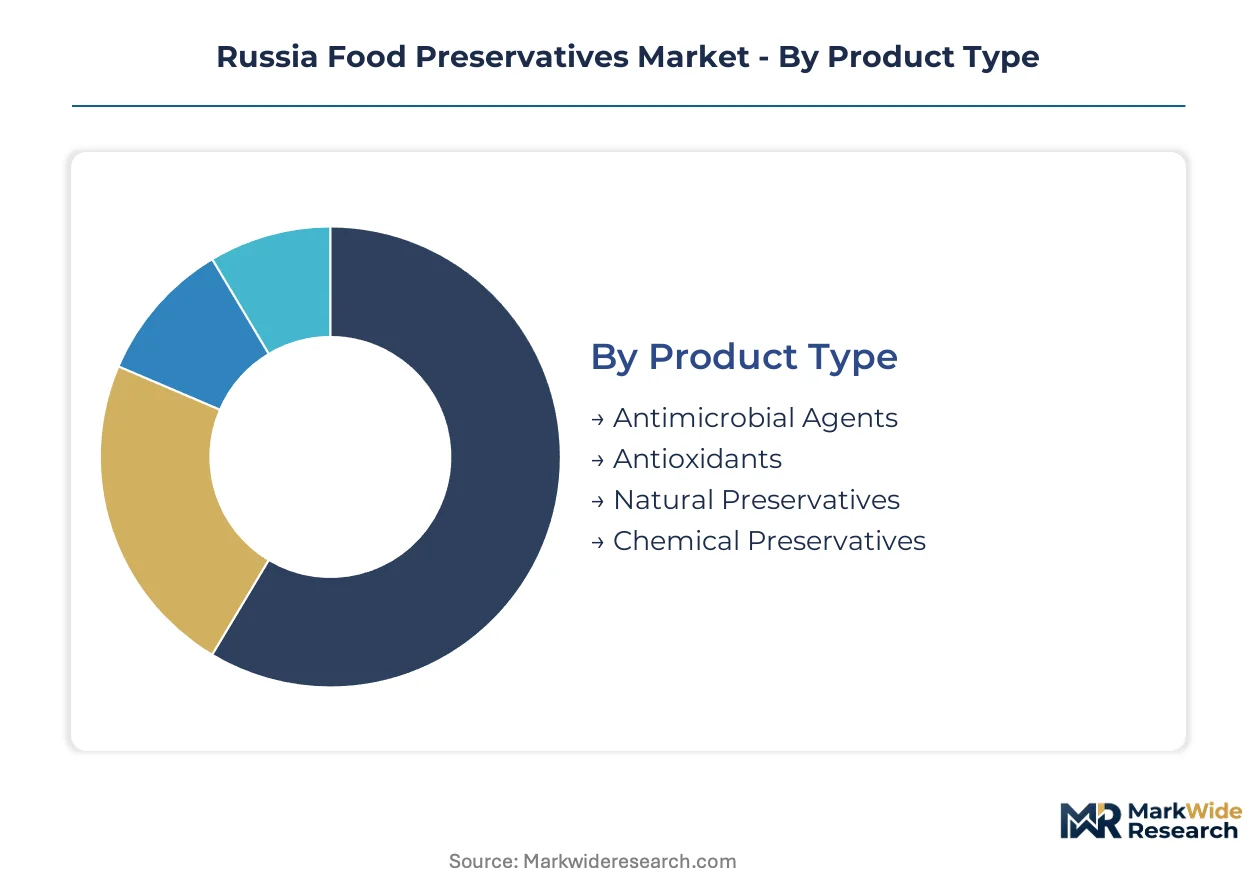
Preservative selection in Russia's food sector tracks tightly with substrate chemistry, distribution temperature requirements, and retailer label specifications. Manufacturers configure additive portfolios differently across meat, dairy, and beverage matrices where pH, water activity, and fat content dictate antimicrobial efficacy thresholds.
Product Type:
Functional chemistry determines procurement decisions, with synthetic and natural systems competing on cost-per-unit-protection and clean-label compliance.
- Antimicrobial Agents:Sorbates, benzoates, and propionates inhibit yeast, mold, and bacterial proliferation in high-moisture foods. Central Federal District meat processors deploy these in emulsified sausages where Listeria control carries regulatory and liability exposure.
- Antioxidants:BHA, BHT, and tocopherol variants scavenge free radicals to prevent lipid oxidation in rendered fats and oily seeds. Demand concentrates in Volga Federal District oilseed processing where extended bulk storage creates rancidity risk.
- Natural Preservatives:Rosemary extract, green tea catechins, and cultured dextrose deliver label-friendly shelf-life extension.
- Chemical Preservatives:Synthetic benzoic and sorbic acid derivatives retain cost advantage in carbonated beverages and acidic sauces.
Mature deployment sits with Antimicrobial Agents. Newer deployment is concentrated in Natural Preservatives.
Application:
End-use substrate properties—pH, fat content, moisture, and thermal processing—determine preservative formulation specifications and dosage rates.
- Meat Products:Cured, emulsified, and fresh meat categories require pathogen inhibition and color stabilization. Moscow-region processors are retrofitting lines for nitrite-free curing systems using celery powder and cultured starter cultures.
- Dairy Products:Yogurt, cheese, and fermented milk applications prioritize mold inhibition and post-acidification control. Siberian cooperatives are adopting bioprotective cultures to replace potassium sorbate in premium-positioned kefir lines.
- Bakery Products:Mold inhibition in extended-shelf-life bread drives propionate and cultured wheat flour demand.
- Beverages:pH-dependent preservative selection favors benzoates in carbonated soft drinks and sorbates in fruit juices.
Volume concentration favors Meat Products. Margin expansion is strongest in Dairy Products.
End User:
Procurement scale and technical capability divide the customer base, with integrated manufacturers driving formulation innovation and retail chains enforcing specification compliance.
- Food Manufacturers:Large-scale processors in the Central Federal District specify custom antioxidant blends and audit supplier manufacturing practices quarterly.
- Retail Chains:X5 Retail Group and Magnit impose unified clean-label standards across private-label suppliers, disqualifying synthetic preservatives from premium tiers.
- Restaurants:Foodservice operators prioritize cost-stable synthetic options for prepared sauces and dressings.
- Home Consumers:Direct retail purchases of preservative ingredients remain minimal, concentrated in artisanal and home-preservation niches.
Specification authority rests with Food Manufacturers. Compliance pressure originates from Retail Chains.
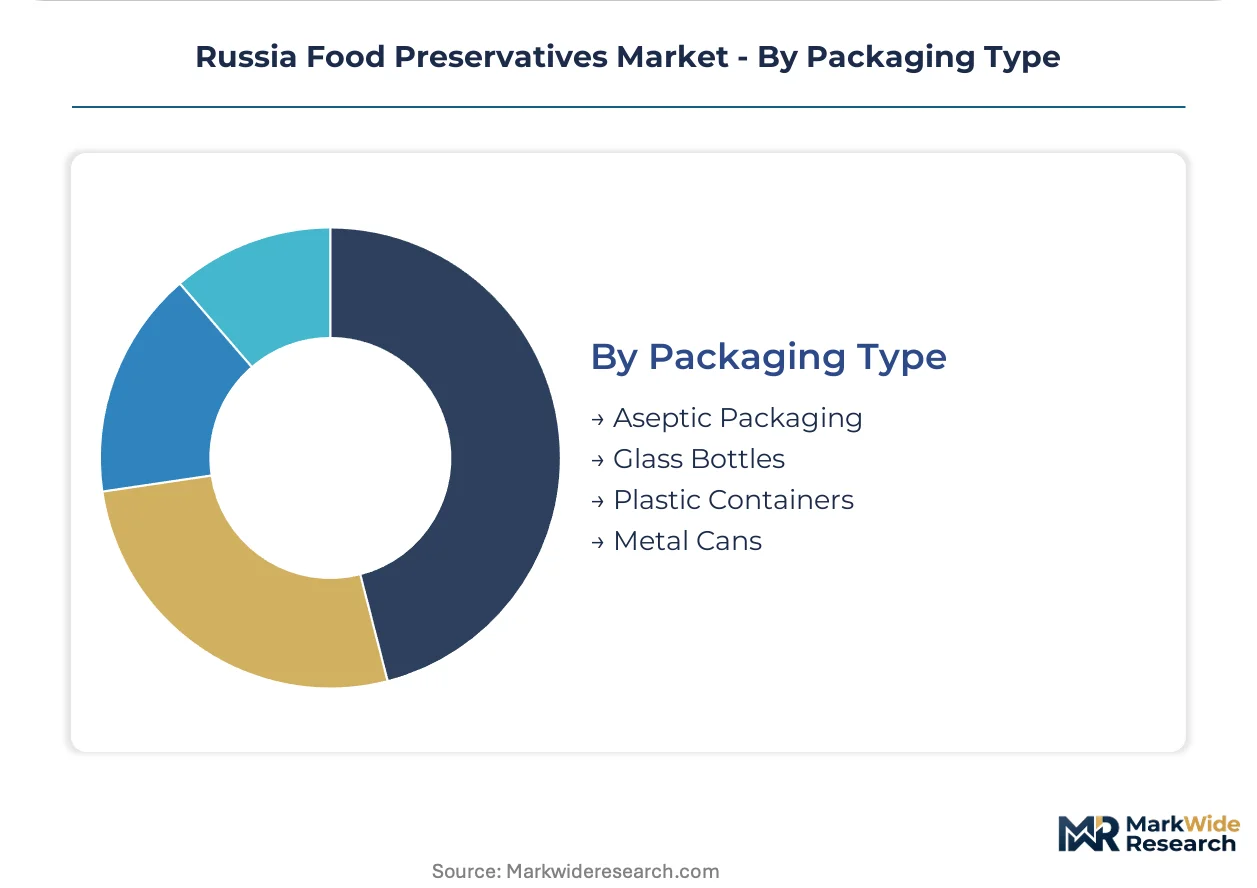
Packaging Type:
Barrier properties and headspace atmosphere interact with preservative selection to determine shelf-life outcomes.
- Aseptic Packaging:Ultra-high-temperature processing with sterile filling reduces preservative dependency in liquid dairy and juices. Novosibirsk beverage plants are expanding aseptic carton lines to eliminate chemical preservatives from extended-shelf-life milk.
- Glass Bottles:Inert, impermeable, and UV-blocking properties suit premium sauces and oils where oxidation sensitivity demands antioxidant protection.
- Plastic Containers:Oxygen permeability in PET and HDPE creates scavenger and antioxidant demand for mayonnaise and dressings.
- Metal Cans:Anaerobic interior with potential metal-catalyzed oxidation drives EDTA chelator and antioxidant use in canned fish and vegetables.
Preservative reduction is most advanced in Aseptic Packaging. Conventional chemical dependence persists in Metal Cans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's preservative production concentrates in the Central Federal District while consumption spreads unevenly across federal districts with varying clean-label maturity.
Central Federal District
Moscow anchors procurement volume for antioxidant and antimicrobial systems. Rospotrebnadzor maintains its headquarters here, accelerating TR TS 021/2011 enforcement timelines for processors in the capital region. Food manufacturers in the Moscow Oblast are retrofitting emulsified meat lines for nitrite-free curing systems.
Volga Federal District
Oilseed processors in Samara and Saratov drive antioxidant demand for bulk fat stabilization. GOST R maintains regional testing laboratories in Kazan that evaluate additive purity against Codex-exceeding thresholds. Dairy cooperatives in Tatarstan are pooling analytical expenses to manage compliance cost burdens.
Siberian Federal District
Novosibirsk food manufacturing clusters operate with lower clean-label compliance rates than Central Russia, creating positioning opportunities for natural preservative suppliers. The regional industry association lags in pooled testing infrastructure compared to Volga counterparts. Meat processors here still rely predominantly on synthetic antimicrobial portfolios.
Far Eastern Federal District
Vladivostok seafood canning operations require chelator and antioxidant systems for metal-catalyzed oxidation control. Import logistics from Chinese extraction facilities for rosemary extract and green tea catechins face currency exposure at this distance from Moscow. Regional beverage plants show minimal natural preservative adoption due to pH-efficacy limitations.
Northwestern Federal District
St. Petersburg's retail consolidation mirrors Moscow's procurement standards, with national chains imposing unified clean-label specifications across their Northwestern footprint. Local dairy processors are piloting bioprotective cultures in fermented milk applications. The district's proximity to European supply chains offers alternative sourcing routes for natural extract imports.
Russia Food Preservatives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Russia's preservative supply base. The market structure tilts toward consolidated multinational presence in synthetic chemistry alongside fragmented domestic blending operations. Three archetypes dominate: global chemical majors with EAEU production networks, regional formulation specialists with customization capabilities, and biotechnology-derived natural solution providers. Capacity expansion and portfolio diversification toward clean-label alternatives constitute the primary competitive vectors.
Among the global chemical majors, BASF SE anchors synthetic preservative supply through established sorbate and benzoate production networks. Cargill Russia occupies a position within the formulation specialist tier, leveraging local expertise for customized antioxidant systems. Chr. Hansen Holding A/S exemplifies the biotechnology-derived archetype, differentiating through bioprotective culture portfolios. These three represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Biesterfeld AG |
| BASF SE |
| Corbion N.V. |
| Cargill Russia |
| Jungbunzlauer AG |
| Kerry Group |
| Chr. Hansen Holding A/S |
| Kemin Industries Russia |
| Koninklijke DSM N.V. |
| Others |
Value Network & Pricing Analysis
Large-scale food manufacturers in the Central Federal District command volume-based contract structures that compress supplier margins while rewarding backward integration into raw material sourcing. Rospotrebnadzor's escalating TR TS 021/2011 enforcement timelines amplify compliance costs, embedding certification premiums into delivered prices.
Pricing Analysis
Margin tightening in synthetic preservative tiers reflects feedstock volatility in petrochemical-derived sorbic acid and benzoic acid precursors. Three-tier pricing structure across premium natural, standard chemical, and economy synthetic levels tracks certification grade and clean-label compliance status. Price differentiation hinges on GOST R purity specifications and volume scale commitments. Food manufacturers exhibit highest price sensitivity in beverage applications where synthetic alternatives retain cost advantage, while dairy processors show lowest sensitivity for bioprotective cultures in premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian extraction facilities supplying rosemary extract and green tea catechins to Russian formulators. Raw material flows draw from German synthetic chemical producers, Chinese botanical extractors, and domestic petrochemical feedstock processors. Supply chain risk concentrates in currency exposure and logistics friction at Far Eastern ports. Distribution runs through Moscow-based blending facilities serving Central Federal District meat and dairy clusters, with secondary nodes in Kazan and Novosibirsk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's food preservatives market functions as a cost-of-compliance arena where TR TS 021/2011 disclosure mandates erect regulatory moats favoring players with established GOST R certification infrastructure and Rospotrebnadzor audit readiness.
For Market Incumbents: Anticipate margin compression from feedstock volatility by securing captive supply of sorbic acid precursors through backward integration into petrochemical partnerships. Defend position against bioprotective culture displacement by accelerating encapsulated essential oil R&D for high-moisture meat applications. Prioritize certification investment in pending organic food law compliance to lock in premium tier access. For New Entrants and Emerging Players: E-commerce ingredient platforms offer direct channel access to Siberian and Far Eastern meat processors bypassing Moscow distributor markups. Target Novosibirsk manufacturing clusters where clean-label penetration lags Central Russia by several years. Lead with natural antimicrobial blends priced against synthetic benchmarks to accelerate adoption curves. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional formulation specialists with GOST R-approved facilities in the Volga Federal District where pooled testing infrastructure spreads compliance costs. Long-term viability rests on positioning for organic certification mandates and retailer private-label qualification. Watch X5 Retail Group and Magnit supplier list rotations as inflection signals for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive sourcing of petrochemical precursors insulates margin structures from import price volatility. |
| Encapsulated Essential Oil Scale-Up | Microencapsulated thyme and oregano systems match synthetic cost-per-unit-protection in emulsified meat. |
| Bioprotective Culture Portfolio Expansion | Bacteriocin-producing cultures open dairy applications previously reserved for potassium sorbate. |
| GOST R Certification Fast-Track | Accelerated approval timelines for novel natural preservatives compress competitive launch windows. |
| Siberian Distribution Partnership | Novosibirsk and Vladivostok channel control captures underpenetrated clean-label demand. |
Research Methodology
Multi-period observation of Rospotrebnadzor enforcement patterns, retailer procurement specifications, and manufacturer formulation shifts anchored the trend analysis, supplemented by interviews with plant managers at Central Federal District meat processors, procurement leads at X5 Retail Group and Magnit, technical R&D directors at antioxidant blend suppliers, and distribution channel partners in Kazan and Novosibirsk. Secondary validation drew from EAEU customs data, GOST R additive purity specifications, Rospotrebnadzor public enforcement disclosures, and trade association reports from the Russian Union of Food Ingredients Producers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrices modeled preservative demand across product type, application substrate, end-user procurement scale, and packaging barrier properties throughout the forecast period. CAGRs derived from regression analysis against food manufacturing output indices and clean-label adoption curves. Industry-specific forecast inputs incorporated TR TS 029/2012 harmonization timelines and pending organic food law amendment trajectories.
The model holds under stable EAEU regulatory harmonization and continued retailer consolidation; deviation in Rospotrebnadzor enforcement intensity or feedstock price spikes would shift volume trajectories. Forecasts reflect documented assumptions about clean-label penetration rates and natural preservative efficacy advancement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market