
 Trans Fatty Acids Market | 2026-2036
Trans Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Trans Fatty Acids Market Analytics
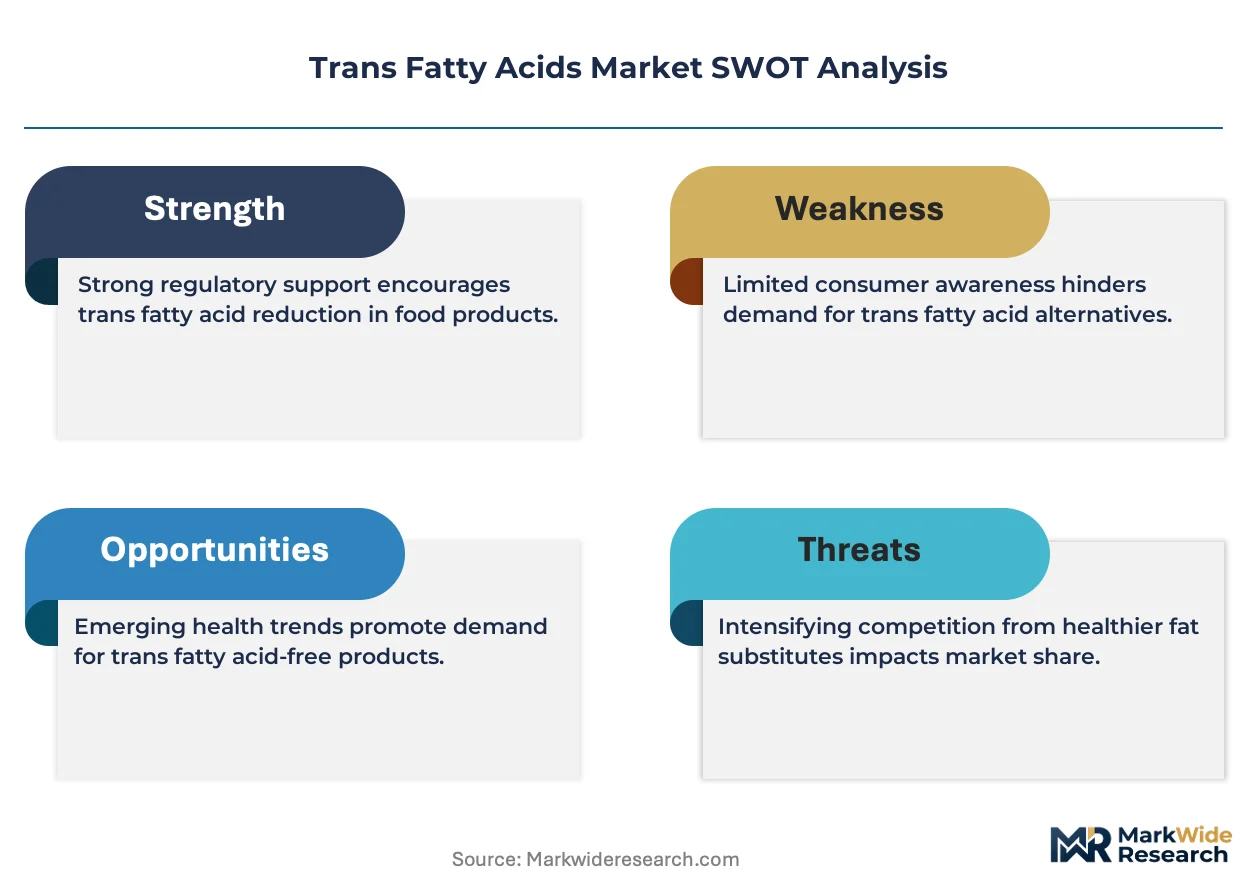
Multi-source procurement of palm and soybean feedstocks is expanding as manufacturers hedge against price volatility and origin-specific regulatory risk. Cargill leverages its global oilseed processing footprint to sustain supply continuity across multiple geographies. BASF SE anchors specialty lipid modification capabilities that differentiate its technical service model. Wilmar International Limited dominates Southeast Asian origination and refining infrastructure, controlling cost positions that smaller competitors struggle to match.
Trans fatty acids comprise unsaturated fatty acids with at least one carbon-carbon double bond in the trans configuration, typically formed through partial hydrogenation of vegetable oils that raises melting points and extends oxidative stability for frying and baking applications. Industrial trans fats and partially hydrogenated oils retain structural importance in emerging-market processed food manufacturing where cost constraints limit premium fat alternatives, while fully hydrogenated oils represent the fastest-growing product category as zero-trans-label compliance tightens across regulatory jurisdictions. Baked goods and margarine applications concentrate the largest volume pools, though snacks and spreads segments attract reformulation investment as clean-label priorities intensify among food manufacturers and food service providers.
WHO REPLACE guidelines, FDA final determination on partially hydrogenated oils, and EFSA intake benchmarks collectively reshape permissible trans fat thresholds and analytical verification requirements for cross-border food trade. India's FSSAI and Indonesia's BPOM enforce progressively stricter labeling and content limits, compelling regional reformulation or import substitution. Stakeholders must monitor divergence between Codex-aligned tolerance standards and national zero-trans ambitions that could fragment compliance architectures and sourcing strategies.
Market Dynamics
WHO REPLACE guidelines and FDA's final determination on partially hydrogenated oils are forcing systematic reformulation across industrial food manufacturing, compressing demand for legacy trans fat feedstocks while accelerating fully hydrogenated oil adoption.
Growth Catalysts
- Clean-label bakery reformulation:Southeast Asian processors are substituting partially hydrogenated oils with fully hydrogenated alternatives to meet export market zero-trans thresholds.
- FSSAI labeling mandates:India's tightened disclosure rules compel domestic manufacturers to source certified low-trans feedstocks, stimulating analytical verification service demand.
- Palm oil fractionation advances:Enzymatic interesterification technologies enable cost-competitive structuring fats without hydrogenation, penetrating margarine applications.
Market Restraints
- Feedstock price volatility:Crude palm oil futures fluctuate with Malaysian ringgit weakness and Indonesian export levy adjustments, compressing blender margins.
- Refining infrastructure concentration:Wilmar International and Cargill control over 60% of Southeast Asian hydrogenation capacity, limiting new entrant supply security.
- Technical reformulation barriers:Fully hydrogenated oils require higher melting point management in tropical climates, demanding modified processing lines.
Strategic Opportunities
- Indian contract manufacturing expansion:FSSAI-compliant toll processors can capture reformulation demand from mid-tier domestic brands lacking in-house lipid modification expertise.
- Specialty fats for plant-based meat:Trans-free hardstock applications in alternative protein texturization represent an underdeveloped end-use vertical.
- EFSA-aligned certification services:Third-party laboratories verifying sub-2% trans fat content can differentiate across EU-bound export supply chains.
Industry Challenges
- Reformulation capex burden:Retrofitting hydrogenation lines for full hydrogenation or interesterification demands $2-5 million per facility, straining regional processors.
- Analytical capability gaps:Gas chromatography infrastructure for trans fat quantification remains scarce in secondary Indian and Indonesian cities, delaying compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trans Fatty Acids Market |
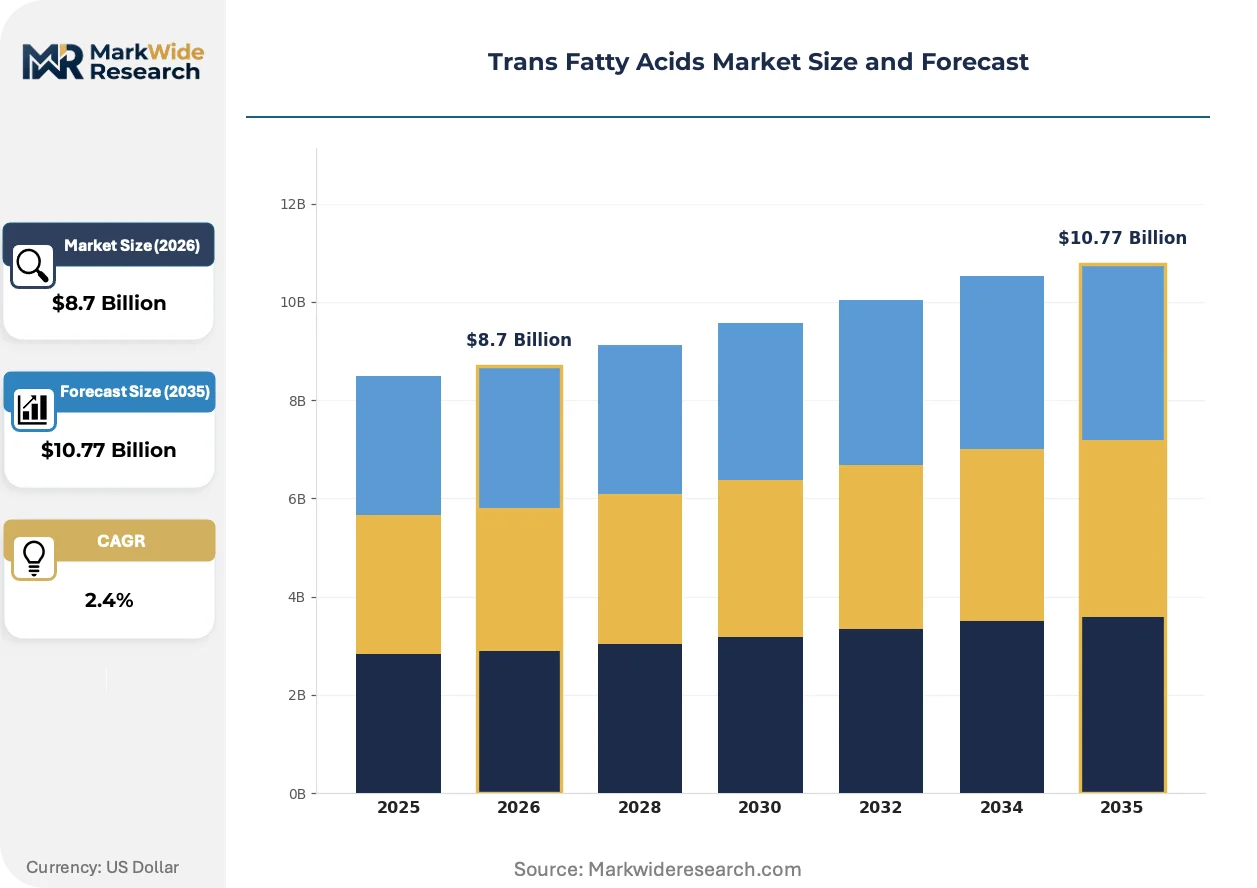
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Trans Fats, Industrial Trans Fats, Partially Hydrogenated Oils, Fully Hydrogenated Oils Application: Baked Goods, Snacks, Margarine, Spreads End User: Food Manufacturers, Restaurants, Retail Consumers, Food Service Providers Form: Liquid, Solid, Semi-solid, Powdered |
| Companies Covered | Unilever, Archer Daniels Midland Company, Cargill, Wilmar International Limited, BASF SE, Kraton Corporation, Royal DSM, Emery Oleochemicals, KLK Oleo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trans Fatty Acids Market Evolving Landscape
Enzymatic processing and precision blending technologies are displacing conventional chemical hydrogenation, enabling trans-free fat structuring without compromising oxidative stability or functional performance in high-temperature applications.
Interesterification technology is integrating enzymatic catalysts with palm mid-fraction blending to replicate the crystallization behavior of partially hydrogenated oils. Bakery manufacturers in Malaysia and Indonesia are adopting these systems at pilot scale ahead of anticipated BPOM content limits. The structural consequence is compressing demand for legacy hydrogenation equipment while expanding specialty lipid modification service contracts.
EFSA intake benchmarks and Codex Alimentarius draft revisions are tightening analytical tolerance definitions for "trans-free" claims. Food exporters to EU member states must now demonstrate sub-2% trans fat content through accredited laboratory verification. Margarine and shortening producers are responding by segregating supply chains for EU-bound versus domestic-market production.
Ingredient procurement from regional refiners is displacing long-haul soybean oil imports as manufacturers prioritize supply chain proximity over cost minimization. Indian biscuit and fried snack producers are consolidating purchases through domestic palm olein distributors with FSSAI-certified storage infrastructure. This pattern is most visible in Maharashtra and Gujarat, where port-adjacent blending facilities are capturing volume from traditional trading houses.
Trans Fatty Acids Market Segmentation
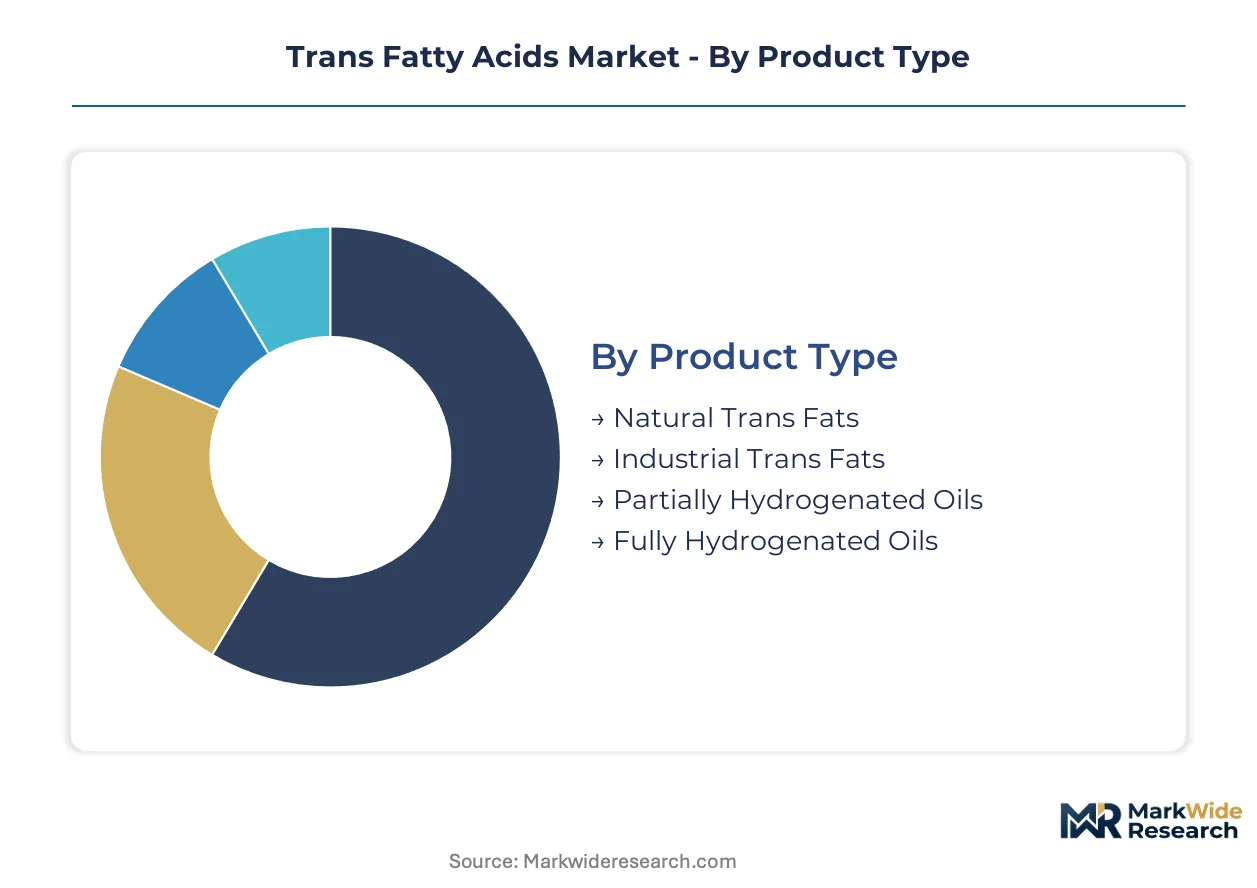
Trans fatty acid procurement patterns diverge sharply across product categories, with regulatory thresholds and reformulation costs driving distinct sourcing behaviors. Buyers prioritize functional performance in tropical climates, zero-trans compliance for export markets, or cost minimization for domestic consumption.
Product Type:
Price sensitivity and technical capability separate buyers in this category, with premium processors absorbing higher input costs for compliance while commodity buyers optimize for margin.
- Industrial Trans Fats:Partially hydrogenated oils with 10-40% trans content deliver crystallization stability for Southeast Asian bakery operations. Indian biscuit manufacturers in Gujarat and Maharashtra continue sourcing these feedstocks for domestic-market production despite FSSAI disclosure mandates tightening.
- Fully Hydrogenated Oils:Zero-trans hardstocks with complete saturation provide structural functionality without trans fat labeling triggers. Malaysian exporters to EU markets are converting hydrogenation lines to full hydrogenation to meet EFSA sub-2% verification requirements.
- Natural Trans Fats:Ruminant-derived trans fats occurring in dairy and meat products fall outside industrial hydrogenation regulations. Clean-label positioning in premium European retail channels sustains niche demand.
- Partially Hydrogenated Oils:Legacy feedstocks with intermediate iodine values face phased elimination under WHO REPLACE guidelines. Indonesian BPOM labeling rules are compressing remaining commercial applications.
Industrial trans fats anchor volume today; fully hydrogenated oils are gaining share fastest.
Application:
Functional requirements around melting point, oxidative stability, and mouthfeel determine formulation choices across these end-uses.
- Baked Goods:Cookies, crackers, and laminated pastries require plastic fat ranges for dough handling and shelf life. Indian contract manufacturers serving mid-tier brands are investing in enzymatic interesterification to replace partially hydrogenated shortenings.
- Margarine:Water-in-oil emulsions demand precise solid fat content across temperature gradients. Malaysian producers blend palm mid-fractions with fully hydrogenated oils to replicate legacy crystallization behavior.
- Snacks:Deep-frying applications prioritize oxidative stability and smoke point over structural properties. Southeast Asian potato chip processors are testing high-oleic palm olein as trans-free alternatives.
- Spreads:Tub and stick formats require distinct solid fat profiles for spreadability and stand-up stability. European retailers are delisting spread products exceeding EFSA intake benchmarks.
Baked goods command the largest volume commitment; margarine applications are climbing the fastest as reformulation investment concentrates.
End User:
Scale and regulatory exposure shape procurement sophistication, with large manufacturers deploying technical resources smaller buyers cannot replicate.
- Food Manufacturers:Industrial-scale processors with in-house lipid modification capabilities manage reformulation internally. Cargill and Wilmar International count these buyers for multi-year supply contracts.
- Food Service Providers:Restaurant chains and institutional caterers face inconsistent trans fat regulations across operating geographies. Pan-Asian operators are standardizing on fully hydrogenated oils to simplify compliance.
- Restaurants:Independent food service operators rely on distributor recommendations without analytical verification. Indian street food vendors remain outside FSSAI enforcement scope.
- Retail Consumers:Household purchases of cooking fats and spreads respond to front-of-pack labeling. EU-bound consumers scan for accredited sub-2% trans fat certifications.
Food manufacturers dominate procurement volumes; food service providers are expanding most quickly as chain standardization accelerates.
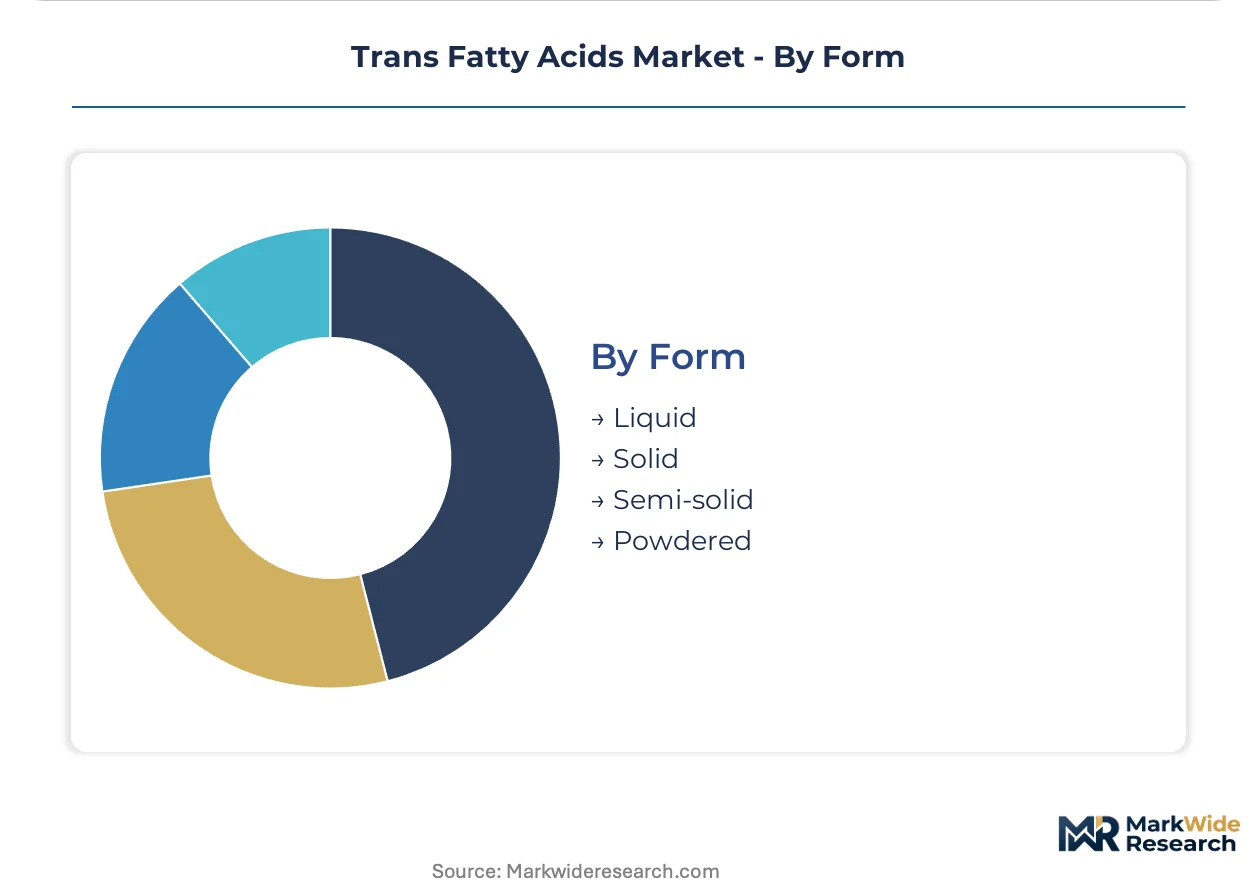
Form:
Handling infrastructure and climate conditions dictate physical state preferences across supply chains.
- Solid:Fully hydrogenated flakes and beads offer extended shelf stability and precise dosing in industrial formulations. Tropical storage facilities in Indonesia and Malaysia require temperature-controlled warehousing.
- Liquid:Unhydrogenated and partially hydrogenated oils flow through bulk handling systems without melting infrastructure. Indian port-adjacent blending facilities prioritize liquid feedstocks for operational simplicity.
- Semi-solid:Plastic shortenings and margarine bases suit small-batch bakery operations without tempering equipment. Malaysian pilot-scale enzymatic processors are sampling these formats for regional biscuit makers.
- Powdered:Encapsulated and spray-dried fats enable dry mix applications and extended ambient distribution. Instant noodle seasoning oil applications in Southeast Asia sustain limited demand.
Solid forms lead industrial volumes; liquid formats are expanding most quickly as interesterification reduces hydrogenation dependence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian palm oil refining clusters dominate industrial trans fat supply chains, with Malaysian and Indonesian processors converting crude palm oil into partially and fully hydrogenated feedstocks for regional bakery and frying applications.
Malaysia
Port Klang and Pasir Gudang refineries supply hydrogenated palm oil to domestic biscuit manufacturers and Indonesian export markets. The country's Department of Standards Malaysia enforces trans fat labeling aligned with Codex draft revisions. Johor-based processors are retrofitting hydrogenation lines for full saturation to meet EU-bound zero-trans specifications.
Indonesia
Medan and Surabaya house the nation's largest palm oil fractionation capacity, serving instant noodle and deep-frying sectors. BPOM labeling regulations are compressing partially hydrogenated oil applications ahead of anticipated content limits. North Sumatran refiners are piloting enzymatic interesterification systems for regional margarine producers.
India
Gujarat and Maharashtra concentrate domestic biscuit and fried snack manufacturing, driving demand for plastic shortenings. FSSAI disclosure mandates now require trans fat content declaration on packaged foods. Mumbai port-adjacent blending facilities are capturing volume from traditional trading houses through FSSAI-certified storage infrastructure.
United States
Midwest soybean processing hubs supply legacy partially hydrogenated oil replacements for domestic food service. FDA's final determination on partially hydrogenated oils eliminated GRAS status, forcing systematic reformulation. Illinois-based oilseed processors are converting hydrogenation capacity toward fully saturated alternatives and interesterification services.
Germany
Ruhr industrial corridor refiners specialize in technical fats for EU bakery and confectionery export markets. EFSA intake benchmarks and sub-2% trans fat verification requirements shape procurement specifications. Hamburg port facilities are segregating supply chains for EU-compliant versus non-EU-bound production lots.
Trans Fatty Acids Market Competitive Landscape
Global majors compete with regional champions across hydrogenation capacity and palm oil origination networks. The vendor base stratifies between integrated agribusiness conglomerates controlling upstream feedstock and specialty lipid modifiers with technical service differentiation. Three archetypes dominate: integrated palm oil processors with captive refining assets, diversified oilseed traders with multi-origin sourcing flexibility, and specialty chemical houses with enzymatic modification capabilities. Competitive moves center on hydrogenation line retrofitting for full saturation and strategic toll processing partnerships with mid-tier food manufacturers lacking in-house lipid expertise.
Among integrated agribusinesses, Cargill and Wilmar International Limited exemplify scale-driven positions anchored in multi-continent oilseed processing and Southeast Asian origination infrastructure respectively. BASF SE occupies the specialty chemical tier with lipid modification capabilities that differentiate technical service offerings. These three entities represent distinct competitive vectors: trading flexibility, regional refining dominance, and enzymatic technology access.
| Leading Market Players |
|---|
| Unilever |
| Archer Daniels Midland Company |
| Cargill |
| Wilmar International Limited |
| BASF SE |
| Kraton Corporation |
| Royal DSM |
| Emery Oleochemicals |
| KLK Oleo |
| Others |
Value Network & Pricing Analysis
WHO REPLACE compliance mandates gate qualified supply and premium-tier pricing access for trans fatty acid processors, as zero-trans certification requirements stratify procurement tiers across Southeast Asian and Indian markets. Buyers seeking EFSA-aligned sub-2% verification face narrower supplier pools and elevated input costs compared to domestic-market feedstock purchasers.
Pricing Analysis
Crude palm oil cost pass-through dominates pricing dynamics, with Malaysian ringgit fluctuations and Indonesian export levy adjustments transmitting directly to hydrogenated fat quotations. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified zero-trans hardstocks from FSSAI-compliant domestic grades and unverified commodity feedstocks. Pricing pressure stems from enzymatic interesterification equipment depreciation costs compressing legacy hydrogenation margins. Mid-tier Indian biscuit manufacturers exhibit highest price sensitivity, while EU-exporting Malaysian processors absorb premiums for compliance security.
Supply Chain Analysis
India's FSSAI domestic-content mandates and Indonesia's BPOM localization rules are reshaping sourcing patterns toward port-adjacent blending facilities with certified storage infrastructure. Supply concentrates in Malaysia, Indonesia, and India, with Malaysian and Indonesian refiners controlling palm oil origination and hydrogenation capacity. Raw material dependencies center on crude palm oil, palm kernel oil, and imported soybean oil for feedstock diversification. Single-source vulnerability runs through Wilmar International and Cargill's collective grip on Southeast Asian hydrogenation infrastructure. Distribution runs through regional refiners with captive port facilities, displacing long-haul trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trans fatty acids market functions as a stable compounder, with regulatory-driven reformulation cycles generating predictable demand migration from partially to fully hydrogenated alternatives. WHO REPLACE implementation timelines across emerging economies sustain volume replacement opportunities.
For Market Incumbents: Anchor hydrogenation line retrofitting investments in Johor and North Sumatra ahead of anticipated BPOM content limits, securing first-mover positions in zero-trans hardstock supply. Defend margin positions by locking multi-year toll processing contracts with mid-tier Indian biscuit manufacturers lacking in-house lipid modification capabilities. Certification investment in EFSA-aligned laboratory partnerships differentiates EU-bound supply chains from commodity competitors.
For New Entrants and Emerging Players: Mid-tier Indian food manufacturers seeking FSSAI-compliant reformulation partners represent the most penetrable buyer archetype, as analytical verification service demand outstrips regional gas chromatography infrastructure. Specialty fats for plant-based meat texturization offer white-space expansion with limited incumbent technical focus. A toll processing go-to-market model minimizes capital intensity while capturing reformulation service premiums.
For Investors and Strategic Acquirers: Roll-up economics work for regional enzymatic interesterification specialists because facility-scale fragmentation across Maharashtra and Gujarat creates consolidation synergies. Long-term viability hinges on positioning for sustained regulatory tightening across Indian and Indonesian markets. Acquisition targets should demonstrate captive relationships with domestic palm olein distributors. The signal to watch is FSSAI progression from disclosure mandates toward hard content limits, which would accelerate replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogenation Line Retrofitting | Johor-based processors converting to full saturation capture EU-bound zero-trans specifications ahead of competitors. |
| Enzymatic Interesterification Scale-Up | Medan pilot systems enable trans-free margarine structuring without hydrogenation compliance burdens. |
| Toll Processing Partnership | Mumbai port-adjacent facilities with FSSAI certification capture mid-tier brand reformulation demand. |
| EFSA-Aligned Laboratory Investment | Third-party verification services differentiate supply chains for EU member state export requirements. |
| Palm Oil Fractionation Integration | Upstream control over Malaysian and Indonesian origination secures cost positions against feedstock volatility. |
Research Methodology
Bottom-up bakery and margarine application modeling reconciled against top-down palm oil processing capacity tracking forms the analytical core of this study. Primary interviews with hydrogenation plant managers, FSSAI compliance officers at Indian food manufacturers, BPOM regulatory affairs leads, and specialty lipid procurement directors at multinational food service operators combined with secondary validation from customs trade data, Malaysian Palm Oil Board production statistics, FSSAI disclosure filings, and EFSA scientific opinions. Triangulation across stakeholder inputs and documentary sources ensures convergence on volume and value estimates.
Input-output matrix framing connects hydrogenation capacity utilization, feedstock cost indices, and regulatory compliance tier adoption to segment-level demand projections. Segmentation dimensions modeled include product type, application, end user, form, and regional production hub across the analysis window. CAGRs derive from regression-based trend extrapolation moderated by regulatory implementation schedule assumptions. Industry-specific forecast inputs incorporate enzymatic processing technology penetration rates and FSSAI enforcement intensity indices.
Underlying measurement precision varies by segment; fully hydrogenated oils and EU-certified supply chains carry tighter precision than legacy partially hydrogenated applications in informal Indian markets. Forecasts reflect assumptions around WHO REPLACE adoption timelines, BPOM regulatory progression, and palm oil price volatility parameters. Regulatory acceleration, feedstock supply disruptions, or analytical verification infrastructure gaps could materially revise projections. A small set of triggers—FSSAI content limit announcements, Indonesian export levy adjustments, and EU Codex alignment decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cook-Up Starch Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Mexico Food Additives Market