
 Europe Nutraceutical Excipients Market | 2026-2036
Europe Nutraceutical Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nutraceutical Excipients Market Foresight
The EU Green Deal is recalibrating how excipient buyers evaluate supplier carbon footprints and circularity credentials. BASF SE leverages its bio-based polymer portfolio to capture formulation mandates from sustainability-driven nutraceutical brands. Roquette Frères anchors its position through pea-derived starch excipients that align with plant-based label trends. Evonik Industries AG differentiates via silica-based flow agents engineered for high-shear tablet manufacturing.
Nutraceutical excipients comprise pharmacologically inactive substances—binders, fillers, disintegrants, and coatings—that enable active-ingredient stability, controlled release, and manufacturability in dosage forms such as tablets, capsules, powders, and granules. These materials must meet compendial standards for purity, particle-size distribution, and hygroscopicity to ensure batch-to-batch consistency in GMP environments. Binders and fillers occupy the largest volume share as tablet and capsule formats dominate European nutraceutical consumption, while coatings command premium positioning due to enteric-release and moisture-barrier functional requirements. Powder excipients sustain broad applicability across sachet and bulk-blend applications, whereas granule grades are gaining traction in direct-compression workflows that reduce manufacturing steps.
EMA guidelines on excipient quality and the EU's REACH framework govern chemical safety disclosures, while the F-Gas Regulation pressures manufacturers to abandon fluorinated propellants and solvents in coating processes. EFSA novel-food assessments increasingly intersect with excipient innovation when plant-derived carriers lack established consumption histories. Buyers and suppliers must monitor how the EU AI Act and digital product passport requirements will reshape batch documentation and supply-chain traceability obligations.
Market Dynamics
The EU Green Deal is compressing excipient procurement timelines as buyers demand verified carbon footprints and bio-based content certifications before contract renewal. German and French nutraceutical formulators now require suppliers to document circularity credentials alongside traditional pharmacopeial compliance.
Growth Catalysts
- Clean-label formulation mandates:Western European nutraceutical brands are eliminating synthetic additives, creating pull for plant-derived binders and coatings that satisfy EFSA novel-food assessments.
- EMA quality guideline updates:Tightened excipient purity standards are forcing supplier consolidation, advantaging firms with in-house analytical capabilities and GMP-certified manufacturing.
- Direct-compression workflow adoption:Tablet manufacturers in Italy and Spain are adopting granule-grade excipients to reduce processing steps, expanding addressable volume for specialty filler suppliers.
Market Restraints
- Feedstock cost volatility:Pea starch and potato-derived excipients face input price swings from agricultural yield variability across Benelux growing regions.
- Western European supply concentration:Over 60% of pharmaceutical-grade excipient capacity sits in Germany and France, creating geographic risk for buyers seeking redundancy.
- REACH compliance burden:Chemical safety dossier requirements for novel bio-based polymers extend time-to-market by 18-24 months versus conventional materials.
Strategic Opportunities
- Central and Eastern European manufacturing:Poland and Czech Republic offer lower-cost production bases with improving logistics connectivity to Western European formulation hubs.
- Enteric coating specialization:Demand for pH-triggered release in probiotic and enzyme supplements is outpacing supply of compliant polymer coatings.
- EU AI Act traceability requirements:Digital product passport mandates will reward suppliers with pre-built batch-documentation systems and blockchain-enabled provenance tracking.
Industry Challenges
- Analytical chemistry talent scarcity:Excipient manufacturers struggle to hire specialists capable of validating particle-size distribution and hygroscopicity under ICH Q2(R1) guidelines.
- Legacy ERP integration friction:Real-time carbon accounting for EU Green Deal reporting conflicts with decades-old manufacturing execution systems at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nutraceutical Excipients Market |
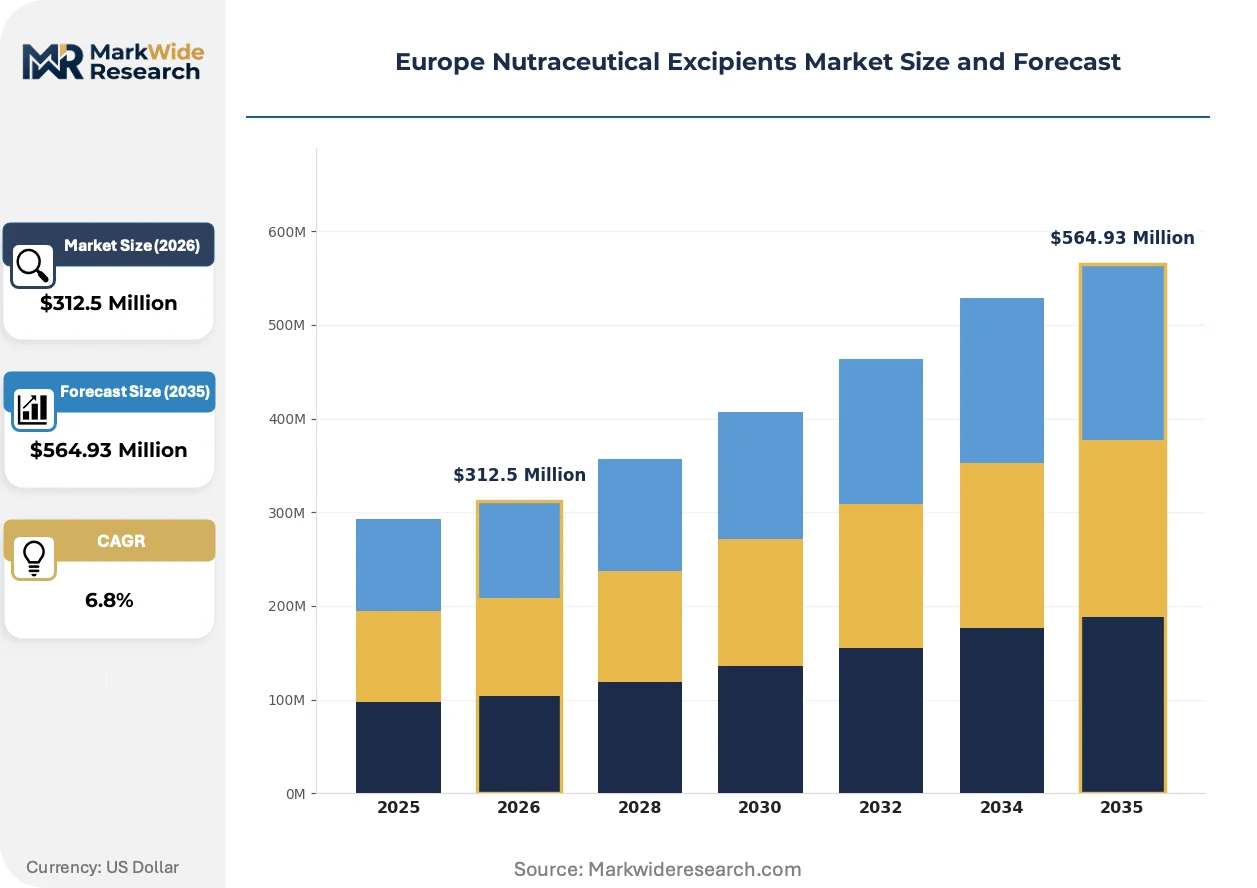
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binders, Fillers, Disintegrants, Coatings Form: Powder, Granules, Capsules, Tablets End User: Pharmaceutical Companies, Nutraceutical Manufacturers, Contract Manufacturers, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | BASF SE, Evonik Industries AG, Roquette Frères, Kerry Group PLC, DFE Pharma, JRS Pharma, Lonza Group Ltd., Tate & Lyle PLC, Brenntag AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nutraceutical Excipients Market Shifts & Advancements
Formulation science is converging with sustainability engineering as bio-based excipients absorb functionality requirements previously met by petrochemical derivatives. Regulatory pressure and brand positioning are jointly accelerating material substitution timelines.
Co-processed excipient systems are absorbing complexity from multi-step manufacturing by combining binder, disintegrant, and lubricant functions in single granule structures. High-shear tablet producers in Germany and Switzerland are adopting these pre-optimized blends to compress cycle times and reduce in-process testing. The technology is absorbing capital that would otherwise flow to discrete excipient inventory expansion.
REACH authorization requirements for persistent organic pollutants are forcing coating manufacturers to abandon fluorinated solvents ahead of F-Gas Regulation phase-out deadlines. Water-based and supercritical CO2 coating processes are capturing investment formerly directed toward conventional solvent systems. Enteric coating applications face the steepest compliance climb, with reformulation costs concentrated among mid-sized nutraceutical contract manufacturers.
Buyer concentration among pan-European nutraceutical brands is compressing supplier negotiation leverage and accelerating long-term contracting. Direct purchasing agreements between formulation houses and excipient producers are displacing traditional distributor intermediaries in tablet and capsule segments. This pattern is most visible in France and Germany, where three contract manufacturers now account for the majority of pharmaceutical-grade excipient procurement volume.
Europe Nutraceutical Excipients Market Segmentation
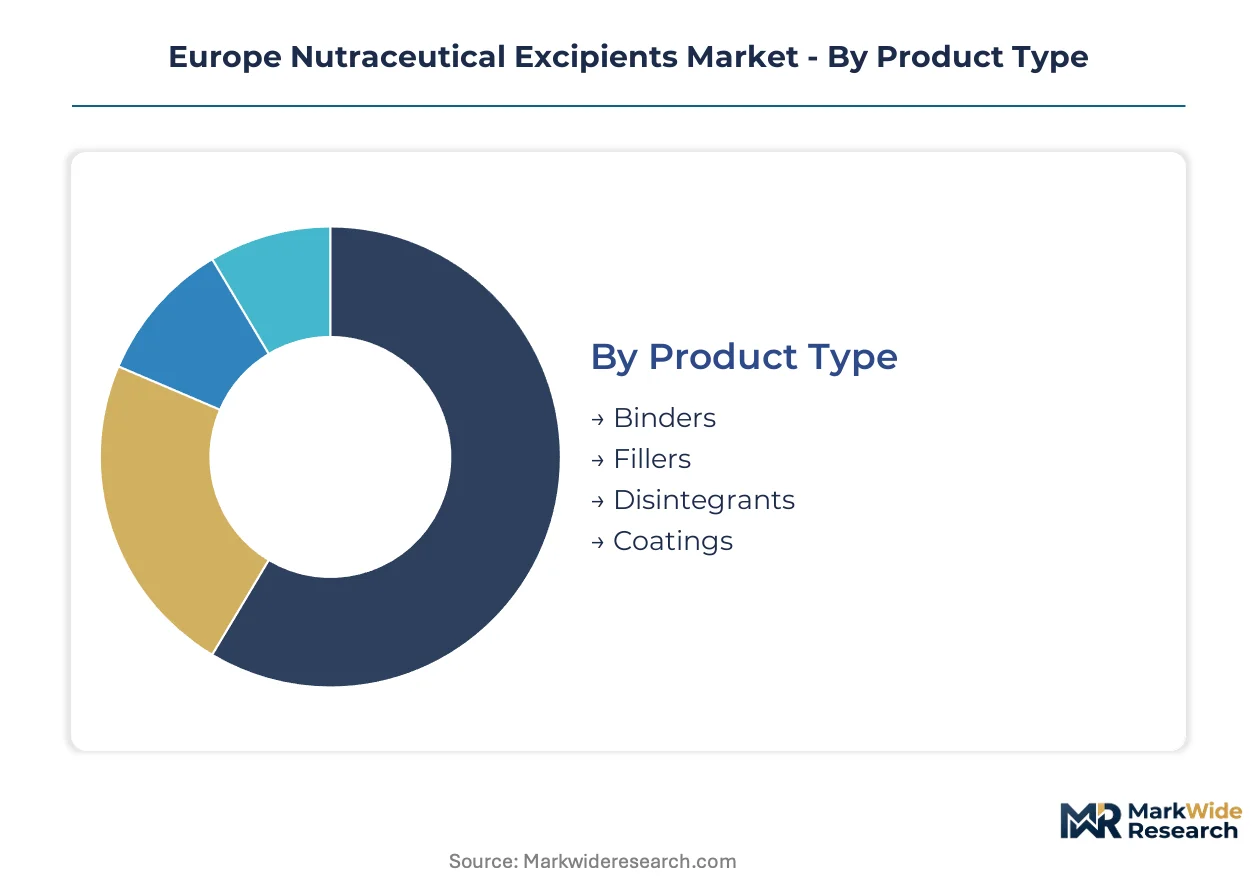
Segmentation in the Europe nutraceutical excipients market reveals how formulation requirements, manufacturing workflows, and procurement channels fragment demand across distinct technical and commercial profiles. Buyers select excipient grades based on dosage form compatibility, regulatory certification tiers, and supply chain integration depth rather than commodity pricing alone.
Product Type:
Buyers differentiate primarily by functional role in dosage form architecture—whether the excipient provides structural integrity, enables release kinetics, or protects actives from environmental degradation.
- Binders:Polymeric adhesives such as povidone and hydroxypropyl cellulose confer tablet integrity under compression forces. German and Swiss tablet manufacturers prioritize binder grades with validated particle-size distribution for high-speed rotary presses, driven by EMA quality guideline updates that tighten batch-to-batch consistency requirements.
- Fillers:Bulking agents including microcrystalline cellulose and lactose monohydrate occupy volume share leadership as tablet and capsule formats dominate European nutraceutical consumption. French formulators are expanding direct-compression workflows that demand filler grades with superior flow properties and reduced lubricant sensitivity.
- Disintegrants:Superdisintegrants like croscarmellose sodium accelerate tablet breakup in aqueous environments. Demand concentrates in effervescent and orodispersible formats where rapid release kinetics are formulation-critical.
- Coatings:Enteric and moisture-barrier polymers command premium positioning due to functional complexity and regulatory scrutiny under REACH and F-Gas Regulation frameworks.
Volume sits with fillers; growth tilts toward coatings as probiotic and enzyme applications expand pH-triggered release requirements.
Form:
Physical state determines manufacturing equipment compatibility, powder handling protocols, and finished dose aesthetics across European GMP facilities.
- Powder:Free-flowing particulate grades sustain broad applicability across sachet, bulk-blend, and capsule-filling operations. Italian nutraceutical contract manufacturers favor powder excipients for multi-component premix flexibility in sports nutrition and personalized nutrition workflows.
- Granules:Agglomerated particle structures engineered for direct-compression tableting absorb processing step reductions that lower manufacturing overhead. Spanish tablet producers are adopting granule-grade fillers to eliminate wet-granulation stages, expanding addressable volume for specialty agglomerated products.
- Capsules:Pre-formulated excipient blends optimized for two-piece hard gelatin and HPMC capsule shells. Demand tracks vegetarian capsule format expansion across Benelux clean-label brands.
- Tablets:Compression-ready excipient systems with validated lubricant and disintegrant inclusion levels. Dominates finished dose economics for high-volume mineral and vitamin applications.
Granules are expanding most quickly as direct-compression adoption accelerates; powders retain volume leadership across contract manufacturing segments.
End User:
Procurement sophistication and technical specification authority separate organizational buyers, with GMP certification tiers and formulation R&D depth driving supplier selection criteria.
- Pharmaceutical Companies:Vertically integrated drug manufacturers with captive nutraceutical divisions impose pharmacopeial-grade purity standards and audit-intensive supplier qualification protocols. Bayer and Sanofi nutraceutical units in Germany and France leverage long-term supply agreements that displace distributor intermediaries.
- Nutraceutical Manufacturers:Dedicated dietary supplement houses including those in Switzerland and the Netherlands prioritize clean-label positioning and bio-based content certifications aligned with EU Green Deal procurement mandates.
- Contract Manufacturers:Third-party formulation and packaging specialists serving multiple brand owners. CDMOs in Italy and Poland consolidate excipient purchasing across client portfolios to extract volume pricing from specialty suppliers.
- Research Institutions:Academic and clinical trial material producers with small-batch, high-variability requirements. Limited volume but significant technology scouting influence for novel excipient platforms.
Contract manufacturers concentrate procurement volume; nutraceutical manufacturers are gaining specification authority fastest as brand owners internalize formulation science.
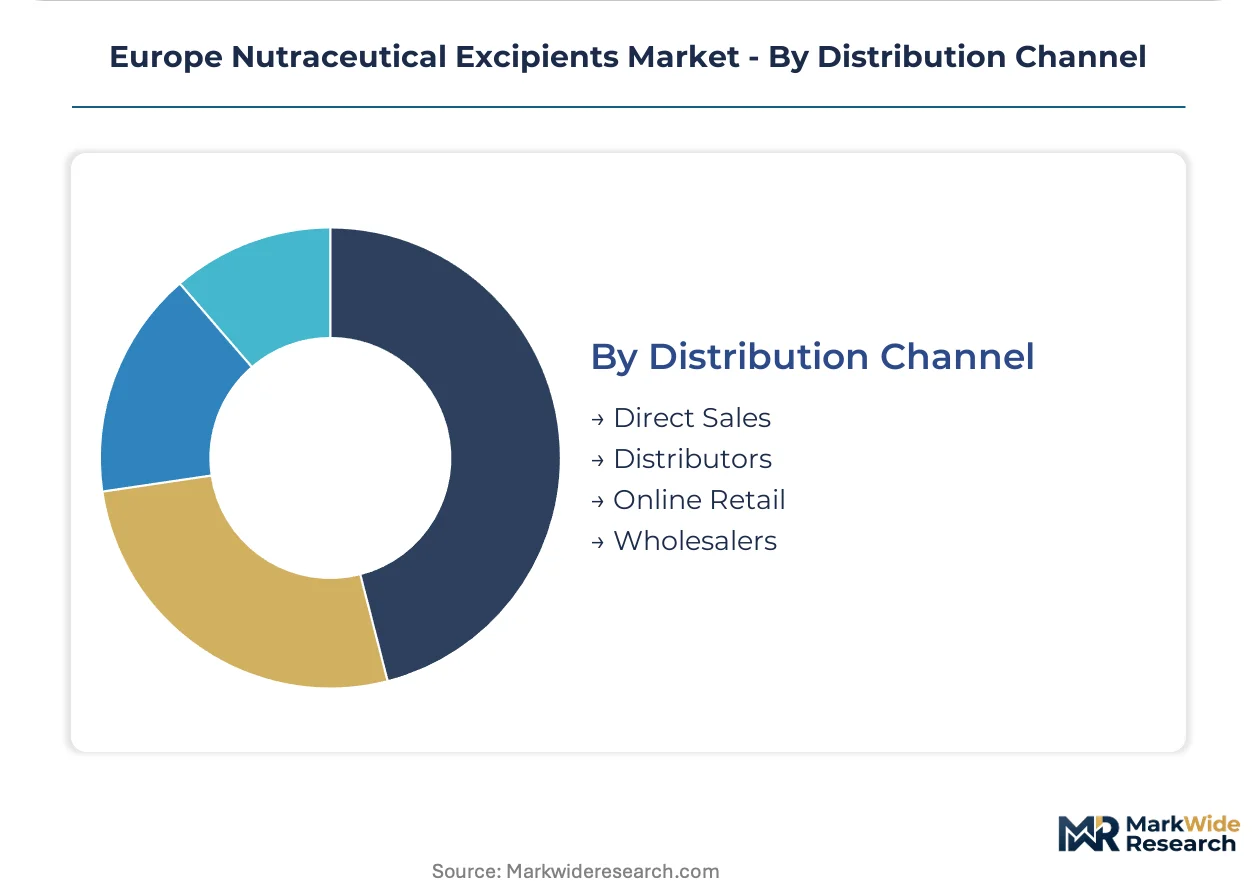
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to formulation facilities across Western and Central Europe.
- Direct Sales:Manufacturer-to-buyer relationships for pharmaceutical-grade and high-volume specialty excipients. BASF SE and Roquette Frères field technical sales teams that co-develop formulation solutions with German and French anchor accounts.
- Distributors:Inventory-holding intermediaries providing just-in-time delivery and multi-supplier consolidation for mid-tier buyers. Traditional channel share is compressing as direct purchasing agreements expand.
- Online Retail:E-procurement platforms serving small-batch researchers and startup nutraceutical brands. Limited to non-pharmaceutical grades and standard catalog items.
- Wholesalers:Regional logistics specialists with cold-chain and hazardous material handling capabilities. Serves Central European manufacturers with fragmented supplier bases.
Distributors retain volume leadership; direct sales channels are climbing the fastest as buyer concentration accelerates long-term contracting with specialty excipient producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European excipient manufacturing, hosting BASF SE and Evonik Industries AG facilities that supply pharmaceutical-grade materials across the continent. German chemical clusters in Ludwigshafen and Marl concentrate GMP-certified capacity that Western European nutraceutical formulators depend upon for batch-to-batch consistency.
Germany
Bavarian and North Rhine-Westphalian tablet manufacturers drive demand for high-shear-compatible flow agents and direct-compression fillers. The country's Federal Institute for Drugs and Medical Devices enforces pharmacopeial-grade purity standards that exceed baseline EMA requirements. Chemical parks in Ludwigshafen and Leverkusen concentrate backward-integrated excipient production with captive analytical validation capabilities.
France
Parisian and Lyonnaise nutraceutical brands are expanding clean-label formulation programs that specify bio-based binders and pea-derived starches. ANSM guidelines on excipient quality intersect with EU Green Deal procurement mandates requiring verified carbon footprints. The Lyonbiopôle cluster anchors contract manufacturing capacity serving pan-European brand owners with enteric coating specialization.
Switzerland
Basel-area pharmaceutical divisions and dedicated nutraceutical houses prioritize Swissmedic-certified excipient grades for premium positioning. The country's dual-track regulatory alignment with both EMA frameworks and independent Swissmedic standards creates certification complexity for suppliers. Geneva and Basel formulation facilities concentrate demand for moisture-barrier coatings in probiotic applications.
Italy
Emilia-Romagna and Lombardy contract manufacturers are adopting granule-grade excipients to eliminate wet-granulation processing steps. Italian health ministry circulars on dietary supplement manufacturing reinforce GMP compliance requirements for imported excipient materials. The Milan-Turin industrial corridor hosts CDMOs consolidating purchasing volume across multiple brand-owner portfolios.
Poland
Warsaw and Łódź manufacturing zones offer lower-cost production bases with improving rail and road connectivity to German formulation hubs. Polish excipient distributors are capturing volume from Western European suppliers seeking geographic redundancy against German-French concentration risk. The country's alignment with EU REACH and EMA standards enables seamless cross-border supply to Benelux and Scandinavian markets.
Europe Nutraceutical Excipients Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with backward-integrated polymer and carbohydrate portfolios. Three archetypes dominate: petrochemical-derived specialty polymer suppliers, plant-based starch and cellulose processors, and toll-manufacturing distributors with blending capabilities. Capacity expansion and direct long-term contracting with anchor nutraceutical brands represent the dominant competitive vectors displacing traditional distributor intermediaries.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the petrochemical-specialty archetype with pharmaceutical-grade certification depth. Roquette Frères represents the plant-based processing tier through its pea-derived excipient positioning. These three anchors demonstrate how European excipient supply concentrates around entities with dual capability in compendial compliance and bio-based content verification.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Roquette Frères |
| Kerry Group PLC |
| DFE Pharma |
| JRS Pharma |
| Lonza Group Ltd. |
| Tate & Lyle PLC |
| Brenntag AG |
| Others |
Supply & Pricing Matrix
Agricultural commodity indices for pea starch and potato-derived carbohydrates cascade through three distinct pricing tiers in European nutraceutical excipient procurement. German and French formulators segment contracts by pharmacopeial certification grade, with REACH-compliant bio-based polymers commanding substantial premia over conventional petrochemical alternatives.
Pricing Analysis
Throughput-linked pricing anchors long-term supply agreements between BASF SE and high-volume tablet manufacturers, where yield guarantees in direct-compression workflows justify contract premia. Pricing stratifies across pharmaceutical-grade, technical-grade, and feed-grade certification tiers, with EMA guideline compliance acting as the primary price differentiator. Cost compression in technical-grade binders is intensifying because Central European distributors are consolidating purchasing volumes across mid-tier nutraceutical brands. Contract manufacturers exhibit highest price sensitivity due to thin margin structures, while captive pharmaceutical divisions absorb premia for batch-to-batch consistency guarantees.
Supply Chain Analysis
Pea starch supply rests on Benelux agricultural processing clusters and Roquette Frères' French manufacturing footprint, with potato-derived excipients drawing from German and Polish starch extraction facilities. Specialty silica flow agents hinge on Evonik Industries AG's Marl chemical park operations and imported precipitated grades. Single-source vulnerability concentrates in pharmaceutical-grade cellulose derivatives, where JRS Pharma and DFE Pharma control majority European capacity. Distribution runs through direct manufacturer relationships for high-volume buyers, with Brenntag AG and regional distributors serving fragmented mid-tier demand across Italy and Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade excipient capacity constraints in the Rhine-Ruhr corridor prop pricing power for incumbent suppliers, with GMP-certified manufacturing expansion timelines extending 36-48 months for greenfield sites.
For Market Incumbents: Anticipate bio-based polymer substitution threats from Roquette Frères' pea-derived portfolio by deepening backward integration into agricultural feedstock sourcing. Anchor position through captive analytical validation capabilities that compress EMA quality guideline compliance timelines for anchor accounts. Prioritize capacity addition in Poland to offset geographic concentration risk flagged by Western European procurement officers. For New Entrants and Emerging Players: Water-based enteric coating technologies offer white-space entry against fluorinated solvent-dependent incumbents facing F-Gas Regulation phase-out deadlines. Target probiotic formulation specialists in Switzerland and the Netherlands with pH-triggered release coatings that bypass REACH authorization bottlenecks. Pursue toll-manufacturing partnerships with Italian CDMOs to bypass direct certification investment requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier distributors with blending capabilities in Central European logistics corridors. Long-term viability centers on suppliers with pre-built digital product passport systems aligned with EU AI Act traceability mandates. Watch EFSA novel-food assessment backlogs as inflection signal for bio-based excipient approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Roquette Frères' pea starch sourcing secures supply continuity against Benelux yield volatility. |
| GMP-Certified Capacity Expansion | BASF SE's Ludwigshafen investments tighten batch-to-batch consistency for EMA-compliant tablet manufacturers. |
| Water-Based Coating Process Transition | Specialty suppliers bypass F-Gas Regulation deadlines while capturing probiotic enteric coating demand. |
| Digital Product Passport Implementation | Blockchain-enabled provenance tracking aligns with EU AI Act mandates for pharmaceutical-grade traceability. |
| Central European Distribution Hub Establishment | Polish logistics nodes reduce delivery friction to German formulation clusters while diversifying geographic risk. |
Research Methodology
Independent corroboration across excipient procurement directors, plant managers at GMP-certified facilities, and regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork engaged technical sales leads at BASF SE and Roquette Frères alongside distribution channel partners at Brenntag AG. Secondary validation drew from EMA quality guideline updates, REACH authorization databases, and EU Green Deal procurement disclosure filings. Bottom-up volume estimates from country-level excipient consumption data triangulate against top-down chemical industry production statistics.
Rate-of-change decomposition separates volume expansion from price escalation effects across the analysis window. The analytical framework models product type, form grade, end-user certification tier, and distribution channel depth as core segmentation dimensions. CAGRs derive from regression-adjusted historical consumption patterns and forward-projected formulation technology adoption curves. Forecast inputs incorporate EFSA novel-food assessment pipeline velocity and F-Gas Regulation compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under agricultural commodity price spikes and REACH authorization delays. Forecasts reflect assumptions on sustained EU Green Deal procurement mandate enforcement and stable EMA guideline interpretation. A small set of named triggers warrants ongoing watch: Benelux starch crop yields, EFSA assessment backlog clearance rates, and EU AI Act digital passport implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Fitness Cookies Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Tryptophan Market
Nutritional Supplements
China Collagen Peptides Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Global Coq10 Supplement Market
Nutritional Supplements
China Whey Protein Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Europe Dietary Supplements Market