
 Europe Nutraceutical Market | 2026-2036
Europe Nutraceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nutraceutical Market Foresight
Subscription-based personalized nutrition programs is realigning how European consumers access nutraceutical products, shifting transactions from one-time purchases to recurring revenue relationships. Nestlé S.A. leverages its direct-to-consumer platforms to capture ongoing engagement through tailored supplement regimens. Glanbia PLC anchors its competitive stance through specialized sports nutrition subscriptions targeting athlete segments. DSM-Firmenich differentiates via science-backed ingredient formulations that command premium positioning in recurring delivery models.
Nutraceuticals comprise bioactive compounds, vitamins, minerals, and botanical extracts formulated to deliver physiological benefits beyond basic nutrition, typically manufactured through cold-pressing, microencapsulation, or fermentation processes to preserve bioavailability. Functional Foods dominate European shelf space as mature categories with established margin pools in dairy and bakery applications. Dietary Supplements in gummy and liquid forms represent the fastest-expanding segment as consumers reject traditional pill formats. Online Retail channels capture disproportionate growth velocity among adult and senior end users seeking convenience and discretion.
EFSA establishes health claim validation thresholds that determine which products qualify for beneficial marketing, while the EU Green Deal packaging requirements force reformulation of encapsulation materials and bottle compositions. REACH chemical safety protocols and the F-Gas Regulation constrain solvent-based extraction processes, elevating capital requirements for compliant manufacturing. Stakeholders must monitor evolving EFSA guidance on microbiome-related claims and assess whether sustainable packaging investments will become mandatory market access conditions rather than competitive differentiators.
Market Dynamics
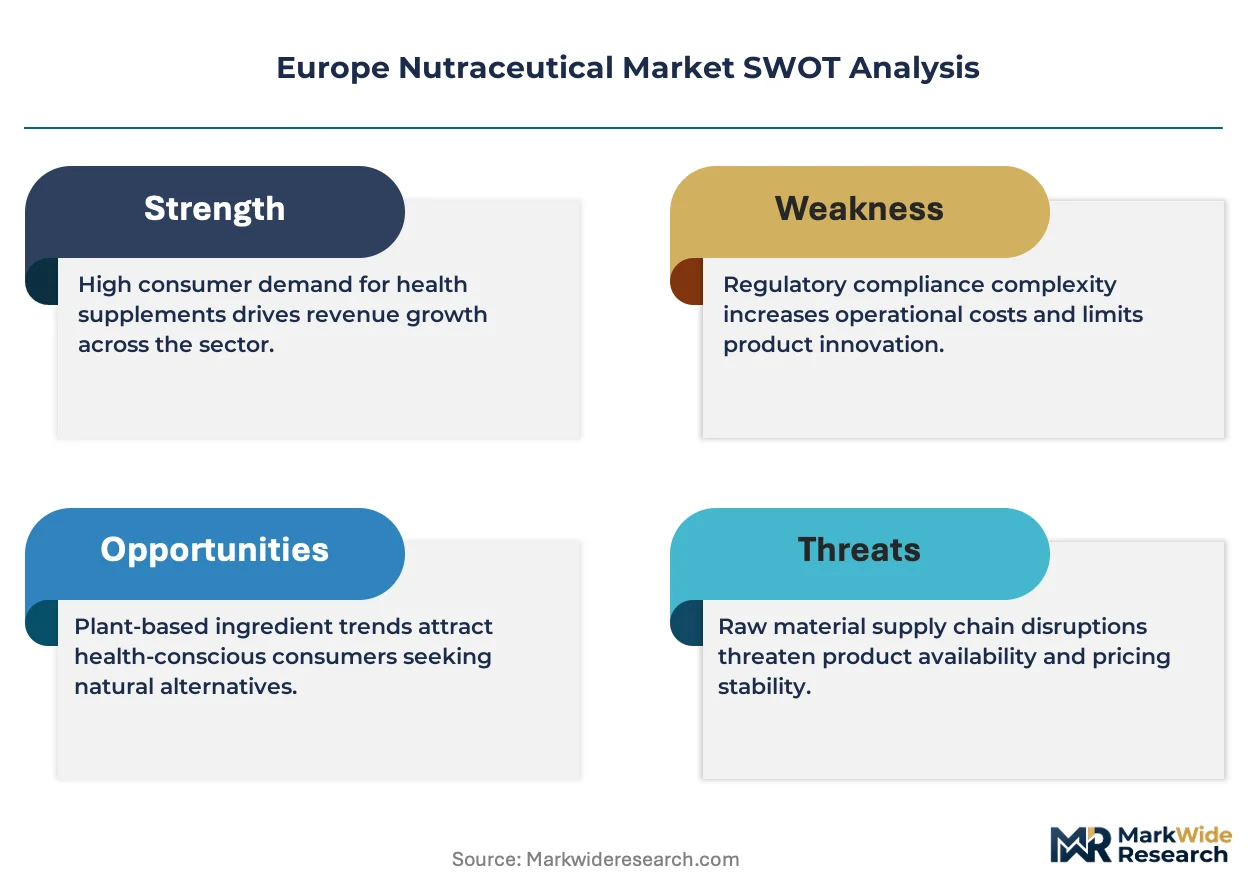
EFSA's evolving health claim validation protocols and the EU Green Deal's sustainable packaging mandates are compressing product development timelines while elevating capital requirements for European nutraceutical manufacturers seeking market access.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined approvals for microbiome-targeted ingredients accelerate time-to-market for fermentation-derived bioactives in Germany and France.
- Senior Preventive Health Demand:Aging demographics in Italy and Spain drive pharmacy-led adoption of clinically validated joint and cognitive health formulations.
- Cold-Press Extraction Scale-Up:Capital investment into solvent-free botanical processing preserves heat-sensitive polyphenols for premium positioning.
Market Restraints
- REACH Compliance Burden:Chemical safety dossier requirements for novel encapsulation materials extend development cycles by 18-24 months.
- F-Gas Regulation Constraints:Solvent-based extraction equipment using fluorinated gases faces phase-out timelines, forcing capital-intensive process retooling.
- Botanical Supply Concentration:Mediterranean and Balkan sourcing clusters for standardized herbal extracts create geographic vulnerability to climate volatility.
Strategic Opportunities
- Poland and Romania Expansion:Underpenetrated pharmacy networks and rising disposable incomes create first-mover advantage for subscription-based personalized nutrition.
- EU Green Deal Packaging Incentives:Biodegradable encapsulation material mandates reward early adopters with preferential retail placement in Nordic markets.
- Gummy Format Convergence:Liquid-to-gummy manufacturing technology transfer from confectionery opens pediatric and senior segments previously rejecting pill formats.
Industry Challenges
- Microbiome Claim Documentation:EFSA's shifting evidentiary standards for gut health benefits require clinical trial investment without guaranteed approval timelines.
- Legacy ERP Integration:Batch traceability systems for REACH-compliant supply chains conflict with existing manufacturing execution platforms in mid-cap facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nutraceutical Market |
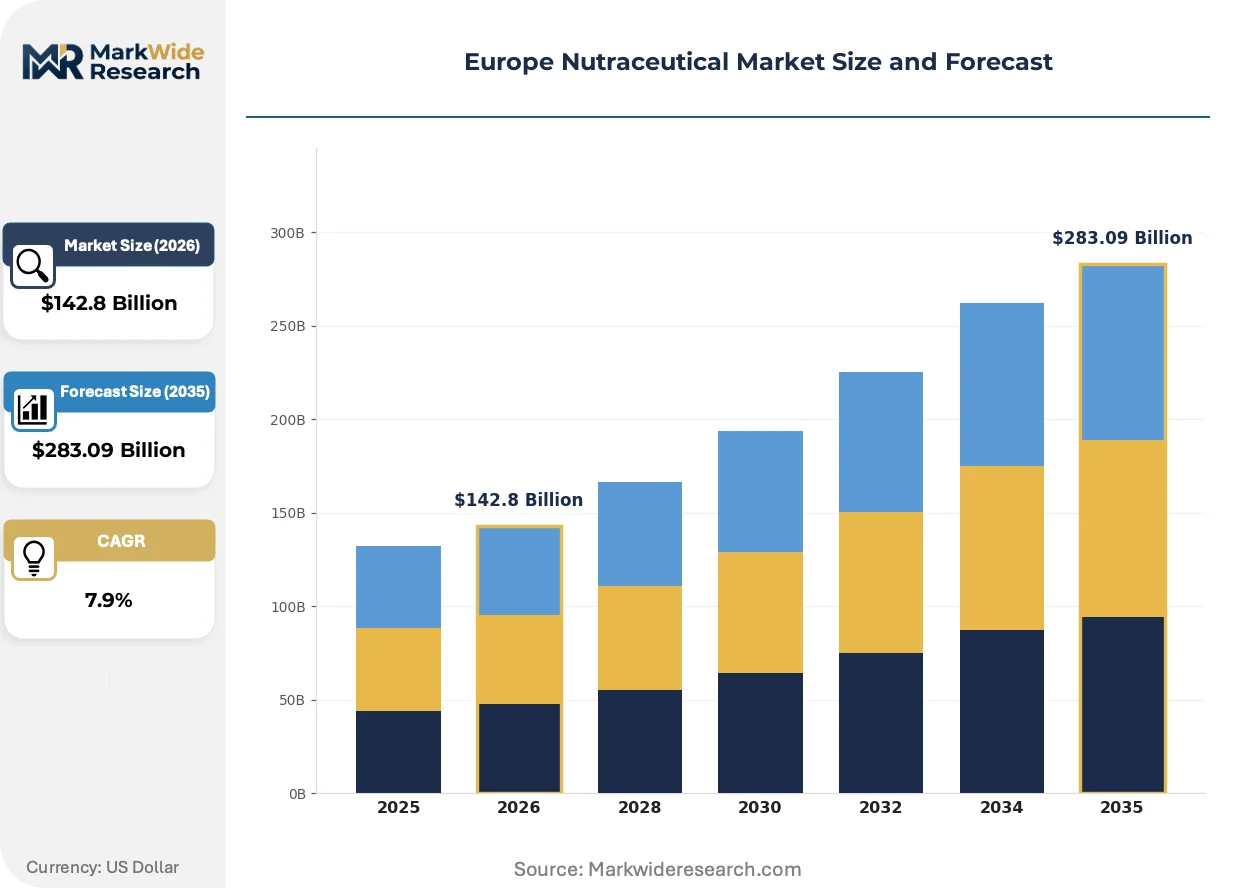
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $283.09 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Functional Foods, Herbal Products, Nutraceutical Drinks Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Adults, Seniors, Athletes, Children Form: Capsules, Powders, Liquids, Gummies |
| Companies Covered | Nestlé S.A., Glanbia PLC, Herbalife Nutrition Ltd., Amway Corp., Arla Foods Group, Danone S.A., Bayer AG, DSM-Firmenich, Abbott Laboratories, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nutraceutical Market Shifts & Advancements
European nutraceutical manufacturing is pivoting toward bioavailability-preserving technologies and regulatory-compliant packaging formats that satisfy both EFSA substantiation requirements and the EU Green Deal's circular economy targets.
Microencapsulation via lipid-based delivery systems is integrating phospholipid complexes and nano-emulsion technologies to enhance absorption of fat-soluble vitamins. German and Dutch contract manufacturers are retrofitting spray-drying lines to accommodate these processes. This convergence is integrating premium ingredient positioning with extended release profiles that command recurring subscription pricing.
EFSA's draft guidance on microbiome-related health claims is forcing reformulation of probiotic and prebiotic portfolios toward strain-specific clinical evidence. Manufacturers must commission human intervention studies rather than relying on generic genus-level claims. Dairy and bakery applications in France and Benelux face the steepest evidentiary recertification burdens.
Subscription-based personalized nutrition platforms are displacing traditional pharmacy and supermarket transactions among urban professionals aged 35-55. Direct-to-consumer channels capture recurring revenue through algorithm-driven supplement regimens matched to biomarker data. This shift concentrates most visibly in German metropolitan clusters where digital health adoption outpaces southern European markets.
Europe Nutraceutical Market Segmentation
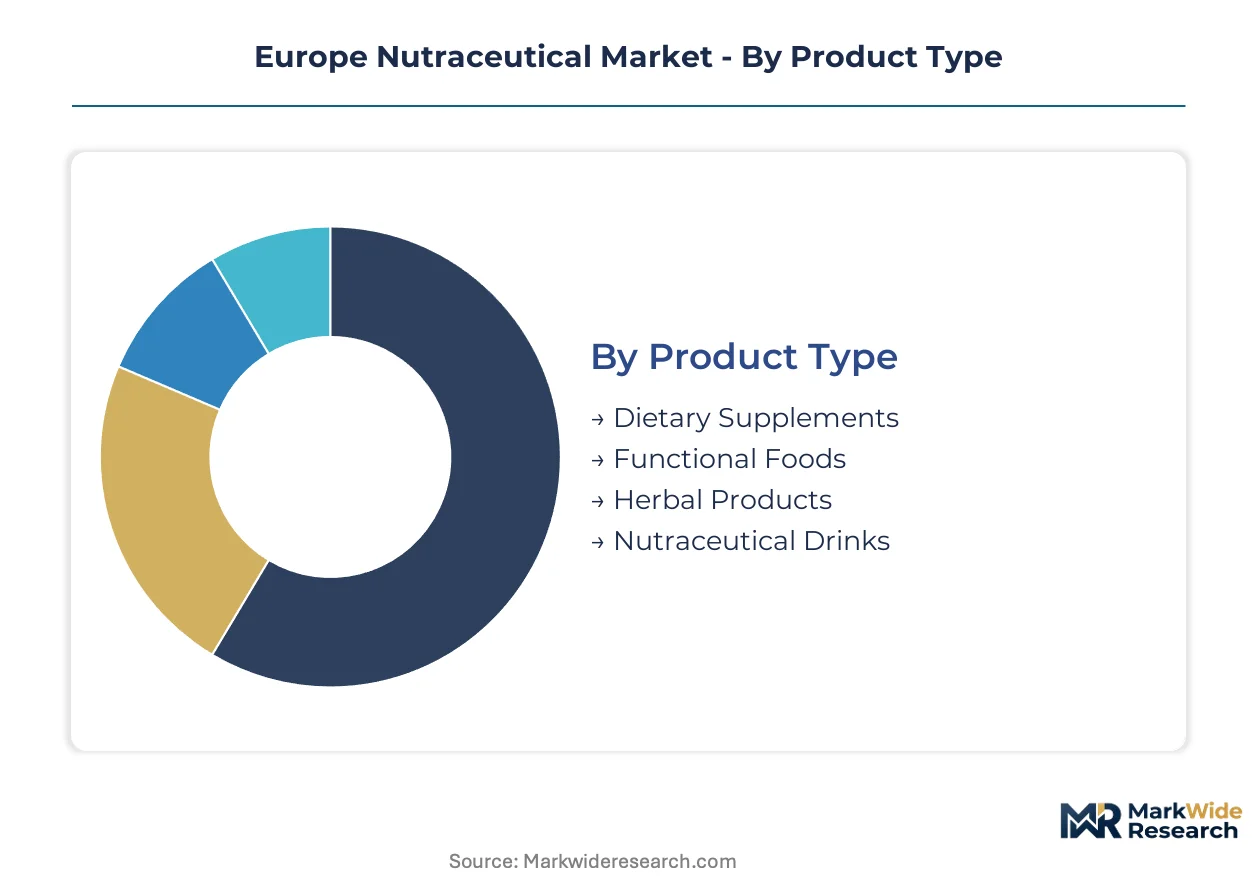
European nutraceutical purchasing decisions diverge sharply across product formats, channel preferences, and demographic targets, requiring manufacturers to calibrate formulations, packaging, and pricing to distinct buyer profiles rather than treating the market as monolithic.
Product Type:
Buyers prioritize physiological benefit specificity over brand loyalty, driving manufacturers to align product architectures with clinically validated outcome claims that satisfy EFSA substantiation thresholds.
- Functional Foods:Dairy and bakery applications dominate shelf space with established margin pools in fortified yogurts and omega-3 enriched breads. German and French retailers concentrate procurement around clinically validated cardiovascular and digestive health positioning that commands premium placement.
- Dietary Supplements:Gummy and liquid formats are expanding most quickly as consumers reject traditional pill architectures, particularly among senior populations seeking ease-of-swallow alternatives. Subscription-based personalized regimens concentrate demand in urban German and Dutch metropolitan clusters.
- Herbal Products:Standardized Mediterranean and Balkan-sourced botanical extracts face climate volatility risks in supply planning.
- Nutraceutical Drinks:Ready-to-consume functional beverages target on-the-go professionals with bioavailability-optimized liquid delivery systems.
Functional Foods leads on scale; Dietary Supplements leads on momentum.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with digital platforms enabling recurring revenue models that traditional retail cannot replicate.
- Pharmacies:Germany's pharmacy-led distribution concentrates consumption clusters for clinically validated joint and cognitive health formulations among aging demographics. EFSA-approved health claims serve as gatekeeping credentials for shelf access in this high-trust channel.
- Online Retail:Direct-to-consumer platforms capture disproportionate growth velocity among adult and senior end users seeking convenience and discretion. Algorithm-driven supplement regimens matched to biomarker data concentrate recurring revenue relationships in metropolitan markets.
- Supermarkets:Mass-market functional food placement depends on established brand recognition and promotional slotting fees.
- Health Stores:Specialized retailers cater to ingredient-conscious consumers prioritizing organic certification and clean-label positioning.
Pharmacies anchor revenue stability; Online Retail commands expansion velocity.
End User:
Demographic targeting shapes formulation priorities, with age-specific physiological needs driving distinct active ingredient portfolios and dosage architectures.
- Seniors:Preventive health demand concentrates in Italy and Spain for pharmacy-led adoption of joint mobility and cognitive support formulations. EFSA novel food approvals for microbiome-targeted ingredients accelerate time-to-market for fermentation-derived bioactives addressing age-related digestive concerns.
- Athletes:Specialized sports nutrition subscriptions target performance optimization through protein and amino acid formulations with batch-certified purity standards.
- Adults:Urban professionals aged 35-55 drive subscription-based personalized nutrition adoption through biomarker-matched regimens.
- Children:Pediatric formulations in gummy formats overcome pill rejection patterns through confectionery-derived manufacturing technology transfer.
Seniors dominate current spending; Adults demonstrate steepest digital adoption curves.
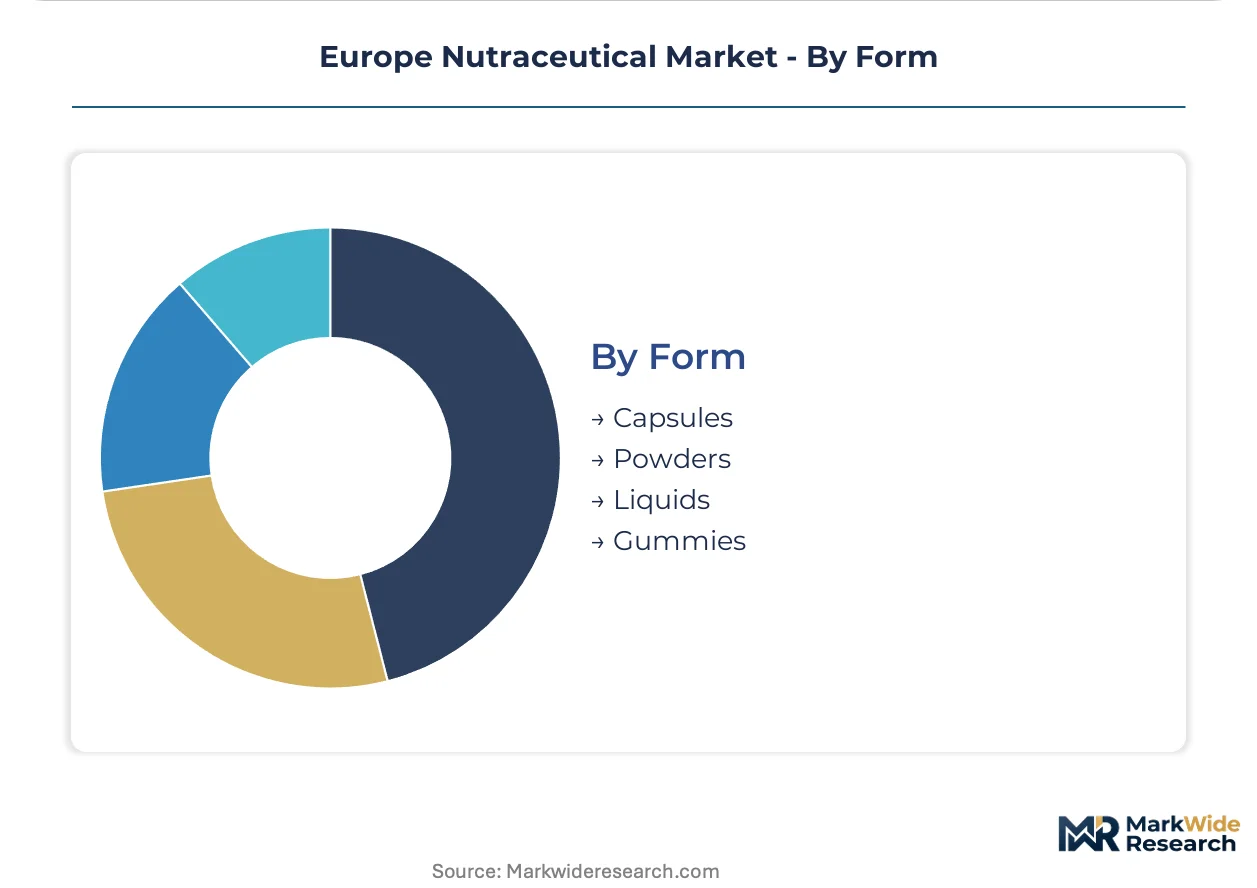
Form:
Format engineering directly impacts bioavailability preservation, patient compliance, and manufacturing process capital requirements.
- Gummies:Liquid-to-gummy manufacturing technology transfer from confectionery opens pediatric and senior segments previously rejecting pill formats. EU Green Deal biodegradable encapsulation material mandates reward early adopters with preferential retail placement in Nordic markets.
- Liquids:Lipid-based delivery systems and nano-emulsion technologies enhance absorption of fat-soluble vitamins through spray-drying line retrofits in German and Dutch contract manufacturing facilities.
- Capsules:Microencapsulation via phospholipid complexes enables extended release profiles that command recurring subscription pricing.
- Powders:Solvent-free cold-press extraction preserves heat-sensitive polyphenols for premium positioning in sports nutrition applications.
Capsules maintain volume leadership; Gummies exhibit sharpest format migration patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pharmacy-led distribution density unmatched elsewhere in Europe, while Italy concentrates aging demographics driving preventive nutraceutical demand through specialized retail channels.
Germany
Pharmacy networks in North Rhine-Westphalia and Bavaria anchor consumption clusters for clinically validated joint and cognitive health formulations among senior populations. EFSA novel food approvals for microbiome-targeted ingredients accelerate fermentation-derived bioactive commercialization. Berlin-Brandenburg metropolitan clusters concentrate subscription-based personalized nutrition platforms serving urban professionals aged 35-55.
France
Dairy and bakery applications dominate functional food shelf space with established margin pools in fortified yogurts and omega-3 enriched breads. EFSA health claim validation thresholds determine beneficial marketing qualifications for cardiovascular positioning. Île-de-France retailers concentrate procurement around clinically substantiated digestive health products commanding premium placement fees.
Italy
Aging demographics in Lombardy and Veneto drive pharmacy-led adoption of joint mobility and cognitive support formulations. EFSA draft guidance on microbiome-related claims forces reformulation of probiotic portfolios toward strain-specific clinical evidence. Milan's metropolitan cluster concentrates demand for bioavailability-optimized liquid delivery systems targeting on-the-go professionals.
Netherlands
Contract manufacturing facilities in Randstad retrofit spray-drying lines for lipid-based delivery systems and nano-emulsion technologies. EU Green Deal biodegradable encapsulation material mandates reward early adopters with preferential retail placement. Eindhoven Region harbors specialized sports nutrition subscriptions targeting athlete segments with batch-certified purity standards.
Spain
Senior preventive health demand concentrates in Madrid and Catalonia for pharmacy-led cognitive support formulations. REACH chemical safety dossier requirements for novel encapsulation materials extend development cycles for mid-cap facilities. Barcelona's industrial cluster faces legacy ERP integration conflicts with batch traceability systems for compliant supply chains.
Europe Nutraceutical Market Competitive Landscape
Top-tier vendors anchor premium positioning through science-backed ingredient formulations, while mid-cap specialists compete on format innovation and regional pharmacy access. The vendor base stratifies across multinational nutrition conglomerates, specialized sports nutrition platforms, and contract manufacturing service providers. Three strategic archetypes dominate: direct-to-consumer subscription operators, clinically validated pharmaceutical-grade formulators, and private-label functional food suppliers. Competitive moves concentrate on M&A for microbiome-targeted ingredient pipelines and capacity expansion into solvent-free cold-press extraction.
Within the multinational nutrition tier, Nestlé S.A. and Danone S.A. exemplify diversified conglomerates spanning functional food and supplement portfolios. DSM-Firmenich occupies a position among science-backed ingredient specialists commanding premium positioning in recurring delivery models. These three entities represent contrasting strategic anchors: subscription platform scale, dairy-based functional food dominance, and pharmaceutical-grade formulation expertise.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Glanbia PLC |
| Herbalife Nutrition Ltd. |
| Amway Corp. |
| Arla Foods Group |
| Danone S.A. |
| Bayer AG |
| DSM-Firmenich |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Captive sourcing of Mediterranean and Balkan botanical extracts anchors premium positioning for European nutraceutical manufacturers while insulating price floors against commodity volatility. This backward integration into standardized herbal supply chains concentrates margin capture among German and French formulators with direct grower relationships, leaving contract-dependent competitors exposed to climate-driven input cost spikes.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for gummy-format dietary supplements as new manufacturing entrants absorb confectionery technology transfer costs. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated clinical formulations from generic botanical blends and private-label functional foods. Cost compression in economy-tier supplements is intensifying because REACH-compliant encapsulation material investments are being amortized across thinner volumes. Pharmacy-led distribution channels exhibit lowest price sensitivity due to clinician endorsement premiums, while mass-market supermarket buyers drive hardest bargain on promotional slotting.
Supply Chain Analysis
Standardized herbal extract supply rests on Mediterranean and Balkan sourcing clusters, with secondary concentration in German cold-press processing facilities. Key inputs include polyphenol-rich botanical matrices, phospholipid complex carriers, and fermentation-derived bioactive strains. Single-source vulnerability runs through climate-exposed Mediterranean growing regions susceptible to drought-induced harvest variability. Distribution runs through pharmacy networks in Germany, direct-to-consumer platforms in metropolitan clusters, and supermarket mass-market channels in France and Benelux.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between REACH-compliant manufacturing in Western Europe and emerging production capacity in Poland and Romania exploits regulatory cost differentials while maintaining EFSA market access. This positioning captures margin expansion as sustainability mandates tighten in core markets.
For Market Incumbents: To counter subscription-platform disintermediation, Nestlé S.A. and Danone S.A. should deepen direct-to-consumer channel control through biomarker-matched regimen algorithms, while DSM-Firmenich prioritizes strain-specific clinical trial investment to defend EFSA claim exclusivity against generic microbiome entrants. For New Entrants and Emerging Players: Direct-to-consumer platform routes offer lowest barrier to pharmacy-adjacent credibility, particularly in underpenetrated Romanian and Polish metropolitan clusters where aging demographics meet rising disposable incomes. White-space targets include pediatric gummy formulations via confectionery technology licensing and senior-focused liquid delivery systems bypassing pill rejection patterns. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap contract manufacturers with solvent-free extraction capabilities because EU Green Deal packaging mandates are forcing asset-retooling decisions that fragmented owners cannot finance independently. Target facilities with existing spray-drying line infrastructure in Randstad or North Rhine-Westphalia. Watch EFSA draft guidance finalization on microbiome claims as inflection indicator for probiotic portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extraction Scale-Up | Solvent-free botanical processing preserves heat-sensitive polyphenols for EFSA-validated premium positioning. |
| Biodegradable Encapsulation Transition | EU Green Deal compliance unlocks preferential Nordic retail placement and pharmacy network access. |
| Direct-to-Consumer Platform Launch | Algorithm-driven supplement regimens capture recurring revenue relationships in German metropolitan clusters. |
| Strain-Specific Clinical Trial Investment | Human intervention studies satisfy EFSA draft guidance on microbiome claims ahead of generic competitors. |
| Pharmacy Network Expansion | Italy and Spain pharmacy-led distribution concentrates senior preventive health demand for joint and cognitive formulations. |
Research Methodology
Direct dialogue with nutraceutical formulation scientists, pharmacy procurement managers, EFSA regulatory affairs specialists, and contract manufacturing executives grounded qualitative insights in operational reality. Secondary validation drew from EFSA novel food approval registers, REACH chemical safety dossiers, EU Green Deal implementation guidance, and customs trade data for standardized herbal extract flows. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with macro consumption pattern analysis.
Bottom-up modeling segmented volume and value across product type, distribution channel, end-user demographic, and geographic production cluster throughout the forecast period. CAGRs were derived from trend-line extrapolation of EFSA approval velocity, pharmacy network penetration rates, and subscription platform adoption curves. Industry-specific inputs incorporated fermentation-derived bioactive commercialization timelines and cold-press extraction capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for microbiome-targeted ingredient substantiation would alter the outlook if EFSA evidentiary requirements shift toward metagenomic endpoints rather than strain-specific clinical markers. Forecasts reflect assumptions about regulatory approval velocity, climate stability in Mediterranean growing regions, and digital health platform adoption curves. A small set of named triggers warrants ongoing watch: EFSA guidance finalization, REACH encapsulation material enforcement actions, and EU Green Deal packaging mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
Bone Meal Supplement Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Fatty Acid Supplements Market