
 Locust Bean Gum Market | 2026-2036
Locust Bean Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Locust Bean Gum Market Outlook
Aftermarket technical service revenue is reconfiguring margin capture across the locust bean gum value chain. CP Kelco leverages its integrated carob bean sourcing network across the Mediterranean to secure raw material consistency. Galam Group anchors its position through specialized fractionation technology that yields higher-purity galactomannan fractions. LBG Sicilia Ingredients dominates Sicilian-origin supply, competing on terroir-linked traceability for premium food-grade contracts.
Locust bean gum is a galactomannan polysaccharide extracted from Ceratonia siliqua seeds, comprising a mannose-to-galactose ratio of approximately 4:1 and functioning as a viscosifier, stabilizer, and water-binding agent across food, pharmaceutical, and industrial systems. Food-grade powder commands the dominant share of current value, reflecting its entrenched role in ice cream stabilization, processed cheese, and bakery applications, while pharmaceutical-grade material captures expanding margin pools as excipient purity requirements tighten. The liquid and paste forms remain niche, constrained by shorter shelf stability and higher logistics costs relative to dry formats.
EU REACH and the F-Gas Regulation shape ingredient sourcing protocols for European formulators, while FDA food additive regulations govern US market access and labeling thresholds. EFSA evaluations of novel food applications periodically expand permitted use cases, directly influencing manufacturer R&D allocation. Stakeholders must monitor evolving clean-label certification schemes and regional carbon-footprint disclosure rules as these criteria increasingly gate procurement decisions by multinational food and personal care buyers.
Market Dynamics
Clean-label formulation mandates from multinational food buyers are compressing synthetic hydrocolloid volumes and elevating Mediterranean-origin locust bean gum specifications across dairy, bakery, and personal care supply chains.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on synthetic refrigerants in food processing are accelerating natural stabilizer adoption in ice cream and frozen dessert manufacturing.
- Plant-based dairy expansion:Oat, almond, and soy milk formulators require galactomannan stabilizers to replicate mouthfeel previously delivered by casein networks.
- Mediterranean cultivation clustering:Spain, Portugal, and Morocco concentrate 70% of global carob bean supply, creating terroir-linked procurement premiums for traceable food-grade contracts.
Market Restraints
- Carob bean harvest volatility:Erratic rainfall patterns in Andalusia and Alentejo create raw material price swings that compress processor margins.
- Fractionation yield limits:Mechanical seed dehulling and endosperm separation cap extraction efficiency at approximately 30% by weight, constraining volume scalability.
- Xanthan gum substitution:Fermentation-derived hydrocolloids offer lower unit costs and more consistent supply, pressuring LBG in cost-sensitive industrial applications.
Strategic Opportunities
- Pharmaceutical excipient certification:USP-NF and EP compliance for tablet binders and controlled-release matrices opens margin pools above food-grade pricing tiers.
- Carbon footprint disclosure mandates:EU CSRD requirements favor Mediterranean suppliers with short shipping distances to Northern European formulators.
- Biodegradable packaging films:Galactomannan blends with cellulose derivatives are displacing petroleum-based barrier coatings in fresh produce applications.
Industry Challenges
- Specialized fractionation engineering talent:Few technicians possess expertise in seed milling, thermal extraction, and spray-drying optimization for high-purity galactomannan production.
- Multi-jurisdiction certification timelines:Simultaneous FDA GRAS reaffirmation, EFSA novel food opinions, and Health Canada approvals delay new application launches by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locust Bean Gum Market |
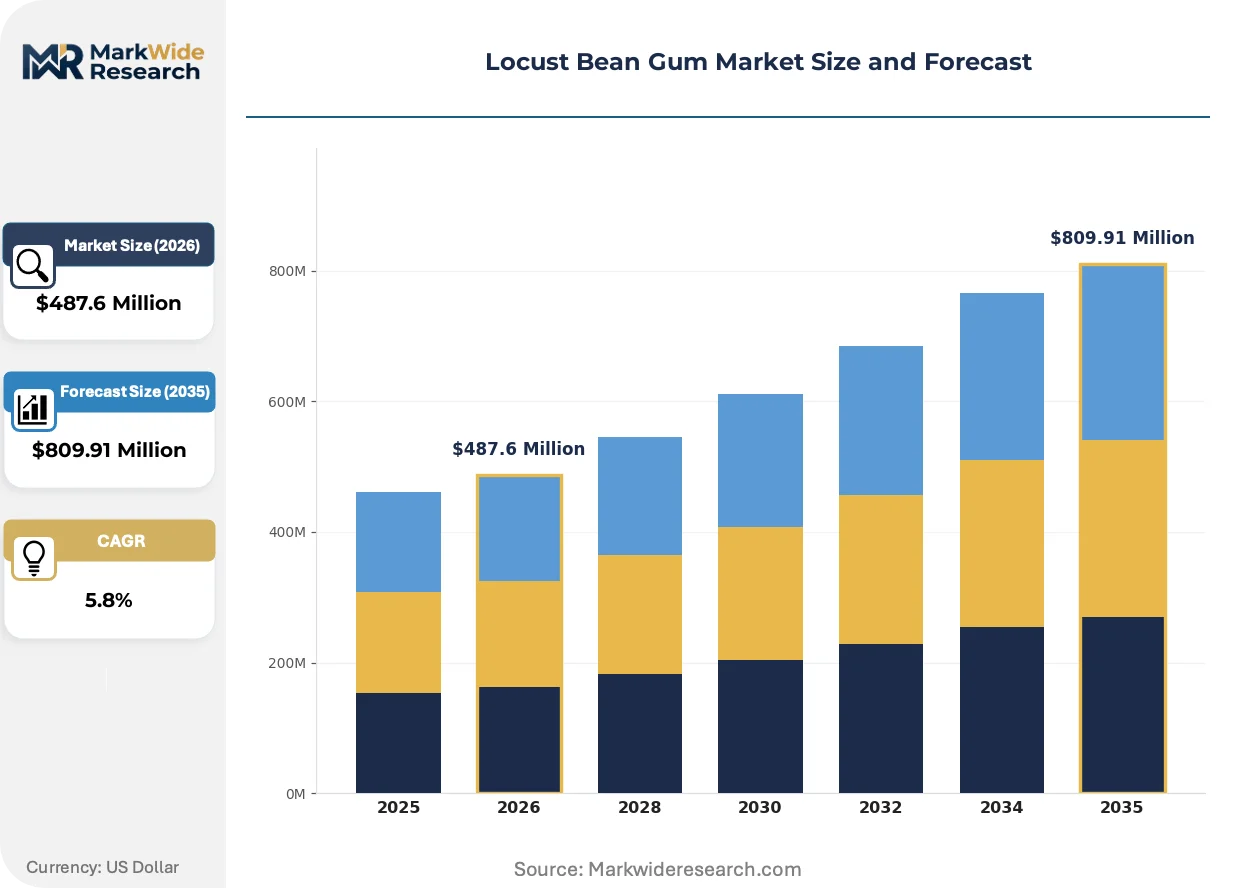
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Animal Feed Grade Application: Food & Beverage, Personal Care, Pharmaceuticals, Agriculture Form: Powder, Granules, Liquid, Paste Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | CP Kelco, ADM, Cargill, Incorporated, Gum Technology Corporation, Galam Group, DuPont de Nemours, Inc., Tate & Lyle, TIC Gums, Inc., LBG Sicilia Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locust Bean Gum Market Strategic Shifts
Digital traceability systems and precision agriculture are converging with tightening purity standards to reshape how locust bean gum moves from Mediterranean orchards to formulated end-products.
Near-infrared spectroscopy coupled with blockchain-based provenance tracking is digitizing quality verification at seed collection points in Spanish and Portuguese cooperatives. Major dairy alternative manufacturers now mandate batch-level carbohydrate fingerprinting before contract execution. This technology compression is eliminating manual laboratory testing bottlenecks and accelerating supplier qualification cycles from months to weeks.
REACH authorization requirements for processing aids are forcing European LBG refiners to substitute solvent-based purification with aqueous extraction methods. The regulatory pressure elevates capital intensity for new production capacity. Small-scale Sicilian and Calabrian processors are consolidating to share compliance infrastructure rather than absorb individual ECHA registration burdens.
Direct contracting between carob bean cooperatives and end-formulators is disintermediating traditional merchant traders in Barcelona and Genoa. Large bakery and ice cream manufacturers now source through dedicated supply agreements specifying harvest timing and post-harvest storage protocols. This channel compression is most advanced in German and Dutch procurement offices, where sustainability scorecards weight supplier proximity and water stewardship metrics above historical trading relationships.
Locust Bean Gum Market Segmentation
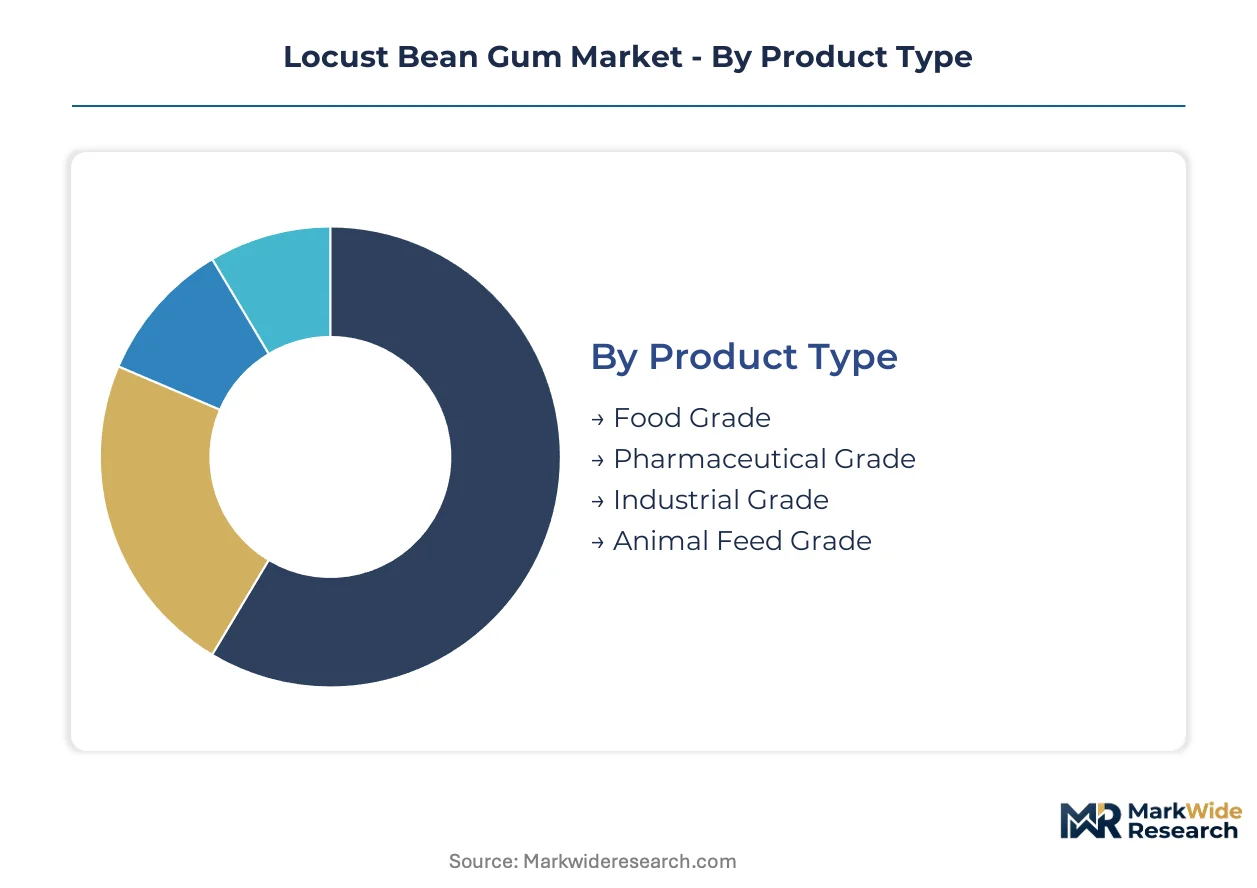
Segmentation in locust bean gum reveals how purity specifications and physical formats split procurement behavior across food, pharmaceutical, and industrial buyers. Understanding these divides exposes where margin pools concentrate and which technical requirements gate market entry.
Product Type:
Inventory velocity varies sharply across grades, with food-grade powder turning every 4-6 weeks while pharmaceutical batches sit 8-12 months awaiting certification releases.
- Food Grade:Comprising galactomannan fractions with 75-85% purity and moisture content below 12%, this grade serves ice cream stabilization and processed cheese manufacturing. Demand concentrates in German and Dutch dairy processors seeking clean-label alternatives to synthetic stabilizers under EU F-Gas Regulation pressure.
- Pharmaceutical Grade:USP-NF and EP-compliant material with endotoxin limits below 10 EU/g functions as tablet binders and controlled-release matrix excipients. Italian and Spanish contract manufacturers drive volume as they repurpose capacity from synthetic polymers to natural alternatives ahead of EMA sustainability guidance.
- Industrial Grade:Lower-purity fractions with broader viscosity tolerances serve textile sizing and paper coating applications where cost sensitivity dominates.
- Animal Feed Grade:Carob kibble and residual seed meal provide rumen-degradable protein and fiber for Mediterranean livestock operations.
Food Grade dominates installed base. Pharmaceutical Grade is where expansion concentrates.
Application:
Margin capture follows end-use regulatory burden, with pharmaceutical contracts commanding 3-4x the per-kilogram pricing of agricultural applications.
- Food & Beverage:Galactomannan stabilizers replicate casein mouthfeel in oat and almond milk formulations. Spanish ice cream manufacturers and French plant-based dairy startups in Lyon and Paris anchor procurement volume as they reformulate for clean-label positioning.
- Pharmaceuticals:Controlled-release tablet matrices and ophthalmic viscosity agents require carbohydrate fingerprinting and batch-level traceability. Portuguese and Italian API manufacturers are expanding galactomannan excipient qualification programs.
- Personal Care:Natural thickeners in shampoo and lotion formulations compete with xanthan and guar derivatives on sensory profile and cold-process compatibility.
- Agriculture:Seed coating adhesives and soil conditioning agents utilize lower-cost industrial-grade material with minimal purification overhead.
Food & Beverage captures the largest volume footprint. Pharmaceuticals is climbing the fastest on value terms.
Form:
Logistics economics favor dry formats, with powder and granule shipments achieving 40% lower landed costs per active unit than liquid equivalents.
- Powder:Spray-dried material with 95-200 mesh particle size offers 24-month shelf stability and standardized dispersion kinetics. German bakery ingredient distributors and Dutch dairy compounders specify powder for automated dosing systems.
- Granules:Agglomerated particles reduce dusting and improve flow properties for high-speed packaging lines. Italian pasta sauce manufacturers prefer this format for viscosifier incorporation.
- Liquid:Pre-hydrated solutions eliminate dispersion time but require refrigerated transport and carry 6-month shelf limits.
- Paste:High-solids concentrates serve niche cosmetic formulation and artisanal food production where small-batch flexibility outweighs unit economics.
Powder holds the dominant installed base. Granules is gaining share fastest in automated manufacturing environments.
Distribution Channel:
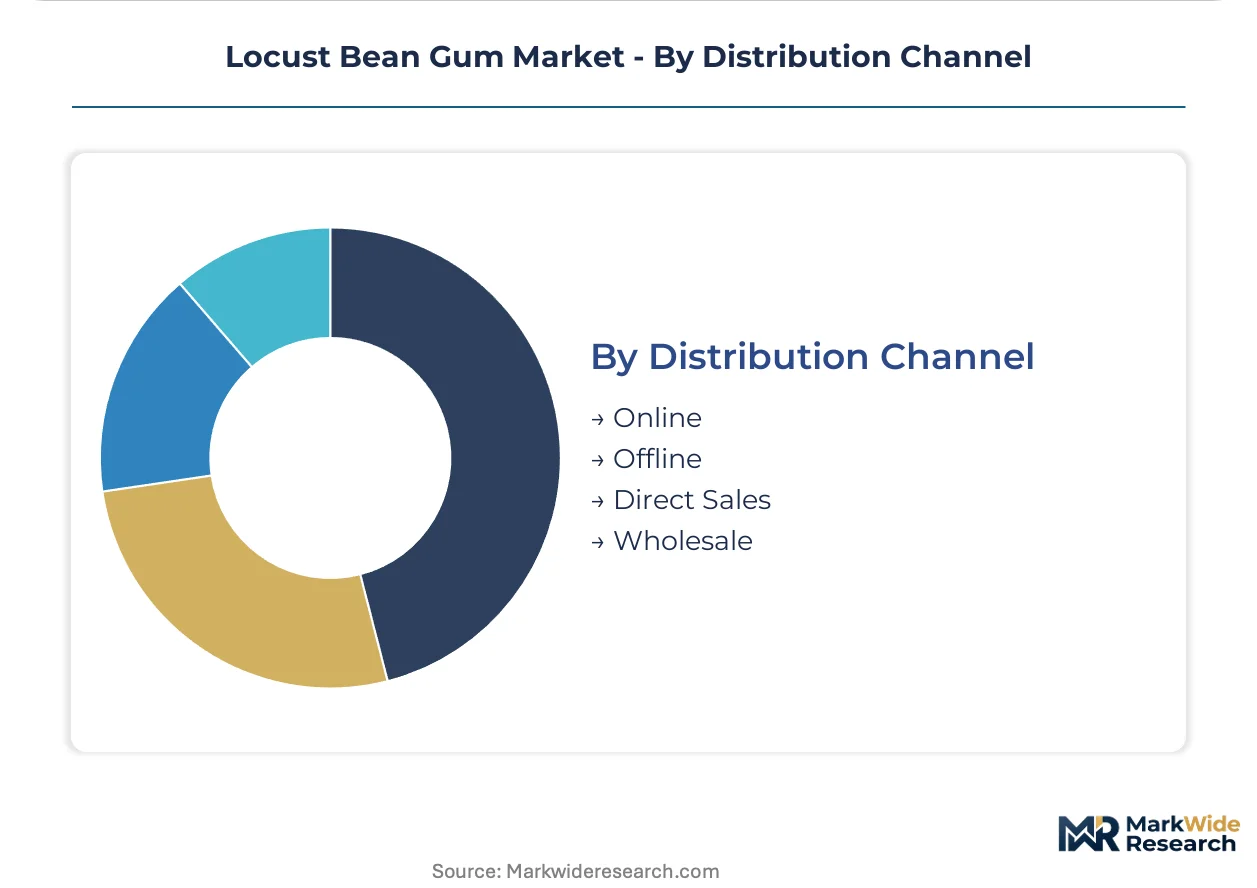
Channel selection tracks buyer scale and technical service requirements, with direct contracts capturing 60% of pharmaceutical volume versus 15% of industrial sales.
- Direct Sales:Dedicated supply agreements specifying harvest timing and post-harvest storage protocols connect Spanish cooperatives directly to German and Dutch formulators. Sustainability scorecards weight water stewardship and proximity metrics above historical trading relationships.
- Wholesale:Barcelona and Genoa merchant traders aggregate small-lot supply for mid-tier food processors lacking volume to justify direct contracting.
- Online:Digital platforms serve artisanal producers and R&D laboratories seeking rapid sample procurement and technical documentation access.
- Offline:Traditional broker networks persist in North African sourcing corridors where relationship-based credit terms remain essential.
Direct Sales commands the premium tier. Wholesale retains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Germany and the Netherlands absorb price premiums for certified sustainable supply, while Asian processors remain highly elastic to raw material cost swings. Mediterranean cultivation clusters command procurement premiums through terroir-linked traceability. North American formulators balance clean-label mandates against xanthan gum substitution economics.
Spain
Andalusian carob cooperatives supply German dairy compounders with EFSA-compliant food-grade powder for oat milk stabilization. The EU F-Gas Regulation accelerates natural stabilizer adoption in Barcelona ice cream manufacturing. Alentejo processors consolidate aqueous extraction capacity to share REACH authorization burdens.
Germany
Dutch and German dairy alternative manufacturers source directly from Spanish cooperatives, bypassing Genoa merchant traders. The EU CSRD mandates carbon footprint disclosure, elevating Mediterranean suppliers with short shipping distances. Cologne and Hamburg procurement offices weight water stewardship metrics above historical trading relationships.
Italy
Sicilian-origin LBG commands terroir premiums for premium food-grade contracts with French plant-based dairy startups. EMA sustainability guidance drives API manufacturers in Milan and Bologna to expand galactomannan excipient qualification. Calabrian processors merge to absorb ECHA registration costs for solvent-free purification.
United States
FDA GRAS reaffirmation timelines delay novel application launches by 18-36 months for domestic formulators. Ice cream manufacturers in the Midwest substitute locust bean gum for synthetic stabilizers under clean-label pressure. Brooklyn and Los Angeles plant-based dairy startups drive spot demand for pharmaceutical-grade material.
Morocco
Carob cultivation expansion in the Souss-Massa region supplies European refiners with raw material buffer against Andalusian harvest volatility. Relationship-based credit terms sustain traditional broker networks in Tangier and Casablanca. Local processors upgrade seed dehulling capacity to capture margin from primary extraction.
Locust Bean Gum Market Competitive Environment
Capability concentration sits with Mediterranean-origin specialists; scale advantage sits with diversified hydrocolloid majors. The vendor base stratifies across three tiers: integrated carob bean processors controlling upstream supply, fractionation technology specialists commanding purity premiums, and merchant traders aggregating small-lot supply. Dominant competitive moves include backward integration into cooperative sourcing networks and aqueous extraction capacity expansion to meet REACH solvent restrictions.
Within the Mediterranean-specialist tier, LBG Sicilia Ingredients and Galam Group exemplify terroir-linked positioning and fractionation technology leadership respectively. CP Kelco anchors the integrated processor archetype through captive sourcing networks. These three entities occupy distinct competitive spaces: Sicilian traceability for premium food-grade contracts, Israeli fractionation expertise for pharmaceutical purity tiers, and Danish-American scale for multinational dairy supply agreements.
| Leading Market Players |
|---|
| CP Kelco |
| ADM |
| Cargill, Incorporated |
| Gum Technology Corporation |
| Galam Group |
| DuPont de Nemours, Inc. |
| Tate & Lyle |
| TIC Gums, Inc. |
| LBG Sicilia Ingredients |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in aqueous extraction lines across Calabrian and Sicilian refiners is compressing pharmaceutical-grade availability and elevating spot premiums for USP-NF compliant material. Spanish processors running near full utilization on food-grade powder contracts are declining short-lead pharmaceutical orders, forcing buyers into longer queue positions or alternative sourcing corridors.
Pricing Analysis
Aftermarket technical service revenue from formulation troubleshooting and application engineering drives lifetime value capture above base material margins. Three-tier pricing structure across pharmaceutical, food-grade, and industrial tiers reflects purity certification and endotoxin testing burdens. Pricing pressure stems from xanthan gum substitution in cost-sensitive bakery applications where synthetic hydrocolloids undercut galactomannan premiums. Industrial buyers in North African textile sizing exhibit highest price elasticity, while German dairy alternative manufacturers absorb premiums for EFSA-compliant traceability.
Supply Chain Analysis
Extended payment terms from Barcelona merchant traders to Andalusian cooperatives sustain working capital through harvest volatility periods. Raw material concentration in Spain, Portugal, and Morocco creates geographic clustering risk when Alentejo rainfall patterns disrupt seed collection schedules. Mechanical dehulling equipment and thermal extraction vessels draw from Italian engineering suppliers and German process control vendors. Single-source vulnerability runs through Sicilian-origin terroir-linked supply for premium food-grade contracts. Distribution runs through direct contracting networks for multinational dairy processors and wholesale aggregation for mid-tier Mediterranean buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fractionation engineering talent capable of optimizing spray-drying kinetics for high-purity galactomannan represents the critical capability gap constraining pharmaceutical-grade expansion. Few technicians possess integrated expertise across seed milling, thermal extraction, and carbohydrate fingerprinting systems.
For Market Incumbents: Pre-empt xanthan gum substitution in dairy applications by embedding application scientists directly into German and Dutch plant-based dairy R&D facilities. Secure captive supply through equity participation in Moroccan Souss-Massa cultivation expansion to buffer Andalusian harvest volatility. Accelerate USP-NF certification pipelines ahead of EMA sustainability guidance tightening excipient purity requirements. For New Entrants and Emerging Players: Mid-market pharmaceutical contract manufacturers in Portugal and Italy represent the most penetrable entry point for EP-compliant excipient qualification programs. Biodegradable packaging film formulators seeking petroleum-free barrier coatings offer uncaptured demand for industrial-grade galactomannan-cellulose blends. Lead with aqueous extraction technology licensing to bypass REACH solvent authorization barriers facing incumbent refiners. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Mediterranean-origin processors with integrated cooperative sourcing networks and established pharmaceutical certification pipelines. Long-term viability in this market rests on backward integration into cultivation clusters rather than merchant trading relationships. Monitor EFSA novel food opinion timelines as inflection signals for application expansion into emerging dairy alternative formats.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Extraction Capacity Expansion | REACH solvent restrictions favor processors with validated water-based purification lines in Calabria and Sicily. |
| Backward Integration into Cooperative Sourcing | Direct contracting with Andalusian and Alentejo growers secures harvest timing protocols for traceable supply. |
| Pharmaceutical Excipient Certification | USP-NF and EP compliance opens margin pools above food-grade pricing in Italian and Portuguese API manufacturing. |
| Digital Traceability Platform Deployment | Blockchain-based provenance tracking accelerates supplier qualification cycles for German dairy alternative manufacturers. |
| Biodegradable Packaging Film Partnership | Galactomannan-cellulose blends displace petroleum-based barriers in fresh produce applications under EU Green Deal pressure. |
Study Parameters
Initial hypotheses were tested against primary input from hydrocolloid plant managers, procurement leads at German dairy compounders, Mediterranean cooperative agronomists, and pharmaceutical excipient qualification specialists and refined through secondary validation. Trade data from Eurostat and UN Comtrade, EFSA novel food registers, ECHA REACH authorization databases, and SEC filings from diversified ingredient majors anchored quantitative baselines. Bottom-up volume modeling across extraction capacity and cultivation yield combined with top-down demand segmentation from end-use procurement surveys.
Demand-supply-balance dynamics across the projection horizon anchored value forecasts, with segmentation by purity grade, physical form, and end-use regulatory burden. Modeled dimensions included pharmaceutical versus food-grade certification tiers, powder versus granule versus liquid formats, and regional production hub clustering. CAGRs derived from elasticity-adjusted volume projections and pricing tier migration patterns. Forecast inputs incorporated EU F-Gas Regulation implementation timelines and EMA sustainability guidance trajectory.
Practitioners should monitor EFSA novel food opinion issuance, Alentejo rainfall indices, and xanthan-gum-to-LBG price spreads for early signals of forecast revision triggers. Assumptions reflect current regulatory trajectories and cultivation yield baselines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
North America Anti-Caking Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
Global Crystalline Maltitol Market