
 South America Food Colorants Market | 2026-2036
South America Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Colorants Market Analytics
Multi-source procurement for natural extracts is decoupling from traditional single-source synthetic pigment agreements across South American food manufacturing. Chr. Hansen leverages its fermentation-based pigment portfolio to anchor supply relationships with regional dairy processors. Döhler competes through integrated botanical extraction capabilities that sustain cost advantages in beetroot-derived colorants. Sensient Technologies Corporation navigates formulation complexity by specializing in application-specific liquid color systems for tropical beverage climates.
Food colorants comprise pigments, dyes, and lakes dissolved or dispersed into edible matrices to impart, enhance, or restore visual appeal, with natural variants typically extracted via solvent, pressing, or fermentation methods yielding carotenoid, anthocyanin, or caramel compounds. Synthetic alternatives rely on azo and triarylmethane chemistries standardized for heat stability and pH tolerance across industrial processing conditions. Natural colorants now command premium positioning as clean-label demand shifts margin pools away from synthetic categories toward botanical extracts and caramel colors. Beverage applications lead volume absorption due to high-throughput bottling lines requiring consistent batch-to-batch hue stability in acidic formulations.
ANVISA governs colorant approval and maximum permissible limits under Brazilian food additive regulations, while Argentina's national food code enforces specific labeling disclosures for synthetic dye content that shapes reformulation priorities. Mercosur harmonization efforts continue streamlining cross-border compliance, though national divergence in natural extract definitions creates fragmented market access requirements. Stakeholders must monitor evolving clean-label certification thresholds and bioprospecting regulations affecting native botanical sourcing before committing to extraction facility investments.
Market Dynamics
Clean-label reformulation mandates across Mercosur are forcing Brazilian and Argentine processors to abandon synthetic azo dyes for botanical extracts and caramel compounds, restructuring procurement contracts and supplier qualification timelines throughout the regional food manufacturing base.
Growth Catalysts
- Mercosur Harmonization:Cross-border regulatory alignment reduces compliance duplication for multinational food processors operating in Brazil and Argentina, accelerating standardized natural colorant adoption.
- Beverage Industry Volume:High-throughput bottling lines in São Paulo and Buenos Aires demand consistent batch-to-batch hue stability, pulling concentrated investment in liquid anthocyanin systems.
- Fermentation-Derived Pigments:Industrial biotechnology platforms yield carotenoid and betalain compounds with superior heat stability compared to solvent-extracted alternatives, qualifying for clean-label positioning.
Market Restraints
- Botanical Raw Material Volatility:Beetroot and grape skin concentrate prices fluctuate with Argentine agricultural yields and seasonal harvest compression, squeezing processor margins.
- Extraction Equipment Concentration:Supercritical CO2 and membrane filtration systems for natural colorant production concentrate among German and Italian equipment suppliers, creating import dependency and currency exposure.
- pH Stability Limitations:Anthocyanin pigments degrade in neutral-to-alkaline formulations, restricting application in dairy and baked goods without encapsulation investments.
Strategic Opportunities
- Colombian Market Entry:Underdeveloped natural colorant adoption in Colombian processed foods creates first-mover positioning for suppliers establishing Bogotá distribution partnerships.
- Regenerative Agriculture Certification:Emerging clean-label premiums for regeneratively farmed botanical inputs allow suppliers to capture margin premiums beyond organic baselines.
- Direct-to-Processor Digital Platforms:B2B marketplaces for spot purchasing of standardized natural colorant lots disintermediate traditional distributor markups in mid-tier Brazilian confectionery.
Industry Challenges
- Application-Specific Formulation Expertise:Shortage of food technologists skilled in natural colorant stability optimization across acidic, neutral, and high-heat processing conditions delays product development cycles.
- Clean-Label Certification Complexity:Divergent definitions of "natural" across ANVISA, Argentina's national food code, and private retailer standards force redundant testing and documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Colorants Market |
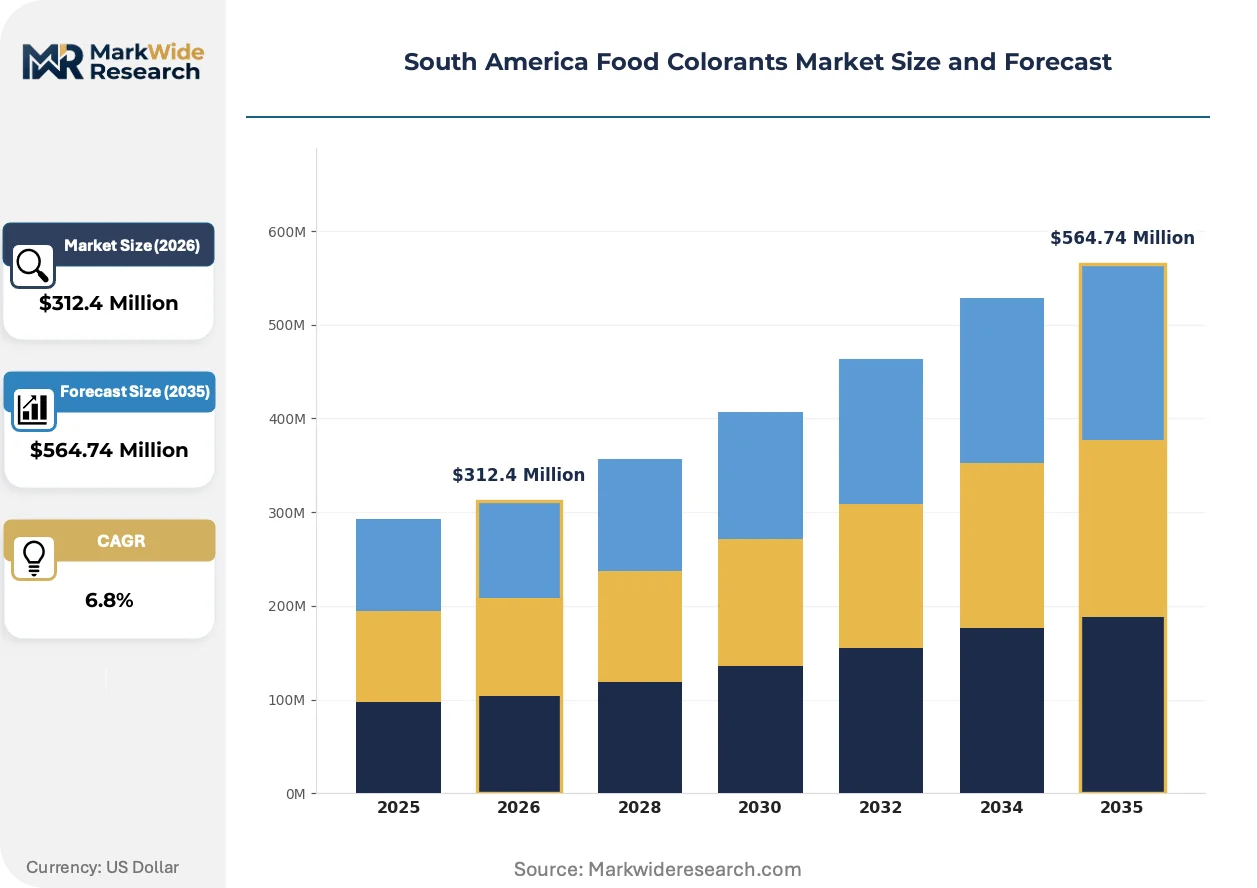
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Caramel Colors, Beetroot Extracts Application: Beverages, Bakery Products, Dairy Products, Confectionery Form: Liquid, Powder, Gel, Granular Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Döhler, Chr. Hansen, Givaudan, Archer Daniels Midland Company, Kerry Group, BASF SE, Sensient Technologies Corporation, Cargill, Koninklijke DSM N.V., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Colorants Market Evolving Landscape
Fermentation-based pigment production and advanced encapsulation systems are restructuring competitive advantage in South American natural colorants, separating biotechnology-capable suppliers from traditional botanical extractors.
Encapsulation technology using modified starch and gum arabic matrices is overtaking conventional liquid dispersion formats in tropical beverage applications. São Paulo-based juice processors adopt spray-dried anthocyanin beads to prevent degradation during ambient storage and distribution. This shift compresses shelf-life risk premiums and enables extended supply chain reach into northern Brazilian markets with limited cold chain infrastructure.
ANVISA's tightening maximum permissible limits for synthetic dyes in children's food categories is accelerating reformulation timelines across Brazilian confectionery and dairy segments. Processors face eighteen-month certification windows for novel natural colorant approvals, compressing product launch cycles. Argentine exporters to Brazil pre-qualify formulations against ANVISA standards to avoid border detention, creating regulatory compliance as a competitive differentiator.
Long-term supply agreements with fixed-price escalators are displacing spot market purchasing for beetroot-derived pigments among large-scale Argentine processors. Mid-tier Brazilian bakeries resist this transition, creating a bifurcated procurement landscape. Chilean ingredient distributors exploit this tension by offering blended contract-spot pricing structures to capture margin from price volatility exposure.
South America Food Colorants Market Segmentation
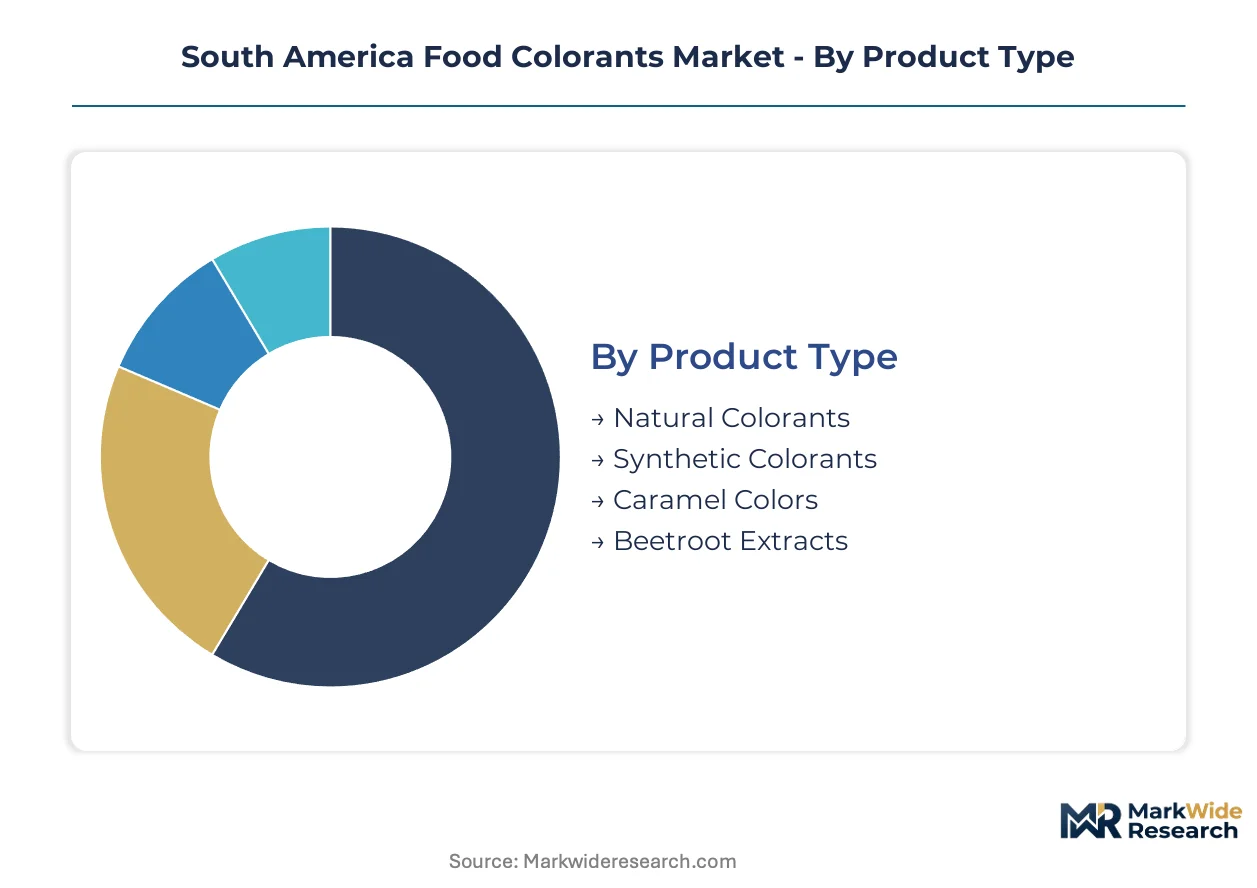
Segmentation in South American food colorants reveals divergent procurement patterns between multinational processors seeking regulatory harmonization and mid-tier manufacturers prioritizing cost flexibility. Understanding these splits enables suppliers to align formulation services, inventory models, and technical support investments with distinct buyer economics across the Mercosur trade zone.
Product Type:
Buyers in this category separate by reformulation urgency driven by regulatory pressure versus margin preservation priorities.
- Natural Colorants:Carotenoid, anthocyanin, and betalain extracts derived from botanical sources via solvent, pressing, or fermentation methods. Brazilian beverage manufacturers in São Paulo and Minas Gerais drive concentrated procurement amid ANVISA's tightening synthetic dye limits for children's food categories.
- Synthetic Colorants:Azo and triarylmethane chemistries standardized for heat stability and pH tolerance across industrial processing conditions. Argentine confectionery exporters retain limited synthetic volumes for price-sensitive export markets outside Mercosur where clean-label mandates remain weaker.
- Caramel Colors:Heat-treated carbohydrates producing Class I through IV color intensities for beverage and bakery applications. Clean-label positioning sustains premium pricing against synthetic alternatives in Brazilian dairy reformulations.
- Beetroot Extracts:Betalain concentrates from Beta vulgaris cultivation concentrated in Argentine agricultural regions. Long-term supply agreements with fixed-price escalators now displace spot purchasing among large-scale processors hedging against harvest volatility.
Volume sits with Natural Colorants; growth tilts toward Beetroot Extracts.
Application:
End-use concentration follows processing line throughput requirements and shelf-life stability demands across tropical distribution networks.
- Beverages:High-throughput bottling operations in São Paulo and Buenos Aires require consistent batch-to-batch hue stability in acidic formulations. Liquid anthocyanin systems absorb concentrated investment as processors adopt spray-dried encapsulation for ambient storage resilience.
- Bakery Products:Heat-stable carotenoid and caramel applications for bread, cake, and pastry matrices. Mid-tier Brazilian bakeries resist long-term contracting, creating procurement fragmentation exploited by Chilean distributors offering blended pricing structures.
- Dairy Products:Neutral pH formulations demanding encapsulation investments to prevent anthocyanin degradation. ANVISA approval windows compress product launch cycles for novel natural colorant entries.
- Confectionery:Argentine producers anchor regional demand for clean-label caramel colors and beetroot-derived pigments. Exporters pre-qualify formulations against ANVISA standards to avoid Brazilian border detention.
Beverages command the largest volume share; Confectionery exhibits the steepest expansion trajectory as export-oriented processors accelerate reformulation timelines.
Form:
Physical format selection tracks cold chain infrastructure maturity and storage duration requirements across northern versus southern Mercosur markets.
- Liquid:Standard dispersions for immediate incorporation into high-throughput beverage lines. Tropical climate storage limitations push processors toward encapsulated alternatives with extended ambient stability.
- Powder:Spray-dried and freeze-dried formats reducing shipping weight and enabling extended supply chain reach. São Paulo juice processors adopt spray-dried anthocyanin beads to penetrate northern Brazilian markets with limited refrigeration.
- Gel:Concentrated semi-solid systems for precise metering in artisanal and small-batch confectionery operations.
- Granular:Free-flowing formats for dry mix applications in bakery and instant beverage powders.
Liquid formats retain volume dominance; Powder is gaining share fastest through encapsulation technology adoption.
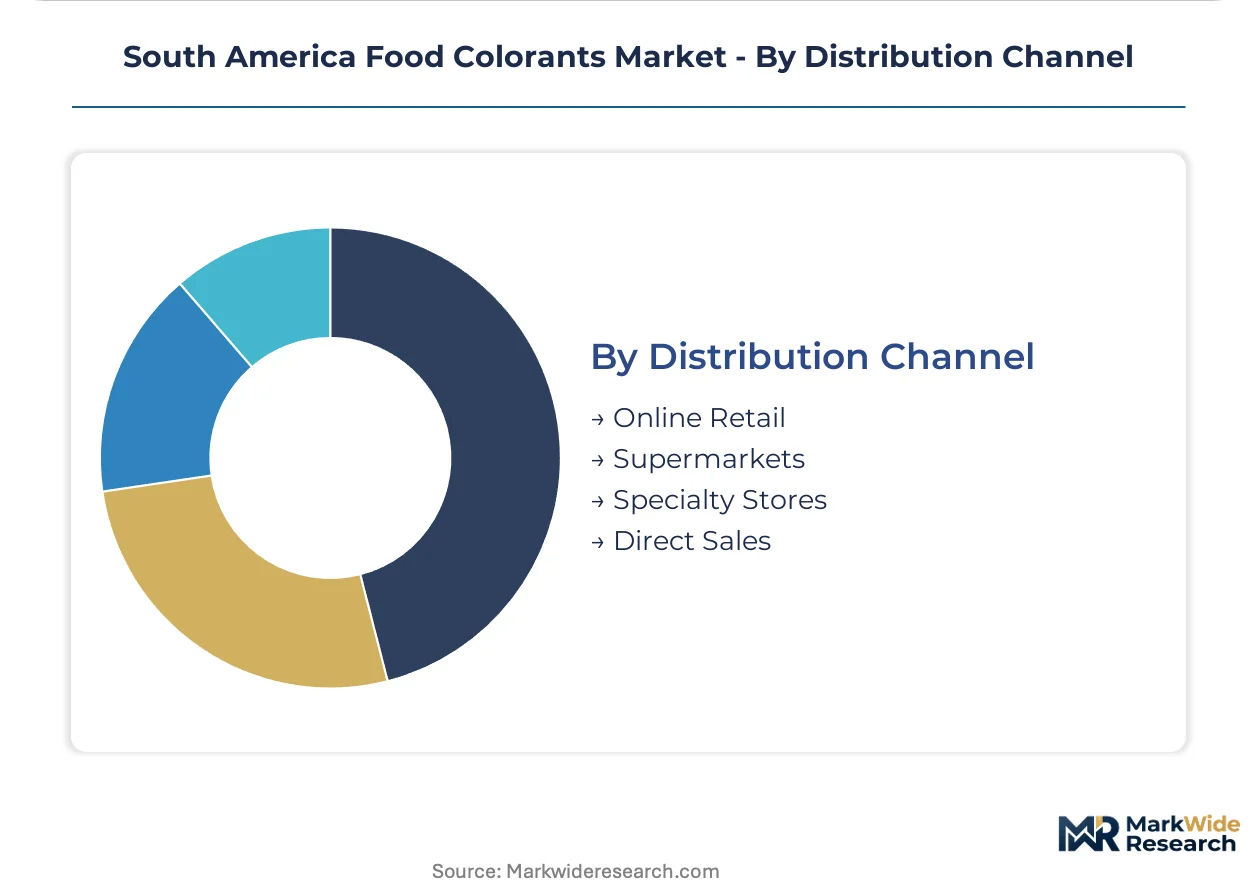
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and price transparency preferences across processor tiers.
- Direct Sales:Long-term supply agreements with dedicated technical support for multinational processors. Chr. Hansen and Döhler anchor regional dairy relationships through fermentation-based and integrated extraction capabilities respectively.
- Specialty Stores:Regional ingredient distributors serving mid-tier Brazilian confectionery with blended contract-spot pricing to capture margin from price volatility exposure.
- Online Retail:Emerging B2B marketplaces for spot purchasing of standardized natural colorant lots disintermediating traditional distributor markups.
- Supermarkets:Limited penetration for industrial-scale colorant procurement; primarily serves artisanal and small commercial bakery segments.
Direct Sales captures the highest volume; Online Retail climbs the fastest as digital procurement platforms expand spot market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beta vulgaris cultivation in Argentine agricultural regions anchors regional beetroot-derived pigment supply chains, while São Paulo's beverage manufacturing corridor absorbs concentrated natural colorant procurement amid tightening regulatory standards.
Brazil
São Paulo and Minas Gerais processors drive anthocyanin and caramel color demand through high-throughput bottling operations. ANVISA's tightening maximum permissible limits for synthetic dyes in children's food categories compresses eighteen-month approval windows for novel natural entries. Northern Brazilian markets with limited cold chain infrastructure adopt spray-dried encapsulated formats from southern processing clusters.
Argentina
Confectionery exporters anchor regional demand for clean-label caramel colors and beetroot-derived pigments, with Buenos Aires processors pre-qualifying formulations against ANVISA standards. The national food code enforces specific labeling disclosures for synthetic dye content that shapes reformulation priorities. Mendoza and Córdoba agricultural zones supply concentrated beetroot cultivation for betalain extraction.
Chile
Ingredient distributors exploit procurement fragmentation between long-term contracting multinationals and spot-market mid-tier Brazilian bakeries through blended pricing structures. The country's food safety authority aligns with Mercosur harmonization efforts while maintaining distinct natural extract definitions. Santiago-based distributors capture margin from Argentine harvest volatility exposure.
Colombia
Underdeveloped natural colorant adoption in processed foods creates first-mover positioning for suppliers establishing Bogotá distribution partnerships. The national food and drug surveillance institute progresses toward Mercosur regulatory alignment. Caribbean coastal beverage processors represent untapped volume potential for liquid anthocyanin systems.
South America Food Colorants Market Competitive Landscape
Global majors compete with regional champions across formulation services and extraction capabilities, producing a tiered structure where biotechnology specialists, integrated botanical processors, and application-specific formulators occupy distinct competitive positions. Market concentration favors players with fermentation platforms and supercritical extraction assets. Strategic archetypes include fermentation-derived pigment specialists, vertically integrated botanical extractors, and climate-adaptive formulation engineers. Dominant competitive moves encompass long-term supply agreements with fixed-price escalators and encapsulation technology licensing partnerships.
Within the fermentation-specialist tier, Chr. Hansen anchors supply relationships through carotenoid and betalain biotechnology platforms, while Döhler exemplifies integrated botanical extraction capabilities sustaining cost advantages in beetroot-derived colorants. Sensient Technologies Corporation occupies a position as application-specific liquid color system specialists for tropical beverage climates. These three players represent the dominant competitive archetypes restructuring procurement patterns across Brazilian and Argentine processing corridors.
| Leading Market Players |
|---|
| Döhler |
| Chr. Hansen |
| Givaudan |
| Archer Daniels Midland Company |
| Kerry Group |
| BASF SE |
| Sensient Technologies Corporation |
| Cargill |
| Koninklijke DSM N.V. |
| Others |
Value Network & Pricing Analysis
Fermentation-based pigment production platforms are compressing cost curves for carotenoid and betalain compounds while simultaneously concentrating supply relationships among biotechnology-capable suppliers in Brazil and Argentina. This technological transition simultaneously reshapes procurement economics and supplier qualification timelines as processors abandon solvent-extracted alternatives for heat-stable fermentation outputs.
Pricing Analysis
Technical service bundling separates contract structures in South American food colorants, with multinational processors paying premiums for dedicated formulation support while mid-tier buyers accept unbundled spot pricing. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with ANVISA-compliant natural extracts commanding substantial premiums over uncertified botanical inputs. Cost compression in synthetic alternatives is intensifying because Argentine confectionery exporters retain limited azo dye volumes for price-sensitive non-Mercosur markets. Mid-tier Brazilian bakeries exhibit highest price sensitivity, resisting long-term contracting and accepting volatility exposure through Chilean distributor spot markets.
Supply Chain Analysis
Clean-label certification gating restricts supplier qualification to processors demonstrating ANVISA-compliant extraction protocols and traceable botanical sourcing documentation. Geographic concentration centers on Argentina for beetroot cultivation, Brazil for fermentation platform deployment, and Chile for distribution arbitrage. Raw material dependencies rest on Beta vulgaris harvests, fermentation feedstocks, and imported German supercritical CO2 equipment. Single-source vulnerability runs through Italian and German extraction machinery suppliers, creating currency exposure and import dependency. Distribution runs through direct sales relationships for multinationals, specialty distributors for mid-tier processors, and emerging B2B platforms for spot market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American food colorants function as a cost-of-compliance market where ANVISA's tightening synthetic dye limits for children's food categories erect regulatory moats protecting qualified natural colorant suppliers from unqualified competitors.
For Market Incumbents: Cement supply relationships through long-term agreements with fixed-price escalators for beetroot-derived pigments, locking in Argentine agricultural capacity before harvest volatility intensifies. Anchor technical service capabilities in São Paulo and Buenos Aires processing corridors to defend against emerging biotechnology specialists offering fermentation-derived alternatives with superior heat stability profiles. For New Entrants and Emerging Players: Mid-tier Brazilian bakeries resisting long-term contracting represent the most penetrable buyer archetype, with procurement fragmentation creating entry points for digital B2B platforms offering blended contract-spot pricing structures. Colombian processed food manufacturers offer geographic white-space with underdeveloped natural colorant adoption, accessible through Bogotá distribution partnerships and pre-emptive ANVISA-aligned formulation qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in fermentation-platform specialists and vertically integrated botanical extractors with captive Argentine agricultural assets. Long-term viability frames around biotechnology capability differentiation and regulatory compliance infrastructure rather than commodity extraction scale. Watch ANVISA approval velocity for novel natural colorant entries as the critical inflection signal indicating competitive window compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Fixed-price escalators for beetroot extracts hedge Argentine harvest volatility for processors. |
| Backward Integration | Captive Beta vulgaris cultivation in Mendoza secures betalain supply chains against spot market exposure. |
| Encapsulation Technology Licensing | Spray-dried anthocyanin beads enable São Paulo juice processors to penetrate northern Brazilian markets. |
| Regulatory Pre-qualification | ANVISA-aligned formulation certification prevents border detention for Argentine confectionery exporters. |
| Digital Platform Launch | B2B spot purchasing disintermediates Chilean distributor markups in mid-tier Brazilian procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, triangulated against primary interviews with Brazilian beverage formulation managers, Argentine confectionery procurement leads, Chilean ingredient distribution channel heads, and ANVISA regulatory affairs specialists. Secondary sources encompassed ANVISA additive approval databases, Argentine national food code amendments, Mercosur harmonization directives, and South American customs import records for extraction equipment. Bottom-up volume estimates from processor procurement patterns reconciled with top-down market sizing from trade flow analysis.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement surveys generated consistent volume and value outputs across the projection horizon. Segmentation modeling tracked product type, application, physical form, and distribution channel dimensions alongside regulatory compliance tier as an industry-specific stratifier. CAGRs derived from fitted growth curves applied to disclosed capacity expansions and reformulation timelines, with fermentation platform adoption rates and encapsulation technology penetration serving as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA approval velocity for novel natural extracts, Argentine agricultural yield volatility, and Mercosur regulatory harmonization progress. Forecasts reflect documented assumptions about biotechnology adoption curves and clean-label certification threshold evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Global Oleate Esters Market