
 Carob Bean Gum Market | 2026-2036
Carob Bean Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Carob Bean Gum Market Analysis
Plant-based dairy alternatives is hardening as the dominant demand vertical for carob bean gum, displacing traditional stabilizer blends in oat and almond milk formulations. CP Kelco leverages its hydrocolloid R&D intensity to supply customized viscosity solutions for beverage manufacturers. Kerry Group anchors European distribution through its Ingredient Technologies division, while Cargill competes on backward integration into Iberian carob orchards.
Carob bean gum, extracted from Ceratonia siliqua seeds, functions as a galactomannan polysaccharide with mannose-to-galactose ratios near 4:1, delivering pseudoplastic thickening and water-binding across pH ranges of 3-11. The powder segment dominates volume due to its dispersion efficiency in industrial batching, while liquid formulations represent the fastest-growing category as ready-to-use systems reduce plant sanitation cycles. Pharmaceutical applications command premium margin pools where USP-grade certification separates qualified from commodity suppliers.
FDA GRAS self-affirmation pathways govern US market entry, while EFSA's novel food catalog updates determine European compliance thresholds for emerging extraction methods. REACH registration requirements for imported gum derivatives constrain smaller traders lacking toxicology dossiers. Stakeholders must monitor EFSA's pending re-evaluations of locust bean gum specifications, as revised purity standards could disqualify legacy processing equipment and reshape supplier qualification timelines.
Market Dynamics
Clean-label procurement mandates from European and North American food manufacturers are compressing supplier qualification timelines, forcing processors to demonstrate seed-to-powder traceability before contract execution.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined approvals for mechanically extracted carob bean gum variants are accelerating European market entry for Iberian processors upgrading legacy milling infrastructure.
- Plant-Based Dairy Formulation:Oat and almond milk manufacturers are specifying carob bean gum as the primary stabilizer, displacing locust bean gum and xanthan blends in neutral-pH beverage systems.
- Mediterranean Cultivation Clusters:Spain and Portugal's established Ceratonia siliqua orchards provide supply reliability that Turkish and Moroccan expansion regions have yet to match.
Market Restraints
- Seed Supply Concentration:Over 70% of raw carob seed processing capacity sits within 200 kilometers of Valencia and Lisbon, creating geographic vulnerability to drought and port congestion.
- Galactomannan Substitution:Guar gum from Indian Rajasthan cultivation zones competes on price in lower-specification applications where viscosity tolerance bands exceed 15%.
- REACH Registration Burden:Toxicology dossier requirements for imported gum derivatives exclude smaller traders lacking six-figure compliance budgets.
Strategic Opportunities
- Pharmaceutical-Grade Certification:USP-grade carob bean gum for tablet binding commands 3-4x commodity pricing, with only three European processors currently qualified.
- Liquid Delivery Systems:Ready-to-use hydrated gum slurries reduce beverage plant sanitation cycles, opening contract manufacturing partnerships with mid-sized dairy alternatives producers.
- EU Green Deal Incentives:Carbon footprint verification for Mediterranean-sourced hydrocolloids qualifies processors for preferential procurement from sustainability-mandated food manufacturers.
Industry Challenges
- Specialized Extraction Engineering:Solvent-free mechanical processing equipment requires process engineers trained in galactomannan rheology, a skill set concentrated among retired technicians from legacy locust bean gum operations.
- Cross-Contamination Protocols:Facilities producing both commodity food-grade and pharmaceutical-grade gum must maintain segregated air-handling systems, doubling capital intensity for dual-certification ambitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carob Bean Gum Market |
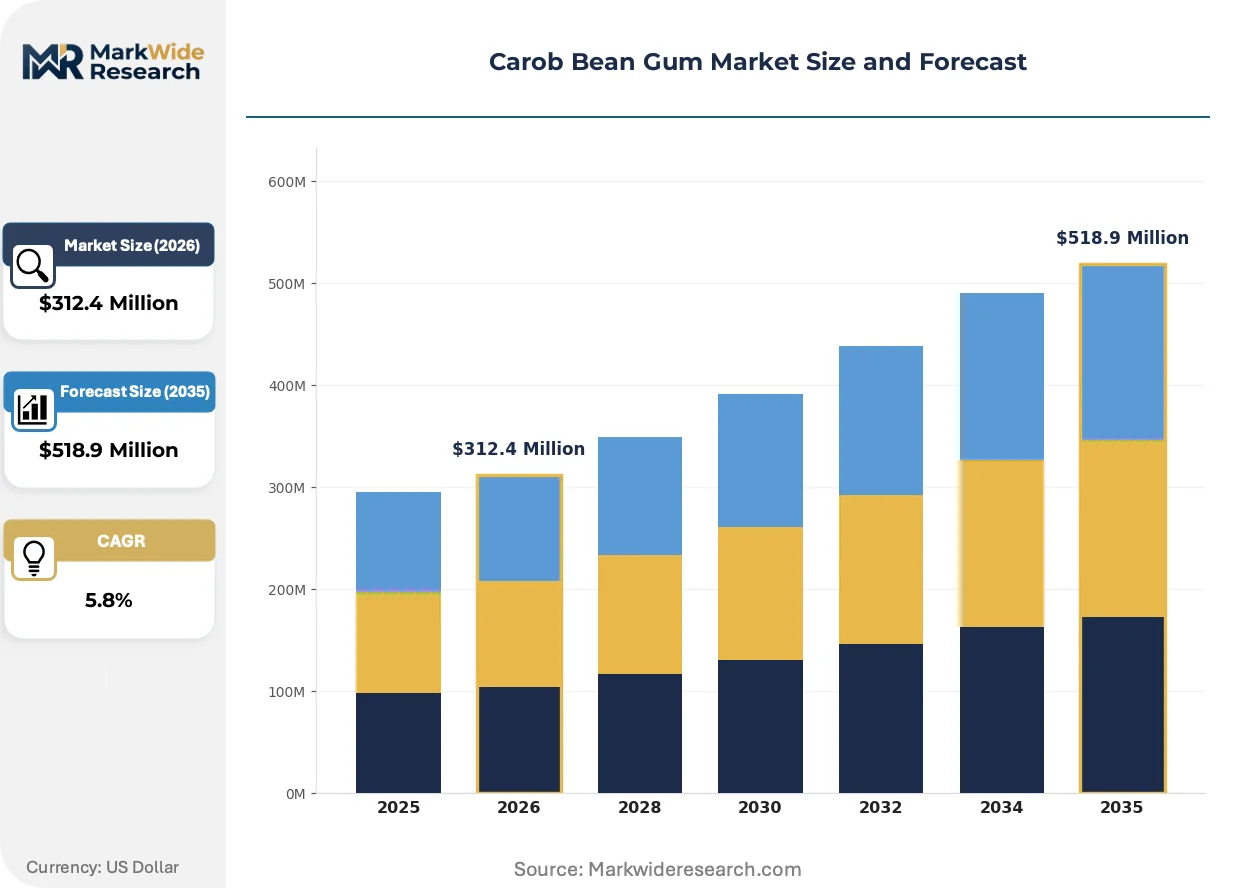
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Flakes, Liquid Application: Food Industry, Cosmetics, Pharmaceuticals, Textiles End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Textile Producers Packaging Type: Bags, Drums, Boxes, Pallets |
| Companies Covered | CP Kelco, Fiberstar Inc., Kerry Group, G Araouzos and Son, TIC Gums Incorporation, Cargill, LBG Sicilia Ingredients, Gum Technology Corporation, FMC Specialty Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carob Bean Gum Market Emerging Trajectories
Extraction technology convergence and regulatory recalibration are compressing the gap between commodity food-grade supply and premium pharmaceutical-grade output, reshaping processor investment priorities.
Enzyme-assisted mechanical extraction is unifying yield efficiency with clean-label positioning. Spanish processors deploying cellulase pre-treatment report 12-18% higher galactomannan recovery without solvent residues. Beverage manufacturers in Germany and France are qualifying these outputs ahead of contract renewals, collapsing the traditional two-tier supplier structure into a single qualified tier.
EFSA's pending re-evaluation of locust bean gum specifications is forcing parallel scrutiny of carob bean gum purity standards. Revised heavy metal thresholds and protein content limits will disqualify legacy Spanish processing equipment installed before 2015. Portuguese processors with upgraded membrane filtration systems are pre-qualifying against anticipated 2027 standards, securing preferential supplier status with pan-European ingredient distributors.
Ingredient buyers are consolidating hydrocolloid procurement around single-source accountability contracts. Mid-sized plant-based dairy manufacturers in the Netherlands and Belgium are terminating multi-supplier stabilizer blends, specifying carob bean gum as the sole hydrocolloid with viscosity guarantees. This specification tightening is visible most acutely in private-label oat milk production, where batch-to-batch consistency failures trigger automatic contract termination clauses.
Carob Bean Gum Market Segmentation
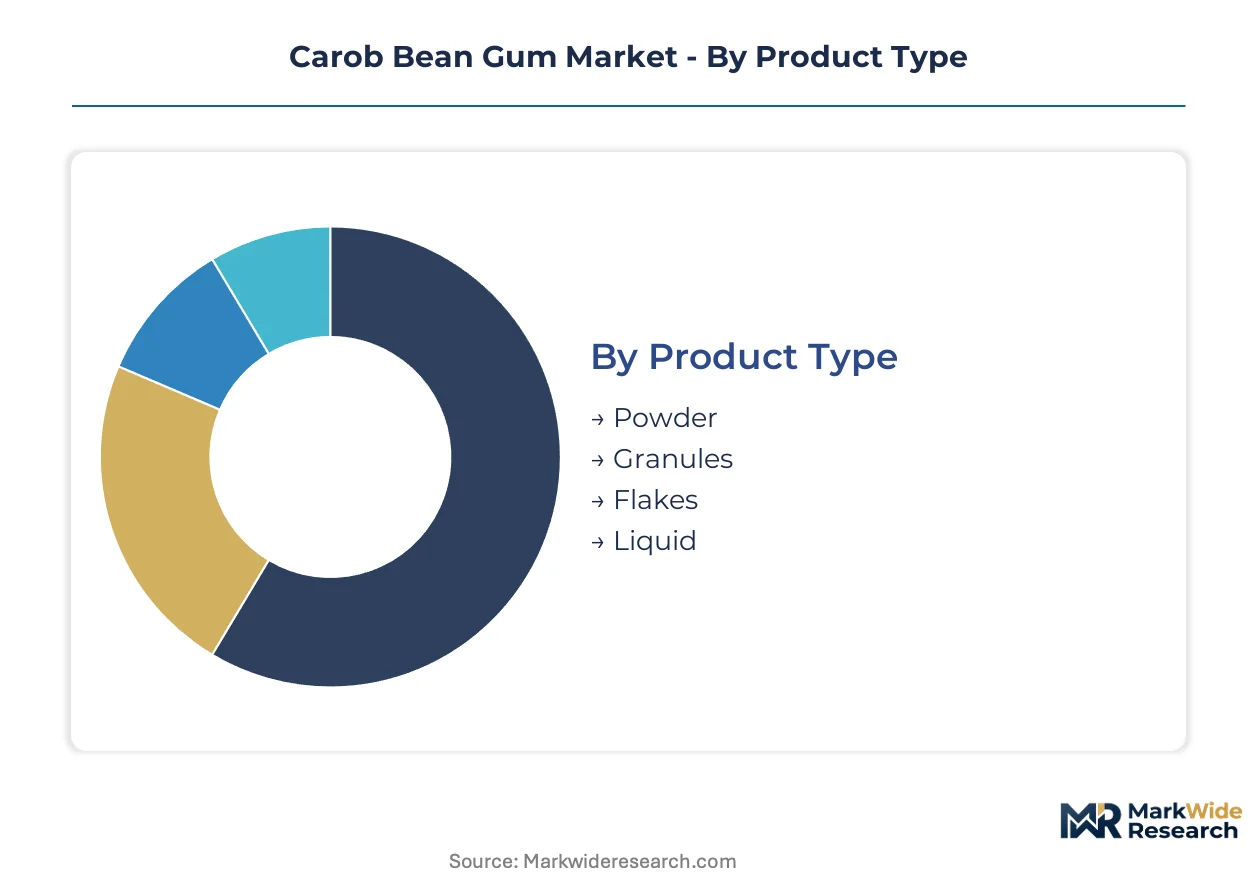
Carob bean gum's functional versatility across viscosity ranges and pH stability creates distinct procurement patterns by physical form and end-use specification. Segmentation reveals where technical performance separates commodity supply from premium positioning.
Product Type:
Physical form determines hydration kinetics, dispersion behavior, and handling economics across industrial batching systems.
- Powder:Finely milled particles below 150 microns enable rapid hydration in ambient-temperature mixing. Beverage manufacturers in Germany and the Netherlands specify powder grades for oat milk stabilizer systems where batch cycle time drives throughput economics.
- Liquid:Pre-hydrated slurries eliminate dust exposure and reduce plant sanitation cycles. Mid-sized dairy alternatives producers in Belgium are qualifying ready-to-use liquid systems to compress changeover downtime between production runs.
- Granules:Coarse particles suit controlled-release applications in bakery matrices where delayed hydration prevents premature water binding during dough development.
- Flakes:Intermediate surface area supports gradual dissolution in cosmetic emulsions requiring extended processing windows.
Powder leads on scale; liquid leads on momentum.
Application:
Regulatory certification thresholds and performance specifications fragment demand across compliance tiers.
- Food Industry:Neutral-pH stabilizer demand from plant-based dairy manufacturers concentrates procurement volumes. EFSA's novel food catalog compliance separates qualified European suppliers from import-dependent traders lacking toxicology dossiers.
- Pharmaceuticals:USP-grade certification for tablet binding commands premium positioning. Only three European processors currently maintain qualified pharmaceutical-grade production lines with segregated air-handling systems.
- Cosmetics:Emulsion stability requirements in skin-care formulations drive specification of low-protein grades to minimize microbial contamination risk.
- Textiles:Sizing applications in yarn processing utilize lower-viscosity grades where price tolerance accommodates commodity procurement.
Food Industry leads on scale; Pharmaceuticals leads on momentum.
End User:
Procurement sophistication varies by industry maturity and regulatory exposure.
- Food Manufacturers:Clean-label mandates from European and North American buyers compress supplier qualification timelines. Seed-to-powder traceability documentation now precedes contract execution for oat and almond milk producers.
- Pharmaceutical Companies:Dual-certification requirements for food-grade and pharmaceutical-grade supply create captive relationships with upgraded Portuguese processors.
- Cosmetic Brands:Sustainability verification under EU Green Deal frameworks steers procurement toward Mediterranean-sourced hydrocolloids with carbon footprint documentation.
- Textile Producers:Price-sensitive procurement accepts viscosity tolerance bands exceeding 15%, opening substitution risk from Indian guar gum.
Food Manufacturers leads on scale; Pharmaceutical Companies leads on momentum.
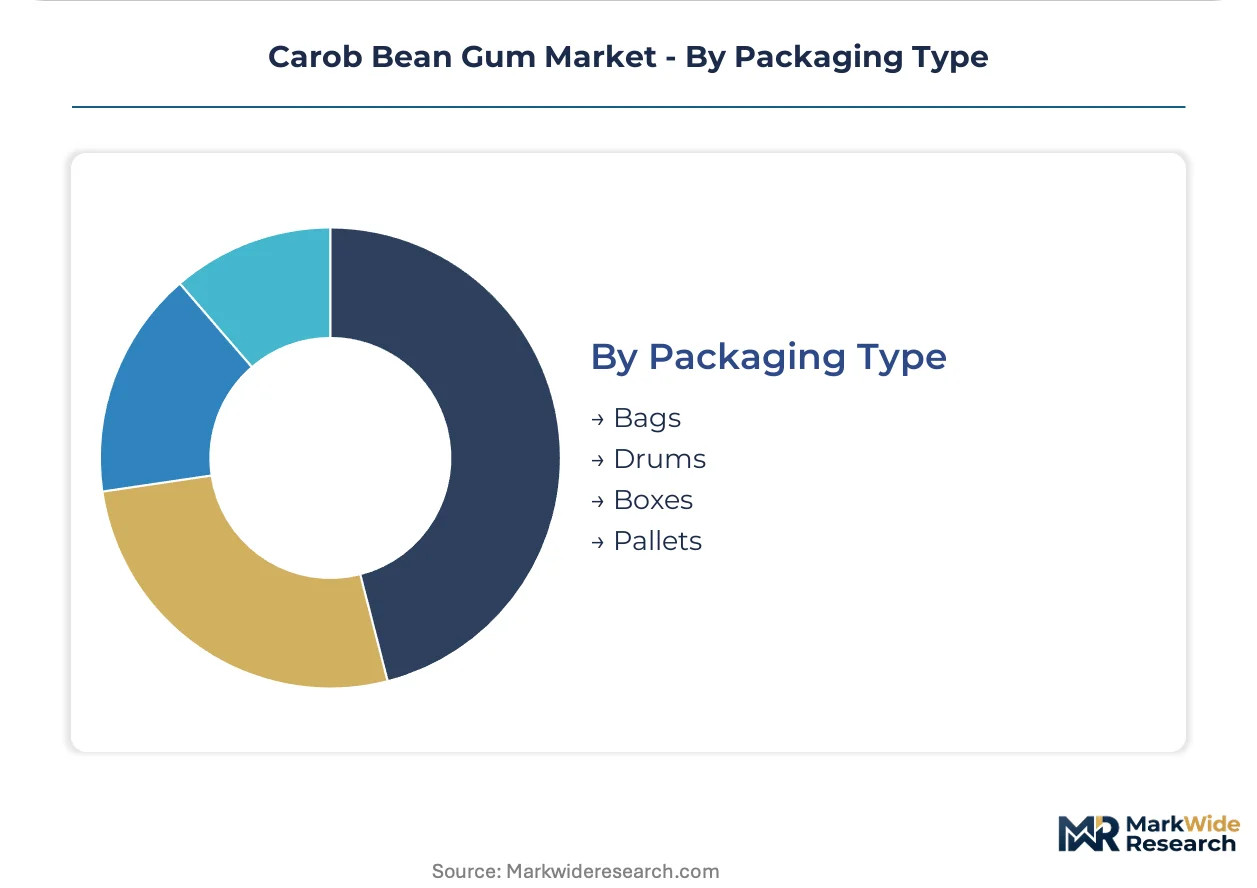
Packaging Type:
Logistics configuration aligns with customer scale and handling infrastructure.
- Bags:25-kilogram multiwall paper sacks serve mid-sized beverage plants with manual batching operations.
- Drums:Fiber drums with polyethylene liners protect powder grades from moisture ingress during extended storage.
- Boxes:Corrugated bulk bins facilitate automated handling in high-throughput dairy alternatives facilities.
- Pallets:Unitized loads reduce per-kilogram handling costs for pharmaceutical compounders with integrated material flow systems.
Bags leads on scale; Pallets leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Valencia-Lisbon corridor anchors Mediterranean carob bean gum processing capacity, with Iberian orchards supplying over 70 percent of European hydrocolloid demand. Clean-label procurement mandates from German and Dutch beverage manufacturers are compressing supplier qualification timelines across the continent. Regulatory divergence between FDA self-affirmation pathways and EFSA novel food evaluations is fragmenting transatlantic market entry strategies.
Spain
Plant-based dairy manufacturers in Germany and France are qualifying Spanish carob bean gum outputs for oat milk stabilizer systems. EFSA's pending re-evaluation of locust bean gum specifications is forcing parallel scrutiny of Spanish carob processors with legacy equipment installed before 2015. The Valencia processing cluster is upgrading membrane filtration infrastructure to pre-qualify against anticipated 2027 purity standards.
Portugal
Pharmaceutical-grade certification requirements are concentrating demand around Portuguese processors with segregated air-handling systems. REACH registration compliance for imported gum derivatives creates regulatory moats that Lisbon-area facilities exploit against smaller traders. The Algarve cultivation zone is expanding Ceratonia siliqua orchard coverage to secure seed supply reliability for upgraded extraction plants.
Germany
Beverage manufacturers in Bavaria and North Rhine-Westphalia are terminating multi-supplier stabilizer blends in favor of single-source carob bean gum accountability contracts. The EU Green Deal carbon footprint verification framework steers procurement toward Mediterranean-sourced hydrocolloids with documented sustainability credentials. Frankfurt-area ingredient distributors are consolidating hydrocolloid procurement around pre-qualified Iberian processors.
United States
Oat and almond milk producers in California and the Pacific Northwest are specifying carob bean gum as the primary stabilizer in neutral-pH beverage formulations. FDA GRAS self-affirmation pathways govern market entry, with USP-grade certification separating qualified pharmaceutical suppliers from commodity traders. Midwestern dairy alternatives facilities are qualifying ready-to-use liquid gum slurries to compress plant sanitation cycles.
Netherlands
Private-label oat milk manufacturers in the Randstad region are enforcing automatic contract termination clauses for batch-to-batch consistency failures. EFSA novel food catalog compliance requirements exclude import-dependent traders lacking toxicology dossiers from European procurement shortlists. Rotterdam logistics hubs are optimizing bulk handling infrastructure for palletized pharmaceutical-grade gum shipments.
Carob Bean Gum Market Vendor Landscape
Backward integration into Iberian carob orchards dominates the current landscape, with processors securing captive seed supply to defend margin positions against Indian guar gum substitution. The vendor base stratifies across three tiers: multinational hydrocolloid specialists with integrated R&D functions, regional Mediterranean processors with cultivation-linked supply chains, and commodity traders dependent on spot market sourcing. Two strategic archetypes define competitive positioning: vertically integrated orchard-to-powder operators and formulation-focused ingredient technology divisions of larger food conglomerates. Capacity expansion in Portuguese pharmaceutical-grade lines and strategic partnerships for liquid delivery system distribution represent the dominant competitive moves.
Within the integrated hydrocolloid specialist tier, CP Kelco and Cargill exemplify divergent approaches to supply chain control. CP Kelco leverages its galactomannan R&D intensity to supply customized viscosity solutions for beverage manufacturers, occupying a position anchored in technical service differentiation. Cargill competes through upstream control over Iberian carob orchards, representing the backward integration archetype that secures seed supply reliability. Kerry Group sits within the ingredient technology division model, anchoring European distribution networks through its Ingredient Technologies division without direct orchard ownership. These three patterns illustrate how competitive positioning in carob bean gum tracks supply chain configuration rather than product differentiation alone.
| Leading Market Players |
|---|
| CP Kelco |
| Fiberstar Inc. |
| Kerry Group |
| G Araouzos and Son |
| TIC Gums Incorporation |
| Cargill |
| LBG Sicilia Ingredients |
| Gum Technology Corporation |
| FMC Specialty Chemicals |
| Others |
Supply Flow & Price Mechanics
Clean-label procurement mandates from German and Dutch beverage manufacturers are compressing supplier qualification timelines, forcing Iberian processors to upgrade membrane filtration infrastructure and pass through capital recovery costs across premium and standard grade tiers.
Pricing Analysis
Input-cost pass-through from seed supply concentration drives a contract-based long-term offtake model with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on USP-grade certification and backward integration into Valencia-Lisbon orchard zones. Pricing pressure stems from Indian guar gum substitution in textile applications where viscosity tolerance bands exceed specification limits. Textile producers exhibit highest price sensitivity; pharmaceutical compounders accept premium positioning for segregated air-handling compliance.
Supply Chain Analysis
Dual-sourcing requirements from pan-European ingredient distributors mandate multi-supplier qualification against EFSA novel food catalog standards. Geographic supply concentration centers on Spain, Portugal, and Turkey with seed processing capacity anchored in the Valencia-Lisbon corridor. Raw material dependencies rest on Ceratonia siliqua seed harvests, cellulase enzyme inputs for pre-treatment, and membrane filtration consumables. Single-source vulnerability from drought exposure in Mediterranean cultivation clusters threatens supply continuity. Distribution runs through Rotterdam logistics hubs for pharmaceutical-grade palletized shipments and Frankfurt-area distributors for beverage plant bulk deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as plant-based dairy manufacturers consolidate procurement around single-source accountability contracts with viscosity guarantees and seed-to-powder traceability documentation.
For Market Incumbents: Lock in captive seed supply through orchard lease arrangements in Algarve expansion zones to defend margin positions against guar gum substitution. Accelerate pharmaceutical-grade line certification with segregated air-handling infrastructure before EFSA's pending re-evaluation of purity standards disqualifies legacy processing equipment.
For New Entrants and Emerging Players: Capture white-space opportunity in ready-to-use liquid gum slurries for mid-sized Belgian and Dutch dairy alternatives producers seeking compressed changeover downtime. Target contract manufacturing partnerships as the most penetrable entry path, leveraging enzyme-assisted mechanical extraction technology for clean-label positioning.
For Investors and Strategic Acquirers: Asymmetric upside sits with Portuguese processors holding dual food-grade and pharmaceutical-grade certification with upgraded membrane filtration systems. Long-term viability across the analysis window favors acquisition targets with carbon footprint verification under EU Green Deal frameworks. Monitor EFSA's finalized heavy metal thresholds as the critical inflection signal for supplier qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iberian Orchards | Secures captive Ceratonia siliqua seed supply against drought-driven harvest volatility. |
| Pharmaceutical-Grade Line Certification | Unlocks USP-grade tablet binding margins at three to four times commodity pricing levels. |
| Liquid Delivery System Partnerships | Reduces beverage plant sanitation cycles for Belgian and Dutch oat milk manufacturers. |
| Enzyme-Assisted Extraction Deployment | Increases galactomannan recovery rates without solvent residues for EFSA compliance. |
| EU Green Deal Carbon Verification | Qualifies processors for preferential procurement from sustainability-mandated food manufacturers. |
Methodological Framework
Multiple input streams — primary interviews with hydrocolloid procurement managers, extraction plant engineers, and regulatory affairs specialists at EFSA-notified bodies; secondary validation through customs trade data, FEFAC compound feed reports, and SEC filings from listed ingredient technology divisions; plus technical literature on galactomannan rheology — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Historical volume trajectories were cross-referenced against panel input from Iberian processors and German beverage formulators to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include physical form, application tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution dynamics between carob bean gum and locust bean gum in neutral-pH stabilizer systems.
Underlying measurement precision varies by segment; pharmaceutical-grade certification tiers carry tighter precision than commodity food-grade volumes given qualified supplier concentration. Forecasts reflect assumptions around EFSA re-evaluation timelines and Mediterranean rainfall patterns. Deviation in EFSA's finalized heavy metal thresholds or prolonged drought in Valencia-Lisbon cultivation zones would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Distilled Monoglyceride Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Cetyl Palmitate Market