
 Hydrocolloids Market | 2026-2036
Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocolloids Market Analysis
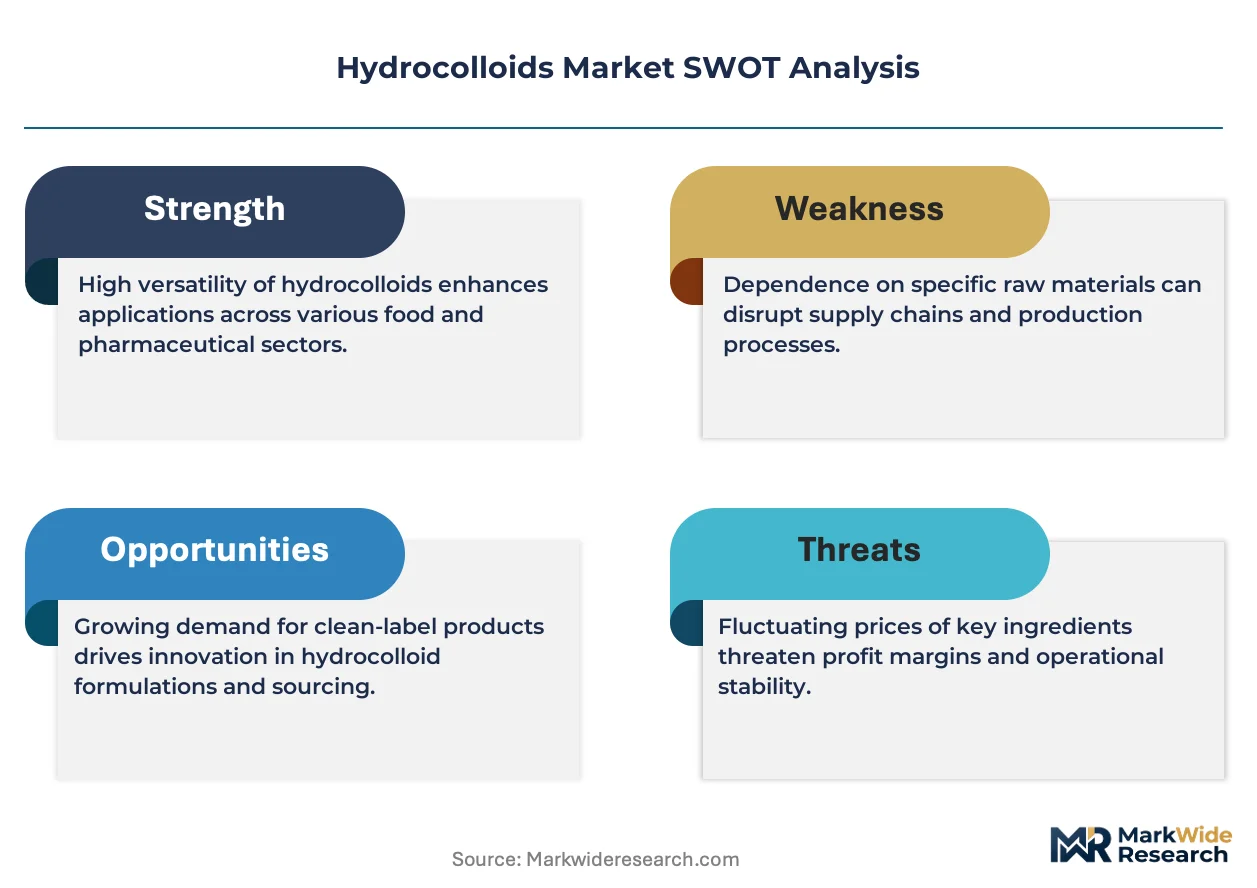
Project finance and leasing arrangements for bioreactor infrastructure is fragmenting competitive entry barriers across the hydrocolloids supply base. Cargill, Incorporated leverages its agricultural origination networks to secure feedstock cost advantages for pectin and xanthan gum production. Kerry Group plc anchors its position through integrated flavor-hydrocolloid formulation services for ready-meal manufacturers. DuPont differentiates via microbial fermentation expertise that yields consistent xanthan gum viscosity grades for oilfield and food applications.
Hydrocolloids are high-molecular-weight hydrophilic biopolymers—typically polysaccharides or proteins—that form viscous dispersions or gels when hydrated in aqueous systems, with gel strengths ranging from brittle (agar) to elastic (gelatin) depending on molecular architecture and ionic environment. These functional properties make them indispensable as thickeners, stabilizers, emulsifiers, and texturizers across formulated products. Gelatin occupies the largest revenue share among product types due to entrenched use in confectionery and capsule manufacturing, while xanthan gum demonstrates the fastest structural expansion driven by gluten-free bakery demand and oilfield drilling fluid requirements. Application segmentation shows food and beverage commanding the dominant volume position, though pharmaceuticals generates superior margin pools through excipient-grade certification requirements.
EFSA purity standards, FDA food additive regulations under 21 CFR, and FSSAI labeling mandates collectively shape product specifications, testing protocols, and market access conditions for hydrocolloid suppliers. REACH compliance in Europe and evolving clean-label definitions across North American retail channels are forcing reformulation investments and supply chain documentation upgrades. Stakeholders must monitor regulatory divergence between jurisdictions while building dual-certified manufacturing capacity to preserve cross-border commercial flexibility.
Market Dynamics
Clean-label formulation mandates from EFSA and FSSAI are forcing simultaneous supply chain requalification and ingredient substitution across hydrocolloid procurement desks, compressing supplier switching timelines and fragmenting specification standards.
Growth Catalysts
- EFSA purity tightening:Updated additive regulations under EFSA are accelerating excipient-grade certification investments. Pharmaceutical manufacturers now specify dual-certified hydrocolloids for capsule and tablet binding.
- Gluten-free bakery expansion:Xanthan gum demand from gluten-free bread and pastry producers is structurally displacing wheat-based stabilizers. Bakery formulators require consistent viscosity grades for dough handling.
- India food processing capacity:Domestic cold chain and ready-meal manufacturing expansion in India is concentrating regional hydrocolloid procurement. Local dairy and sauce producers are adopting pectin and guar gum for texture control.
Market Restraints
- Seaweed supply concentration:Carrageenan and agar raw material sourcing clusters in Southeast Asian coastal regions. Climate volatility and harvesting permit restrictions in Indonesia and the Philippines create input cost instability.
- Gelatin substitution pressure:Plant-based alternatives from pectin and modified starches are displacing animal-derived gelatin in confectionery. Vegetarian label requirements from European retailers accelerate this displacement.
- REACH compliance burden:European hydrocolloid importers face extended substance registration timelines and testing costs. Small and mid-scale suppliers lack resources for full dossier preparation.
Strategic Opportunities
- Pharmaceutical excipient certification:USP-NF and EP compliance for hydrocolloid binders and disintegrants opens premium margin pools. Generic drug manufacturers in India and Brazil seek pre-qualified suppliers.
- Precision fermentation platforms:Microbial production of xanthan gum and gellan gum is hybridizing with synthetic biology tools. This convergence reduces batch-to-batch viscosity variation and agricultural feedstock dependence.
- Direct-to-manufacturer digital channels:Specialty chemical marketplaces and formulation databases are disintermediating traditional distributor networks. Mid-size food developers now sample and specify hydrocolloids through digital platforms.
Industry Challenges
- Dual-certification timeline compression:Simultaneous FSSAI, FDA, and EFSA qualification for the same hydrocolloid SKU requires parallel documentation streams. Quality teams face resource strain managing divergent testing protocols.
- Bioreactor scale-up capital intensity:Fermentation-based hydrocolloid production demands stainless steel vessel investments and sterile utility infrastructure. Project finance availability constrains mid-tier entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocolloids Market |
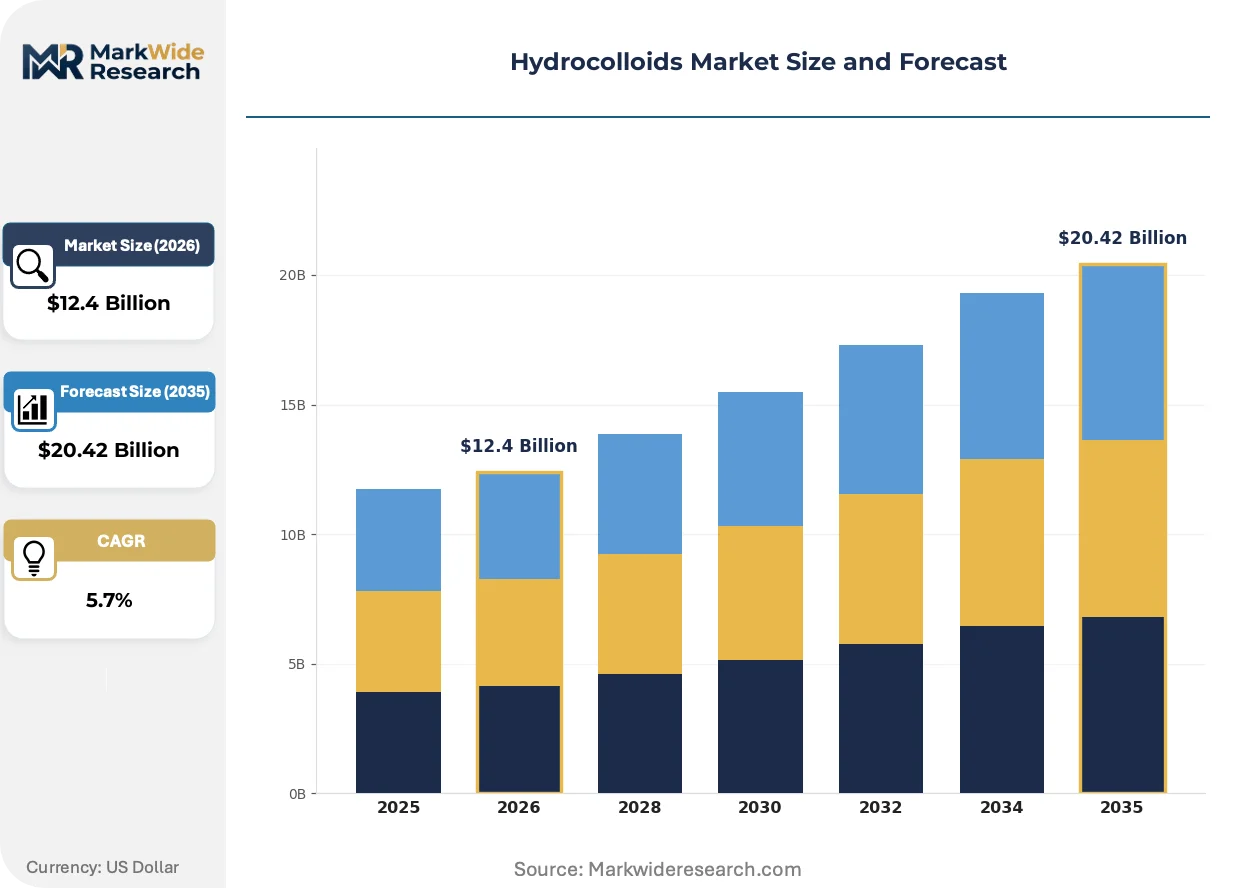
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Agar, Xanthan Gum Application: Food & Beverage, Pharmaceuticals, Cosmetics, Personal Care Form: Powder, Liquid, Granular, Sheet End User: Food Manufacturers, Healthcare Providers, Cosmetic Companies, Research Institutions |
| Companies Covered | CP Kelco, Kerry Group plc, Cargill, Incorporated, DuPont, Archer Daniels Midland Company, Ingredion Incorporated, International Flavors & Fragrances Inc., Ashland, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocolloids Market Emerging Trajectories
Active reformulation across food, pharmaceutical, and oilfield verticals is compressing hydrocolloid specification cycles and forcing suppliers to demonstrate functional equivalence under tighter purity thresholds.
Precision fermentation for xanthan gum and gellan gum is hybridizing with metabolic engineering and AI-driven strain optimization. Biotech specialists and established hydrocolloid producers are adopting these platforms to reduce agricultural feedstock exposure. This technology is hybridizing cost structures between traditional extraction and microbial production, pressuring commodity-grade suppliers while enabling premium viscosity consistency claims.
REACH authorization requirements for polymer additives are extending substance evaluation timelines for hydrocolloid modifiers and processing aids. Chemical suppliers now pre-register hydrocolloid-compatible excipients under ECHA frameworks to preserve European market access. Food-grade carrageenan and modified cellulose producers face downstream documentation requests from formulation customers seeking full supply chain transparency.
Buyer concentration among multinational food manufacturers is compressing hydrocolloid procurement cycles and unbundling technical service from volume contracts. Category managers now run competitive blind trials for texture-matched alternatives before renewing incumbent supply agreements. This pattern is most visible in North American and Western European ready-meal and dairy segments where clean-label claims drive rapid ingredient substitution.
Hydrocolloids Market Segmentation
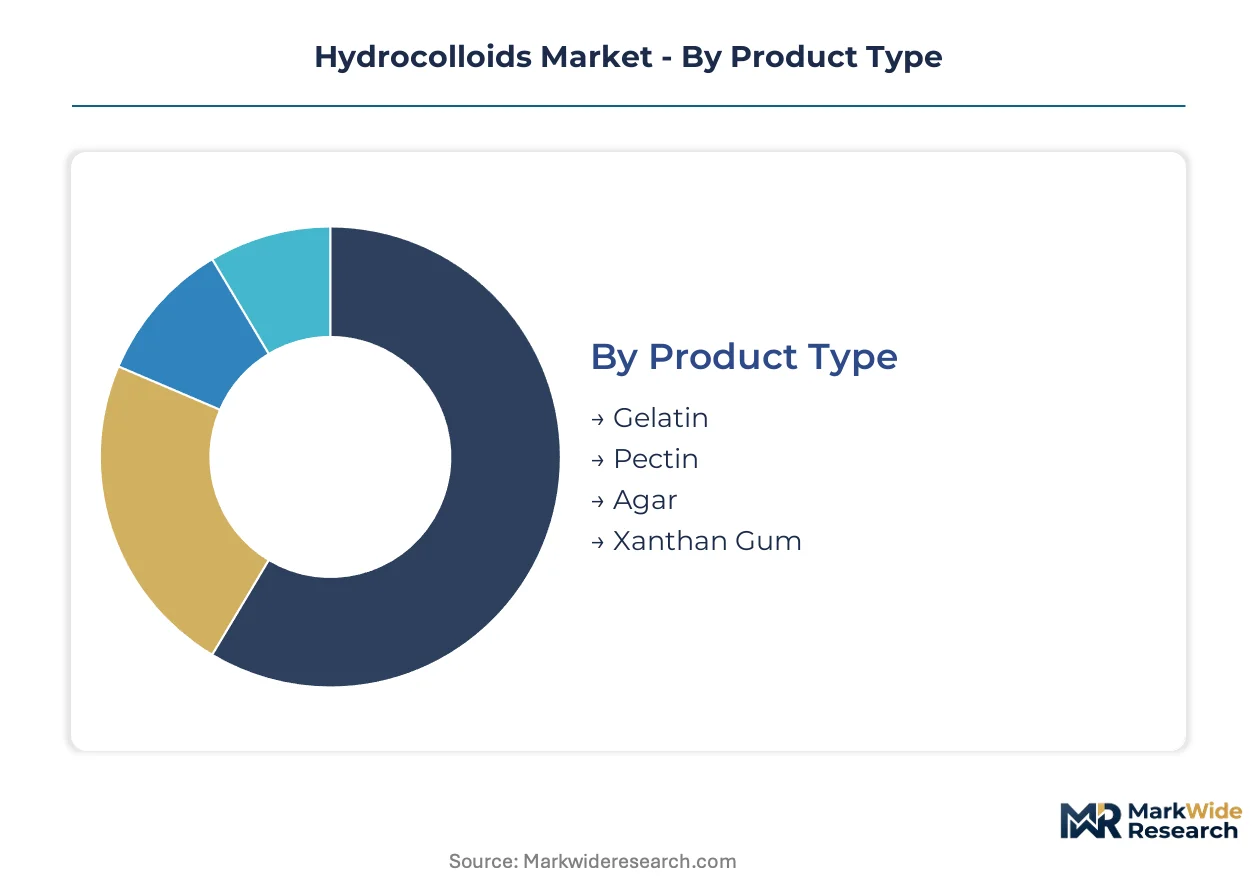
Hydrocolloid procurement decisions split across functional performance requirements and regulatory certification tiers. Formulators select product types based on gel strength profiles while end-use verticals impose divergent purity and documentation standards.
Product Type:
Cost tier positioning differentiates commodity extraction grades from fermentation-derived premium specifications.
- Gelatin:Collagen-derived protein hydrocolloid with thermoreversible gel properties. Pharmaceutical capsule manufacturers in India and Brazil specify USP-NF compliant grades for tablet binding applications. Animal sourcing constraints and vegetarian label mandates from European retailers accelerate substitution pressure from plant-based alternatives.
- Xanthan Gum:Microbial polysaccharide produced via Xanthomonas campestris fermentation with pseudoplastic rheology. Gluten-free bakery producers in Germany and the United States require consistent viscosity grades for dough handling and shelf-life extension. Oilfield drilling fluid specifications in Texas and North Dakota consume industrial-grade volumes.
- Pectin:Citrus and apple pomace extraction yields high-methoxyl and low-methoxyl variants for acid-gel applications.
- Agar:Red seaweed extract from Gelidium and Gracilaria species forms brittle gels for microbiological culture media.
Gelatin holds installed capacity. Xanthan gum is rotating up the share rankings.
Application:
Margin capture varies sharply across end-use certification requirements and technical service intensity.
- Food & Beverage:Volume-dominant segment spanning dairy stabilization, confectionery texture control, and sauce viscosity modification. Clean-label formulation mandates from FSSAI and EFSA force simultaneous supply chain requalification and ingredient substitution across procurement desks.
- Pharmaceuticals:Excipient-grade certification requirements generate superior margin pools through USP-NF and EP compliance for capsule binders, tablet disintegrants, and controlled-release matrices. Generic drug manufacturers in India seek pre-qualified suppliers with dual-certified manufacturing capacity.
- Cosmetics:Rheology modifiers for emulsion stability and skin-feel optimization in premium skincare formulations.
- Personal Care:Toothpaste binders and shampoo thickening applications with mild surfactant compatibility requirements.
Food & Beverage holds installed capacity. Pharmaceuticals is rotating up the share rankings.
Form:
Supply chain handling characteristics and dissolution kinetics determine form selection for specific manufacturing environments.
- Powder:Dominant dry-blend format for industrial-scale food and pharmaceutical processing with controlled particle size distribution for hydration kinetics.
- Liquid:Pre-hydrated dispersions for ready-to-use convenience in small-batch cosmetic and research laboratory settings.
- Granular:Reduced dusting and improved flow properties for high-speed tableting and direct compression operations.
- Sheet:Traditional agar presentation for microbiological culture media preparation and specialized culinary applications.
Powder holds installed capacity. Liquid is rotating up the share rankings.
End User:
Customer type dictates procurement scale, technical service requirements, and specification complexity.
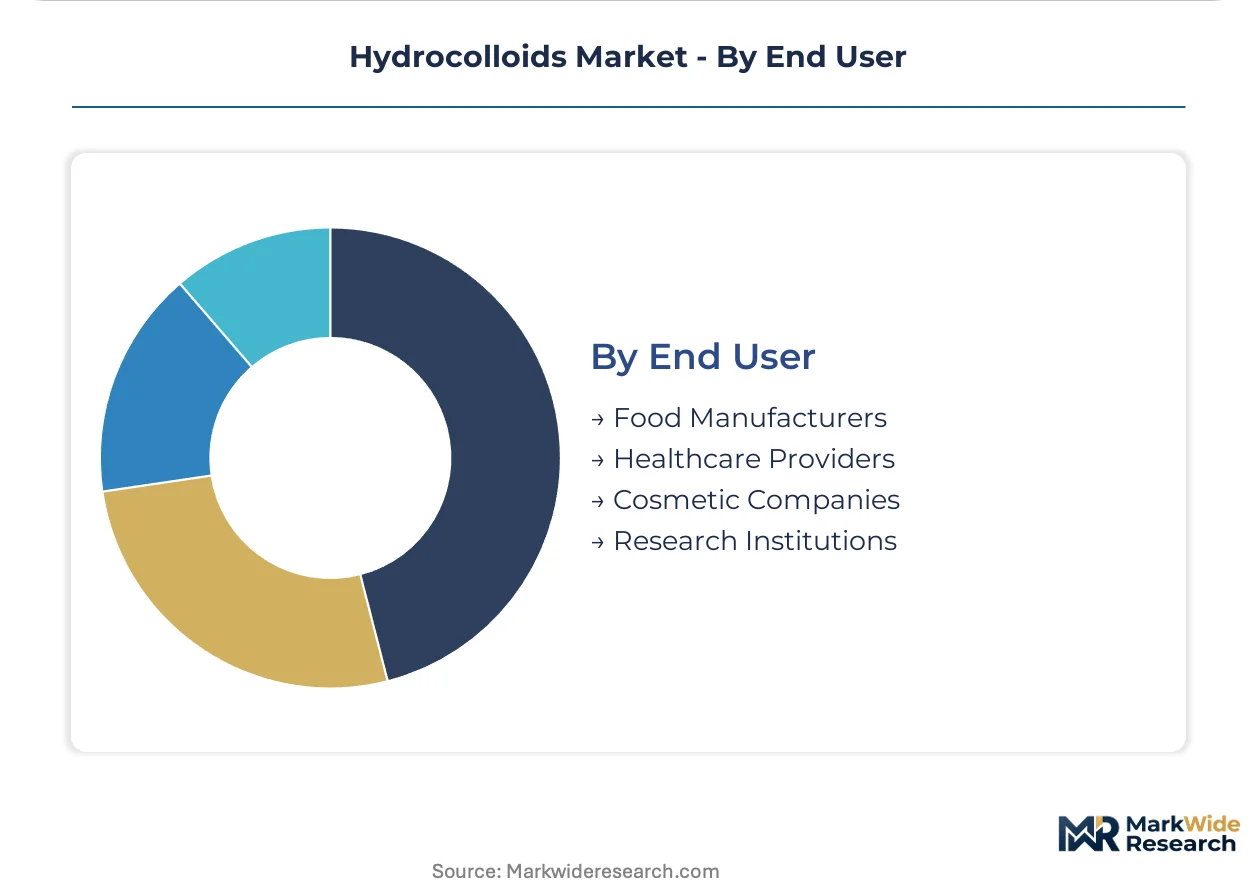
- Food Manufacturers:Multinational ready-meal and dairy producers run competitive blind trials for texture-matched alternatives before renewing supply agreements. Category managers unbundle technical service from volume contracts.
- Healthcare Providers:Hospital and clinic pharmacies specify excipient-grade hydrocolloids for extemporaneous compounding and nutritional supplement formulation.
- Cosmetic Companies:Premium skincare and haircare formulators prioritize sensory performance and label-friendly ingredient positioning.
- Research Institutions:Academic and industrial R&D laboratories sample through digital platforms and specialty chemical marketplaces for formulation development.
Food Manufacturers holds installed capacity. Healthcare Providers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across hydrocolloid-consuming regions, with processing capacity expansion in Asia reshaping traditional Atlantic trade flows. The United States and Germany remain net importers of specialty grades, while India and China build domestic fermentation and extraction infrastructure.
United States
Gluten-free bakery producers in Texas and North Dakota drive xanthan gum consumption for dough stabilization and oilfield drilling fluid applications. FDA food additive regulations under 21 CFR govern excipient-grade certification for pharmaceutical capsule manufacturing. Chicago and Minneapolis house major food processing clusters where clean-label reformulation accelerates hydrocolloid substitution trials.
Germany
Confectionery manufacturers in Cologne and Hamburg specify pectin and modified starches to displace animal-derived gelatin for vegetarian label compliance. EFSA purity standards under updated additive regulations tighten thickener specifications for ready-meal exports. The Bavarian dairy processing corridor concentrates regional guar gum and carrageenan procurement for yogurt and dessert texture control.
India
Domestic cold chain expansion and ready-meal manufacturing in Maharashtra and Gujarat concentrate regional hydrocolloid demand from sauce and dairy producers. FSSAI labeling mandates force simultaneous supply chain requalification and ingredient documentation upgrades. The Hyderabad-Visakhapatnam pharmaceutical belt drives excipient-grade gelatin and xanthan gum consumption for generic drug capsule binding.
China
Microbial fermentation capacity for xanthan gum and gellan gum scales up in Shandong and Jiangsu provinces to reduce agricultural feedstock dependence. SAMR food additive standards and GB quality specifications shape import requirements for carrageenan and agar from Southeast Asian suppliers. Qingdao and Dalian host seaweed processing clusters where red algae extraction yields agar for microbiological culture media.
Brazil
São Paulo-based food manufacturers adopt pectin from domestic citrus processing waste for acid-gel applications in jams and dairy desserts. ANVISA pharmaceutical regulations drive USP-NF certification requirements for imported hydrocolloid excipients. The Campinas research corridor connects formulation laboratories to specialty chemical marketplaces for direct hydrocolloid sampling and specification.
Hydrocolloids Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional portfolios. The vendor base organizes around three strategic archetypes: agricultural origination networks securing feedstock cost positions, integrated flavor-hydrocolloid formulation service providers, and microbial fermentation specialists delivering viscosity consistency. Dominant competitive moves include backward integration into citrus and seaweed extraction assets, plus capacity expansion in precision fermentation platforms.
Within the agricultural-origination tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify feedstock-integrated positioning. Kerry Group plc occupies a position among formulation-integrated service providers. CP Kelco anchors the specialty extraction segment. These three represent distinct strategic postures rather than direct segment overlap.
| Leading Market Players |
|---|
| CP Kelco |
| Kerry Group plc |
| Cargill, Incorporated |
| DuPont |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| International Flavors & Fragrances Inc. |
| Ashland |
| Tate & Lyle PLC |
| Others |
Supply Flow & Price Mechanics
Shandong and Jiangsu provinces anchor global xanthan gum fermentation capacity, and their scale-up dynamics directly compress pricing power for agricultural extraction grades of pectin and carrageenan. Buyers in European confectionery and Indian pharmaceuticals face divergent cost structures depending on whether they source microbial-derived or plant-extracted hydrocolloids.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the hydrocolloids market. Price differentiation rests on USP-NF certification tier and volume scale, with excipient-grade gelatin commanding substantial premiums over food-standard equivalents. Cost compression in commodity pectin and guar gum is intensifying because Indonesian seaweed harvest volatility feeds raw material instability. Small-batch cosmetic formulators exhibit the highest price sensitivity, while pharmaceutical capsule manufacturers prioritize certification compliance over unit cost.
Supply Chain Analysis
REACH authorization requirements and evolving EFSA purity standards function as de facto export controls limiting hydrocolloid flows into European formulation markets. Geographic supply concentration centers on China for microbial fermentation, Indonesia and the Philippines for red seaweed extraction, and India for domestic guar gum processing. Raw material dependencies encompass citrus pomace for pectin, red algae biomass for agar and carrageenan, and corn-derived glucose for xanthan gum fermentation feedstock. Single-source vulnerability from Southeast Asian seaweed harvesting permits creates structural risk. Distribution runs through specialty chemical distributors and direct-to-manufacturer digital platforms serving mid-size food developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrocolloids sit in early-cycle expansion as precision fermentation platforms displace agricultural extraction for premium viscosity grades. Clean-label mandates from EFSA and FSSAI are accelerating ingredient substitution trials across food and pharmaceutical procurement desks.
For Market Incumbents: Insulate installed base relationships by embedding technical service teams within multinational ready-meal manufacturer R&D labs. Accelerate backward integration into citrus processing waste streams in Brazil and Spain to secure pectin feedstock cost positions. Counter plant-based gelatin substitution pressure by pursuing dual USP-NF and EP certification for pharmaceutical-grade collagen derivatives.
For New Entrants and Emerging Players: Build out precision fermentation capacity for gellan gum and xanthan gum in India and Brazil where regulatory qualification timelines remain shorter than European REACH dossier preparation. Target the generic pharmaceutical excipient segment in Hyderabad and São Paulo, where pre-qualified supplier scarcity creates white-space opportunity. Deploy direct sampling through specialty chemical marketplaces to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation-platform specialists with multi-year pharmaceutical supply agreements. Long-term viability over the next decade favors asset-light biotech platforms over capital-intensive seaweed extraction infrastructure. Acquisition targets should demonstrate existing USP-NF or EP certification infrastructure with capacity to add FSSAI qualification. Watch for inflection signals when major food manufacturers unbundle technical service from volume contracts and initiate competitive blind trials.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Reduces batch-to-batch viscosity variation for xanthan gum and gellan gum producers. |
| Dual-Certification Manufacturing Investment | Preserves cross-border commercial flexibility under divergent FDA, EFSA, and FSSAI standards. |
| Backward Integration into Citrus Processing | Secures captive pectin feedstock from São Paulo and Valencia orange juice waste streams. |
| Direct-to-Manufacturer Digital Channel Buildout | Disintermediates traditional distributors for mid-size cosmetic and food formulation laboratories. |
| Pharmaceutical Excipient Pre-Qualification | Opens premium margin pools with generic drug manufacturers in India and Brazil. |
Methodological Framework
Initial hypotheses were tested against primary input from hydrocolloid procurement managers at multinational food manufacturers, pharmaceutical excipient specification leads, fermentation platform R&D directors, and specialty chemical distribution channel partners and refined through secondary validation. Bottom-up and top-down triangulation incorporated customs and trade data, EFSA additive regulation filings, USP-NF monograph updates, FSSAI labeling mandate documentation, and SEC filings from publicly traded ingredient suppliers.
Demand-supply balance dynamics across the analysis window were modeled through segmented projections by product type, application vertical, certification tier, and regional production hub. CAGRs were derived from growth rate reconciliation across independent volume and value build-ups. Industry-specific forecast inputs included gluten-free bakery expansion rates, oilfield drilling fluid consumption patterns, and pharmaceutical capsule manufacturing capacity build-outs in India and Brazil.
Practitioners should monitor regulatory divergence between EFSA, FDA, and FSSAI jurisdictions for early signals of qualification timeline compression. Forecasts reflect assumptions about continued clean-label adoption and precision fermentation cost convergence. Material shifts in REACH authorization timelines or Southeast Asian seaweed harvest permit restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market