
 Salt Substitutes Market | 2026-2036
Salt Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Salt Substitutes Market Outlook
Capital-intensity divergence between extraction-based mineral salt producers and fermentation-derived flavor enhancer specialists is rotating competitive advantage toward biotechnology capabilities. Cargill Inc leverages its integrated potassium chloride mining and food-grade processing infrastructure across North American salt basins. Kerry Group PLC anchors its position through sustained R&D spending on yeast extract and savory flavor modulation systems that mask potassium chloride bitterness.
Salt substitutes comprise potassium chloride, mineral salts, yeast extracts, and amino acid-based flavor enhancers formulated to replicate sodium chloride's sensory and functional properties in food systems, typically containing 40-70% less sodium by mass while maintaining water-binding capacity in processed meat matrices. Their primary commercial purpose centers on enabling food manufacturers to achieve sodium reduction targets without reformulating entire product lines. Potassium chloride formulations dominate volume due to established supply chains and cost parity with standard salt, while flavor enhancers capture disproportionate margin pools through proprietary bitter-blocking technologies. The processed foods application segment sustains the largest revenue base as multinational brands face reformulation mandates, whereas healthcare facilities represent the fastest-growing end-user channel driven by clinical nutrition protocols for hypertension management.
The FDA's draft sodium reduction targets for commercially processed foods directly expand addressable demand for potassium chloride and mineral salt blends in US manufacturing facilities. EFSA's ongoing re-evaluation of potassium-based additives under EU food additive regulations shapes product registration timelines and labeling requirements for European suppliers. WHO sodium intake guidelines influence national procurement standards in multiple jurisdictions, creating compliance-driven substitution mandates for institutional foodservice operators. Stakeholders must monitor evolving potassium chloride purity standards and bitter-masking patent expirations to time capacity investments and partnership strategies.
Market Dynamics
Reformulation mandates from the FDA and WHO are compressing sodium reduction timelines for processed food manufacturers, forcing rapid adoption of potassium chloride and bitter-masking systems across institutional procurement channels.
Growth Catalysts
- FDA Sodium Reduction Targets:Draft guidelines for commercially processed foods mandate sodium thresholds in categories including bakery, meat, and snack products, expanding bulk procurement of mineral salt blends by US food manufacturers.
- Yeast Extract Flavor Modulation:Biotechnology-derived savory enhancers are masking potassium chloride bitterness at lower cost-in-use than historical bitter-blockers, accelerating reformulation feasibility for mid-tier processors.
- Germany:Federal nutrition policies and concentrated meat processing infrastructure create institutional demand for reduced-sodium ingredient systems in Central European supply chains.
Market Restraints
- Potassium Chloride Supply Concentration:North American salt basin mining operations dominate food-grade potassium chloride feedstock, creating geographic concentration risk for European and Asian formulators.
- EFSA Additive Re-evaluation:Ongoing regulatory review of potassium-based additives under EU food additive regulations extends product registration timelines and increases compliance documentation burdens.
- Bitter Taste Perception Variability:Consumer acceptance thresholds for potassium chloride bitterness vary significantly across demographic cohorts, limiting universal substitution rates in consumer-facing products.
Strategic Opportunities
- Healthcare Foodservice:Clinical nutrition protocols for hypertension management in hospital and long-term care facilities are driving specification of reduced-sodium meal systems as reimbursable care components.
- Amino Acid-Potassium Convergence:Integration of glutamate-based flavor enhancers with mineral salt matrices enables sodium reduction beyond standalone potassium chloride capabilities in savory applications.
- Clean Label Positioning:Mineral salt blends positioned as "sea salt alternatives" command premium placement in natural and organic retail channels despite functional equivalence to standard potassium chloride.
Industry Challenges
- Reformulation Technical Talent:Shortage of food scientists with specialized expertise in sodium reduction, water-binding compensation, and sensory masking creates hiring bottlenecks for mid-size manufacturers.
- Legacy Equipment Compatibility:Existing salt dosing and blending infrastructure in processed meat facilities requires modification to handle hygroscopic potassium chloride without caking or flow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salt Substitutes Market |
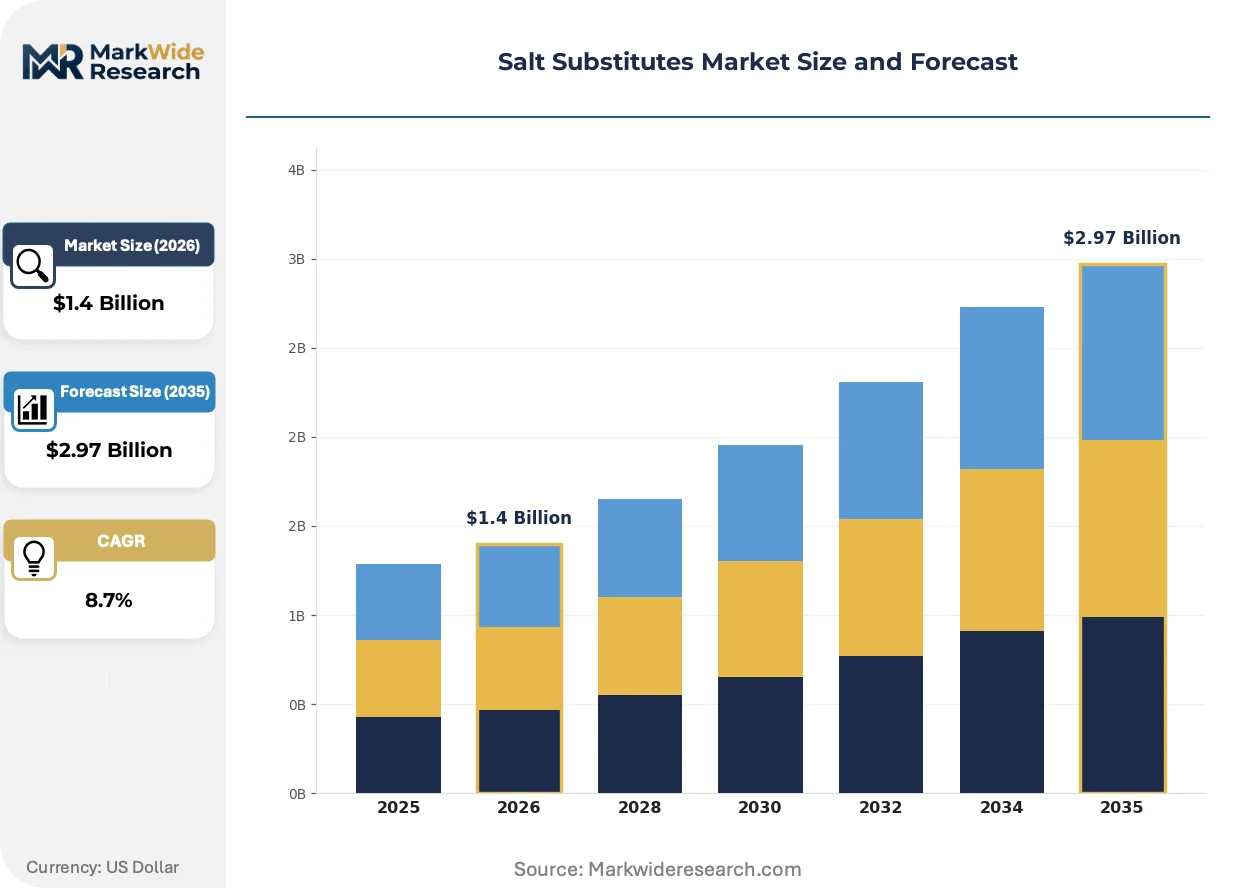
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Chloride, Sea Salt, Mineral Salt, Flavor Enhancers Application: Culinary, Processed Foods, Snacks, Meat Products End User: Households, Restaurants, Food Manufacturers, Healthcare Facilities Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice |
| Companies Covered | Cargill Inc, Tate & Lyle PLC, Kerry Group PLC, Ajinomoto Co Inc, DSM - Firmenich, Givaudan SA, The Kraft Heinz Company, McCormick & Company, Angel Yeast Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salt Substitutes Market Strategic Shifts
Biotechnology capabilities are displacing extraction-based production as the primary source of competitive advantage, while regulatory pressure compresses reformulation timelines and procurement patterns shift toward compliance-driven specification.
Fermentation-derived flavor enhancers are fragmenting the traditional mineral salt substitute market. Yeast extract and amino acid-based systems now deliver bitter-masking functionality previously requiring synthetic additives. Meat processors in Germany and the Netherlands are adopting these systems at accelerated rates. The technology is fragmenting margin pools away from bulk potassium chloride suppliers toward biotechnology specialists with proprietary strain libraries.
WHO sodium intake guidelines are reshaping national procurement standards across multiple jurisdictions. Institutional foodservice operators in healthcare and education sectors face compliance-driven substitution mandates. The processed foods segment in the United States responds through accelerated reformulation pipelines to meet FDA-aligned targets ahead of formal enforcement.
Specification-driven procurement is consolidating buyer power among multinational food manufacturers with dedicated sodium reduction programs. These buyers are unbundling flavor modulation from mineral salt supply, contracting separately with biotechnology firms for bitter-masking systems. The shift is most visible in North American and Western European processed meat and bakery categories where reformulation timelines are shortest.
Salt Substitutes Market Segmentation
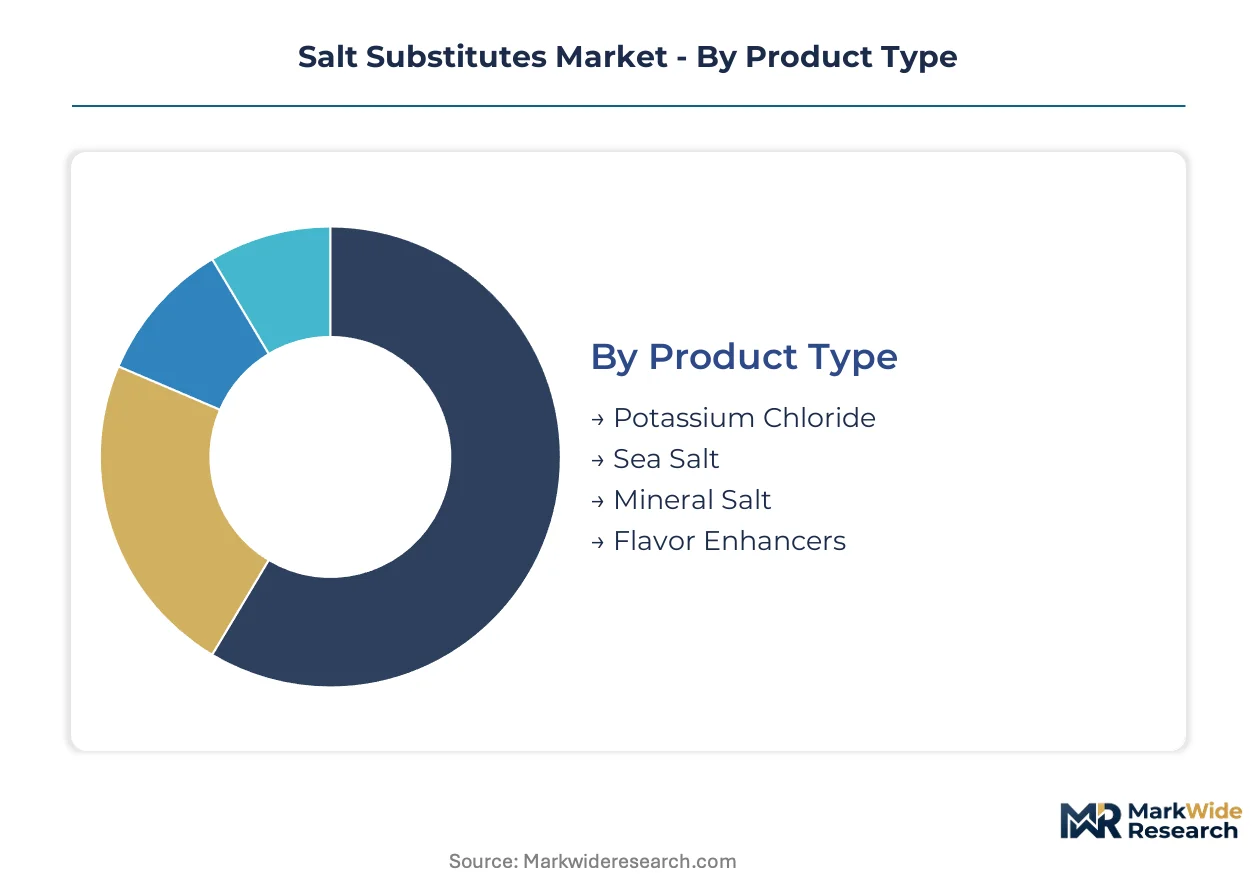
Salt substitutes serve divergent functional requirements across consumer, industrial, and institutional channels. Product specifications vary sharply between retail household formats and bulk ingredient systems for processed food manufacturing. Understanding these segment boundaries clarifies where formulation investments concentrate versus where price competition dominates procurement decisions.
Product Type:
Domestic production of potassium chloride concentrates in North American salt basins, while flavor enhancer manufacturing clusters in European biotechnology corridors. Sea salt and mineral salt blends draw from geographically dispersed extraction operations across multiple continents.
- Potassium Chloride:Crystalline potassium salt formulated to replicate sodium chloride's ionic functionality in food matrices, typically comprising 60-70% potassium by mass. US food manufacturers absorb the largest procurement volumes as FDA sodium reduction targets compress reformulation timelines for processed meat and bakery categories. Supply chains anchor to integrated mining and refining infrastructure in Saskatchewan and New Mexico.
- Flavor Enhancers:Fermentation-derived yeast extracts and amino acid systems that mask potassium chloride bitterness while contributing savory umami notes. German meat processors and Dutch savory food manufacturers drive specification growth as these systems enable sodium reduction beyond standalone mineral salt capabilities. Biotechnology specialists with proprietary strain libraries capture disproportionate margin pools in this segment.
- Mineral Salt:Blended potassium-magnesium-calcium formulations positioned as natural sodium alternatives in clean-label retail channels.
- Sea Salt:Reduced-sodium evaporated salt products marketed through premium positioning despite functional equivalence to standard mineral substitutes.
Potassium chloride commands the established base. The steepest expansion runs through flavor enhancers.
Application:
Volume concentration tilts toward industrial-scale food manufacturing rather than consumer-facing culinary use. Cost structures separate commodity-grade bulk formulations from precision-engineered savory systems.
- Processed Foods:Institutional procurement of reduced-sodium ingredient systems for large-scale bakery, sauce, and prepared meal manufacturing. US and German food manufacturers face the most compressed reformulation timelines as regulatory targets approach enforcement windows. Water-binding functionality in these applications demands precise potassium chloride particle size distribution and anti-caking specifications.
- Meat Products:Cured and processed meat categories where sodium chloride reduction threatens shelf stability and texture integrity without compensatory ingredient systems. Central European meat processing clusters in Germany and the Netherlands adopt bitter-masking technologies at accelerated rates. Potassium chloride's hygroscopicity creates equipment compatibility challenges requiring modified dosing infrastructure.
- Culinary:Direct consumer use in home cooking applications, primarily through retail-packaged potassium chloride table salt alternatives.
- Snacks:Seasoning applications for chips, crackers, and extruded products where sodium reduction must preserve flavor impact and mouthfeel.
Processed foods anchor procurement volumes. Meat products are climbing the fastest as equipment retrofit cycles complete.
End User:
Specification authority separates institutional buyers with dedicated sodium reduction programs from fragmented household purchasing decisions.
- Food Manufacturers:Multinational processed food companies with centralized procurement functions and mandated sodium reduction targets across product portfolios. These buyers unbundle mineral salt supply from flavor modulation, contracting separately with biotechnology firms for bitter-masking systems. Reformulation technical talent shortages create hiring bottlenecks that delay adoption timelines.
- Healthcare Facilities:Hospital and long-term care foodservice operations where clinical nutrition protocols for hypertension management drive reimbursable meal system specifications. WHO sodium intake guidelines reshape national procurement standards for institutional operators across multiple jurisdictions. This channel demands documented sodium content and consistent supply reliability for therapeutic diet compliance.
- Households:Individual consumers purchasing retail-packaged salt substitutes through supermarket and online channels.
- Restaurants:Commercial foodservice operators with limited technical capacity for reformulation, typically relying on supplier-provided sodium-reduced ingredient systems.
Food manufacturers dominate procurement scale. Healthcare facilities represent the fastest-growing specification channel.
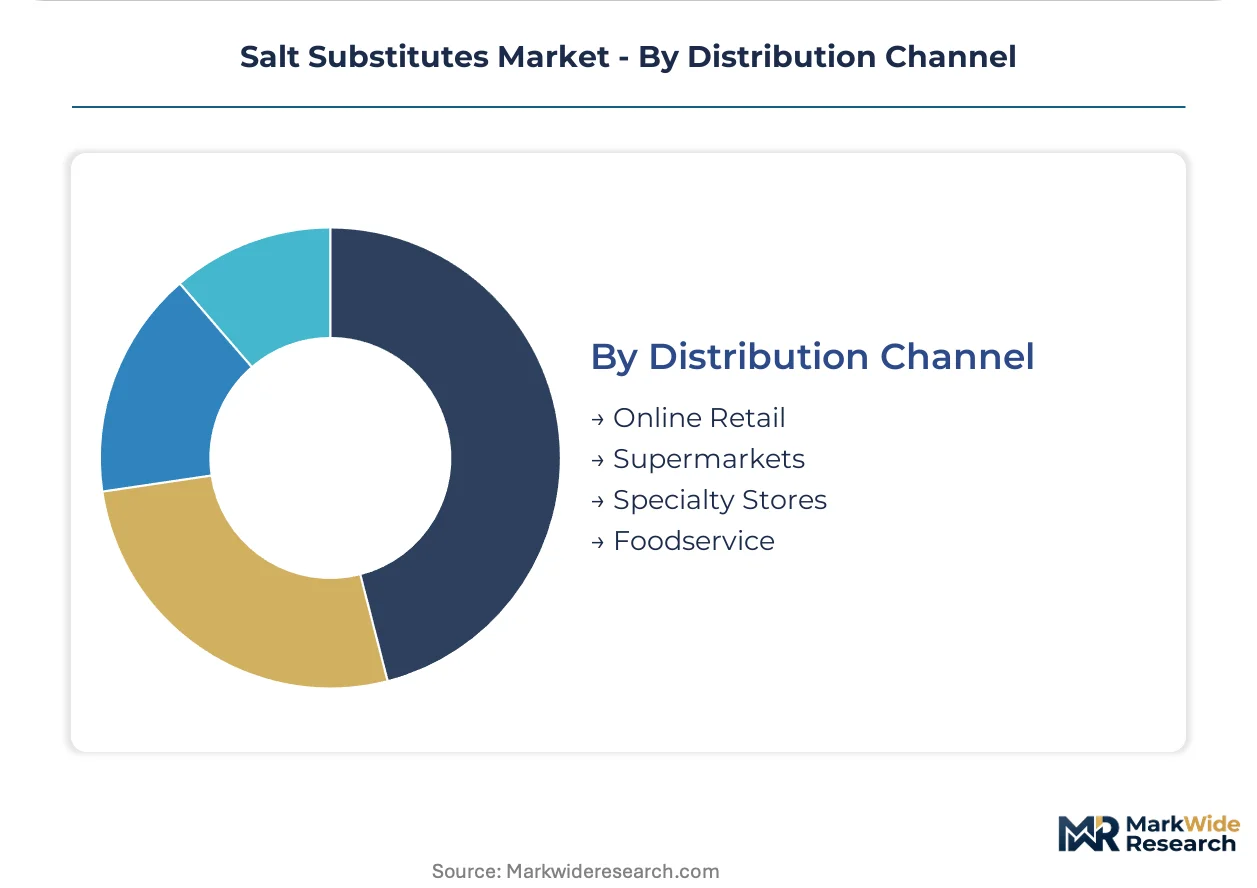
Distribution Channel:
Channel selection tracks buyer scale and technical sophistication, with bulk ingredient systems bypassing retail infrastructure entirely.
- Foodservice:Direct supply relationships between ingredient manufacturers and institutional operators including healthcare facilities, educational institutions, and contract catering companies. German federal nutrition policies drive specification of reduced-sodium meal systems through centralized procurement frameworks. This channel demands technical support capabilities for menu reformulation and staff training.
- Supermarkets:Mass retail distribution for consumer-packaged potassium chloride table salt alternatives and mineral salt blends. Clean-label positioning enables premium placement for products functionally equivalent to standard formulations.
- Online Retail:Direct-to-consumer and small-business procurement of specialty and bulk salt substitute products.
- Specialty Stores:Natural and organic retail channels where mineral salt blends command placement through positioning rather than functional differentiation.
Foodservice captures institutional volume. Online retail is gaining share fastest among small and mid-tier processors seeking direct supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers in Germany absorb price premiums for certified mineral salt blends with minimal elasticity, while household consumers in emerging markets remain acutely sensitive to per-unit costs. This demand-elasticity contrast shapes regional investment priorities and distribution infrastructure.
United States
Processed meat and bakery manufacturers drive bulk procurement of potassium chloride as FDA sodium reduction targets compress reformulation timelines. The agency's draft guidelines for commercially processed foods mandate specific sodium thresholds across multiple categories. Midwest manufacturing clusters in Illinois and Ohio retrofit legacy dosing equipment to handle hygroscopic mineral salts.
Germany
Federal nutrition policies and concentrated meat processing infrastructure create institutional demand for reduced-sodium ingredient systems. EFSA's ongoing re-evaluation of potassium-based additives under EU food additive regulations shapes product registration requirements. The North Rhine-Westphalia industrial corridor anchors Central European supply chains for bulk mineral salt distribution.
China
Domestic food manufacturers accelerate sodium reduction programs ahead of anticipated national standards alignment with WHO intake guidelines. SAMR oversees evolving food additive classifications affecting potassium chloride labeling requirements. Yangtze River Delta processing hubs in Jiangsu and Zhejiang provinces adopt bitter-masking technologies for savory sauce production.
Netherlands
Savory food manufacturers specification of yeast extract flavor modulation systems enables sodium reduction beyond standalone mineral salt capabilities. EU Green Deal sustainability criteria influence procurement standards for fermentation-derived ingredients. The Eindhoven biotechnology corridor hosts specialist strain development operations for bitter-blocking applications.
Japan
Amino acid-based flavor enhancers integrate with mineral salt matrices in traditional seasoning applications requiring precise umami calibration. METI coordinates industry alignment with international sodium reduction frameworks. Kansai region food technology clusters in Osaka prefecture advance glutamate-potassium convergence formulations.
Salt Substitutes Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure rather than consolidated dominance. Integrated mining and refining operations control potassium chloride feedstock economics across North American salt basins. Biotechnology specialists with proprietary fermentation platforms capture premium positioning in flavor modulation segments. Dominant competitive moves include capacity expansion in food-grade mineral salt refining and strategic partnerships between mineral suppliers and bitter-masking technology developers.
Within the integrated extraction tier, Cargill Inc anchors positions through captive control of upstream potassium chloride resources. Kerry Group PLC and Ajinomoto Co Inc exemplify biotechnology-led competitive positioning, occupying roles defined by fermentation-derived savory enhancement capabilities rather than bulk commodity supply. These archetypes represent fundamentally different margin structures and capital intensity requirements.
| Leading Market Players |
|---|
| Cargill Inc |
| Tate & Lyle PLC |
| Kerry Group PLC |
| Ajinomoto Co Inc |
| DSM - Firmenich |
| Givaudan SA |
| The Kraft Heinz Company |
| McCormick & Company |
| Angel Yeast Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Saskatchewan potash mines anchors North American feedstock economics, concentrating pricing power among integrated operators while compressing margin floors for European and Asian formulators lacking captive mineral sources.
Pricing Analysis
Technical service contracts for bitter-masking formulation support drive lifetime value capture for biotechnology specialists. Three-tier pricing structure across premium, standard, and economy levels separates proprietary yeast extract systems from commodity potassium chloride and unbranded mineral blends. Pricing pressure stems from EFSA additive re-evaluation extending registration timelines and compliance documentation burdens. Healthcare facilities exhibit lowest price sensitivity due to reimbursable care protocols, while emerging market households remain acutely cost-responsive.
Supply Chain Analysis
Canada and the United States anchor food-grade potassium chloride extraction through integrated mining and refining infrastructure across Saskatchewan and New Mexico salt basins. Supply chains draw from potash ore deposits, fermentation feedstocks for yeast extract production, and magnesium-calcium mineral deposits for blended formulations. Single-source vulnerability concentrates in North American potash corridor dominance for mineral salt feedstock. Distribution runs through direct bulk supply relationships with multinational food manufacturers and foodservice procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Salt substitutes sit in early-cycle expansion as FDA sodium reduction targets and WHO intake guidelines compress reformulation timelines across processed food manufacturing, accelerating specification of potassium chloride and bitter-masking systems.
For Market Incumbents: Shield market position through backward integration into captive potassium chloride refining capacity and accelerated patent filing on next-generation bitter-masking strain libraries. Biotechnology specialists threaten margin pools in flavor modulation segments. Certification investment in EU food additive compliance creates defensive moats against EFSA re-evaluation delays.
For New Entrants and Emerging Players: Healthcare foodservice technical support gaps offer white-space entry where incumbents under-serve menu reformulation and staff training needs. Target hospital and long-term care procurement frameworks in Germany and the Netherlands as most penetrable channels. Lead with reimbursable meal system documentation and therapeutic diet compliance capabilities as go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biotechnology specialists with proprietary fermentation platforms and long-term flavor modulation contracts. Five-to-ten year viability favors players with integrated mineral supply or locked-in strain IP rather than pure-play extraction operators. Watch potassium chloride purity standard tightening and bitter-masking patent expiration schedules as inflection indicators for capacity investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potash Refining | Captive Saskatchewan feedstock secures supply certainty against North American concentration risk. |
| Proprietary Strain Library Expansion | Fermentation-derived bitter-masking IP captures premium positioning in yeast extract segments. |
| Healthcare Foodservice Partnership | Hospital procurement frameworks in Germany drive reimbursable reduced-sodium meal specifications. |
| EFSA Compliance Certification Program | EU additive registration readiness accelerates product launch timelines amid regulatory re-evaluation. |
| Equipment Retrofit Technical Service | Legacy dosing infrastructure modification unlocks mid-tier processor adoption of hygroscopic potassium chloride. |
Study Parameters
A spread of perspectives from food formulation scientists, procurement directors at multinational manufacturers, healthcare foodservice operators, and biotechnology R&D leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA sodium reduction guideline documents, EFSA additive re-evaluation proceedings, WHO intake target publications, and customs trade data on potassium chloride flows. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Product type, application, end user, and distribution channel dimensions structured the analytical framework across the analysis window. CAGRs derived from segment-level adoption curve modeling and regulatory enforcement timeline assumptions. Forecast inputs included FDA draft target finalization probability, EFSA re-evaluation outcome scenarios, and WHO guideline national adoption rates.
Forecasts assume regulatory continuity in US FDA and EU EFSA regimes; material policy shifts would require re-modeling adoption timelines and procurement specification patterns. Forecasts reflect assumptions on bitter-masking technology cost curves and potassium chloride mining capacity expansion schedules. Recalibration cycles align with material shifts in sodium reduction mandate enforcement windows and biotechnology patent expiration events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Egypt Food Preservatives Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Lake Food Colors Market
Food Additives and Ingredients
Japan Food Preservatives Market