
 Food Humectants Market | 2026-2036
Food Humectants Market Size, Share, and Industry Trends Forecast 2026-2036
Food Humectants Market Analysis
The food humectants category is restructuring around a widening split between premium-grade, non-GMO and fermentation-derived glycerin and commodity petrochemical-sourced alternatives. Cargill Incorporated leverages its agricultural supply chain to dominate plant-derived glycerin production for clean-label buyers. BASF SE anchors the European market with high-purity synthetic grades serving industrial confectionery clients. Roquette Frères differentiates through its pea starch and polyol expertise, positioning specialty sorbitol for reduced-sugar applications.
Food humectants are hygroscopic substances—typically polyols such as glycerin, sorbitol, and propylene glycol or natural syrups like honey—that retain moisture in processed foods through hydrogen bonding with water molecules, with glycerin commonly specified at 99.5% purity for pharmaceutical and food-grade use. Their primary commercial purpose is to extend shelf life, preserve texture, and prevent staling in moisture-sensitive products. Glycerin leads product type volumes due to its versatility across baked goods and dairy, while sorbitol captures margin pools in sugar-free confectionery where crystallization control commands premium pricing. Powder and granule forms are gaining share among dry-mix manufacturers seeking easier handling and dosing precision than liquid alternatives.
The FDA governs humectant safety through 21 CFR food additive regulations, while REACH mandates full toxicological dossiers for polyol imports into Europe, and the FSSAI enforces BIS-aligned purity standards for glycerin used in Indian processed foods. These frameworks compel suppliers to maintain multi-jurisdiction certification portfolios, raising barriers for unqualified entrants. Stakeholders must monitor evolving clean-label definitions and biobased certification schemes as procurement criteria harden across retail and foodservice channels.
Market Dynamics
Precision fermentation infrastructure is pulling glycerin supply chains away from petrochemical feedstocks, forcing ingredient buyers to requalify suppliers against tightening REACH purity dossiers and FDA food additive benchmarks simultaneously.
Growth Catalysts
- REACH toxicological dossiers:European importers now demand full substance registration for polyol shipments, filtering out unqualified suppliers and concentrating volume among certified producers.
- Clean-label bakery expansion:Artisan and industrial bakers across Germany, France, and Italy are specifying non-GMO glycerin for moisture retention in extended-shelf-life products.
- Reduced-sugar confectionery:Sorbitol crystallization control commands premium positioning as sugar-free candy formulations multiply in Western European retail channels.
Market Restraints
- Crude glycerin price volatility:Biodiesel byproduct supply fluctuations destabilize plant-derived glycerin cost structures for fermentation-based producers.
- Propylene glycol substitution threat:Industrial confectionery clients in cost-sensitive segments retain synthetic polyols despite clean-label pressure from retail buyers.
- Multi-jurisdiction certification burden:FSSAI BIS-aligned purity standards for Indian imports add compliance layers atop existing REACH and FDA requirements.
Strategic Opportunities
- Pea starch-derived polyols:Roquette Frères specialty sorbitol expertise positions reduced-sugar applications for expansion into Nordic functional food markets.
- Dry-mix manufacturer channel:Powder and granule humectant formats are capturing share among industrial bakeries seeking dosing precision over liquid handling.
- EU Green Deal biobased certification:Procurement criteria hardening across European retail channels favor fermentation-derived glycerin with verified carbon intensity scores.
Industry Challenges
- Precision fermentation scale-up capex:Commercial cell-line optimization and bioreactor capacity expansion demand capital commitments stretching 36-48 month payback horizons.
- Cross-regulatory audit synchronization:Suppliers must align REACH dossier updates with FDA food additive petition timelines and FSSAI inspection windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Humectants Market |
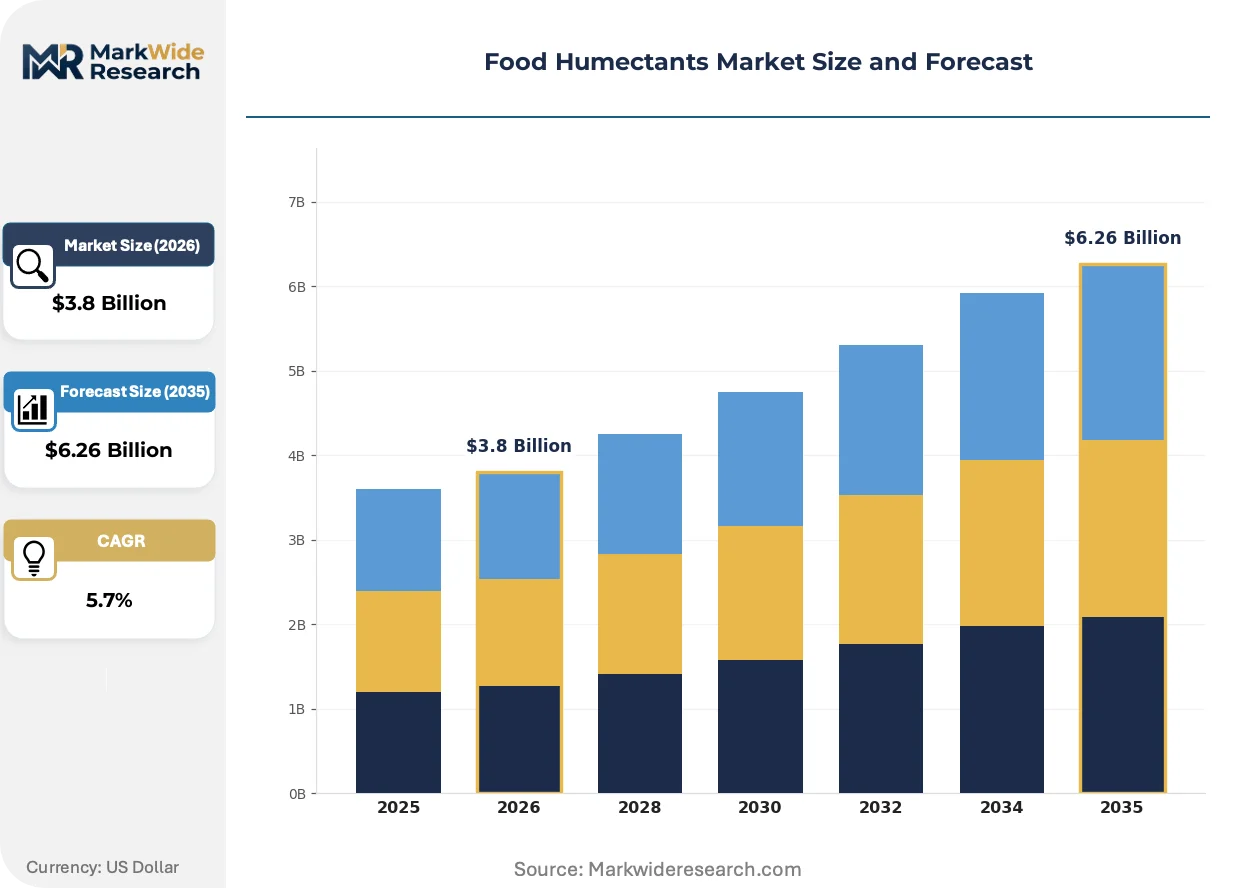
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycerin, Sorbitol, Propylene Glycol, Honey Application: Baked Goods, Confectionery, Dairy Products, Sauces End User: Food Manufacturers, Retailers, Hospitals, Restaurants Form: Liquid, Powder, Granules, Tablets |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Roquette Frères, Ingredion Incorporated, BASF SE, Corbion N.V., Ashland Global Holdings Inc., Brenntag SE, DuPont Tate & Lyle Bio Products Company LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Humectants Market Emerging Trajectories
Active restructuring of humectant value chains centers on three parallel developments: biological production methods displacing synthetic chemistry, regulatory purity thresholds compressing supplier bases, and dry-format product innovation reshaping industrial handling protocols.
Precision fermentation-derived glycerin is converging with synthetic biology platforms to produce pharmaceutical-grade 99.5% purity feedstocks. German industrial bakeries and dairy processors are accelerating adoption timelines from pilot to commercial scale. This convergence is compressing the cost gap between plant-derived and petrochemical glycerin, forcing commodity suppliers to defend volume through price repositioning.
REACH substance registration requirements now mandate full toxicological profiling for polyol imports into European Economic Area markets. Industrial confectionery manufacturers face reformulation audits as ECHA evaluates updated hazard classifications for high-volume humectants. German precision fermentation clusters are responding by pre-submitting enhanced dossiers to secure uninterrupted supply continuity.
Buyer specification protocols now embed carbon intensity scoring alongside traditional purity metrics. European retail and foodservice procurement teams are disintermediating distributors to contract directly with certified fermentation producers. This pattern is most visible in German clean-label bakery supply chains, where industrial buyers bypass commodity traders to secure batch-traceable glycerin with verified biobased content.
Food Humectants Market Segmentation
Humectant procurement specifications diverge sharply across end-use applications, forcing suppliers to maintain parallel certification portfolios and production lines. Segmentation discipline separates commodity volume plays from specialty margin opportunities in this bifurcated market.
Product Type:
Capital intensity concentrates in fermentation infrastructure and pharmaceutical-grade purification systems, with synthetic chemistry requiring lower upfront investment but carrying stranded asset risk from regulatory displacement.
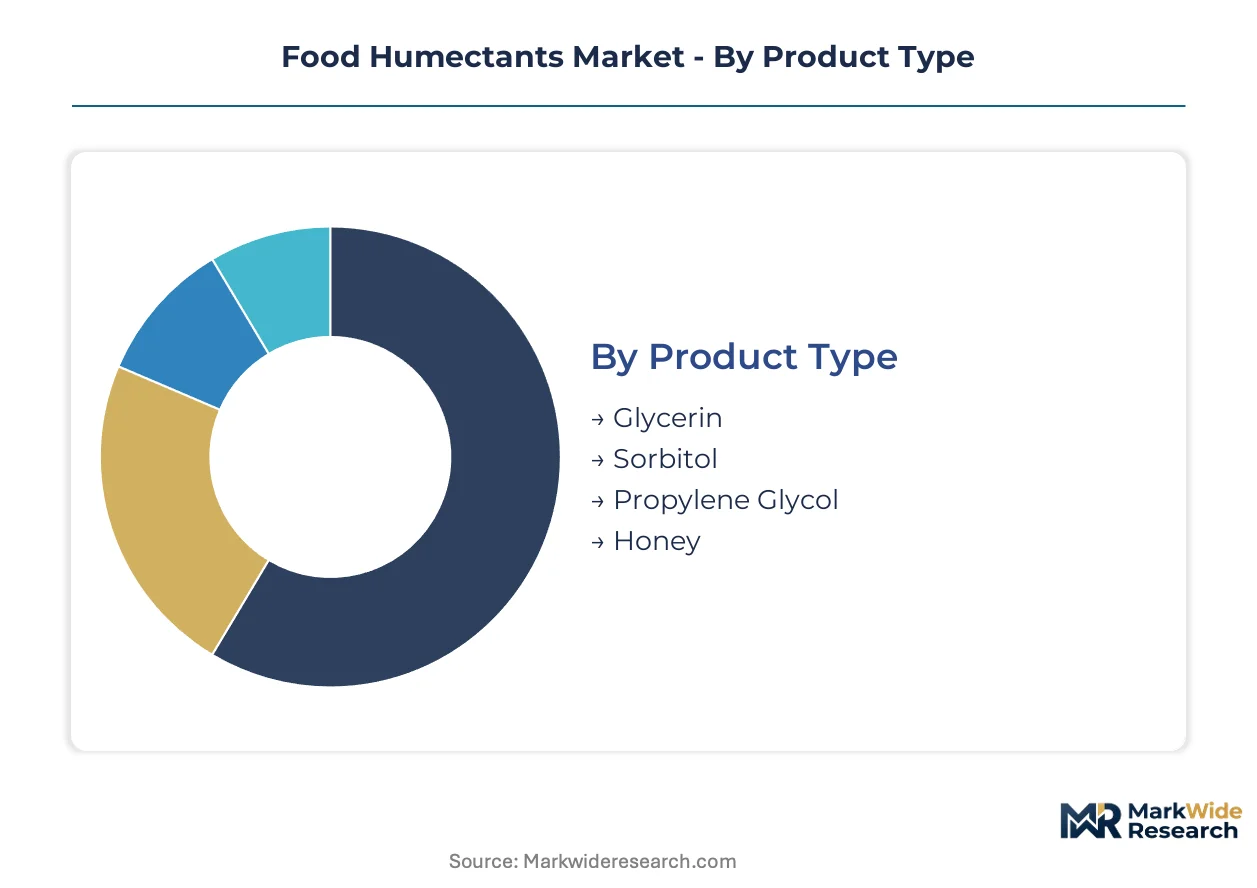
- Glycerin:A trihydric alcohol specified at 99.5% purity for pharmaceutical and food-grade applications through molecular distillation and activated carbon filtration. German industrial bakeries and dairy processors are pulling fermentation-derived supply into extended-shelf-life formulations as REACH dossier requirements harden. Most installed capacity flows through Glycerin. Expansion is steepest in Sorbitol.
- Sorbitol:A hexahydric sugar alcohol produced through catalytic hydrogenation of glucose, available in crystalline or liquid grades with specified moisture retention indices. Reduced-sugar confectionery manufacturers in France and Italy command premium positioning through crystallization control specifications that commodity glycerin cannot match.
- Propylene Glycol:Synthetic diol manufactured through hydration of propylene oxide, retaining cost-sensitive industrial confectionery volume despite clean-label substitution pressure from retail channel buyers.
- Honey:Natural syrup with enzymatic and floral provenance specifications, capturing artisan bakery segments where non-GMO and biobased certification commands procurement priority.
Product mix strategy separates fermentation-capable producers defending margin through purity premiums from petrochemical operators competing on unit economics.
Application:
Application-driven formulation requirements dictate humectant selection through moisture activity targets, water binding capacity, and shelf-life extension protocols.
- Baked Goods:Industrial bread and pastry production specifies glycerin for crumb softening and staling retardation across high-volume automated lines. German clean-label bakery chains are bypassing distributors to contract directly with certified fermentation producers for batch-traceable supply.
- Confectionery:Sugar-free candy formulations rely on sorbitol crystallization control to prevent graining and moisture migration during distribution. Western European retail channel growth in reduced-sugar segments is concentrating procurement among polyol specialists with ECHA-aligned dossier portfolios.
- Dairy Products:Processed cheese and yogurt applications require low-hygroscopicity humectants to prevent surface moisture accumulation during refrigerated distribution.
- Sauces:Viscosity-stable moisture retention in shelf-stable dressings and condiments favors liquid glycerin grades with specified refractive index ranges.
Baked Goods and Confectionery together concentrate volume demand. Dairy Products are gaining specification share fastest as clean-label processed food portfolios expand.
End User:
End-user procurement authority determines specification stringency, with direct manufacturers imposing purity and certification requirements that downstream channels cannot match.
- Food Manufacturers:Industrial processors with in-house R&D capabilities specify humectant grades through technical data sheet protocols and supplier audit programs. REACH and FDA multi-jurisdiction compliance is mandatory for qualified vendor status.
- Retailers:Private-label procurement teams are embedding carbon intensity scoring alongside traditional purity metrics, disintermediating commodity traders in favor of certified fermentation producers with verified biobased content.
- Hospitals:Clinical nutrition and therapeutic food applications require pharmaceutical-grade glycerin with full toxicological documentation.
- Restaurants:Foodservice channel specifications remain price-sensitive, with synthetic polyols retaining share in cost-driven segments.
Food Manufacturers control the majority of volume contracting. Retailers are restructuring procurement fastest through direct supplier engagement.
Form:
Physical form selection trades handling efficiency against dissolution kinetics, with dry formats commanding manufacturing flexibility premiums over liquid alternatives.
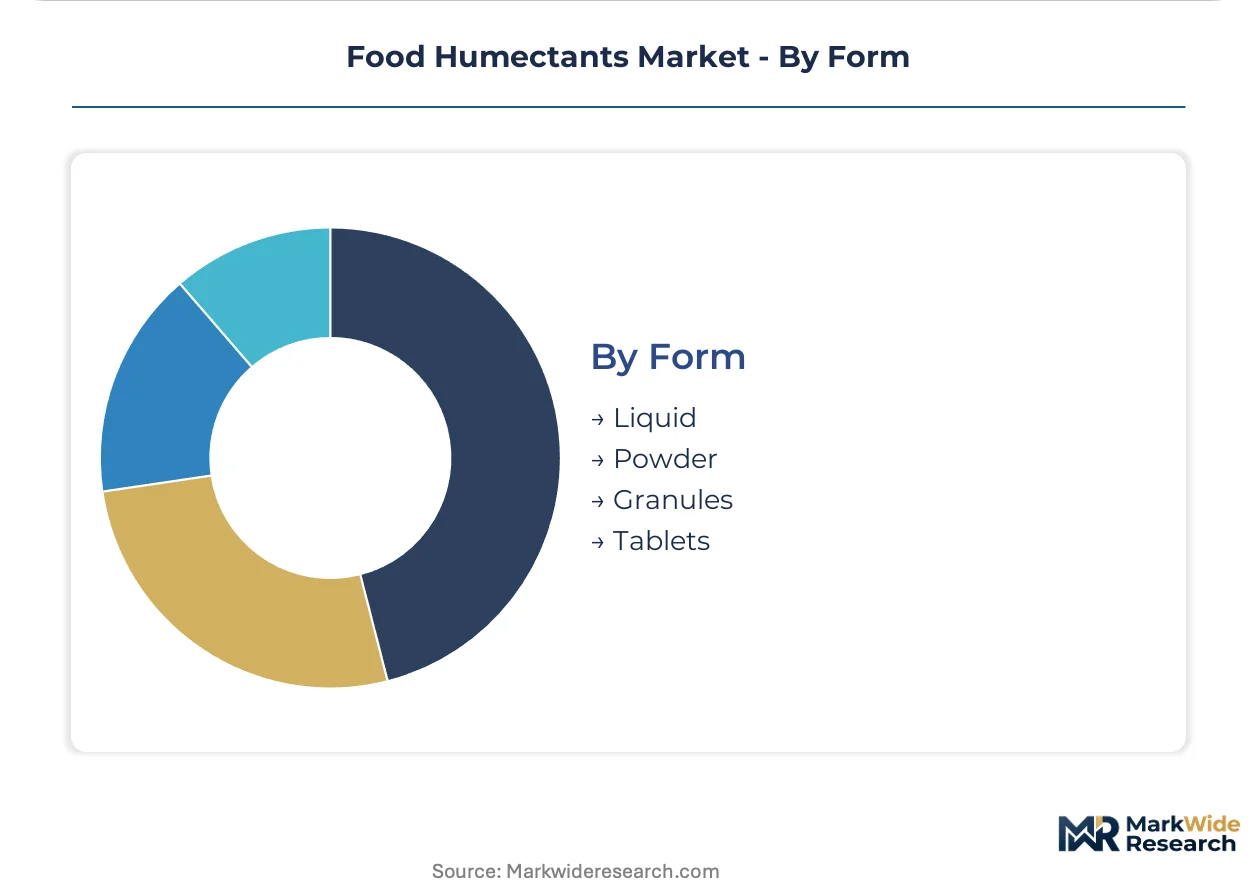
- Liquid:Standard bulk delivery format for high-volume industrial users with automated dosing infrastructure and tank storage capacity. Liquid glycerin dominates current volume flows through established supply chain configurations.
- Powder:Spray-dried or agglomerated formats enabling precise dry-blending in industrial bakery and confectionery operations without liquid handling equipment.
- Granules:Free-flowing crystalline sorbitol grades for reduced-sugar applications requiring controlled dissolution rates and reduced dusting versus powder alternatives.
- Tablets:Compressed unit-dose formats for specialized clinical nutrition and foodservice portion control applications.
Liquid formats retain the largest installed base. Powder and granule segments are expanding most quickly among dry-mix manufacturers seeking dosing precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands fermentation-derived glycerin capacity while the United States retains synthetic polyol infrastructure. France and Italy drive sorbitol specification in reduced-sugar confectionery. India enforces BIS-aligned purity thresholds that reshape import qualification protocols.
Germany
Industrial bakeries and dairy processors specify non-GMO glycerin for extended-shelf-life formulations. REACH dossier requirements mandate full toxicological profiling for polyol imports. Precision fermentation clusters in Baden-Württemberg and North Rhine-Westphalia are scaling commercial cell-line operations.
United States
FDA 21 CFR food additive regulations govern humectant safety for confectionery and baked goods applications. The agency maintains pharmaceutical-grade purity benchmarks for glycerin at 99.5% specification. Midwest industrial bakeries and Southeast dairy processors anchor domestic demand concentration.
France
Reduced-sugar confectionery manufacturers command premium sorbitol positioning through crystallization control specifications. ECHA evaluates updated hazard classifications for high-volume humectants under REACH substance registration. Lyon and Paris basin food manufacturers are consolidating procurement among ECHA-aligned dossier specialists.
India
FSSAI enforces BIS-aligned purity standards for glycerin used in processed foods and clinical nutrition applications. The regulator's import inspection windows add compliance layers atop existing FDA and REACH requirements. Maharashtra and Gujarat processed food corridors are driving specification upgrades among domestic suppliers.
Italy
Artisan and industrial bakers specify non-GMO glycerin for moisture retention in traditional and extended-shelf-life products. EU Green Deal biobased certification criteria harden procurement standards across retail channels. Emilia-Romagna and Lombardy bakery clusters are bypassing commodity traders for batch-traceable fermentation supply.
Food Humectants Market Vendor Landscape
Top-tier vendors anchor fermentation-derived glycerin capacity, while petrochemical-sourced polyol operators defend volume through price repositioning. The market structure concentrates among agricultural supply chain integrators, synthetic chemistry majors, and specialty polyol specialists. Three archetypes dominate: plant-derived glycerin producers leveraging crop processing infrastructure; high-purity synthetic grade manufacturers serving industrial confectionery; and pea starch polyol specialists targeting reduced-sugar applications. Competitive moves center on precision fermentation scale-up investments and direct retailer contracting to disintermediate distribution channels.
Among the named players, Cargill Incorporated and Archer Daniels Midland Company represent agricultural supply chain integrators with crop-derived glycerin positioning. BASF SE occupies a position within synthetic chemistry majors serving industrial volume requirements. Roquette Frères exemplifies the specialty polyol archetype through pea starch expertise for reduced-sugar formulation demand.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Roquette Frères |
| Ingredion Incorporated |
| BASF SE |
| Corbion N.V. |
| Ashland Global Holdings Inc. |
| Brenntag SE |
| DuPont Tate & Lyle Bio Products Company LLC |
| Others |
Supply Flow & Price Mechanics
Crude glycerin feedstock costs from biodiesel byproduct streams cascade through three pricing tiers: fermentation-derived pharmaceutical grades for German clean-label bakery chains, high-purity synthetic grades for industrial confectionery, and commodity petrochemical alternatives for cost-sensitive foodservice channels. REACH dossier compliance investments compress margins at the premium tier while crude supply volatility destabilizes cost structures for plant-derived producers.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for fermentation-derived glycerin as precision fermentation clusters scale commercial operations. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified pharmaceutical grades from industrial synthetic polyols and commodity imports. Price differentiation hinges on certification tier and biobased verification under EU Green Deal frameworks. Cost compression in the standard tier is intensifying because petrochemical operators defend volume through repositioning. Food manufacturers with direct R&D capabilities show least price sensitivity; foodservice distributors remain most cost-driven.
Supply Chain Analysis
Freight cost differentials between bulk liquid tanker shipments and containerized powder formats are shifting procurement patterns among dry-mix manufacturers. Supply concentrates in Germany, the United States, and India, with Baden-Württemberg fermentation hubs, Midwest biodiesel corridors, and Maharashtra processing zones anchoring regional flows. Raw material dependencies include crude glycerin from biodiesel production, glucose feedstocks for sorbitol hydrogenation, and propylene oxide for synthetic diol manufacture. Single-source vulnerability runs through German precision fermentation capacity for pharmaceutical-grade supply. Distribution runs through certified producer-direct contracts that disintermediate commodity traders for batch-traceable glycerin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food Humectants Market operates as a geographic-arbitrage play between REACH-regulated European premiums and FSSAI-compliant Indian import opportunities, with certification cost differentials creating margin capture potential for multi-jurisdiction qualified suppliers.
For Market Incumbents: Deploy backward integration into precision fermentation infrastructure to secure pharmaceutical-grade capacity ahead of REACH dossier hardening. Cargill Incorporated and BASF SE should consolidate supplier audit programs to capture disintermediated retailer contracts bypassing commodity traders. Defend margin pools in reduced-sugar confectionery through crystallization control IP that commodity glycerin cannot replicate. For New Entrants and Emerging Players: Capture white-space in Nordic functional food markets where pea starch-derived polyol demand outpaces Roquette Frères capacity expansion. Target dry-mix manufacturer channels with spray-dried glycerin formats that eliminate liquid handling infrastructure requirements. Position through EU Green Deal biobased certification as a procurement threshold for retail channel entry. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction compliance costs exceed standalone producer returns, favoring acquisition of FSSAI-aligned Indian suppliers by REACH-certified European platforms. Fermentation-capable assets with pharmaceutical-grade purification systems represent the priority acquisition archetype. Watch for ECHA hazard classification updates as inflection signals for reformulation-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Commercial cell-line optimization in Baden-Württemberg compresses cost gaps with petrochemical glycerin. |
| REACH Dossier Pre-Submission | ECHA-aligned toxicological profiling secures uninterrupted supply continuity for German industrial bakeries. |
| Dry-Format Product Line Expansion | Spray-dried glycerin captures dosing precision demand from industrial bakery dry-mix operations. |
| Direct Retailer Contracting | Batch-traceable supply agreements disintermediate commodity traders for EU Green Deal verified biobased content. |
| Pea Starch Polyol Capacity Addition | Specialty sorbitol expansion targets reduced-sugar confectionery crystallization control premiums in France and Italy. |
Methodological Framework
Coverage spans Germany, the United States, France, Italy, and India, with primary inputs from each market cluster combining interviews with fermentation plant managers, industrial bakery procurement leads, confectionery R&D directors, and FSSAI regulatory affairs specialists. Secondary validation draws from REACH substance registration databases, FDA 21 CFR food additive filings, ECHA hazard classification updates, and customs trade flows for glycerin and sorbitol shipments. Bottom-up capacity modeling and top-down demand triangulation anchor volume and value estimates.
Rate-of-change decomposition across the projection horizon segments the market by product type, application, end-user procurement authority, and physical form. CAGRs derive from weighted capacity expansion timelines, regulatory compliance cost trajectories, and substitution elasticity between fermentation-derived and petrochemical feedstocks. Forecast inputs include precision fermentation yield improvements, REACH dossier approval velocities, and retailer biobased procurement threshold adoption curves.
Crude glycerin supply disruptions, ECHA hazard reclassification decisions, and FSSAI inspection window delays are the dominant revision risks that could compress or extend adoption timelines. Forecasts reflect assumptions about regulatory stability and feedstock cost convergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Carob Gum Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Sustained Release Excipients Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Germany Anticaking Market