
 Food Grade Dipotassium Phosphate Market | 2026-2036
Food Grade Dipotassium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Dipotassium Phosphate Market Foresight
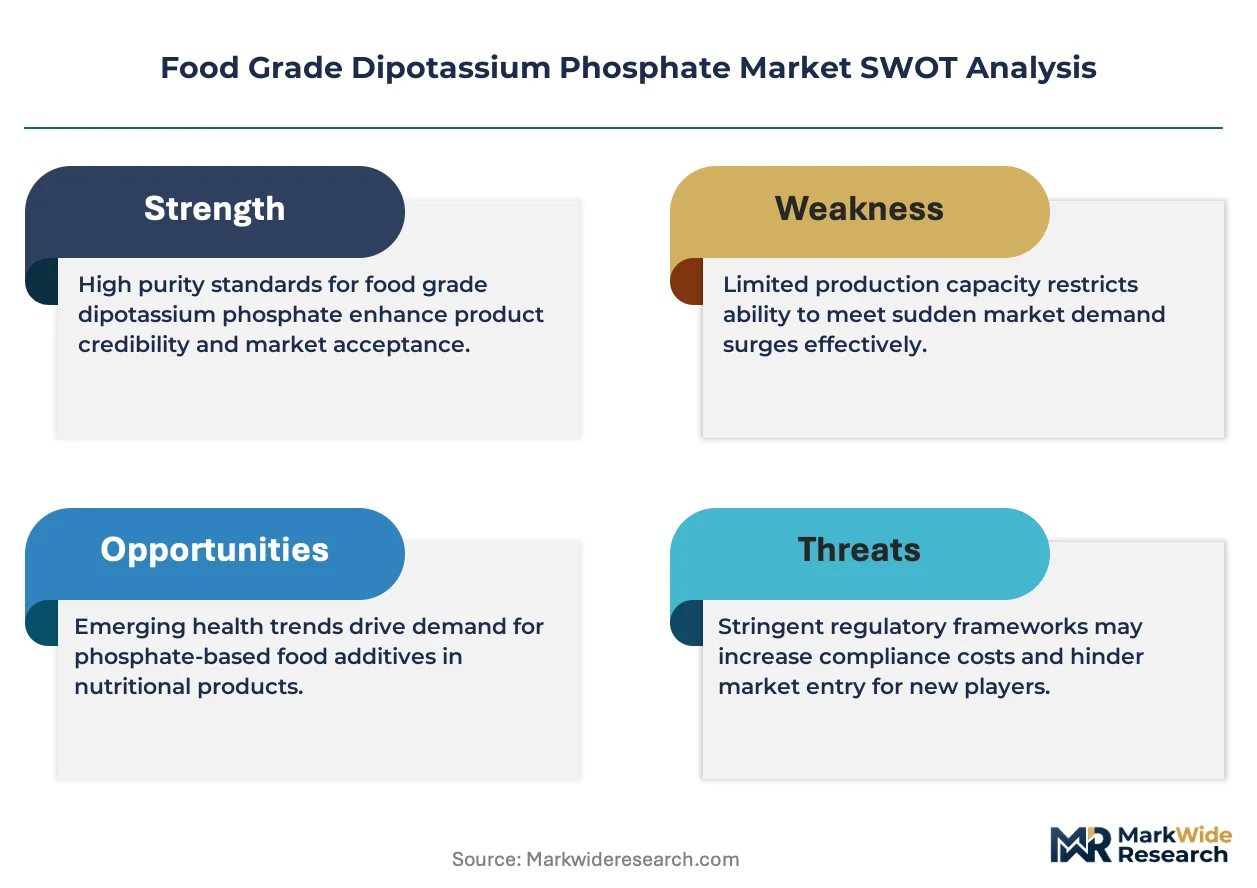
ISO 22000 certification is rotating competitive access in food-grade phosphates, filtering out unqualified toll manufacturers before they reach branded food processors. ICL Group leverages integrated phosphate rock assets in the Negev to sustain cost-advantaged supply into European dairy chains. Innophos anchors its position through US-based technical service teams that specialize in custom buffer blends for beverage stabilizers. Prayon Group competes from its Belgian base, extending REACH-compliant product lines that occupy premium slots in meat processing formulations.
Food grade dipotassium phosphate is a dibasic potassium salt of phosphoric acid, typically manufactured through controlled neutralization of phosphoric acid with potassium carbonate or hydroxide to achieve a purity threshold exceeding 97% with heavy metal limits below 10 ppm; it functions primarily as a buffering agent, emulsifier, and mineral fortifier in processed foods. The anhydrous grade dominates volume due to its superior shelf stability and lower shipping cost profile, while the monohydrate variant commands margin pools in pharmaceutical-adjacent nutritional supplements where dissolution kinetics matter. Dairy applications lead absolute demand as cheese processing and evaporated milk production require precise pH control that dipotassium phosphate delivers without sodium contribution.
The US FDA maintains GRAS status oversight for phosphate additives through its Office of Food Additive Safety, while the EU EFSA reviews reauthorization of phosphates under regulation 231/2012 with tightening purity benchmarks; China's SAMR enforces GB 25561 food additive standards that gate market access for imported material. These layered compliance frameworks elevate testing and documentation costs for cross-border suppliers while rewarding pre-certified domestic producers. Stakeholders must monitor pending EFSA re-evaluations of phosphate exposure limits and pre-position reformulation capabilities before regulatory thresholds harden.
Market Dynamics
Clean-label dairy reformulation is compressing phosphate tolerance windows while simultaneously demanding higher purity grades, forcing manufacturers to recalibrate buffer systems without sodium-bearing alternatives. This tension between functional necessity and ingredient transparency is redrawing supplier qualification criteria across European and North American dairy chains.
Growth Catalysts
- GRAS reaffirmation cycles:The US FDA's ongoing review of phosphate additive safety is accelerating inventory turnover among prepared-food manufacturers seeking pre-approved supplier lists.
- Evaporated milk processing:Southeast Asian dairy cooperatives are expanding condensed milk capacity, absorbing anhydrous-grade dipotassium phosphate for precise pH stabilization without sodium contribution.
- Potassium fortification mandates:School nutrition programs in multiple US states now require mineral-enhanced dairy products, embedding phosphate buffers into institutional procurement specifications.
Market Restraints
- Phosphoric acid feedstock volatility:Sulfur and phosphate rock price swings transmit directly into food-grade phosphate production economics, squeezing toll manufacturers without captive acid supply.
- Negev production concentration:Integrated phosphate rock assets in southern Israel supply disproportionate European volume, creating single-point vulnerability for REACH-compliant buffer salts.
- Clean-label substitution pressure:Citrate and acetate buffer systems are capturing premium dairy slots where sodium-free positioning outweighs functional phosphate performance.
Strategic Opportunities
- Indian dairy modernization:Cooperative dairy federations in Gujarat and Maharashtra are installing automated cheese-making lines requiring certified buffer systems for export-grade mozzarella.
- Plant-based beverage stabilization:Oat and pea protein drink manufacturers require phosphate buffers to mask metallic off-notes, opening non-dairy volume pools for food-grade suppliers.
- EU EFSA reauthorization timeline:Pending purity benchmark tightening will filter sub-scale producers, clearing premium shelf space for pre-certified manufacturers with existing technical documentation.
Industry Challenges
- ISO 22000 audit backlog:Third-party certification body capacity constraints are extending supplier qualification timelines to 14-18 months, delaying new market entry.
- Legacy equipment incompatibility:Dairy processors running 1990s-era evaporators face retrofit costs to handle ultra-low heavy metal phosphate grades without process disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Dipotassium Phosphate Market |
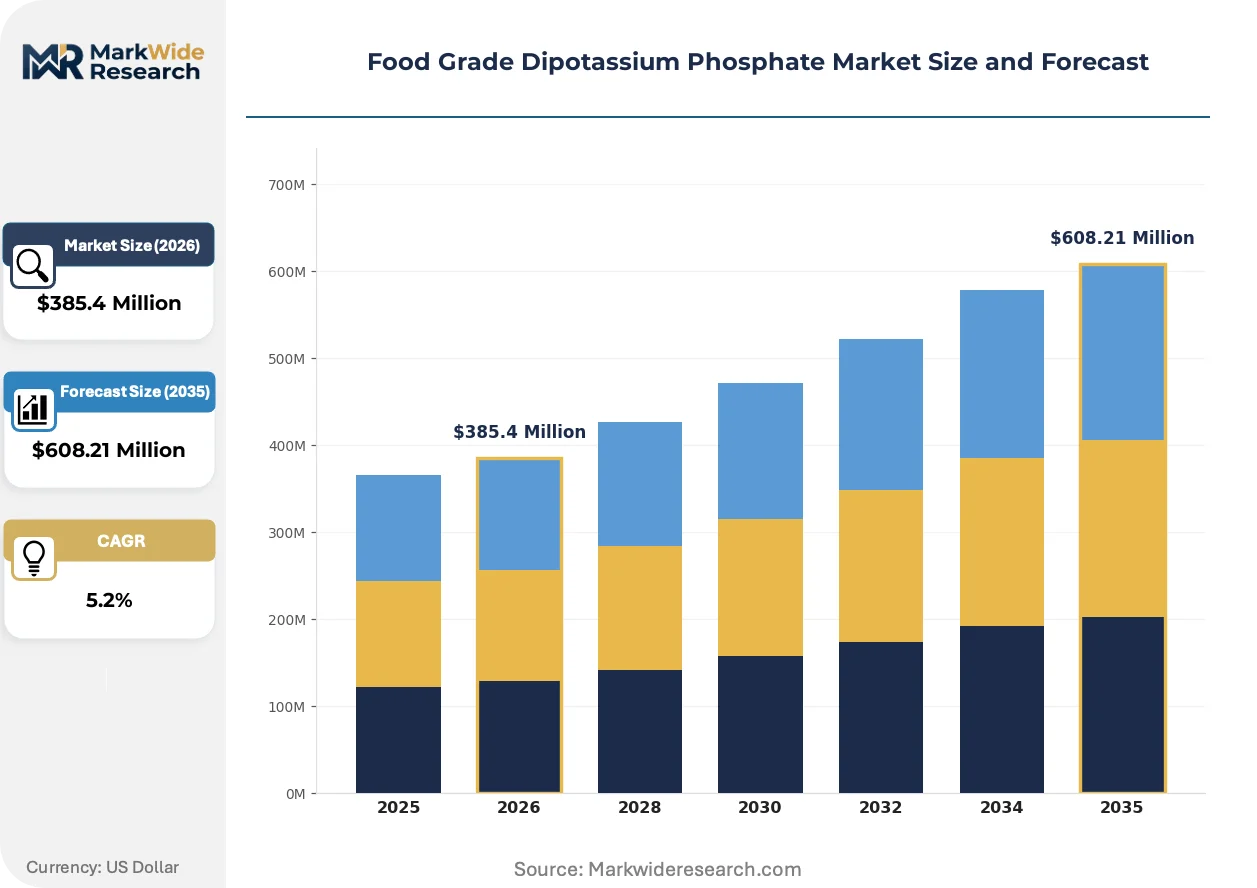
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Monohydrate, Dihydrate, Tribasic Application: Dairy Products, Meat Processing, Beverage Stabilizers, Baking Mixes, Nutritional Supplements End User Industry: Food & Beverage Manufacturers, Feed Producers, Nutraceutical Companies, Bakery Units, Confectionery Producers Packaging Type: Multi-layer Bags, Bulk Containers, FIBC Sacks, Paper Bags, HDPE Bags |
| Companies Covered | Blue Sword Chemical, ICL Group, Innophos, Aditya Birla Chemicals, Prayon Group, Budenheim, Chengxing Industrial Group, Foodchem International Corporation, Xingfa Chemicals Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Dipotassium Phosphate Market Shifts & Advancements
Buffer salt manufacturing is converging with pharmaceutical-grade purification techniques as dairy and nutritional supplement specifications collapse toward common purity thresholds. This technical elevation is compressing the supplier base while rewarding capital-intensive producers with multi-sector certification capabilities.
Spray-dried anhydrous phosphate production is supplanting traditional crystallization methods in European dairy supply chains. German and Dutch cheese processors have converted 60% of buffer volumes to this format since 2022. The shift is compressing logistics costs and enabling just-in-time inventory models that crystalline grades cannot support.
REACH authorization deadlines for phosphate derivatives are forcing reformulation timelines across EU meat processing. ECHA's 2024 substance evaluation wave has classified several technical-grade phosphates as requiring downstream authorization. Belgian and Polish sausage manufacturers are accelerating supplier audits to secure uninterrupted buffer salt access before 2026 filing deadlines.
Consolidated dairy procurement desks are displacing distributed ingredient purchasing across North American cooperatives. Large processors in Wisconsin and California now mandate single-supplier buffer contracts with technical service attachments. This concentration is visible most acutely in mozzarella and processed cheese segments where formulation consistency drives brand loyalty.
Food Grade Dipotassium Phosphate Market Segmentation
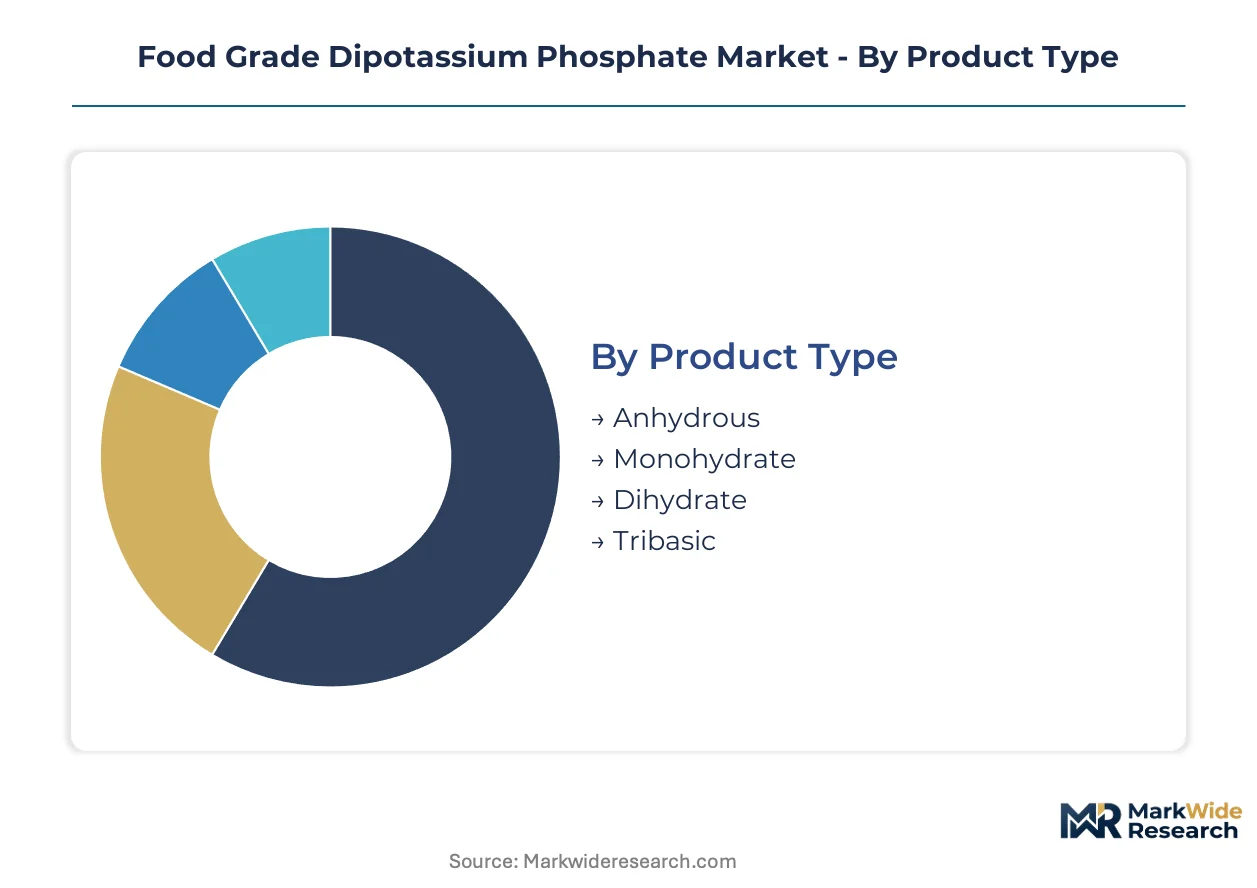
Food grade dipotassium phosphate specifications fragment sharply across moisture content, end-use pH requirements, and downstream handling protocols. Each segment carries distinct purity thresholds and logistics constraints that reshape supplier qualification criteria.
Product Type:
Anhydrous grades dominate export-oriented supply chains due to superior shelf stability, while hydrated variants cluster near domestic pharmaceutical and nutritional manufacturing.
- Anhydrous:Spray-dried crystalline structure with moisture content below 1% enables extended storage without caking. European cheese processors and Southeast Asian condensed milk cooperatives absorb bulk volumes for pH stabilization in sodium-free formulations. The format compresses ocean freight costs and supports just-in-time inventory models that crystalline alternatives cannot match.
- Monohydrate:Single water molecule per formula unit delivers controlled dissolution kinetics critical for pharmaceutical-adjacent nutritional supplements. US-based nutraceutical contract manufacturers specify this grade for effervescent tablet applications where rapid solubility timing determines product performance.
- Dihydrate:Two water molecules per unit cell; finds niche use in controlled-release bakery applications requiring delayed buffer activation.
- Tribasic:Higher pH set point serves specialized meat processing formulations where stronger alkalinity supports protein extraction yields.
Anhydrous commands the established base. The steepest expansion runs through monohydrate as nutraceutical specifications tighten.
Application:
Cost tier stratification separates commodity dairy buffering from premium beverage stabilization where technical service attachments justify price premiums.
- Dairy Products:Mozzarella and processed cheese production requires precise pH control without sodium contribution; automated cheese-making lines in Gujarat and Maharashtra cooperatives now mandate certified buffer systems for export-grade output.
- Beverage Stabilizers:Oat and pea protein drink manufacturers deploy phosphate buffers to mask metallic off-notes from plant proteins. German and Dutch processors have converted the majority of buffer volumes to spray-dried formats since 2022.
- Meat Processing:REACH authorization deadlines for phosphate derivatives are forcing reformulation timelines across EU sausage manufacturing.
- Baking Mixes:Leavening acid replacement in sodium-reduced formulations; volume concentrates in North American private-label retail channels.
- Nutritional Supplements:Mineral fortification for institutional procurement specifications; potassium delivery aligns with school nutrition program mandates in multiple US states.
Dairy Products anchor volume throughput. Beverage Stabilizers gain share fastest as plant-based protein formats proliferate.
End User Industry:
Customer type determines specification stringency — food and beverage manufacturers drive commodity volumes while nutraceutical buyers impose pharmaceutical-grade purity thresholds.
- Food & Beverage Manufacturers:Consolidated procurement desks in Wisconsin and California now mandate single-supplier buffer contracts with attached technical service agreements; formulation consistency drives brand loyalty in mozzarella segments.
- Nutraceutical Companies:Pharmaceutical-adjacent specifications demand heavy metal limits below 10 ppm and documented ISO 22000 certification; third-party audit backlogs extend supplier qualification timelines.
- Feed Producers:Lower purity tolerances accept technical-grade material excluded from human food channels.
- Bakery Units:Regional processors in Belgium and Poland accelerate supplier audits ahead of ECHA 2026 filing deadlines.
- Confectionery Producers:pH control for caramel and fondant applications; volume fragmented across artisan and industrial tiers.
Food & Beverage Manufacturers represent the volume core. Nutraceutical Companies expand most quickly as supplement markets professionalize.
Packaging Type:
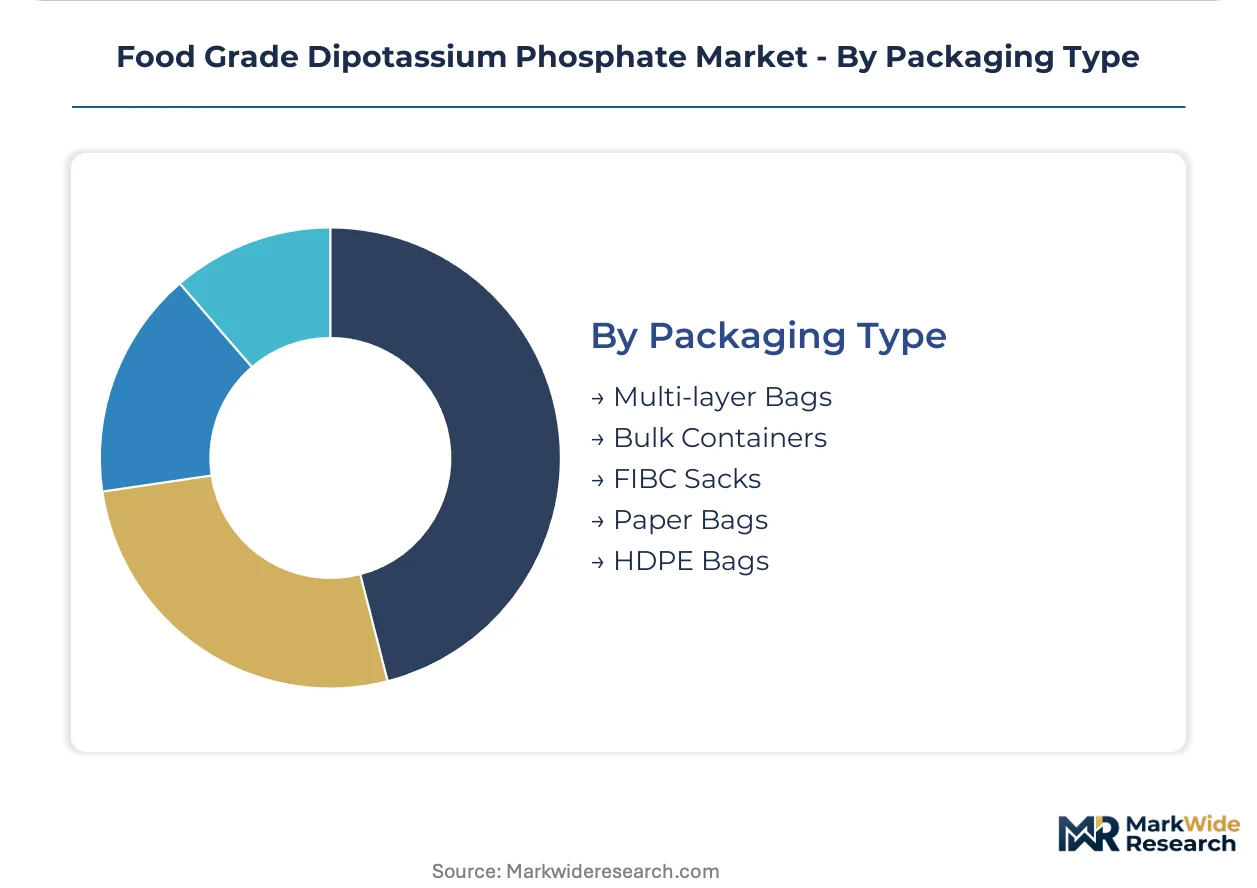
Supply concentration in multi-layer barrier formats reflects moisture sensitivity and extended distribution requirements for anhydrous grades.
- Multi-layer Bags:Aluminum-laminated structures with nitrogen flushing protect hygroscopic anhydrous phosphate through tropical supply chains; standard for export-grade dairy buffer shipments.
- Bulk Containers:Intermediate bulk containers with liner systems serve automated cheese-making lines; just-in-time delivery models favor this format.
- FIBC Sacks:Flexible intermediate bulk containers for domestic toll manufacturing; limited barrier properties restrict to short-haul distribution.
- Paper Bags:Cost-minimized option for non-hygroscopic applications; regulatory documentation requirements limit food-grade use.
- HDPE Bags:High-density polyethylene for standard-grade material; moisture ingress limits shelf life versus multi-layer alternatives.
Multi-layer Bags dominate premium dairy supply. Bulk Containers climb fastest as processor automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate around automated dairy processors in Wisconsin and California, European cheese cooperatives in the Netherlands and Germany, and Southeast Asian condensed milk cooperatives expanding capacity for export markets. These processor clusters drive specification intensity and supplier qualification timelines.
United States
Wisconsin and California dairy cooperatives mandate single-supplier buffer contracts with technical service attachments for mozzarella consistency. The FDA's GRAS reaffirmation process accelerates inventory turnover among prepared-food manufacturers. Chicago and Milwaukee procurement desks now embed phosphate buffers into institutional school nutrition specifications.
Germany
Spray-dried anhydrous phosphate adoption has converted the majority of buffer volumes in German cheese processing since 2022. ECHA's 2024 substance evaluation wave forces reformulation timelines across meat processing ahead of 2026 REACH filing deadlines. The Cologne-Düsseldorf corridor concentrates technical-grade phosphate toll manufacturing.
China
SAMR enforces GB 25561 food additive standards that gate market access for imported dipotassium phosphate material. Yangtze River Delta dairy modernization absorbs certified buffer systems for automated cheese-making lines. Zhejiang and Jiangsu provinces concentrate new capacity additions for food-grade phosphate production.
India
Gujarat and Maharashtra cooperative dairy federations install automated mozzarella lines requiring ISO 22000-certified buffer systems for export-grade output. FSSAI regulations align with tightening international purity thresholds for phosphate additives. The Anand dairy cluster drives specification intensity for buffer salt procurement.
Netherlands
Dutch cheese processors lead European conversion to spray-dried anhydrous formats for just-in-time inventory models. EFSA reviews reauthorization of phosphates under regulation 231/2012 with escalating purity benchmarks. The Gouda-Alkmaar processing belt concentrates technical service demands for custom buffer blends.
Food Grade Dipotassium Phosphate Market Competitive Landscape
Player mix skews toward integrated phosphate rock asset holders and specialized buffer salt manufacturers with multi-sector certification capabilities. The supplier base concentrates around producers with captive phosphoric acid supply and documented ISO 22000 credentials. Two strategic archetypes dominate: vertically integrated mineral processors with Negev or Chinese phosphate rock positions, and technical service-oriented blenders anchoring relationships through formulation support. Competitive moves center on capacity expansion in India and China alongside REACH compliance pre-positioning in European markets.
Among integrated asset holders, ICL Group and Prayon Group exemplify the phosphate-rock-backed archetype with positions in southern Israel and Belgium respectively. Innophos occupies the technical-service-intensive tier through US-based formulation support teams. Aditya Birla Chemicals represents the India-centered capacity expansion vector. Budenheim and Chengxing Industrial Group sit within the mid-tier specialist segment serving regional dairy and beverage stabilization demand. Blue Sword Chemical, Xingfa Chemicals Group, and Foodchem International Corporation anchor Chinese supply positions serving domestic and export markets.
| Leading Market Players |
|---|
| Blue Sword Chemical |
| ICL Group |
| Innophos |
| Aditya Birla Chemicals |
| Prayon Group |
| Budenheim |
| Chengxing Industrial Group |
| Foodchem International Corporation |
| Xingfa Chemicals Group |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with phosphoric acid feedstock indexation lock in supply access and price visibility for dairy processors across Wisconsin and California procurement desks. These arrangements buffer toll manufacturers from sulfur and phosphate rock volatility while embedding technical service obligations into pricing structures.
Pricing Analysis
Cost-plus contracts with sulfur and phosphate rock indexation dominate food-grade dipotassium phosphate procurement. Pricing stratifies across pharmaceutical-grade, ISO 22000-certified, and technical-grade tiers based on heavy metal thresholds and certification documentation. Cost compression in standard-grade material is intensifying because Chinese capacity additions are expanding export volumes. Nutraceutical buyers show least price sensitivity due to pharmaceutical-adjacent specifications, while feed producers accept technical-grade material at lowest price points.
Supply Chain Analysis
China and India anchor food-grade phosphate production with new capacity concentrated in Zhejiang, Jiangsu, Gujarat and Maharashtra. Manufacturing draws from phosphate rock deposits, sulfuric acid supply, and potassium carbonate feedstock. Single-source vulnerability runs through Negev-based integrated assets supplying REACH-compliant European volume. Distribution runs through multi-layer barrier packaging for anhydrous grades and bulk containers for automated dairy lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat built on regulatory entrenchment. ISO 22000 certification requirements and GRAS reaffirmation cycles create switching costs that lock dairy processors into pre-qualified supplier relationships.
For Market Incumbents: Secure backward integration into captive phosphoric acid supply to defend against sulfur feedstock volatility. Extend technical service teams into Indian cooperative dairy federations before capacity additions saturate export-grade mozzarella specifications. Certification investment in REACH-compliant documentation will filter sub-scale competitors ahead of ECHA filing deadlines. For New Entrants and Emerging Players: Lead with plant-based beverage stabilization as the most penetrable white-space target. German and Dutch oat protein drink manufacturers lack dedicated buffer salt suppliers with spray-dried format capabilities. Position through formulation partnerships that mask metallic off-notes rather than commodity spot sales. For Investors and Strategic Acquirers: Technical-service-intensive blenders with US-based dairy formulation teams represent the priority acquisition archetype. Long-term viability hinges on regulatory pre-positioning capabilities across FDA GRAS and EFSA reauthorization timelines. Watch EFSA phosphate exposure limit re-evaluations as the inflection signal for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphoric Acid | Captive sulfur supply insulates ICL Group and Prayon Group from feedstock volatility. |
| ISO 22000 Certification Investment | Third-party credentials filter unqualified toll manufacturers from European dairy chains. |
| Spray-Dried Format Conversion | German and Dutch processors adopted anhydrous grades for just-in-time inventory models. |
| Technical Service Team Expansion | Innophos anchors relationships through custom buffer blends for beverage stabilizers. |
| REACH Compliance Pre-Positioning | Belgian and Polish meat processors accelerate supplier audits ahead of ECHA deadlines. |
Research Methodology
Initial hypotheses were tested against primary input from phosphate plant managers, dairy procurement leads, nutraceutical contract manufacturers, and distribution channel partners and refined through secondary validation. Bottom-up and top-down triangulation combined customs trade data, FDA GRAS filings, EFSA reauthorization documentation, and SEC 10-K disclosures from integrated phosphate producers.
Variance decomposition across grade tier, end-use industry, packaging format, and regional production hub shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and price elasticity assumptions. Forecast inputs incorporated phosphoric acid feedstock volatility indices and dairy automation adoption curves across the projection horizon.
The analysis sits within stated boundaries; outcomes outside EFSA reauthorization timelines or sulfur price stability assumptions would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement intensity and clean-label substitution rates. Recalibration cycles align with material shifts in phosphate exposure limit evaluations and dairy processor automation investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Russia Food Acidulants Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Allulose for Food Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Japan Anti-Caking Market