
 India Animal Protein Market | 2026-2036
India Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
India Animal Protein Market Foresight
Multi-source procurement among dairy and meat processors is rebalancing toward contracted livestock farming and cooperative supply networks. Amul Dairy anchors its dominance through Gujarat's cooperative milk grid, while Godrej Agrovet Limited leverages integrated poultry and animal feed operations across Andhra Pradesh and Telangana. Parag Milk Foods sustains its position via specialized cheese and whey processing facilities in Maharashtra.
Animal protein encompasses structurally complete proteins derived from livestock, poultry, and aquatic species, containing essential amino acid profiles with biological value scores typically exceeding 75% for egg and dairy sources. These proteins serve as foundational inputs for human nutrition, sports nutrition formulations, and processed food manufacturing. Poultry leads product type volume due to lower feed conversion ratios and shorter production cycles, while seafood commands premium positioning in export channels. Fresh processing retains the largest share of household and restaurant offtake, though frozen methods gain traction among online retail platforms serving tier-two cities.
The Food Safety and Standards Authority of India mandates hygiene ratings and contaminant thresholds that reshape processing investments, while BIS certification requirements for packaged meat products filter smaller unorganized operators from modern retail shelves. The Bureau of Indian Standards periodically revises quality parameters for frozen and dried protein products, forcing capital upgrades among mid-scale processors. Stakeholders must weigh cooperative supply integration against independent cold-chain buildouts as urban demand fragmentation accelerates.
Market Dynamics
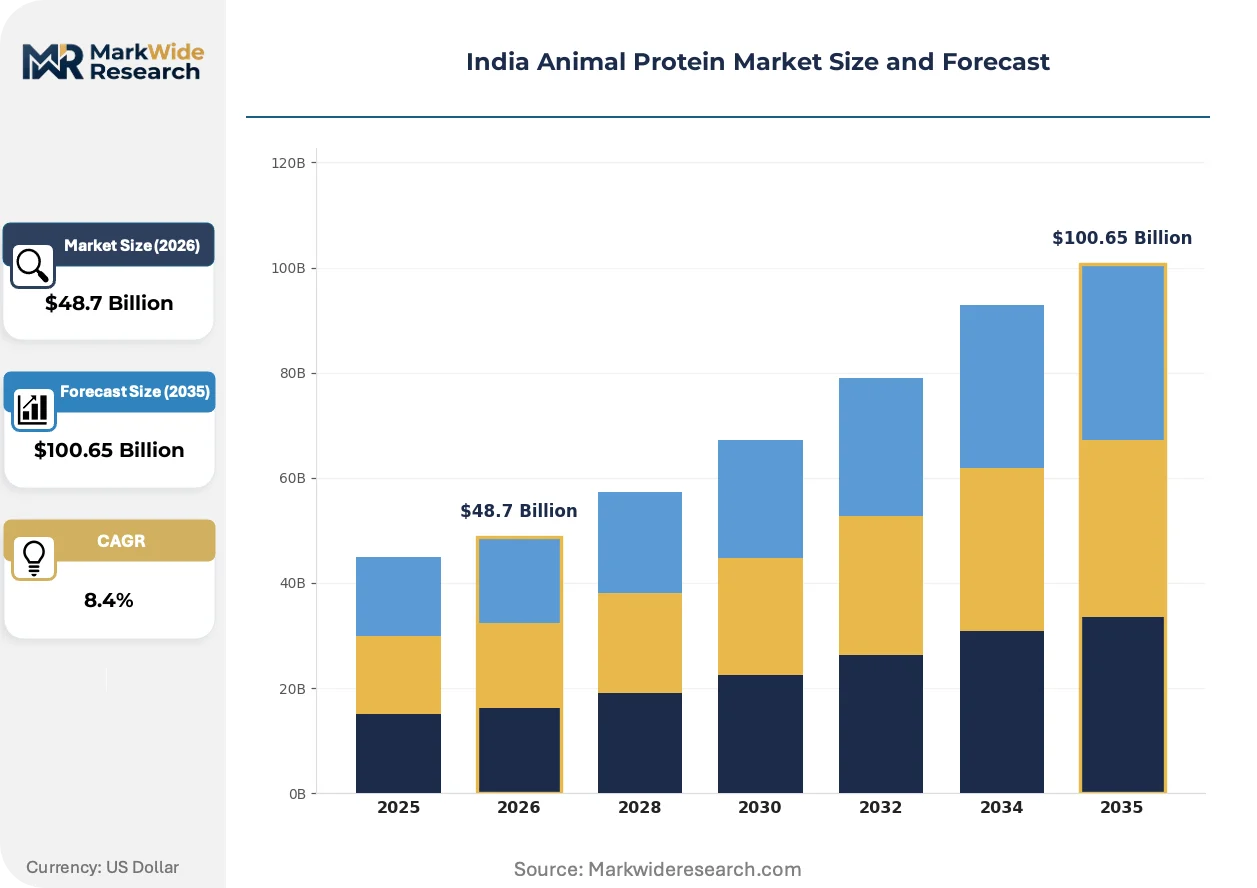
The FSSAI hygiene rating mandate and BIS certification requirements are compressing the unorganized segment while channeling investment toward integrated cold-chain infrastructure and cooperative supply networks.
Growth Catalysts
- Urban Protein Demand:Mumbai, Delhi NCR, and Bangalore households are diversifying protein baskets beyond traditional dairy into poultry and seafood categories.
- Export Channel Expansion:Frozen processing methods are capturing premium positioning in seafood export corridors, with cold-chain investments tracking online retail penetration into tier-two cities.
- FSSAI Enforcement:Stricter labeling and hygiene protocols are filtering sub-scale operators from modern retail shelves, consolidating volume toward compliant processors.
Market Restraints
- Feed Input Volatility:Maize and soybean meal price swings compress poultry processor margins and destabilize production planning across Andhra Pradesh and Telangana operations.
- Cold-Chain Capital Intensity:Fresh distribution requirements demand continuous refrigeration infrastructure that smaller Maharashtra and Gujarat operators cannot finance.
- Regulatory Compliance Burden:Periodic BIS revisions for frozen and dried protein products force capital upgrades among mid-scale processors with limited balance sheet capacity.
Strategic Opportunities
- Cooperative Supply Integration:Gujarat's cooperative milk grid model offers replicable architecture for poultry and seafood procurement consolidation.
- Sports Nutrition Formulations:Whey protein isolates and specialized dairy derivatives are penetrating fitness and clinical nutrition channels.
- PLI Scheme Alignment:Food processing infrastructure incentives under India's production-linked incentive framework subsidize cold-chain and packaging technology adoption.
Industry Challenges
- Veterinary Skill Scarcity:Qualified livestock health professionals are concentrated in academic centers rather than field operations across rural production belts.
- Certification Timeline Compression:FSSAI hygiene ratings and BIS mark acquisition cycles lag capacity expansion schedules, delaying market access for new facilities.
- Legacy System Integration:Cooperative milk grids and independent meat processors operate on incompatible ERP platforms, blocking unified supply visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Animal Protein Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Seafood End User: Restaurants, Households, Food Service, Exporters Distribution Channel: Online Retail, Supermarkets, Local Markets, Wholesale Processing Method: Fresh, Frozen, Canned, Dried |
| Companies Covered | Arla Foods, Mother Dairy, Fonterra Co-operative Group Limited, Karnataka Milk Federation, Parag Milk Foods, Glanbia PLC, Amul Dairy, Godrej Agrovet Limited, Kerry Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Animal Protein Market Shifts & Advancements
Processing technology and distribution architecture are converging to compress spoilage windows and fragment procurement authority across buyer tiers.
Advanced blast freezing and modified atmosphere packaging is absorbing moisture migration risk in seafood and premium poultry segments. Hotel chains and organized retail buyers in Bangalore and Mumbai are specifying these technologies in procurement contracts. The capital deployment is absorbing smaller fresh-only processors into contract manufacturing relationships with integrated operators.
FSSAI's contaminant threshold revisions and mandatory hygiene rating displays are restructuring processing floor layouts and HACCP documentation requirements. Mid-scale meat and dairy facilities in Maharashtra are reconfiguring production lines ahead of enforcement windows. The compliance burden is absorbing engineering resources that previously targeted capacity expansion.
Restaurant offtake is fragmenting into direct-procurement relationships with integrated farms, bypassing traditional mandi intermediaries. Cloud kitchen operators in Delhi NCR are negotiating weekly contract volumes with certified poultry farms. The disintermediation is compressing price discovery transparency and shifting credit risk onto farm-gate suppliers.
India Animal Protein Market Segmentation
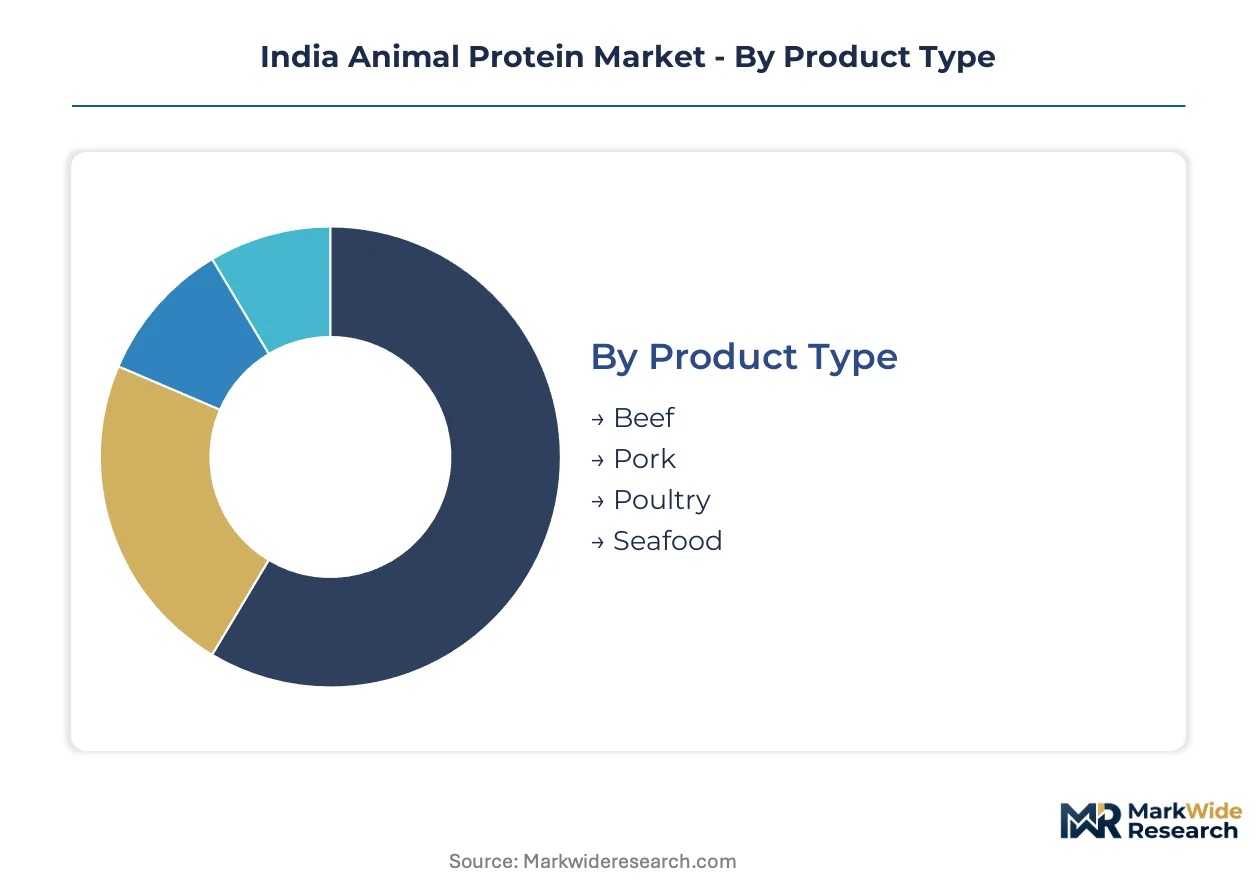
India's animal protein market fragments along production technology, consumption occasion, and distribution infrastructure axes. Each segmentation layer reveals distinct margin structures and regulatory exposure that processors must navigate across Maharashtra, Gujarat, and southern production belts.
Product Type:
Biological value scores and feed conversion efficiency separate protein categories on cost-competitiveness and nutritional positioning.
- Poultry:Delivers complete essential amino acid profiles with biological values exceeding 75% and the shortest production cycles among livestock categories. Demand concentrates in Mumbai and Delhi NCR households where cold-chain reliability supports daily fresh distribution, though feed input volatility from maize and soybean meal price swings compresses processor margins.
- Seafood:Commands premium positioning in export corridors through blast freezing and modified atmosphere packaging that extends shelf stability for international shipment. Frozen processing investments track online retail penetration into Bangalore and tier-two cities, with FSSAI contaminant thresholds forcing HACCP documentation upgrades ahead of enforcement windows.
- Beef:Faces restricted distribution in several states due to varying slaughter regulations, concentrating supply in permitted processing zones.
- Pork:Serves niche consumption pockets with limited organized retail presence outside northeastern and Goan markets.
Poultry leads on scale; seafood leads on momentum.
End User:
Procurement authority and volume predictability vary sharply across buyer tiers, reshaping contract structures and credit terms.
- Restaurants:Cloud kitchen operators in Delhi NCR negotiate weekly contract volumes directly with certified poultry farms, bypassing traditional mandi intermediaries and compressing price discovery transparency while shifting credit risk onto farm-gate suppliers.
- Households:Urban clusters in Mumbai, Bangalore, and Delhi NCR diversify protein baskets beyond traditional dairy into poultry and seafood categories, with fresh processing retaining dominant share though frozen methods gain traction through online platforms.
- Food Service:Hotel chains specify advanced blast freezing and modified atmosphere packaging in procurement contracts, absorbing smaller fresh-only processors into contract manufacturing relationships.
- Exporters:Frozen seafood shipments face BIS certification requirements and periodic quality parameter revisions that filter sub-scale operators from modern retail shelves.
Households anchor volume absorption; restaurants drive procurement innovation.
Distribution Channel:
Cold-chain capital intensity and regulatory compliance burden stratify channel access by processor scale.
- Supermarkets:Modern retail shelves in Maharashtra and Gujarat enforce FSSAI hygiene rating displays and BIS mark requirements that consolidate volume toward compliant processors with documented HACCP systems.
- Online Retail:Frozen processing methods capture premium positioning as e-commerce platforms extend into tier-two cities, with PLI scheme subsidies supporting packaging technology adoption.
- Local Markets:Traditional mandi intermediaries retain dominance in fresh poultry and seafood distribution where continuous refrigeration infrastructure remains unfinanceable for smaller operators.
- Wholesale:Bulk procurement relationships with integrated farms and cooperative supply networks disintermediate legacy trader networks.
Supermarkets concentrate compliant volume; online retail expands geographic reach fastest.
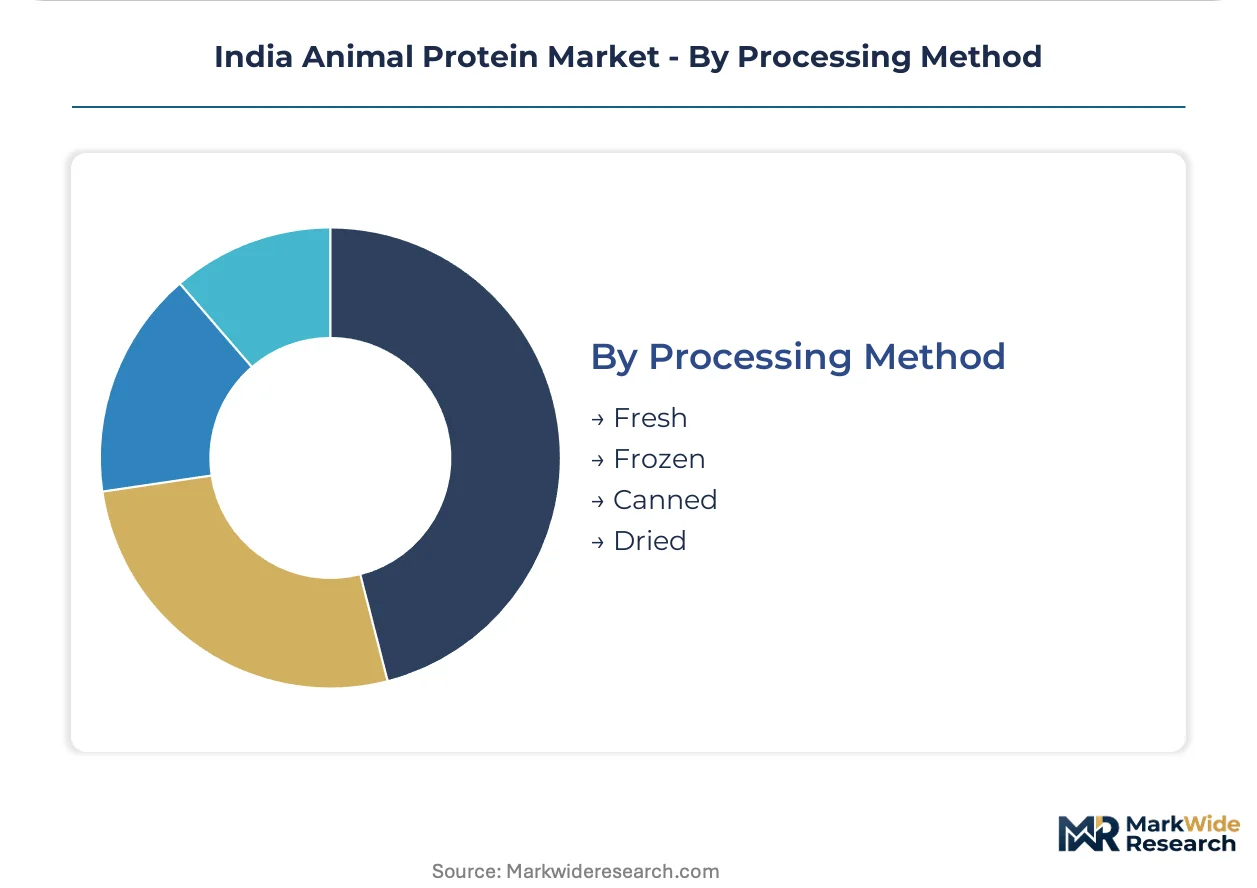
Processing Method:
Spoilage window compression and capital deployment requirements differentiate margin structures across preservation technologies.
- Fresh:Retains largest share of household and restaurant offtake through continuous cold-chain infrastructure that demands capital intensity beyond smaller Maharashtra and Gujarat operator capacity.
- Frozen:Gains traction among online retail platforms serving tier-two cities, with blast freezing technology absorbing moisture migration risk in seafood and premium poultry segments.
- Canned:Serves institutional and emergency reserve applications with limited household penetration outside price-sensitive segments.
- Dried:Periodic BIS revisions for dried protein products force capital upgrades among mid-scale processors with constrained balance sheet capacity.
Fresh dominates current throughput; frozen captures expansion investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's dairy and poultry processing corridor anchors national protein distribution, with cold-chain density enabling fresh product throughput to Mumbai's urban households and restaurant networks.
Maharashtra
Mumbai and Pune households drive diversified protein demand beyond traditional dairy into poultry and seafood categories. FSSAI hygiene rating mandates enforce documented HACCP systems across processing facilities. The Nashik-Solapur production belt concentrates mid-scale meat processors reconfiguring production lines ahead of enforcement windows.
Gujarat
Cooperative milk grids supply protein derivatives to Ahmedabad and Surat's expanding food service sectors. BIS certification requirements for packaged meat products filter smaller operators from modern retail shelves. The Anand-Vadodara corridor anchors Amul Dairy's integrated operations and cooperative procurement networks.
Karnataka
Bangalore's tech workforce sustains premium positioning for blast-frozen seafood and modified atmosphere packaging products. PLI scheme subsidies support packaging technology adoption among processors serving online retail platforms. The Mysore-Mandya belt hosts specialized whey processing facilities supplying sports nutrition channels.
Delhi NCR
Cloud kitchen operators negotiate weekly contract volumes directly with certified poultry farms, bypassing traditional mandi intermediaries. FSSAI contaminant threshold revisions force capital upgrades among mid-scale processors with constrained balance sheet capacity. Gurugram and Noida cold-chain hubs distribute fresh protein to restaurant and household segments.
Andhra Pradesh and Telangana
Integrated poultry operations leverage shorter production cycles and lower feed conversion ratios to serve Hyderabad and Vijayawada demand. Feed input volatility from maize and soybean meal price swings compresses processor margins and destabilizes production planning. The Guntur-Nellore belt concentrates contract farming arrangements with integrated feed-to-farm operators.
India Animal Protein Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized nutrition and export-oriented processing segments. The market structures around three tiers: cooperative federations with captive supply networks, integrated agribusinesses controlling feed-to-retail value chains, and mid-scale specialists in premium dairy derivatives. Competitive moves concentrate on cooperative supply integration and cold-chain infrastructure buildouts rather than price-based rivalry.
Within the cooperative federation tier, Amul Dairy and Karnataka Milk Federation exemplify procurement consolidation through state-level milk grids. Among integrated agribusinesses, Godrej Agrovet Limited occupies a position spanning poultry operations and animal feed production across southern states. Parag Milk Foods represents the specialist archetype, anchoring premium cheese and whey processing capacity in Maharashtra's dairy corridor.
| Leading Market Players |
|---|
| Arla Foods |
| Mother Dairy |
| Fonterra Co-operative Group Limited |
| Karnataka Milk Federation |
| Parag Milk Foods |
| Glanbia PLC |
| Amul Dairy |
| Godrej Agrovet Limited |
| Kerry Group PLC |
| Others |
Supply & Pricing Matrix
Maize and soybean meal price indices cascade through India's poultry supply chain, compressing processor margins in Andhra Pradesh and Telangana while amplifying cost pass-through to restaurant and household buyers across Mumbai and Delhi NCR. Feed input volatility fragments pricing power between integrated operators with captive supply networks and independent processors exposed to spot commodity markets.
Pricing Analysis
Input-cost pass-through operates through contract farming arrangements and cooperative procurement networks, with integrated players buffering margin erosion better than independent operators. Pricing stratifies across FSSAI hygiene rating tiers, with certified facilities commanding premiums over unorganized competitors. Cost compression in standard poultry segments is intensifying because maize price swings destabilize production planning. Quick-service restaurants and cloud kitchens exhibit highest price sensitivity, while hotel chains and export buyers prioritize certification grade over unit cost.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale demand from organized supermarket chains and online platforms, while traditional mandi networks retain fresh distribution dominance in tier-two cities. Supply concentrates in Gujarat's cooperative milk grids, Maharashtra's Nashik-Solapur processing belt, and Andhra Pradesh's Guntur-Nellore poultry corridor. Raw material dependencies center on maize, soybean meal, and cold-chain refrigerants. Single-source vulnerability in veterinary feed additives creates supply chain risk. Distribution runs through cooperative federations, integrated agribusinesses, and independent trader networks in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's animal protein market functions as a regulatory compounder where FSSAI hygiene rating mandates and BIS certification requirements continuously filter sub-scale operators while consolidating volume toward compliant infrastructure.
For Market Incumbents: Lock in cooperative supply integration across Gujarat and Maharashtra to defend against feed input volatility and emerging integrated competitors. Prioritize cold-chain capacity additions in Bangalore and Delhi NCR corridor to capture online retail expansion. Certification investment in blast freezing and modified atmosphere packaging creates differentiation against fresh-only processors.
For New Entrants and Emerging Players: E-commerce platform partnerships offer lowest-friction route to bypass entrenched mandi intermediaries and access tier-two city households directly. White-space targets include specialized whey processing for sports nutrition channels in Karnataka and frozen seafood export corridors serving Middle Eastern markets. Direct procurement relationships with cloud kitchen operators in Delhi NCR provide predictable volume anchors.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale processors possessing FSSAI compliance infrastructure but lacking integrated feed operations, as regulatory enforcement accelerates consolidation. Long-term viability hinges on backward integration into cooperative supply networks or contract farming arrangements. Watch FSSAI enforcement timeline acceleration as inflection indicator for compliance-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cooperative Supply Integration | Amul Dairy's Gujarat milk grid model replicates procurement consolidation for poultry and seafood categories. |
| Cold-Chain Infrastructure Buildout | PLI scheme subsidies reduce capital intensity for blast freezing and modified atmosphere packaging adoption. |
| FSSAI Compliance Certification | Hygiene rating acquisition filters unorganized competitors from modern retail shelves in Maharashtra. |
| Sports Nutrition Channel Development | Whey protein isolate penetration into fitness markets leverages Karnataka's specialized processing capacity. |
| Direct Restaurant Procurement | Weekly contract volumes with cloud kitchens in Delhi NCR disintermediate legacy mandi intermediaries. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Karnataka, and Delhi NCR, with primary inputs from each region's production and consumption clusters. Primary interviews engaged dairy cooperative managers, poultry farm operators, cold-chain logistics providers, FSSAI compliance officers, and restaurant procurement heads. Secondary validation drew from FSSAI regulatory filings, BIS certification databases, NDDB production statistics, and APEDA export records. Bottom-up volume estimates triangulated against top-down consumption surveys across urban household and food service segments.
Rate-of-change decomposition separated volume growth drivers from price evolution across the projection horizon. Segmentation dimensions modeled include product type, processing method, distribution channel, and end-user category with regional regulatory cluster overlays. CAGRs were derived from historical trajectory analysis adjusted for enforcement timeline impacts and infrastructure investment cycles. Feed conversion efficiency improvements and cold-chain penetration rates served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for blast freezing and modified atmosphere packaging; alternative pathways for fresh-only distribution with rapid logistics would alter the outlook. Forecasts reflect assumptions about FSSAI enforcement consistency, PLI scheme continuity, and feed commodity price stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Europe Meat Products Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Organic Halal Meat Market
Meat Products
Smokehouse Market
Meat Products
Meat Paste Market
Meat Products
Shark Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Pork Meat Market
Meat Products
Beef Fat Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Beef Jerky Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Hams Market
Meat Products
Low Fat Sausage Market
Meat Products
Canned Chicken Market
Meat Products
Edible Offal Market