
 Nuclear Waste Management Market | 2026-2036
Nuclear Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Waste Management Market Intelligence
The capability gap between firms offering capital-intensive, long-term geological disposal solutions and those providing specialized, lower-cost treatment services is rotating the competitive landscape. Bechtel Corporation leverages its large-scale project management expertise for complex decommissioning contracts. In contrast, Perma-Fix Environmental Services specializes in advanced waste treatment technologies for specific waste streams. Orano Group positions itself across the full fuel cycle, including recycling and interim storage, to capture diverse revenue opportunities.
Nuclear waste management encompasses the handling, treatment, conditioning, transport, and final disposal of radioactive materials generated from nuclear activities. This process often requires converting liquid high-level waste into a stable solid form, such as borosilicate glass, through vitrification to ensure long-term safety. High-level waste and spent fuel from nuclear power plants represent the most critical segment due to radiological hazards. Low-level waste from research institutes and decommissioning units constitutes the largest volume, driving demand for near-surface disposal and cementation technologies.
Regulatory frameworks from the US Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) dictate stringent disposal protocols. Compliance with international standards like those from the ISO and national rules from bodies such as France's nuclear safety authority shapes technology choices and operational costs. Stakeholder decisions on the final siting and funding of permanent geological repositories remain the central challenge for long-term market certainty.
Market Dynamics
The fundamental tension between the accelerating pace of nuclear power plant decommissioning and the protracted timeline for establishing permanent geological repositories defines the market's structure. This dynamic forces a greater emphasis on advanced interim storage and waste treatment technologies, creating distinct competitive arenas for specialized service providers and large-scale project managers.
Growth Catalysts
- Nuclear Fleet Expansion:The construction of new nuclear reactors, particularly in China, creates a predictable long-term pipeline for spent fuel management, transportation, and eventual disposal services, underpinning market volume growth.
- Decommissioning Mandates:Regulatory pressure from bodies like France's nuclear safety authority (ASN) to finalize and fund concrete decommissioning and waste management plans for aging reactors is compelling utilities to contract for these services.
- Vitrification Technology:The maturation of vitrification processes, which convert liquid high-level waste into stable borosilicate glass, enhances long-term safety and facilitates transport, making it a standard requirement for waste conditioning projects.
Market Restraints
- Repository Siting Delays:Public opposition and political challenges in securing and developing sites for permanent deep geological repositories create significant uncertainty and delay the final stage of the waste management lifecycle.
- High Capital Costs:The immense capital investment and decades-long development timelines required for constructing and licensing final disposal facilities act as a major structural barrier to market completion and long-term planning.
- Legacy Waste Complexity:Waste streams from older, first-generation nuclear facilities often lack complete documentation and possess unique chemical or radiological properties, complicating characterization and treatment and increasing project risk.
Strategic Opportunities
- Advanced Recycling Technologies:Development of partitioning and transmutation (P&T) systems presents an opportunity to reduce the volume and long-term radiotoxicity of high-level waste, potentially altering the requirements for final disposal.
- Modular Treatment Systems:There is an underserved market for mobile and modular waste treatment units that can be deployed at smaller sites, such as research institutions and hospitals, which generate low-level waste but lack scale for large fixed facilities.
- Emerging Nuclear Programs:Countries in Eastern Europe and Asia initiating new nuclear power programs require external expertise, creating opportunities for established firms to provide full-lifecycle waste management consulting and operational services.
Industry Challenges
- Workforce Skill Gaps:A critical shortage of qualified nuclear engineers, radiochemists, and decommissioning specialists creates a talent bottleneck, delaying projects and increasing labor costs across the industry.
- Regulatory Compliance Burden:Navigating and maintaining compliance with the complex and evolving web of national regulations, such as those from the US EPA, and international standards from the ISO increases operational costs and extends project timelines.
- Legacy System Integration:Integrating modern waste processing technologies with aging infrastructure at existing nuclear sites presents significant engineering and safety challenges, often requiring bespoke solutions and extensive site modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Waste Management Market |
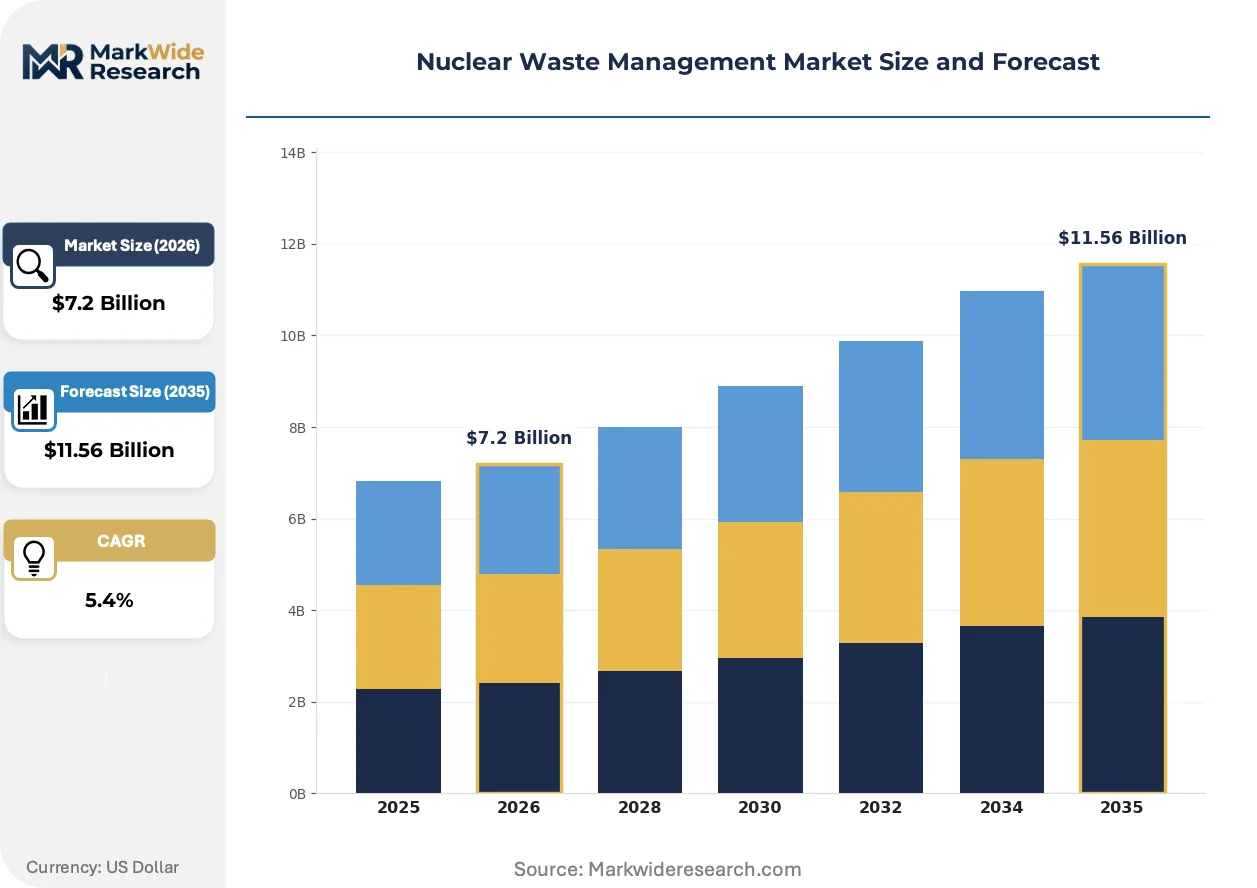
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $11.56 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Low-Level Waste, Intermediate-Level Waste, High-Level Waste, Spent Fuel Treatment Technology: Vitrification, Cementation, Bituminization, Encapsulation Disposal Method: Near-Surface Disposal, Geological Repository, Borehole Disposal, Interim Storage End User: Nuclear Power Plants, Research Institutes, Defense Facilities, Decommissioning Units |
| Companies Covered | Jacobs Engineering Group, EnergySolutions, Bechtel Corporation, Perma-Fix Environmental Services, Westinghouse Electric Company, Veolia Environmental Services, Orano Group, US Ecology, Inc., Fluor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Waste Management Market Strategic Shifts & Innovations
The market is pivoting from a passive storage-focused model toward active waste volume reduction and resource valorization. This shift is driven by technological advancements in waste treatment, evolving regulatory incentives, and new long-term contracting models that prioritize lifecycle cost management.
Advanced Waste Form Conversion
Plasma gasification technology utilizes extremely high temperatures to break down organic and inorganic materials in low-level waste. Operators of facilities with heterogeneous waste streams are adopting the technology to achieve superior volume reduction compared to standard compaction. This technique is decomposing the traditional model of simply burying waste, enabling the recovery of metals and producing a stable, glass-like slag with minimal leachability.
Regulatory Incentives for Modernization
The EU Taxonomy Complementary Climate Delegated Act classifies certain nuclear energy activities as environmentally sustainable under strict technical screening criteria. This policy encourages new investment in nuclear power, provided that a credible plan for long-term waste disposal is in place. Consequently, waste management firms in EU member states like France and Finland are aligning their recycling and storage solutions to meet the taxonomy's "do no significant harm" principles.
Integrated Decommissioning Contracts
A shift is occurring away from procuring discrete services toward awarding long-term, integrated contracts that bundle decommissioning with waste management. This model transfers lifecycle risk to a prime contractor or consortium, which manages all stages from shutdown and decontamination to waste conditioning and storage. This trend is most visible in the large-scale cleanup of government-owned nuclear complexes in the United Kingdom and the United States.
Nuclear Waste Management Market Segmentation
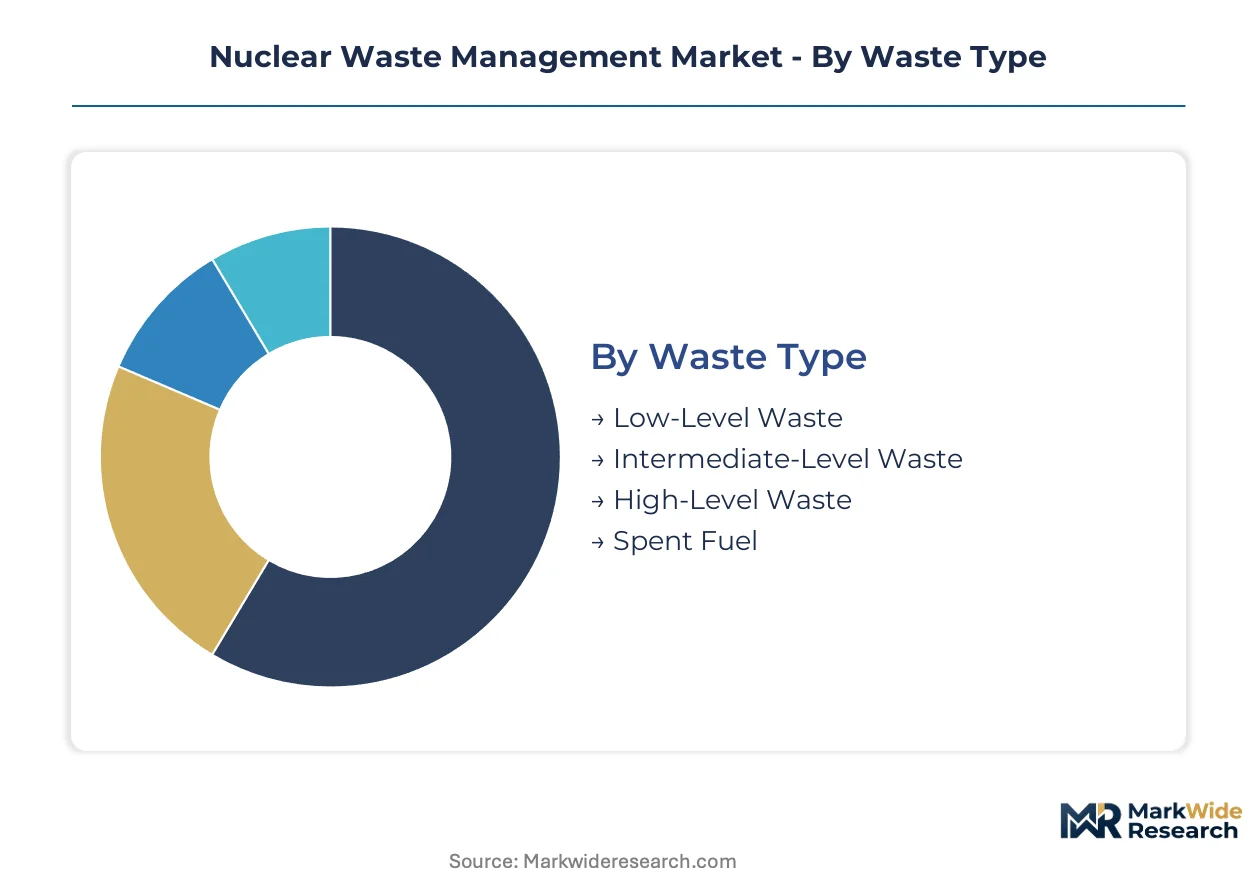
The nuclear waste management market presents a complex array of requirements, necessitating a granular understanding of its various segments. This segmentation analysis highlights the distinct characteristics and demand drivers across different waste types, treatment technologies, disposal methods, and end-user categories, revealing specialized needs within the industry.
Waste Type:
Substitution pressure is minimal for high-level waste streams, which have no viable alternatives for safe management, unlike some low-level waste options where volume reduction techniques can offer flexibility.
- High-Level Waste:These are highly radioactive byproducts resulting from the reprocessing of spent nuclear fuel or direct disposal of spent fuel. Demand for managing high-level waste concentrates in countries with active nuclear power programs, driven by the critical need for long-term isolation and containment.
- Spent Fuel:Irradiated nuclear fuel assemblies removed from nuclear reactors after use. Management focuses on long-term storage and eventual disposal, particularly in nations like China which are actively expanding their nuclear energy capacity.
- Low-Level Waste:Materials with limited radioactivity, often including contaminated tools, clothing, and equipment from nuclear facilities.
- Intermediate-Level Waste:Contains higher levels of radioactivity than low-level waste, often requiring shielding during handling and storage.
Low-Level Waste anchors the volume base while Spent Fuel gains share at the steepest rate.
Treatment Technology:
Cost tiering is evident in treatment technologies, with advanced vitrification demanding higher capital investment compared to more conventional cementation processes for lower activity wastes.
- Vitrification:This process converts liquid high-level radioactive waste into a stable, durable borosilicate glass matrix. Vitrification is a standard requirement for waste conditioning projects, enhancing long-term safety and facilitating transport.
- Cementation:This technology solidifies low-level and intermediate-level radioactive waste into a stable cement matrix. Demand is strong for near-surface disposal applications, driven by requirements for volume reduction and immobilization.
- Bituminization:Encapsulates radioactive waste in bitumen for disposal, reducing leachability.
- Encapsulation:Involves containing waste within a robust, durable material like concrete or metal for safe handling and storage.
The development of novel treatment approaches continues to evolve, driven by environmental safety and volume reduction mandates.
Disposal Method:
Application-specific requirements define disposal methods, with deep geological repositories targeting high-level waste and spent fuel, while near-surface options are suitable for lower activity materials.
- Geological Repository:These are deep underground facilities designed for the permanent isolation of high-level waste and spent nuclear fuel. Repository siting delays and immense capital costs present significant challenges for this critical disposal method.
- Interim Storage:Temporary storage solutions for radioactive waste, often located on-site at nuclear facilities or in centralized facilities, until permanent disposal options become available. This method addresses the protracted timeline for establishing geological repositories.
- Near-Surface Disposal:Shallow land burial facilities used for the disposal of low-level radioactive waste.
- Borehole Disposal:Involves placing waste packages into deep, narrow boreholes drilled into stable rock formations.
Regulatory frameworks from bodies like the US Environmental Protection Agency (EPA) significantly influence the selection and implementation of appropriate disposal methods.
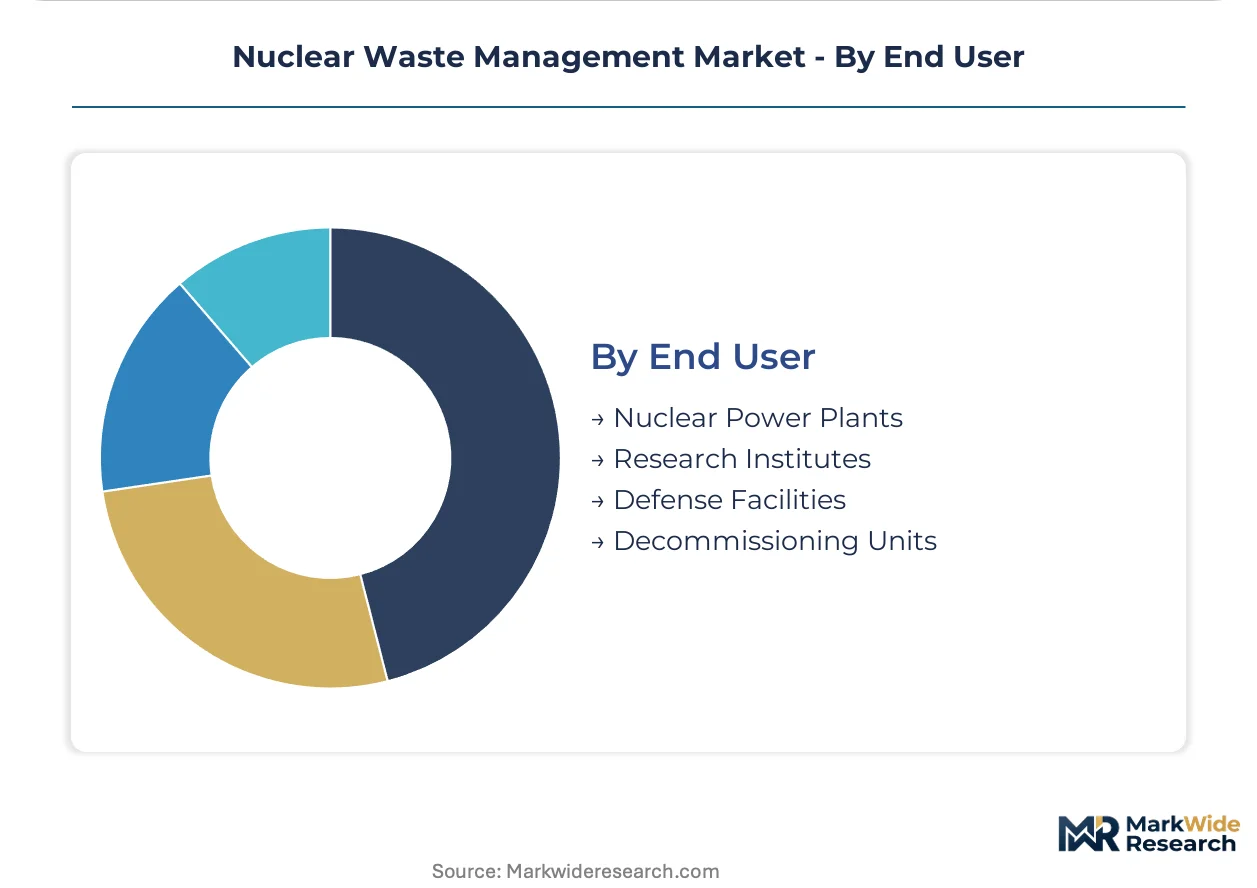
End User:
Customer type dictates the scale and complexity of waste management services, ranging from large nuclear power plants with diverse waste streams to smaller research institutes with specific low-level waste needs.
- Nuclear Power Plants:Primary generators of spent fuel and high-level waste, requiring comprehensive lifecycle management services. New reactor construction, particularly in China, creates a predictable long-term pipeline for these management services.
- Decommissioning Units:Facilities undergoing shutdown and dismantling, generating diverse waste streams from contaminated structures and equipment. Regulatory pressure from authorities like France's nuclear safety authority (ASN) compels utilities to contract for these specialized services.
- Research Institutes:Generate low-level radioactive waste from various scientific experiments and medical applications.
- Defense Facilities:Produce unique and complex waste streams stemming from nuclear weapons programs and related activities.
The accelerating pace of nuclear power plant decommissioning is creating substantial demand for specialized waste management solutions across this end-user segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for nuclear waste management services varies significantly across regions. Countries with established nuclear fleets and decommissioning mandates often exhibit less price sensitivity for critical high-level waste solutions. Conversely, nations developing new programs may prioritize cost-effective low-level waste treatment and interim storage.
United States
Decommissioning aging nuclear power plants and managing legacy waste drives demand for advanced treatment. The US Environmental Protection Agency (EPA) dictates stringent disposal protocols for radioactive materials. Hanford Site in Washington State continues large-scale cleanup efforts, requiring complex waste conditioning and storage solutions.
China
Expanding nuclear energy capacity creates a predictable long-term pipeline for spent fuel management and disposal services. China's Ministry of Ecology and Environment (MEE) enforces strict regulations for nuclear waste handling and storage. New reactor construction in provinces like Guangdong and Fujian generates a growing volume of spent fuel needing comprehensive management.
France
Regulatory pressure from France's nuclear safety authority (ASN) compels utilities to finalize decommissioning and waste management plans. The EU Taxonomy Complementary Climate Delegated Act encourages credible plans for long-term waste disposal. Orano Group, headquartered in Châtillon, positions itself across the full fuel cycle, including recycling and interim storage.
Finland
Establishing permanent geological repositories for spent nuclear fuel underpins long-term market certainty. Posiva Oy, a Finnish company, is developing the Onkalo spent nuclear fuel repository near Olkiluoto, aligning with EU taxonomy principles. This pioneering project sets a precedent for deep geological disposal solutions in Europe.
United Kingdom
Large-scale cleanup of government-owned nuclear complexes, like Sellafield, creates substantial demand for integrated waste management contracts. The UK's Nuclear Decommissioning Authority (NDA) oversees the safe and cost-effective cleanup of legacy sites. Sellafield in Cumbria remains a focal point for advanced waste treatment and storage challenges.
Nuclear Waste Management Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the nuclear waste management competitive landscape. The market structure exhibits a tiered approach, with large engineering and construction firms handling complex, long-term projects. Specialized service providers focus on niche waste streams and advanced treatment technologies. Strategic partnerships and technology licensing are dominant competitive moves, enabling firms to expand their service offerings and geographic reach.
Within the integrated solutions tier, Bechtel Corporation represents large-scale project management expertise for complex decommissioning contracts. Perma-Fix Environmental Services exemplifies specialization in advanced waste treatment technologies for specific waste streams. Orano Group, with its French origins, occupies a position across the full nuclear fuel cycle, including recycling and interim storage. These firms anchor diverse approaches to addressing the challenges of nuclear waste, from comprehensive lifecycle management to targeted technical solutions. Their distinct capabilities reflect the varied demands of the market.
| Leading Market Players |
|---|
| Jacobs Engineering Group |
| EnergySolutions |
| Bechtel Corporation |
| Perma-Fix Environmental Services |
| Westinghouse Electric Company |
| Veolia Environmental Services |
| Orano Group |
| US Ecology, Inc. |
| Fluor Corporation |
| Others |
Cost & Logistics Intelligence
Multi-decade project lead times for geological repositories shape the nuclear waste management supply chain, directly influencing pricing power for specialized long-term storage and disposal services. The bespoke nature of high-level waste solutions contrasts with more standardized offerings for lower-activity materials.
Pricing Analysis
After-sales services and long-term maintenance contracts drive lifetime value in nuclear waste management. Project-based pricing models dominate, reflecting the bespoke nature of high-level waste treatment and disposal, with certification level from regulatory bodies like France's nuclear safety authority (ASN) and customization for unique waste streams serving as key differentiation drivers. Pricing pressure stems from the immense capital investment required for new facilities. Research institutes exhibit the most price sensitivity for low-level waste services, while nuclear power plants prioritize long-term safety and compliance.
Supply Chain Analysis
Secure access to specialized transportation infrastructure, including shielded casks and dedicated rail lines, represents a critical chokepoint for high-level waste movement. Supply concentration for advanced vitrification equipment centers in countries like Germany, France, and the United States, with key raw material dependencies including specialized borosilicate glass formulations and high-integrity steel alloys. Single-source vulnerability for these highly engineered components represents a structural risk. Distribution for large-scale projects often runs through integrated engineering, procurement, and construction (EPC) firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a high-growth disruption, driven by the accelerating pace of nuclear power plant decommissioning and the maturation of advanced treatment technologies like vitrification.
For Market Incumbents: Shield core competencies in large-scale project management and complex waste conditioning by investing in next-generation vitrification and plasma gasification technologies. Consolidate market share through strategic acquisitions of specialized treatment providers, mitigating the threat from niche players. Expand geographic reach into emerging nuclear programs in Eastern Europe and Asia, leveraging established regulatory compliance expertise. Develop integrated decommissioning contracts that transfer lifecycle risk to a prime contractor, reinforcing long-term client relationships.
For New Entrants and Emerging Players: Expedited regulatory certification pathways for modular waste treatment systems present a significant white-space opportunity. Target the underserved market for mobile low-level waste treatment units at research institutions and hospitals, which lack scale for large fixed facilities. Focus on advanced recycling technologies like partitioning and transmutation (P&T) to reduce waste volume and radiotoxicity. A direct-to-site service model, emphasizing rapid deployment and cost-effectiveness, offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a mission-critical infrastructure play because of the non-negotiable societal need for safe nuclear waste management. Target specialized technology firms offering advanced waste form conversion or modular treatment systems for acquisition. The increasing number of integrated decommissioning contracts awarded to single consortia represents a key signal to watch for consolidation and market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Recycling Technologies | Reduces long-term radiotoxicity and volume of high-level waste, altering disposal requirements. |
| Develop Modular Treatment Systems | Addresses demand from smaller waste generators like research institutes, expanding market reach. |
| Form Integrated Decommissioning Consortia | Transfers lifecycle risk to prime contractors, streamlining complex cleanup projects for utilities. |
| Expand Geographic Footprint in Asia | Captures growth from new nuclear power programs in countries like China, securing future revenue. |
| Acquire Niche Technology Providers | Enhances capability in specialized waste streams and treatment processes, strengthening competitive positioning. |
Research Approach
A spread of perspectives from nuclear engineers, radiochemists, regulatory affairs specialists, and utility procurement managers converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were rigorously validated against secondary data from international energy agencies, national nuclear safety authorities, and specialized technical journals. Both bottom-up market sizing and top-down revenue validation approaches were employed for triangulation.
Market segmentation dimensions modeled include waste type, treatment technology, disposal method, and end-user category, alongside an industry-specific dimension of waste radiotoxicity levels. Analytical frameworks were applied across the modeling period to derive compound annual growth rates from historical trends and projected future demand. Key forecast inputs included planned reactor decommissioning schedules, new nuclear build pipelines, and regulatory mandates for waste conditioning.
Decision-makers should treat outputs as directional under current regulatory stability and technological development assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding long-term geological repository progress and vitrification technology adoption. Practitioners should keep alternative scenarios live as public acceptance and national energy policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Canada Waste-To-Energy Market
Waste to Energy Systems
Drilling Waste Management Services Market