
 Nuclear Waste Recycling Market | 2026-2036
Nuclear Waste Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Waste Recycling Market Analysis
The premium spent fuel reprocessing tier is rebalancing away from commodity low-level waste disposal as utilities seek closed-loop fuel cycles. Orano Group leverages its La Hague complex to sustain a dominant position in commercial reprocessing capacity. Westinghouse Electric Company competes through advanced fuel fabrication technology that accepts recycled mixed-oxide material. China National Nuclear Corporation anchors its vertical position via captive domestic reprocessing infrastructure under state direction.
Nuclear waste recycling encompasses the chemical separation and recovery of fissile materials from irradiated reactor fuel, typically involving nitric acid dissolution, solvent extraction with tributyl phosphate, and conversion to uranium-plutonium oxide for reuse. The process reduces final waste volumes by factors of four to five while recovering energy-bearing isotopes for fresh fuel fabrication. Pyroprocessing and electrometallurgical methods are attracting R&D investment as alternatives to aqueous separation for metallic fast-reactor fuels. Government Agencies represent a concentrated demand node where procurement for national laboratory programs and defense legacy cleanup creates stable, long-duration contracts. Spent Fuel recycling commands the deepest value pool due to plutonium and uranium recovery economics, while Transuranic Waste treatment remains technically constrained by americium and curium separation challenges.
The U.S. Nuclear Regulatory Commission and the Department of Energy jointly shape market access through licensing requirements for spent fuel storage and transportation cask certification. France's Autorité de Sûreté Nucléaire enforces reprocessing facility standards that Orano must satisfy for continued La Hague operations. China's Ministry of Ecology and Environment oversees radiological release limits that constrain domestic reprocessing plant design parameters. Stakeholders must monitor whether the U.S. Congress appropriates funding for a consolidated interim storage program that would alter spent fuel ownership economics and reprocessing incentives.
Market Dynamics
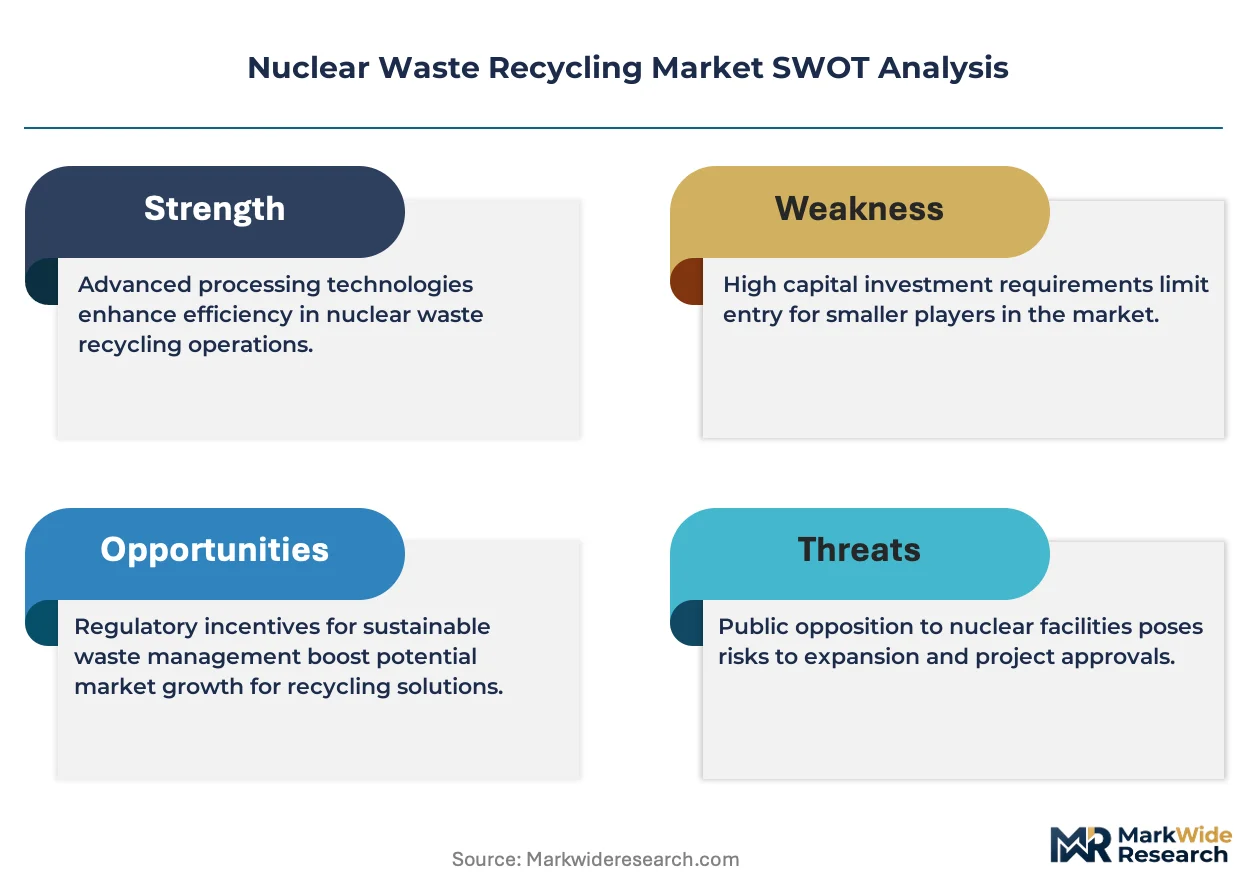
Pressurized water reactor operators are locking in long-term reprocessing contracts to hedge against uranium price volatility and secure fuel supply chains, while the U.S. Nuclear Regulatory Commission's streamlined licensing for consolidated interim storage facilities is unlocking private capital for recycling infrastructure deployment.
Growth Catalysts
- Closed-Loop Fuel Mandates:France's Autorité de Sûreté Nucléaire maintains operational permits for commercial reprocessing facilities, sustaining domestic utility demand for plutonium-uranium recovery services.
- Fast-Reactor Development:Metallic fuel pyroprocessing is attracting government laboratory R&D funding as an alternative separation pathway for Generation IV reactor deployment.
- Defense Legacy Cleanup:The U.S. Department of Energy maintains procurement for transuranic waste treatment at national laboratories, generating stable long-duration contracts for separation technology vendors.
Market Restraints
- Americium-Curium Separation Bottleneck:Transuranic waste treatment remains technically constrained by the absence of commercial-scale processes for minor actinide recovery, limiting high-level waste volume reduction potential.
- Transportation Cask Certification Delays:The U.S. Nuclear Regulatory Commission's extended review timelines for spent fuel shipping containers create inventory backlogs at reactor sites awaiting reprocessing shipment.
- Capital Intensity Barrier:Aqueous reprocessing plants require billion-dollar upfront investment in shielded hot cells and solvent extraction cascades, deterring market entry outside state-backed programs.
Strategic Opportunities
- Pyroprocessing Licensing Pathway:The U.S. Department of Energy's electrometallurgical demonstration programs could establish regulatory precedent for non-aqueous separation, opening alternative technology commercialization.
- China's Domestic Capacity Expansion:China's Ministry of Ecology and Environment oversight of radiological release limits is driving captive reprocessing infrastructure investment under state-directed vertical integration.
- Consolidated Interim Storage Program:U.S. Congressional appropriations for centralized spent fuel repositories would alter ownership economics and create reprocessing feedstock aggregation points.
Industry Challenges
- Specialized Workforce Scarcity:Radiochemical separation operations require personnel certified in glovebox handling and remote manipulator systems, with training pipelines failing to match facility expansion timelines.
- Legacy Facility Integration:New pyroprocessing and electrometallurgical systems must interface with existing aqueous separation infrastructure, creating process compatibility and contamination control complexities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Waste Recycling Market |
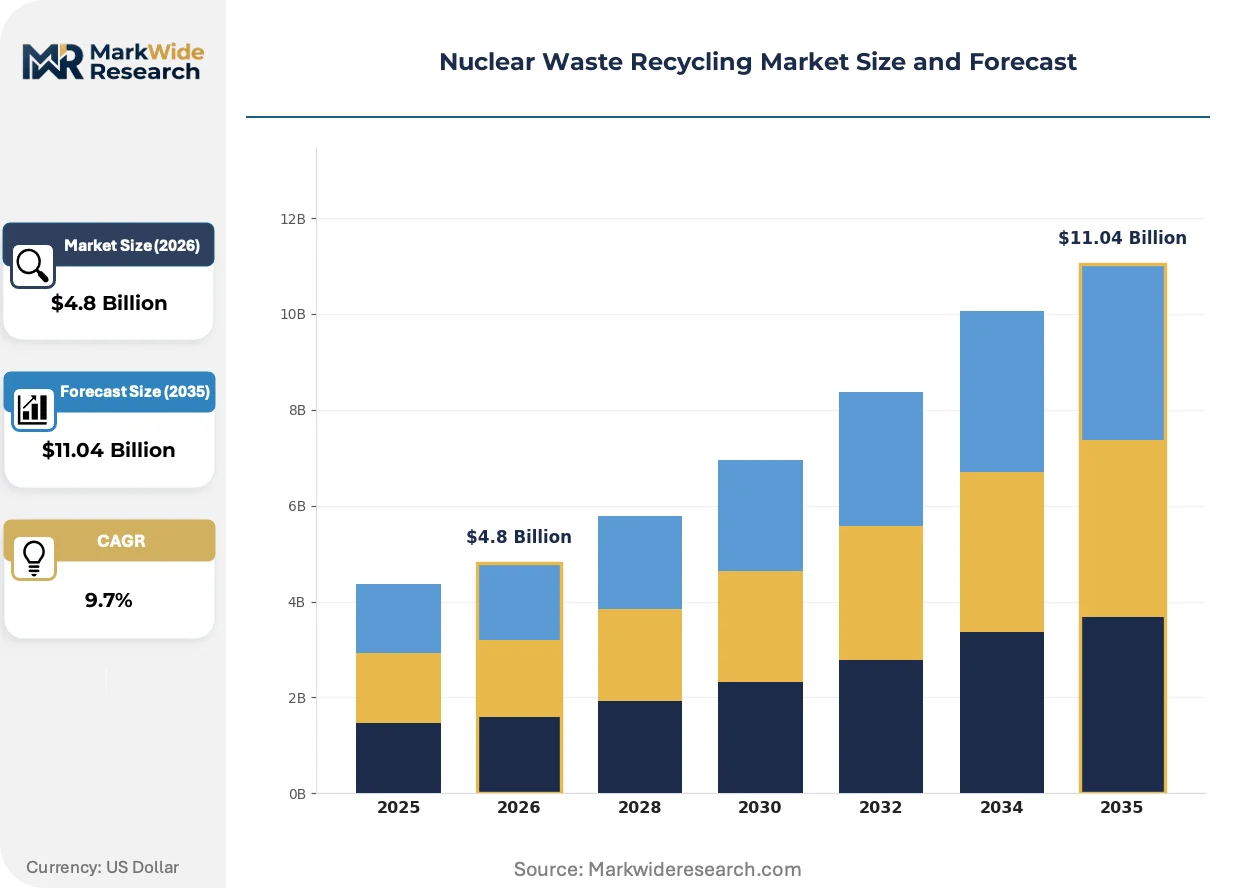
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pyroprocessing, Electrometallurgical, Advanced Separation, Bioremediation End User: Nuclear Power Plants, Research Facilities, Waste Management Firms, Government Agencies Service Type: Consulting, Characterization, Treatment, Storage Solutions Material Type: High-Level Waste, Low-Level Waste, Spent Fuel, Transuranic Waste |
| Companies Covered | Orano Group, Veolia Environmental Services, Bechtel Corporation, Fluor Corporation, Westinghouse Electric Company, Perma-Fix Environmental Services, EnergySolutions, Augean PLC, China National Nuclear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Waste Recycling Market Emerging Trajectories
Electrometallurgical separation methods are disrupting the aqueous reprocessing monopoly established since the 1950s, while regulatory frameworks in multiple geographies are adapting to accommodate alternative fuel cycle technologies and consolidated waste management approaches.
Pyroprocessing is electrifying fast-reactor fuel cycle economics by enabling metallic fuel recycling without aqueous dissolution steps. The U.S. Department of Energy's Idaho National Laboratory is piloting electrometallurgical treatment for Experimental Breeder Reactor-II legacy fuel. This technology is electrifying investment patterns away from traditional solvent extraction infrastructure toward modular, salt-based separation systems.
France's Autorité de Sûreté Nucléaire is tightening radiological release standards for La Hague facility operations, requiring enhanced effluent treatment systems. The regulatory pressure is compressing permitted discharge limits for liquid waste streams. Commercial reprocessing contracts are now incorporating penalty clauses tied to environmental compliance metrics, with utility buyers demanding transparency in separation efficiency reporting.
Utility procurement departments are unbundling fuel fabrication from reprocessing services, creating spot-market purchasing for mixed-oxide material. This disintermediation is compressing contract durations from decade-long arrangements to shorter-term agreements with price renegotiation clauses. The shift is most visible among European pressurized water reactor operators seeking supply chain flexibility amid uranium market volatility.
Nuclear Waste Recycling Market Segmentation
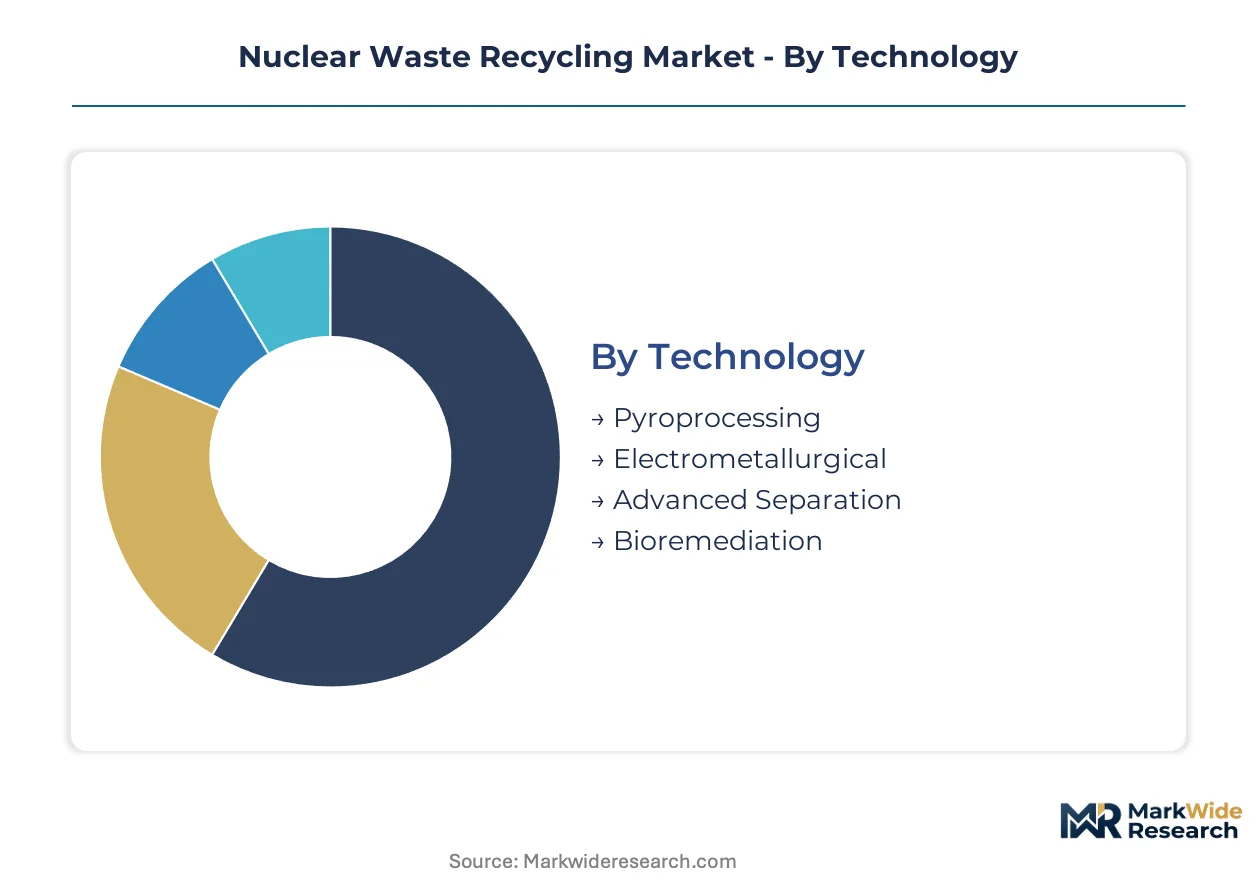
Technology selection dictates capital deployment timelines and regulatory approval pathways across the nuclear waste recycling value chain. End user procurement patterns and material characteristics further segment operational risk profiles and contract duration economics.
Technology:
Pyroprocessing and electrometallurgical systems demand billion-dollar upfront investment in shielded hot cells, while aqueous alternatives carry lower initial capital but higher ongoing solvent replacement costs.
- Pyroprocessing:High-temperature molten salt electrochemical separation recovers metallic fuel constituents without nitric acid dissolution. Demand concentrates at Idaho National Laboratory for Experimental Breeder Reactor-II legacy fuel treatment, driven by Generation IV fast-reactor deployment timelines.
- Electrometallurgical:Electrorefining in molten chloride salts separates uranium from fission products and transuranics. U.S. Department of Energy demonstration programs are accelerating licensing precedent for non-aqueous pathways, displacing conventional solvent extraction infrastructure investment.
- Advanced Separation:Emerging solvent extraction variants and ion exchange systems target minor actinide recovery.
- Bioremediation:Microbial reduction processes for low-level waste decontamination operate at laboratory scale.
Most installed capacity flows through aqueous separation legacy infrastructure. Expansion is steepest in electrometallurgical demonstration programs.
End User:
Contract duration and payment security vary sharply across buyer categories, with government procurement offering decade-long visibility against utility spot-market flexibility.
- Nuclear Power Plants:Pressurized water reactor operators negotiate reprocessing contracts spanning 10-15 years to hedge uranium price volatility. France's utility procurement concentrates at Orano's La Hague facility under closed-loop fuel cycle mandates.
- Government Agencies:National laboratory programs and defense legacy cleanup generate stable, appropriations-backed demand with limited counterparty risk. The U.S. Department of Energy maintains procurement for transuranic waste treatment at Los Alamos and Savannah River sites.
- Research Facilities:University reactors and test facilities generate small-volume, high-frequency characterization demand.
- Waste Management Firms:Private contractors bid for transportation and interim storage services.
Revenue concentration sits with utility long-term contracts. Procurement volume is climbing fastest at government agencies.
Service Type:
Margin structure inverts across the service hierarchy, with front-end consulting commanding premium pricing against commoditized storage solutions.
- Treatment:Chemical separation and volume reduction operations require licensed facility infrastructure and specialized radiochemical workforce. Demand aggregates at consolidated interim storage sites where the U.S. Nuclear Regulatory Commission's streamlined licensing is unlocking private capital deployment.
- Storage Solutions:Dry cask systems and pool storage at reactor sites pending reprocessing shipment. Transportation cask certification delays at the U.S. Nuclear Regulatory Commission create inventory backlogs and extended revenue recognition timelines.
- Consulting:Regulatory compliance and licensing support for facility permitting.
- Characterization:Radiological assay and waste stream profiling for treatment routing.
Contract value pools deepest in treatment operations. Consulting margins are compressing fastest amid regulatory standardization.
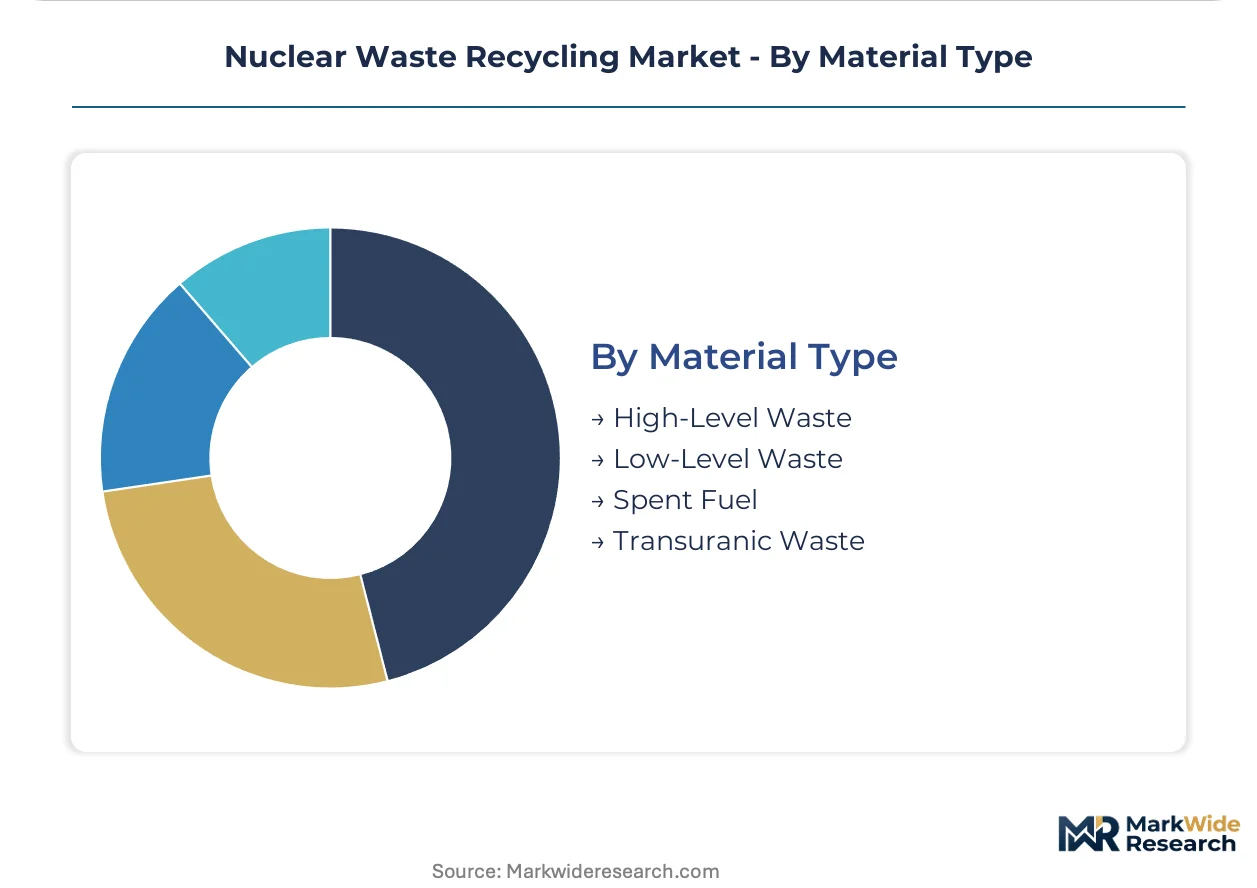
Material Type:
Radiotoxicity and decay heat profiles determine handling infrastructure requirements and final disposal pathway economics.
- Spent Fuel:Irradiated uranium dioxide assemblies containing recoverable plutonium and uranium isotopes. France's La Hague facility processes domestic and foreign utility feedstock under Autorité de Sûreté Nucléaire permits, with plutonium-uranium recovery economics driving reprocessing contract pricing.
- Transuranic Waste:Alpha-emitting isotopes beyond uranium in the actinide series, primarily americium and curium. Separation challenges constrain commercial-scale recovery, limiting high-level waste volume reduction potential at existing facilities.
- High-Level Waste:Fission product concentrates from reprocessing raffinate streams.
- Low-Level Waste:Contaminated protective clothing, tools, and resins with limited radioactivity.
Reprocessing throughput centers on spent fuel feedstock. Transuranic waste treatment capacity is expanding most quickly under defense legacy cleanup appropriations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiochemical specialists cluster around established reprocessing sites, with France's La Hague facility anchoring the deepest talent pool. Licensing expertise concentrates at regulatory interfaces in Washington, Beijing, and Paris. Facility construction crews rotate between national laboratory programs, creating transient skill shortages during expansion phases.
United States
Pressurized water reactor operators at Exelon and Duke Energy negotiate reprocessing contracts to hedge uranium price volatility. The U.S. Nuclear Regulatory Commission's streamlined licensing for consolidated interim storage facilities is unlocking private capital deployment. Idaho National Laboratory pilots electrometallurgical treatment for Experimental Breeder Reactor-II legacy fuel, anchoring pyroprocessing R&D concentration.
France
Électricité de France maintains closed-loop fuel cycle mandates driving plutonium-uranium recovery demand. The Autorité de Sûreté Nucléaire enforces tightened radiological release standards for La Hague operations. The Normandy coastal cluster around La Hague sustains the world's largest commercial reprocessing capacity, processing domestic and foreign utility feedstock under enhanced effluent treatment requirements.
China
China National Nuclear Corporation anchors vertical integration via captive domestic reprocessing infrastructure. The Ministry of Ecology and Environment oversees radiological release limits constraining plant design parameters. The Gansu province corridor hosts pilot reprocessing facilities under state-directed expansion timelines for metallic fast-reactor fuel cycles.
United Kingdom
Sellafield Ltd manages legacy Magnox reprocessing site decommissioning and plutonium stockpile disposition. The Office for Nuclear Regulation oversees spent fuel storage and transportation cask certification. The Cumbria coastal cluster maintains defense legacy cleanup procurement generating stable contracts for transuranic waste treatment vendors.
Japan
Japan Atomic Power Company and utilities suspended full reprocessing operations post-Fukushima, creating inventory backlogs at reactor sites. The Nuclear Regulation Authority reviews Rokkasho reprocessing plant licensing under enhanced safety standards. The Aomori prefecture facility awaits commercial startup, with spent fuel pool storage capacity constraining fleet restart timelines.
Nuclear Waste Recycling Market Vendor Landscape
Capital-heavy producers compete with asset-light technology licensors for reactor operator procurement budgets. The market structures around three tiers: state-backed national champions with captive fuel cycle infrastructure, integrated engineering conglomerates bundling construction with operations, and specialized environmental services firms handling transportation and interim storage. Dominant competitive moves include strategic partnerships between utilities and reprocessors locking in decade-long feedstock agreements, and technology licensing deals transferring pyroprocessing intellectual property from national laboratories to commercial vendors.
Among state-backed champions, Orano Group and China National Nuclear Corporation exemplify vertical integration archetypes controlling reprocessing through fuel fabrication. Westinghouse Electric Company occupies a technology-licensing position, competing through advanced fuel fabrication systems that accept recycled mixed-oxide material. Engineering conglomerates Bechtel Corporation and Fluor Corporation anchor the construction-integration tier, bidding for facility builds and defense legacy cleanup programs.
| Leading Market Players |
|---|
| Orano Group |
| Veolia Environmental Services |
| Bechtel Corporation |
| Fluor Corporation |
| Westinghouse Electric Company |
| Perma-Fix Environmental Services |
| EnergySolutions |
| Augean PLC |
| China National Nuclear Corporation |
| Others |
Supply Flow & Price Mechanics
Government procurement programs at the U.S. Department of Energy and France's utility sector anchor long-term contract pricing, with closed-loop fuel mandates compressing spot-market flexibility for reprocessing services. This buyer concentration sustains premium pricing for plutonium-uranium recovery while pressuring storage and transportation margins.
Pricing Analysis
Bundled reprocessing-fuel fabrication contracts are fragmenting into unbundled service procurement, with utility buyers now sourcing mixed-oxide material on shorter-term agreements. Price differentiation hinges on separation efficiency certification and volume scale, with La Hague-originated material commanding brand premiums over emerging capacity. Cost compression in interim storage services is intensifying because transportation cask certification delays extend inventory holding periods. Government agencies exhibit lowest price sensitivity due to appropriations-backed procurement, while waste management firms face acute margin pressure in commoditized dry cask segments.
Supply Chain Analysis
Domestic-content mandates in China's Gansu corridor and France's Normandy coastal cluster are reshaping sourcing patterns, with state-directed programs prioritizing captive reprocessing infrastructure over cross-border feedstock flows. Supply concentration centers on France, China, and the United States for licensed separation capacity. The value chain draws from specialized hot cell manufacturing, tributyl phosphate solvent systems, and certified transportation cask fabrication. Single-source vulnerability in radiochemical workforce pipelines creates bottleneck risk. Distribution runs through consolidated interim storage aggregation points prior to reprocessing facility intake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds, with the U.S. Nuclear Regulatory Commission's streamlined licensing for consolidated interim storage facilities creating durable demand visibility for treatment and storage vendors.
For Market Incumbents: Hedge uranium price volatility exposure by locking decade-long reprocessing contracts with pressurized water reactor operators before pyroprocessing technology matures. Prioritize certification investment in electrometallurgical separation capabilities at Idaho National Laboratory to preempt regulatory precedent shifts. Defend margin position by controlling captive transportation cask fleets rather than relying on third-party certification timelines. For New Entrants and Emerging Players: Defense legacy cleanup procurement at Los Alamos and Savannah River sites represents the most penetrable demand node, with stable appropriations-backed contracts and limited incumbent saturation. Target transuranic waste treatment capacity expansion where americium-curium separation bottlenecks constrain existing players. Pursue technology licensing pathways from national laboratory demonstration programs rather than greenfield aqueous plant construction. For Investors and Strategic Acquirers: Engineering conglomerates with defense contracting relationships are the most active acquirer in this space, seeking radiochemical separation capabilities to bundle with facility construction portfolios. Long-term viability rests on positioning for Generation IV fast-reactor fuel cycle deployment. Acquisition targets should demonstrate licensed hot cell infrastructure or proprietary pyroprocessing intellectual property. Watch U.S. Congressional appropriations for consolidated interim storage programs as the critical inflection signal altering spent fuel ownership economics.| Strategic Initiative | Industry Significance |
|---|---|
| Pyroprocessing Licensing Pathway | U.S. Department of Energy demonstration programs establish regulatory precedent for non-aqueous separation commercialization. |
| Consolidated Interim Storage Buildout | U.S. Nuclear Regulatory Commission streamlined licensing unlocks private capital for feedstock aggregation infrastructure. |
| Closed-Loop Fuel Mandate Compliance | France's Autorité de Sûreté Nucléaire permits sustain Orano's La Hague dominance in plutonium-uranium recovery. |
| Defense Legacy Cleanup Procurement | Department of Energy appropriations generate stable long-duration contracts for transuranic waste treatment vendors. |
| Captive Domestic Capacity Expansion | China's Ministry of Ecology and Environment oversight drives state-directed vertical integration in Gansu corridor. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility procurement officers, national laboratory program managers, regulatory affairs specialists at the U.S. Nuclear Regulatory Commission, and radiochemical operations directors with secondary validation against FERC filings, IEA nuclear fuel cycle reports, and national laboratory technical disclosures. Bottom-up facility capacity modeling and top-down demand aggregation from pressurized water reactor operator contracts were cross-referenced for triangulation.
Segment-weighting approaches distributed value across technology pathways, end-user procurement categories, and material type radiotoxicity profiles across the projection horizon. The analytical framework modeled pyroprocessing, electrometallurgical, and aqueous separation technology segments alongside government agency, nuclear power plant, and research facility end-user demand. CAGRs were derived from facility expansion timelines, regulatory licensing velocity, and feedstock contract duration patterns. Fast-reactor deployment roadmaps and defense legacy cleanup appropriation cycles served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; spent fuel reprocessing throughput carries tighter precision than transuranic waste treatment capacity given established La Hague operational data. Forecasts reflect assumptions regarding regulatory licensing velocity, Congressional appropriation continuity, and Generation IV reactor deployment timelines. A small set of triggers—U.S. consolidated interim storage funding decisions, pyroprocessing regulatory precedent rulings, and China's metallic fuel cycle expansion pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market