
 Waste Heat to Power Market | 2026-2036
Waste Heat to Power Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Heat to Power Market Analysis
The EU Green Deal's industrial decarbonization mandates is shifting investment toward waste heat recovery across European energy-intensive sectors. Ormat Technologies leverages its geothermal expertise to dominate Organic Rankine Cycle deployments. Siemens Energy anchors its position through large-scale turbomachinery integration for combined cycle applications. General Electric competes with advanced steam turbine retrofits targeting existing power infrastructure.
Waste heat to power captures thermal energy discarded from industrial processes, engines, and exhaust streams, converting it into electricity through thermodynamic cycles typically operating between 80°C and 350°C depending on the working fluid and cycle architecture. Its primary purpose is to improve facility energy efficiency while reducing purchased fuel and grid dependency. Organic Rankine Cycle systems occupy the leading share due to proven scalability across low-to-medium temperature waste streams. Industrial Waste Heat Recovery applications sustain the fastest growth trajectory as steel, cement, and chemical producers face escalating carbon costs. Combined Heat and Power installations concentrate margin pools where thermal and electric output can be monetized simultaneously.
The EPA enforces emissions standards under the Clean Air Act that indirectly mandate efficiency improvements at US industrial facilities, while the EU's F-Gas Regulation restricts high-global-warming-potential working fluids in ORC systems, shaping refrigerant selection and equipment redesign. China's MEE implements dual carbon goals that compel provincial steel and power plants to install waste heat recovery or face production curtailments. Stakeholders must monitor evolving refrigerant phase-down schedules and carbon border adjustment mechanisms to align technology choices with compliance timelines.
Market Dynamics
The EU Green Deal's tightening emission thresholds are forcing energy-intensive facilities toward waste heat recovery retrofits, compressing payback period expectations from five years to under three.
Growth Catalysts
- Carbon Border Adjustment Mechanism:The EU's phased CBAM implementation exposes imported steel and cement to carbon pricing parity, compelling non-EU exporters to install waste heat recovery systems to preserve market access.
- Industrial cluster density:Germany's Rhine-Ruhr and Saarland steel corridors concentrate retrofit demand where shared infrastructure and technical labor pools reduce installation costs.
- Organic Rankine Cycle maturation:Proven performance across low-temperature waste streams below 150°C unlocks viability for chemical and food processing facilities previously excluded from waste heat power economics.
Market Restraints
- Working fluid supply concentration:The EU F-Gas Regulation's phase-down of high-GWP refrigerants constrains hydrofluorocarbon availability, forcing equipment redesigns and extending procurement timelines for ORC systems.
- Capital intensity barrier:Front-loaded engineering and turbominery costs exceed internal hurdle rates at mid-sized industrial facilities without green financing instruments or carbon credit revenue streams.
- Site-specific engineering:Each waste heat source demands customized heat exchanger sizing and working fluid selection, preventing module standardization and economies of scale in manufacturing.
Strategic Opportunities
- Data center thermal coupling:Hyperscale computing facilities in Northern Europe generate constant low-grade heat ideal for Organic Rankine Cycle integration, creating new demand outside traditional industrial verticals.
- China's provincial enforcement:The MEE's dual carbon goals drive mandatory waste heat recovery installations at steel plants in Hebei and Jiangsu provinces, opening equipment supply contracts for technology licensors.
- Heat-to-hydrogen process integration:Converging waste heat capture with electrolyzer thermal management enables efficiency gains in emerging green hydrogen production clusters.
Industry Challenges
- Thermodynamic engineering scarcity:Specialized expertise in working fluid thermophysical properties and turbine blade erosion modeling concentrates at a handful of technical universities and incumbent equipment suppliers.
- Legacy plant integration complexity:Retrofitting ORC skids into operating steel mills and cement kilns requires extended shutdown windows that conflict with continuous production schedules and offtake commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Heat to Power Market |
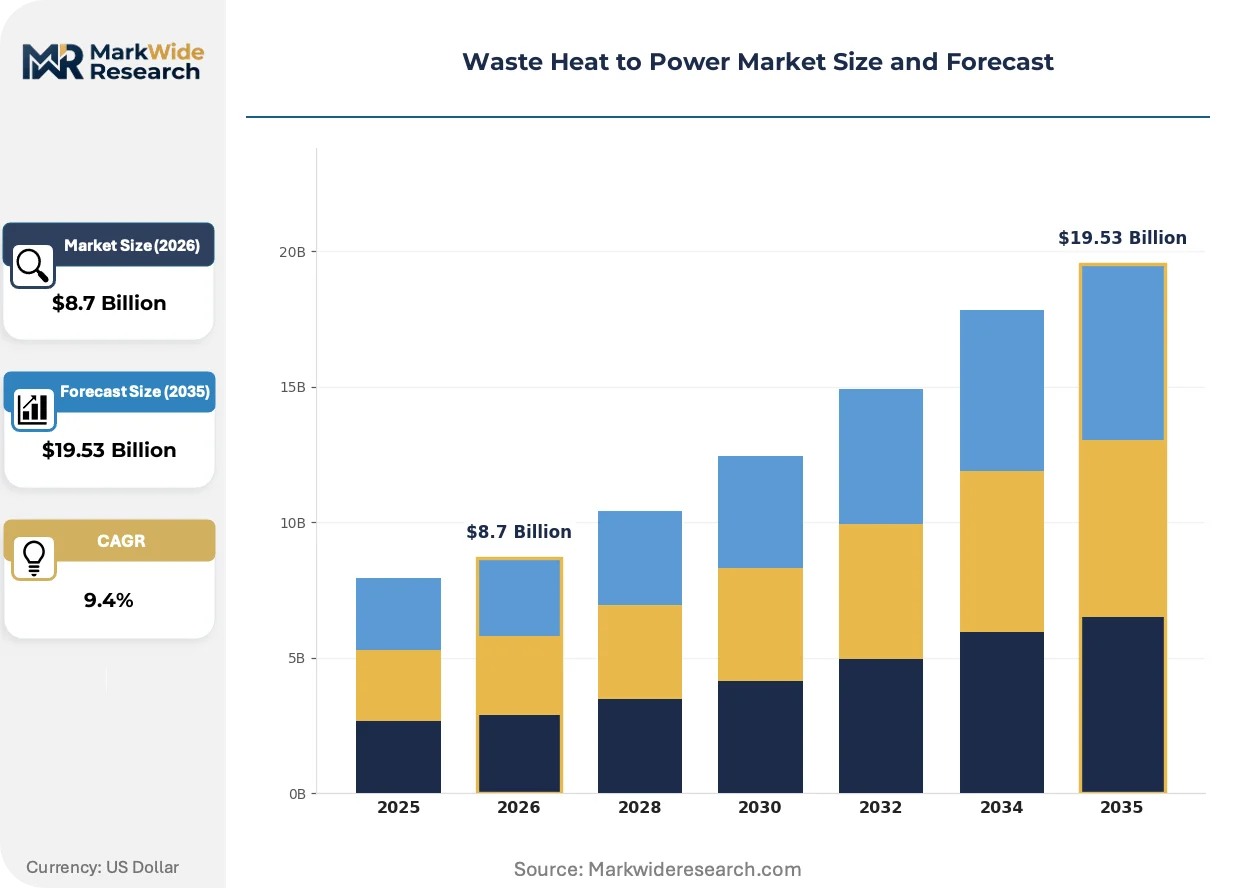
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Organic Rankine Cycle, Steam Rankine Cycle, Kalina Cycle, Stirling Engine End User: Power Plants, Manufacturing Facilities, Oil & Gas, Automotive Application: Combined Heat and Power, Industrial Waste Heat Recovery, Geothermal Energy, Combined Cycle Generation Installation: Onsite Installation, Offsite Installation, Retrofitting, New Build Systems |
| Companies Covered | Ormat Technologies, Turboden, Atlas Copco, Exergy International, Alfa Laval, General Electric, Siemens Energy, Mitsubishi Heavy Industries, IHI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Heat to Power Market Emerging Trajectories
Technology convergence between waste heat recovery and industrial decarbonization is compressing equipment development cycles and expanding addressable temperature ranges.
Supercritical CO2 power cycles are converging with geothermal engineering expertise to unlock higher thermal efficiencies at waste stream temperatures above 300°C. Steel producers in Germany and the Netherlands are piloting these systems at electric arc furnace exhaust points. The structural consequence is displacing steam turbine retrofits in high-temperature applications where water-based working fluids face corrosion and scaling constraints.
The EU F-Gas Regulation's refrigerant phase-down schedule is forcing ORC manufacturers toward hydrofluoroolefin and natural working fluid alternatives by 2030. Equipment redesigns to accommodate lower-flammability or higher-pressure refrigerants extend certification timelines. Chemical producers in Belgium and the Netherlands face the tightest compliance windows, accelerating partnerships with fluid suppliers for drop-in replacements.
Energy service companies are capturing waste heat recovery projects through performance contracting structures that assume technical and carbon price risk. Industrial facilities in energy-intensive sectors transfer capex burden and guarantee energy savings through shared savings agreements. This model concentrates in Germany where carbon pricing visibility and green bond markets support long-dated revenue projections.
Waste Heat to Power Market Segmentation
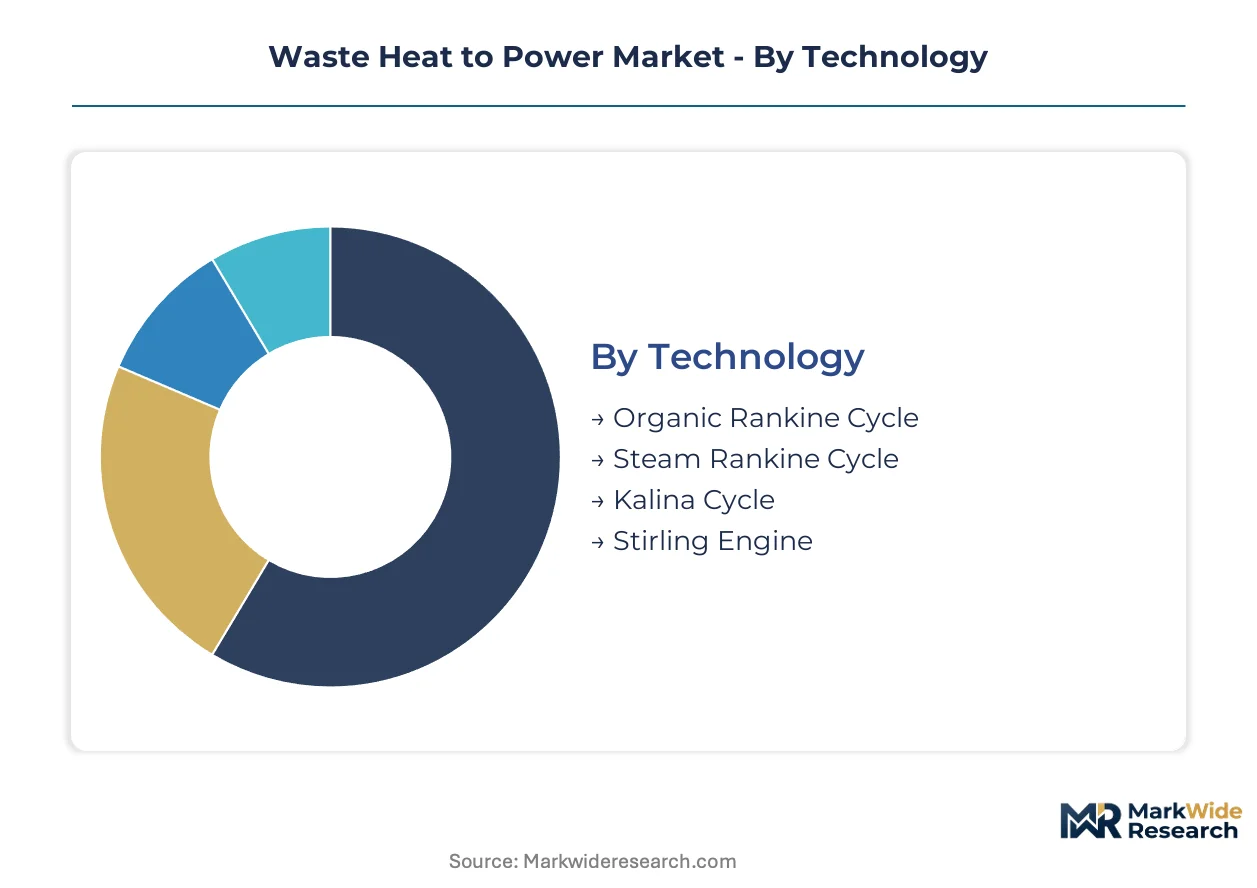
Waste heat to power systems vary dramatically in thermodynamic efficiency, capital intensity, and integration complexity across technology architectures and installation contexts. Segment-level analysis reveals where margin pools concentrate and which configurations face structural barriers to scale.
Technology:
Buyers in this category differentiate primarily by waste stream temperature range and working fluid compatibility constraints.
- Organic Rankine Cycle:Closed-loop systems using organic working fluids with low boiling points operate efficiently at 80-350°C, dominating low-grade industrial waste applications. Demand concentrates in Germany's chemical corridor and Netherlands food processing clusters where the EU F-Gas Regulation's refrigerant phase-down is forcing fluid redesigns toward hydrofluoroolefin alternatives.
- Steam Rankine Cycle:Water-based working fluid systems achieve higher thermal efficiencies above 300°C but face corrosion and scaling challenges in steel mill exhaust streams. Cement producers in Poland and Spain favor these for preheater tower integration where temperature profiles align with saturated steam economics.
- Kalina Cycle:Ammonia-water mixture enables variable boiling temperature matching to heat source profiles, improving efficiency in geothermal hybrid applications. Limited commercial deployment concentrates at Icelandic and Turkish geothermal sites with established turbomachinery partnerships.
- Stirling Engine:External combustion architecture suits small-scale distributed applications below 100kW with minimal maintenance requirements. Remote oil field operations in Norway and Scotland deploy these for flare gas recovery where rotating equipment reliability concerns dominate.
Volume sits with Organic Rankine Cycle deployments; growth tilts toward Steam Rankine Cycle retrofits as high-temperature steel sector recovery accelerates.
End User:
Capital allocation cycles and carbon pricing exposure create divergent procurement timelines across buyer categories.
- Power Plants:Combined cycle and cogeneration facilities integrate waste heat recovery for efficiency compliance with grid dispatch requirements. Coal-to-gas conversion projects in Germany's industrial heartland anchor equipment demand as operators face EU ETS cost pressure.
- Manufacturing Facilities:Steel, cement, and chemical producers face the tightest emission thresholds under the EU Green Deal's industrial decarbonization mandates. Hebei and Jiangsu province steel mills under China's MEE dual carbon enforcement drive mandatory installation timelines.
- Oil & Gas:Refinery and upstream operations recover flare gas and process heat for captive power generation. North Sea platform electrification projects in Norwegian and UK waters create offshore ORC demand for auxiliary power displacement.
- Automotive:Internal combustion engine exhaust recovery and electric vehicle battery thermal management represent emerging applications. German OEM test facilities pilot Stirling-based range extenders for commercial vehicle segments.
Procurement scale favors power plant integrations; policy pressure is accelerating manufacturing facility deployment fastest.
Application:
Revenue model structures—captive consumption versus grid export versus thermal offtake—determine project finance viability.
- Combined Heat and Power:Simultaneous thermal and electric output monetization maximizes facility energy economics through district heating integration. Danish and Swedish municipal networks anchor demand where heat purchase agreements provide revenue certainty.
- Industrial Waste Heat Recovery:Direct electricity generation from process exhaust streams reduces purchased power and grid dependency. German steel and cement producers under escalating carbon costs compress payback expectations below three years.
- Geothermal Energy:Low-to-medium enthalpy resource development leverages ORC expertise from industrial waste heat engineering. Italian and Hungarian sedimentary basin projects benefit from shared turbomachinery supply chains.
- Combined Cycle Generation:Gas turbine exhaust heat recovery for bottoming cycles improves plant heat rates for grid dispatch competitiveness. Spanish and Italian merchant power operators prioritize these for capacity market revenue optimization.
Margin pools concentrate in Combined Heat and Power; Industrial Waste Heat Recovery is climbing the fastest as carbon border adjustments tighten.
Installation:
Project risk allocation between engineering-procurement-construction firms and end users shapes contracting structures.
- Onsite Installation:Greenfield industrial facilities integrate waste heat recovery during construction for optimized heat exchanger placement and piping topology. New German steel mill investments in Lower Saxony embed ORC skids in initial engineering phases.
- Offsite Installation:Modular system fabrication in controlled manufacturing environments reduces field construction risk and accelerates commissioning timelines. Dutch equipment suppliers serve Belgium and Luxembourg markets through centralized assembly facilities.
- Retrofitting:Brownfield integration into operating plants demands extended shutdown windows and legacy system compatibility engineering. Poland's aging cement kiln fleet faces the tightest retrofit scheduling constraints against continuous production commitments.
- New Build Systems:Integrated design from project inception enables optimal working fluid selection and turbine sizing for specific heat source profiles. Green hydrogen production clusters in Netherlands and Denmark embed waste heat recovery in electrolyzer thermal management.
Project volume flows through Retrofitting engagements; New Build Systems are gaining share fastest as industrial decarbonization investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European waste heat recovery deployment, with steel and chemical clusters driving retrofit demand under tightening carbon pricing regimes.
Germany
Steel mills in Duisburg and Dortmund face EU ETS costs exceeding €80 per tonne, compressing ORC project paybacks below three years. The National Industrial Decarbonization Program mandates efficiency audits for facilities above 10MW thermal capacity. Saarland's cement producers cluster around Merzig, installing preheater tower heat recovery systems to maintain export competitiveness under CBAM.
China
Hebei province steel plants operate under MEE production curtailment threats unless waste heat recovery achieves 35 percent thermal efficiency. The dual carbon goals framework enforces provincial installation quotas at Jiangsu chemical complexes. Tangshan steel corridor operators deploy supercritical CO2 systems at electric arc furnace exhaust points, displacing conventional steam cycles.
United States
Gulf Coast refineries recover flare gas heat for captive power under EPA Clean Air Act enforcement. The Inflation Reduction Act's clean energy tax credits improve project IRRs for petrochemical facilities in Texas and Louisiana. Houston Ship Channel clusters integrate ORC skids into existing coker units, reducing grid dependency during peak demand periods.
Netherlands
Rotterdam port industrial parks monetize waste heat through district heating networks serving 200,000 households. The National Climate Agreement requires energy-intensive facilities to publish recovery implementation roadmaps by 2026. Chemelot chemical cluster in Limburg pilots hydrofluoroolefin working fluids ahead of EU F-Gas Regulation deadlines.
India
Cement producers in Chhattisgarh and Rajasthan install waste heat recovery boilers under Bureau of Energy Efficiency Perform Achieve Trade schemes. The PLI scheme for green hydrogen production creates thermal coupling opportunities at electrolyzer facilities. Andhra Pradesh steel corridor operators face state-level renewable purchase obligations that waste heat power satisfies.
Waste Heat to Power Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and project financing capability. The vendor base stratifies between turbomachinery incumbents with captive EPC resources and specialized ORC licensors dependent on third-party installation partnerships. Three archetypes dominate: geothermal-to-industrial technology transfer specialists, combined cycle equipment suppliers with bottoming cycle expertise, and energy service companies assuming performance risk through shared savings contracts. Consolidation pressure concentrates among mid-scale fabricators lacking working fluid R&D partnerships or green bond market access.
Within the technology transfer tier, Ormat Technologies and Turboden exemplify geothermal engineering adaptation to industrial waste streams. Siemens Energy anchors the turbomachinery-integrated segment through large-scale project execution capabilities. General Electric occupies a position bridging retrofit steam turbine expertise with emerging supercritical CO2 cycle development.
| Leading Market Players |
|---|
| Ormat Technologies |
| Turboden |
| Atlas Copco |
| Exergy International |
| Alfa Laval |
| General Electric |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| IHI Corporation |
| Others |
Supply Flow & Price Mechanics
Performance-guarantee contracting bifurcation separates premium ORC integrators from commodity skid suppliers, with the former capturing value through energy savings verification while the latter compete on equipment-only procurement. This divergence concentrates margin pools with German and Dutch EPC firms capable of underwriting carbon price exposure, whereas Asian fabricators without green bond access face compressed equipment margins and extended payment terms.
Pricing Analysis
Outcome-based pricing anchors premium-tier ORC deployments, with Siemens Energy and Ormat Technologies structuring shared-savings contracts that tie revenue to verified megawatt-hour generation. Price differentiation rests on working fluid thermodynamic modeling depth and turbine blade erosion warranty duration. Cost compression in mid-scale equipment runs through constrained hydrofluorocarbon availability under EU F-Gas Regulation phase-down schedules. Manufacturing facilities in Poland and Spain exhibit highest price sensitivity due to limited green financing instrument access, while German steel producers under CBAM pressure accept premium pricing for guaranteed carbon compliance.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke turbomachinery logistics, feeding installation clusters across the Rhine-Ruhr and Benelux chemical corridors. Manufacturing concentration centers on Germany, Italy, and Japan for precision turbine components, with working fluid production concentrated in Belgium and the United States. Supply chain risk from single-source dependency on specialized heat exchanger alloys feeds from nickel price volatility and Russian supply disruption legacy. Distribution runs through EPC-led turnkey contracting for large industrial retrofits, while modular skid suppliers serve mid-scale facilities through direct equipment sales with third-party installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
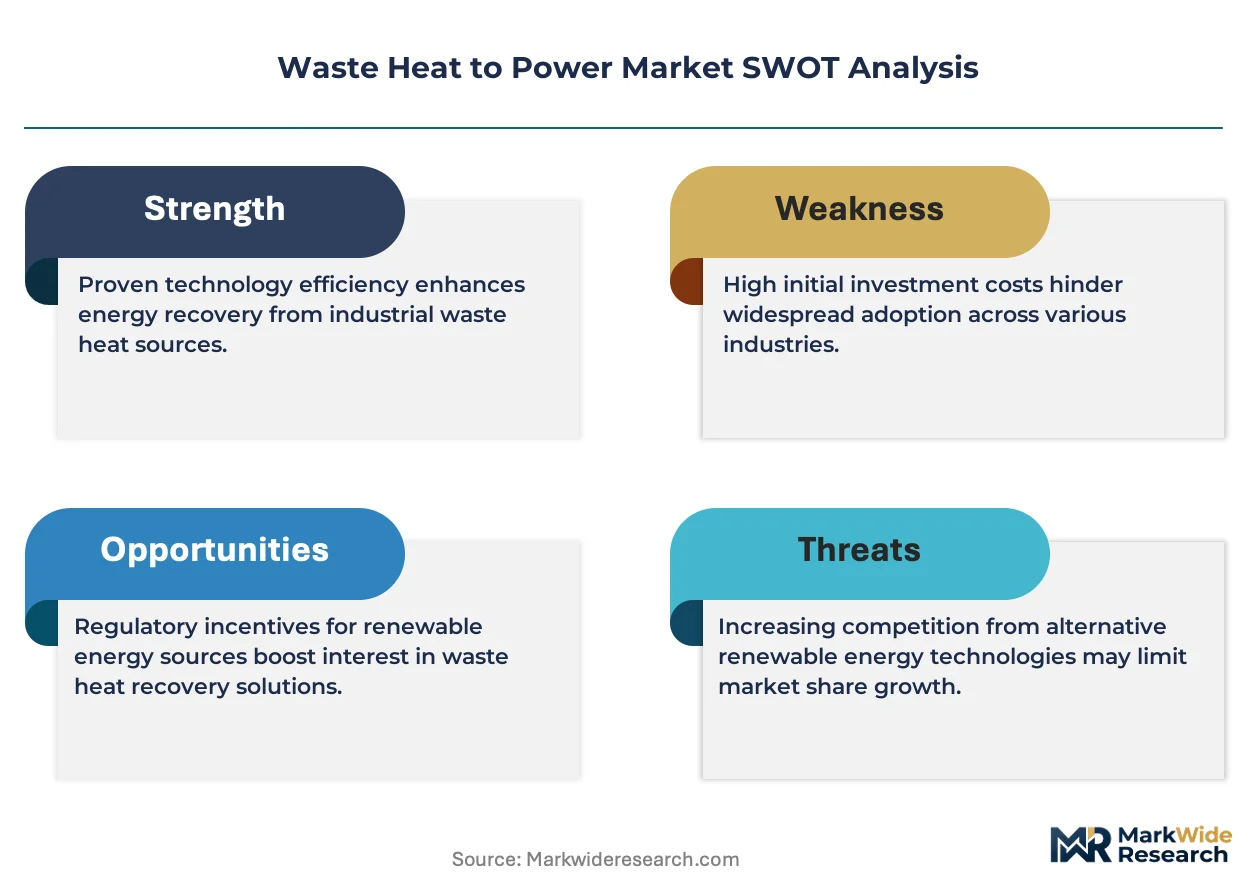
The EU Green Deal's industrial decarbonization mandates construct a compliance-cost moat that favors incumbent ORC specialists with established refrigerant fluid partnerships and carbon credit monetization expertise.
For Market Incumbents: Deploy performance-contracting balance sheet capacity to lock in German steel and cement retrofit pipelines before 2026 CBAM full implementation. Siemens Energy and Turboden should deepen backward integration into hydrofluoroolefin working fluid supply to preempt EU F-Gas Regulation procurement bottlenecks. Threat from supercritical CO2 cycle entrants at high-temperature steel applications demands accelerated sCO2 turbomachinery R&D partnerships. For New Entrants and Emerging Players: Capture data center thermal coupling white space in Northern Europe, where hyperscale computing facilities generate constant low-grade heat absent legacy industrial scheduling constraints. India's green hydrogen production clusters under PLI scheme incentives represent the most penetrable geography for electrolyzer-integrated waste heat recovery. Go-to-market positioning should emphasize modular ORC skids with rapid commissioning timelines against incumbent EPC-heavy project structures. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale ORC fabricators possessing working fluid R&D partnerships and green bond market access given accelerating industrial decarbonization capex cycles. Long-term viability favors technology licensors over pure equipment manufacturers as project finance structures shift toward energy service company risk assumption. Watch provincial enforcement intensity under China's MEE dual carbon goals as inflection signal for equipment supply contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Working Fluid Redesign Partnership | Hydrofluoroolefin transitions ahead of EU F-Gas Regulation deadlines secure certification continuity for Belgian and Dutch chemical producers. |
| Performance Contracting Expansion | Shared-savings structures transfer carbon price risk from German steel mills to ORC integrators with balance sheet depth. |
| Supercritical CO2 Cycle Development | sCO2 turbomachinery pilot programs at Tangshan electric arc furnaces displace steam turbine retrofits above 300°C. |
| Data Center Thermal Integration | Hyperscale computing facilities in Northern Europe generate constant low-grade heat outside traditional industrial verticals. |
| Provincial Quota Compliance Servicing | MEE enforcement at Hebei and Jiangsu steel plants creates mandatory installation timelines for technology licensors. |
Methodological Framework
Multi-period observation of ORC deployment volumes, carbon pricing trajectories, and refrigerant regulatory phase-down schedules anchored the trend analysis, supplemented by interviews with plant engineers at German steel and cement facilities, EPC project developers, working fluid procurement leads, and aftermarket service heads. Secondary validation drew from EU ETS price databases, EPC contract announcement tracking, F-Gas Regulation implementation notices, and SEC filings of listed turbomachinery suppliers. Bottom-up project pipeline enumeration triangulated against top-down carbon compliance cost modeling.
Input-output matrices mapped waste stream temperature profiles to technology economics across segmentation dimensions including thermodynamic cycle architecture, end-user industry vertical, application revenue model structure, and installation context. CAGRs were derived from regression-weighted deployment scenarios across the analysis window. Forecast inputs incorporated EU CBAM implementation timelines, China's MEE provincial enforcement intensity, and working fluid substitution cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment mechanism expansion beyond EU jurisdictions and breakthrough sCO2 cycle commercialization timelines. Outputs reflect documented assumptions around refrigerant availability, industrial production continuity, and green financing instrument accessibility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Canada Waste-To-Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market