
 Brazil Waste to Energy Market | 2026-2036
Brazil Waste to Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Waste to Energy Market Outlook
Capital-intensity divergence between incineration-focused multinationals and biological-technology domestic firms is unwinding competitive stability in Brazil. Veolia Environnement SA leverages its global thermal processing expertise to sustain large-scale project development in southeastern industrial corridors. SABESP anchors municipal feedstock access through its control of São Paulo's sanitation infrastructure. Solví Participações S.A. differentiates through specialized landfill gas capture and anaerobic digestion operations across multiple states.
Waste to energy encompasses thermal and biological processes that convert municipal solid waste, agricultural residues, and industrial byproducts into electricity, heat, or synthetic fuels through combustion, gasification, or anaerobic digestion at temperatures ranging from 35°C in bioreactors to over 850°C in incineration chambers. The technology serves Brazil's industrial and utility sectors by reducing landfill volumes while generating baseload power from otherwise discarded materials. Thermal processes currently dominate installed capacity due to mature equipment supply chains and higher energy output per ton processed. Biological methods represent the fastest-expanding segment as agricultural residues from Brazil's vast sugarcane and soybean operations create distributed feedstock opportunities with lower capital requirements. Feedstock type segmentation reveals municipal solid waste as the most contested input stream, with margin pools concentrating in long-term concession contracts for urban waste collection and processing.
ANVISA regulates emissions standards and public health protections for waste processing facilities, while the National Solid Waste Policy mandates landfill diversion targets that directly stimulate waste-to-energy project development. State environmental agencies in São Paulo and Minas Gerais enforce additional permitting requirements that shape project timelines and technology selection. Stakeholders must monitor proposed federal carbon credit mechanisms and state-level renewable energy auctions to determine whether biological or thermal platforms offer superior returns under evolving incentive structures.
Market Dynamics
Landfill capacity exhaustion in southeastern Brazil is decomposing the traditional waste disposal model and forcing municipalities toward energy recovery infrastructure. ANVISA emission standards and PNRS diversion mandates now compel utilities to procure thermal and biological processing capacity at unprecedented scale.
Growth Catalysts
- São Paulo State Landfill Constraints:Municipal utilities in Brazil's most populous state face imminent capacity exhaustion, accelerating procurement of waste-to-energy concessions.
- National Solid Waste Policy Mandates:Federal landfill diversion targets create binding obligations that channel municipal budgets toward energy recovery projects.
- Sugarcane Residue Feedstock Abundance:Brazil's ethanol industry generates distributed agricultural waste streams ideal for anaerobic digestion with lower transport costs than urban municipal solid waste.
Market Restraints
- Capital Intensity Disparity:Thermal incineration projects require substantially higher upfront investment than biological alternatives, limiting municipal procurement flexibility.
- Feedstock Supply Concentration:SABESP's control over São Paulo's sanitation infrastructure creates bottleneck risk for competitors seeking urban waste streams.
- Grid Interconnection Delays:State environmental agencies in Minas Gerais impose permitting timelines that extend project commissioning by 18-24 months.
Strategic Opportunities
- Northeast Industrial Corridor Expansion:Ceará and Pernambuco states offer underpenetrated markets with rising landfill costs and limited existing processing capacity.
- Federal Carbon Credit Mechanisms:Proposed national emissions trading systems would enhance project economics for early biological platform adopters.
- Biogas Upgrading Convergence:Integration of anaerobic digestion with biomethane purification technology opens pipeline injection revenue streams.
Industry Challenges
- Thermal Process Engineering Talent Scarcity:Brazil's academic pipeline produces insufficient specialists in high-temperature combustion system design and emissions control.
- Legacy Landfill Contract Renegotiation:Existing concession agreements bind municipalities to disposal fees that undercut energy recovery project viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Waste to Energy Market |
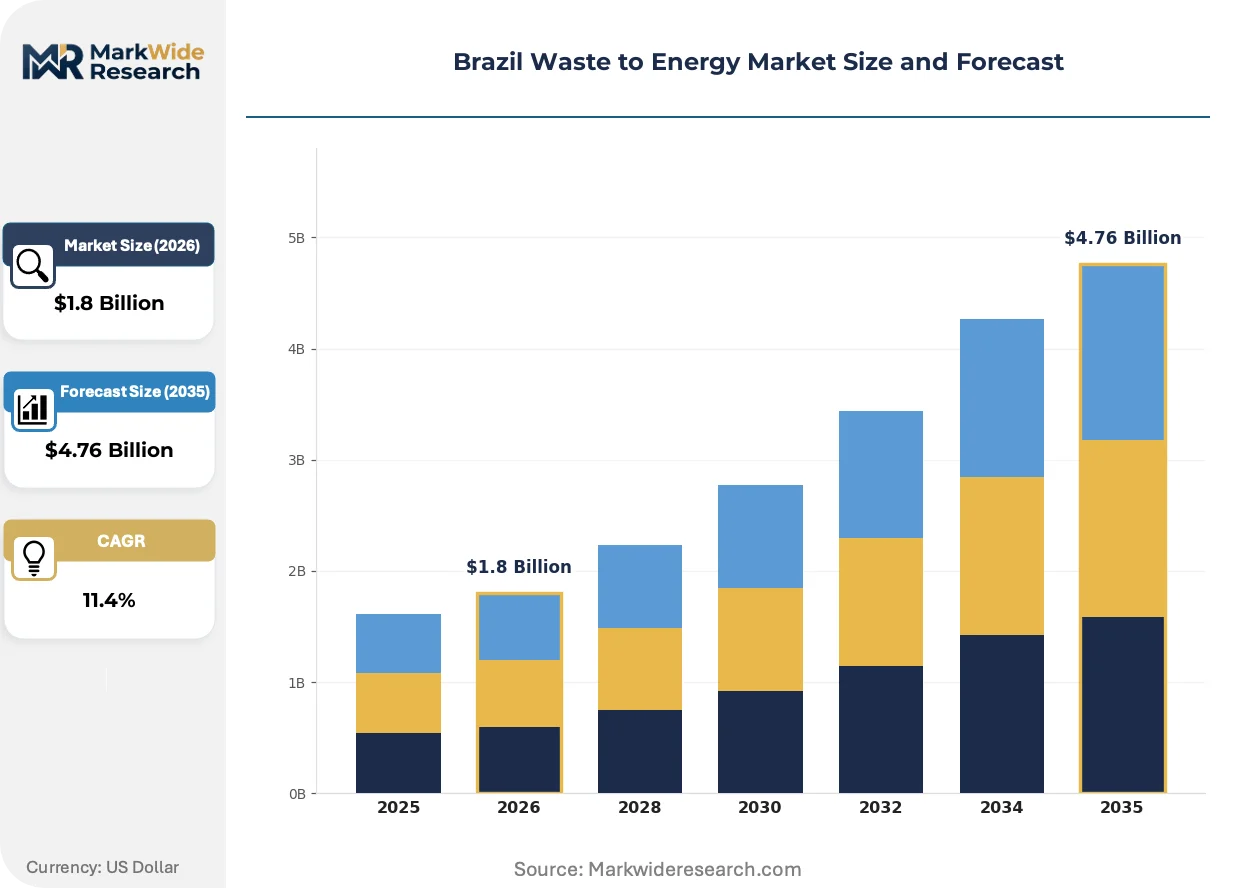
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal, Biological, Gasification, Incineration Feedstock Type: Municipal Solid Waste, Agricultural Residues, Industrial Waste, Biomass End User: Utilities, Industrial Sectors, Government Entities, Commercial Establishments Application: Electricity Generation, Heat Production, Fuel Production, Waste Reduction |
| Companies Covered | Haztec Tec. e Plan. Ambiental S.A., Veolia Environnement SA, Solví Participações S.A., ZEG Ambiental, CS Bioenergia, BOOTEC, RSU Brasil, Saneamento Básico do Estado de São Paulo (SABESP), AEGEA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Waste to Energy Market Strategic Shifts
Biological processing platforms are gaining ground against thermal incumbents as distributed agricultural feedstock logistics improve and carbon accounting methodologies mature. Three developments are restructuring competitive positioning.
Plasma gasification is decomposing the traditional incineration technology hierarchy in Brazil's southeastern industrial corridors. Steel mills and cement manufacturers in Minas Gerais are piloting plasma arc systems for hazardous industrial residue processing at 1,500°C operating temperatures. This technology is decomposing the volume-yield tradeoff that previously favored mass-burn incineration, enabling higher efficiency from lower-calorific feedstocks.
ANVISA's revised atmospheric emission standards for dioxins and furans are compressing project approval timelines for thermal facilities. The regulator's 2024 technical guidance requires continuous emissions monitoring systems that add substantial instrumentation costs. Municipal bidders in Rio de Janeiro state are responding by specifying fluidized bed combustion over grate systems to meet stricter thermal destruction efficiency thresholds.
Power purchase agreement structures are rotating toward long-term fixed-price contracts with industrial off-takers rather than spot-market merchant exposure. Food processing conglomerates in Paraná state are now contracting directly with biogas facility developers, bypassing traditional utility intermediaries. This bilateral contracting pattern is most visible in Brazil's southern states where industrial energy demand density intersects with agricultural residue availability.
Brazil Waste to Energy Market Segmentation
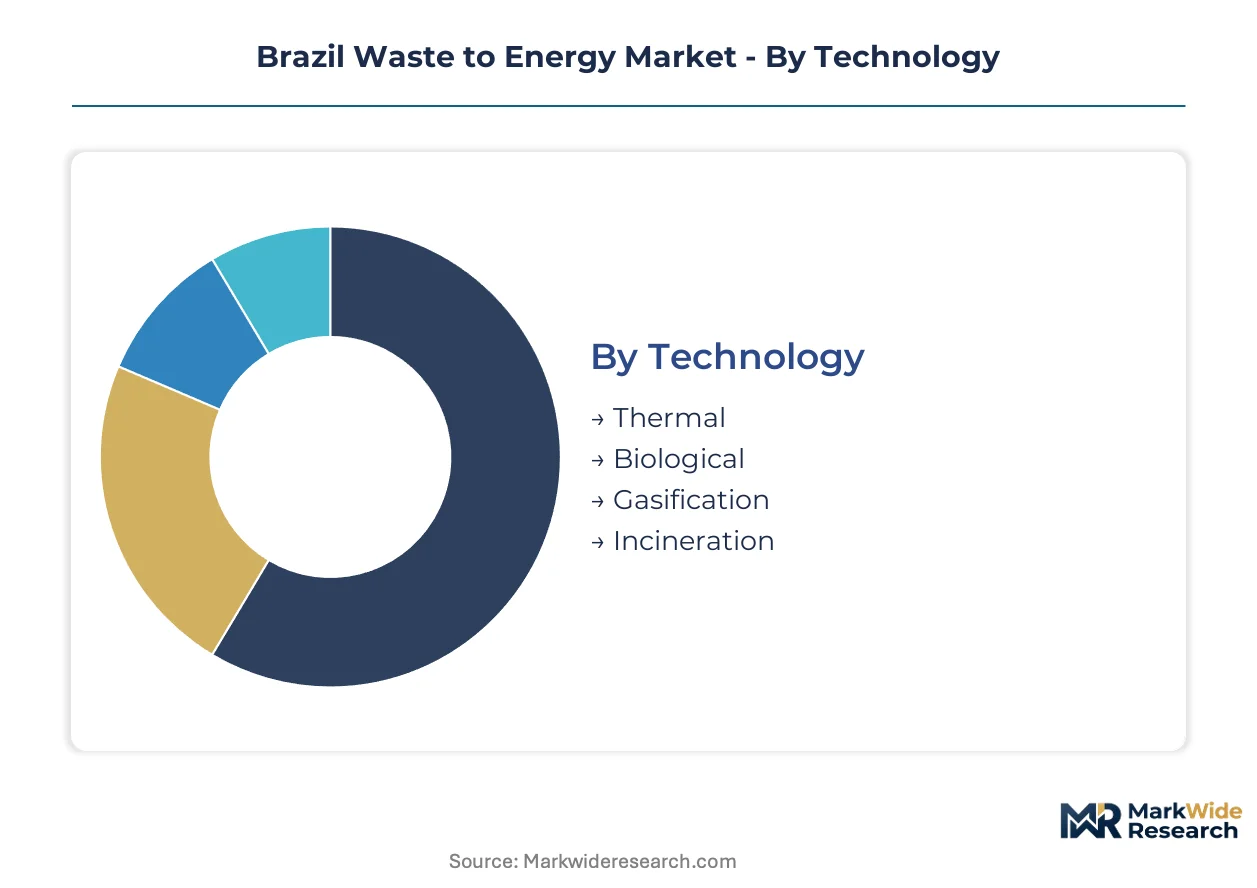
Waste-to-energy technologies in Brazil fragment across distinct processing platforms, feedstock origins, and offtake arrangements. Each segmentation dimension carries specific regulatory, capital, and logistics implications that shape project viability across São Paulo's urban corridors and the agricultural interior.
Technology:
Thermal platforms dominate southeastern Brazil's municipal procurement, while biological systems spread through sugarcane-producing states with lower transport infrastructure requirements.
- Thermal:Combustion-based systems operating above 850°C convert high-calorific waste streams into electricity through steam turbine generation. Demand concentrates in São Paulo state's metropolitan utilities, where ANVISA emission standards and landfill diversion mandates compel large-scale infrastructure investment.
- Biological:Anaerobic digestion and fermentation processes at 35-55°C break down organic matter to produce biogas for electricity or biomethane upgrading. Minas Gerais and Goiás agricultural processors drive procurement, leveraging distributed sugarcane bagasse and manure feedstock with minimal collection radius constraints.
- Gasification:Partial oxidation at 700-1000°C converts carbonaceous materials into synthetic gas for power generation or chemical synthesis.
- Incineration:Mass-burn and grate combustion systems remain the baseline thermal technology for urban municipal solid waste with established equipment supply chains.
Thermal commands the established base. The steepest expansion runs through biological.
Feedstock Type:
Input sourcing determines project economics through collection logistics, calorific value, and contamination risk profiles across Brazil's diverse waste generation geography.
- Municipal Solid Waste:Mixed urban refuse from household and commercial collection streams serves thermal incineration and gasification facilities. São Paulo's SABESP-controlled sanitation networks anchor supply security for concession-based projects in the state's industrial corridor.
- Agricultural Residues:Sugarcane bagasse, corn stover, and soybean hulls from Brazil's commodity crop belt provide distributed, low-contamination feedstock for anaerobic digestion. Paraná and Mato Grosso processors favor this stream for on-site energy self-sufficiency.
- Industrial Waste:Manufacturing byproducts and hazardous residues from steel, cement, and chemical operations.
- Biomass:Dedicated energy crops and forestry residues cultivated for intentional fuel supply.
Municipal solid waste anchors concession revenues. Agricultural residues are climbing the fastest as ethanol producers integrate circular energy systems.
End User:
Customer type dictates contracting structures, with utilities favoring standardized power purchase agreements and industrial offtakers pursuing bilateral supply arrangements.
- Utilities:State and municipal electricity distributors procure baseload capacity through auction mechanisms and concession tenders. Eletrobras subsidiaries and state distributors in Rio de Janeiro and São Paulo specify waste-to-energy in renewable portfolio requirements.
- Industrial Sectors:Food processing, pulp and paper, and chemical manufacturers contract directly for captive power and steam cogeneration. Paraná's meatpacking conglomerates now bypass utility intermediaries for biogas supply security.
- Government Entities:Federal and state agencies own and operate demonstration facilities and public infrastructure projects.
- Commercial Establishments:Retail, hospitality, and office complexes deploy on-site digestion for waste cost reduction and sustainability targets.
Utilities retain the largest procurement volumes. Industrial offtakers are expanding most quickly through direct bilateral contracting.
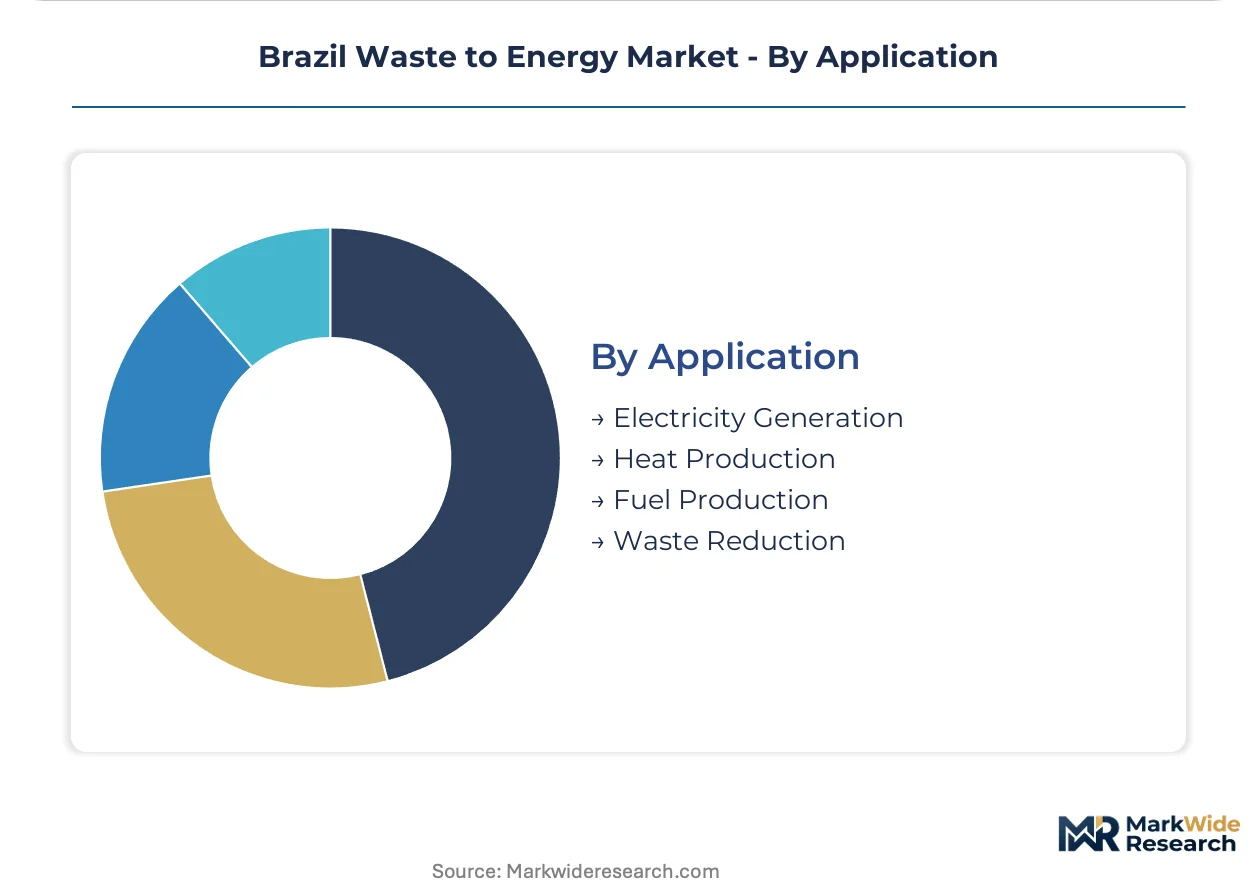
Application:
Output configuration determines technology selection and revenue stacking potential across Brazil's evolving energy market regulations.
- Electricity Generation:Grid-synchronized power production dominates project economics, with ANEEL regulatory frameworks governing interconnection and dispatch priority for renewable sources.
- Heat Production:Industrial process steam and district heating applications serve cement kilns, pulp dryers, and sugar mills in Minas Gerais and São Paulo.
- Fuel Production:Biomethane upgrading and synthetic fuel synthesis from syngas.
- Waste Reduction:Volume minimization and landfill diversion as primary objectives with energy recovery as secondary benefit.
Electricity generation holds the revenue base. Fuel production shows the steepest trajectory as biomethane pipeline injection standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo commands premium concession pricing that Minas Gerais municipalities cannot replicate, creating a two-tier procurement landscape across Brazil's southeastern corridor.
São Paulo
Landfill capacity exhaustion and SABESP's sanitation infrastructure dominance drive concession-based procurement. ANVISA emission standards tighten project approval timelines. The metropolitan corridor anchors thermal incineration deployment with industrial energy demand density.
Minas Gerais
Steel and cement manufacturers generate hazardous industrial residue streams requiring high-temperature processing. State environmental agencies impose 18-24 month permitting extensions. The Belo Horizonte industrial cluster pilots plasma gasification for complex waste streams.
Rio de Janeiro
Municipal utilities face binding PNRS diversion mandates with limited existing processing infrastructure. ANVISA's 2024 dioxin monitoring requirements reshape technology specifications. The metropolitan region accelerates fluidized bed combustion procurement over grate systems.
Paraná
Food processing conglomerates drive bilateral biogas contracting outside utility channels. Distributed sugarcane bagasse feedstock enables anaerobic digestion at lower transport costs. The western agricultural belt integrates circular energy systems with ethanol production.
Bahia
Northeast industrial corridor expansion offers underpenetrated markets with rising landfill disposal fees. Limited existing processing capacity reduces competitive congestion for new entrants. The Camaçari petrochemical complex evaluates captive waste-to-energy for process steam.
Brazil Waste to Energy Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive stability across Brazil's waste-to-energy procurement channels. Thermal incineration specialists command premium concession margins in São Paulo's metropolitan utilities, while biological platform operators capture distributed agricultural feedstock opportunities at lower capital intensity. Three archetypes dominate: multinational engineering conglomerates with global thermal expertise, domestic sanitation utilities controlling urban feedstock access, and specialized biological processors leveraging agricultural residue logistics. Competitive moves concentrate on long-term concession bidding for municipal contracts and strategic partnerships with industrial offtakers seeking captive energy supply.
Among Brazil-based operators, SABESP exemplifies the utility-archetype through its control of São Paulo's sanitation infrastructure and municipal feedstock channels. Veolia Environnement SA represents the multinational engineering tier with thermal processing capabilities deployed across southeastern industrial corridors. Solví Participações S.A. occupies a position within the specialized biological segment, with operations spanning multiple states through landfill gas capture and anaerobic digestion platforms.
| Leading Market Players |
|---|
| Haztec Tec. e Plan. Ambiental S.A. |
| Veolia Environnement SA |
| Solví Participações S.A. |
| ZEG Ambiental |
| CS Bioenergia |
| BOOTEC |
| RSU Brasil |
| Saneamento Básico do Estado de São Paulo (SABESP) |
| AEGEA |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month permitting timelines in Minas Gerais compress equipment procurement windows and amplify pricing power for thermal incineration specialists with established ANVISA compliance track records. Municipal utilities in São Paulo's metropolitan corridor absorb premium concession pricing to secure feedstock certainty through SABESP-controlled sanitation networks, while agricultural residue processors in Paraná negotiate lower capital intensity through distributed anaerobic digestion deployments.
Pricing Analysis
Configured-to-order thermal incineration systems command 40-60% premiums over standardized biological platform pricing due to ANVISA emission monitoring requirements and site-specific engineering. Project-based long-term offtake contracts dominate municipal procurement, with price differentiation resting on certification tier (continuous emissions monitoring vs. periodic sampling) and volume scale (metropolitan concessions vs. distributed rural facilities). Cost compression in biological segments intensifies as ethanol producers integrate captive energy systems and bypass utility intermediaries. Industrial offtakers in food processing exhibit lowest price sensitivity due to energy security premiums, while municipal utilities face acute budget constraints from PNRS compliance mandates.
Supply Chain Analysis
Port congestion at Santos and Paranaguá elevates inbound logistics costs for European and Asian combustion equipment, extending commissioning timelines for thermal projects. Equipment supply concentrates in Germany, Italy, and China for grate systems, fluidized bed reactors, and emissions control instrumentation. Raw material dependencies center on specialty steel alloys, ceramic refractories, and continuous monitoring sensors. Single-source vulnerability runs through plasma gasification arc torch suppliers, where limited qualified vendors constrain project scalability. Distribution runs through EPC contractors with ANVISA certification relationships, anchoring downstream structure in southeastern Brazil's industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's waste-to-energy market represents early-cycle expansion with landfill diversion mandates from PNRS and ANVISA tightening emission standards creating structural demand tailwinds. Penetration remains below 15% of addressable municipal waste streams, leaving substantial runway for technology deployment.
For Market Incumbents: Compound concession portfolios in São Paulo's metropolitan corridor to lock feedstock access against SABESP's infrastructure dominance. Prioritize fluidized bed combustion R&D to meet ANVISA's 2024 dioxin monitoring thresholds, defending thermal platform margins against biological alternatives. Add anaerobic digestion capacity in Paraná and Minas Gerais agricultural belts to capture distributed residue flows before regional specialists consolidate.
For New Entrants and Emerging Players: Lead with biomethane upgrading technology in Ceará and Pernambuco, where underpenetrated markets and rising landfill costs reduce competitive congestion. Target food processing conglomerates in southern Brazil with bilateral contracting models that bypass utility auction mechanisms. Establish go-to-market positioning through equipment-leasing structures that minimize municipal capital expenditure barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because PNRS diversion targets and ANVISA emission standards create binding procurement obligations that outlast commodity price cycles. Acquisition targets should display landfill gas capture expertise with existing concession relationships in multiple states. Watch federal carbon credit mechanism legislation as the inflection signal for biological platform valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Portfolio Expansion | Secures decades-long feedstock access through SABESP-partnered municipal contracts in São Paulo state. |
| Biomethane Upgrading Integration | Opens pipeline injection revenue streams under evolving ANP regulatory frameworks for renewable gas. |
| Plasma Gasification Piloting | Addresses hazardous industrial residue streams from Minas Gerais steel and cement manufacturers. |
| Backward Integration into Feedstock Collection | Reduces transport cost exposure for agricultural residue processors in Goiás and Mato Grosso. |
| Continuous Emissions Monitoring Certification | Qualifies thermal projects for expedited ANVISA approval under 2024 technical guidance requirements. |
Study Parameters
Desk research of ANVISA regulatory filings, PNRS policy documents, and ANEEL interconnection databases preceded structured interviews with utility planning officers, EPC contractors, municipal sanitation directors, and agricultural processor energy managers. Primary fieldwork with thermal equipment suppliers and biological platform developers was cross-validated against state environmental agency permitting records and concession tender documentation. Bottom-up project pipeline enumeration was triangulated with top-down market sizing from waste generation statistics and energy recovery potential estimates.
Variance decomposition across technology platform, feedstock type, and regional regulatory cluster shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included thermal versus biological processing, municipal solid waste versus agricultural residue sourcing, and utility offtake versus industrial captive consumption. CAGRs were derived from installed capacity buildout trajectories, concession award timelines, and feedstock availability curves. Key inputs encompassed ANVISA emission standard compliance costs and state-level renewable energy auction participation rates.
The analysis sits within stated boundaries; outcomes outside sustained PNRS enforcement, ANVISA regulatory continuity, or grid interconnection capacity expansion would require recalibration. Forecasts reflect assumptions regarding landfill capacity exhaustion timelines and carbon credit mechanism implementation. Specific risks that could revise projections include federal policy reversals on waste diversion mandates, prolonged permitting delays in Minas Gerais, or feedstock competition from alternative agricultural residue valorization pathways. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Drilling Waste Management Services Market