
 Drilling Waste Management Services Market | 2026-2036
Drilling Waste Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Waste Management Services Market Foresight
Offshore well construction is consolidating as the dominant demand vertical for drilling waste management services. Halliburton Company leverages its integrated wellbore construction portfolio to bundle waste handling with drilling contracts. Baker Hughes Company competes through advanced solids control equipment deployed across deepwater basins. Schlumberger Limited anchors its position via technology leadership in automated waste characterization systems.
Drilling waste management services encompass the collection, treatment, transportation, and disposal of cuttings, spent drilling fluids, and associated contaminants generated during oil and gas well construction, typically handling synthetic-based muds with oil retention below 1% by weight for offshore discharge compliance. Solid control represents the most mature service category, with centrifuge and shaker technology dominating routine onshore operations while thermal desorption commands premium pricing for hazardous offshore cuttings requiring zero-discharge handling. Fluid management is gaining share as operators prioritize closed-loop systems that reduce freshwater consumption and chemical exposure liability.
The US EPA governs offshore discharge through NPDES permits and coastal zone management requirements, while the EU REACH regulation restricts hazardous chemical additives in drilling formulations. Norway's Petroleum Safety Authority enforces some of the strictest offshore waste handling protocols, effectively mandating advanced treatment equipment for North Sea operations. Stakeholders must monitor regulatory divergence between jurisdictions to calibrate technology investment and service pricing models.
Market Dynamics
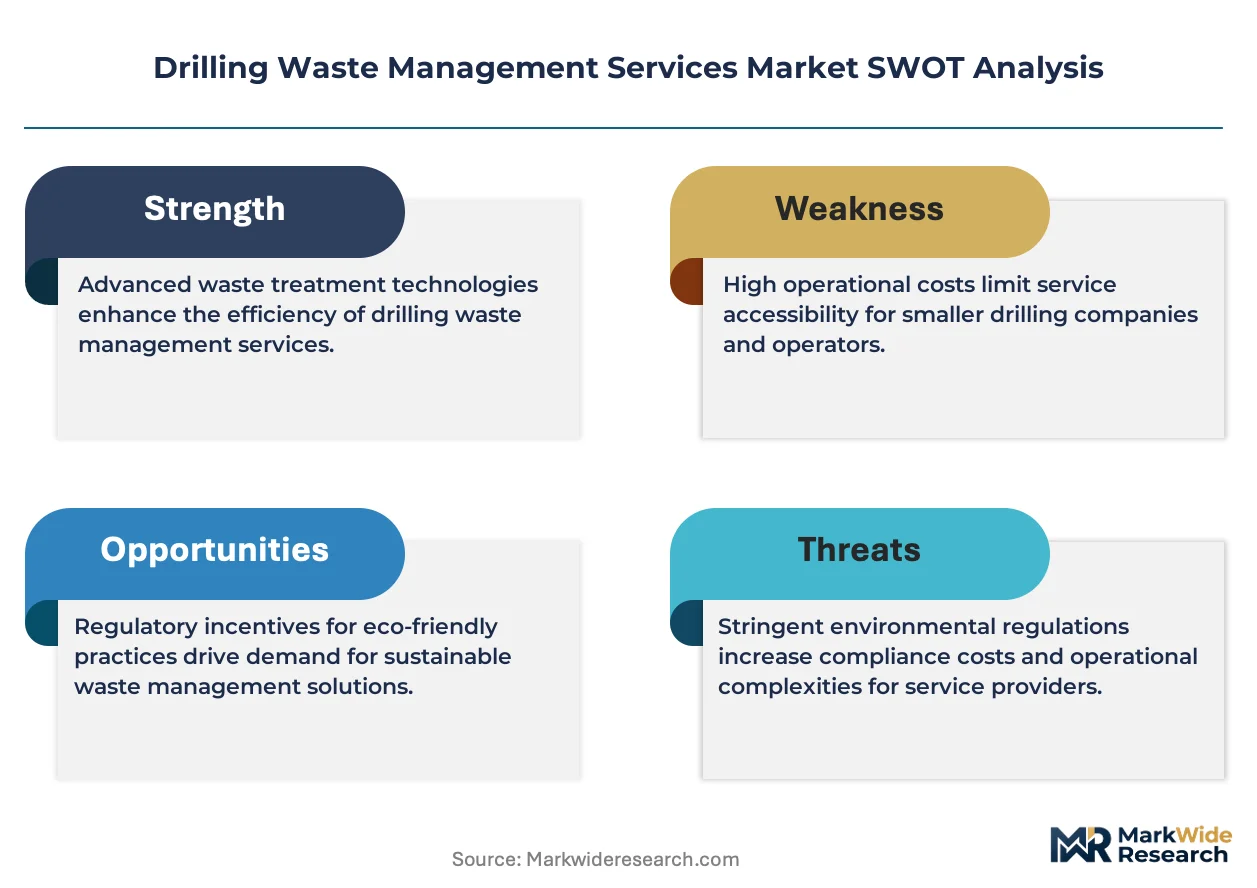
Integrated closed-loop systems are compressing the addressable market for standalone waste transport and disposal vendors, as operators internalize treatment capacity to meet zero-discharge mandates.
Growth Catalysts
- EPA NPDES discharge limits:Tightened offshore permit conditions in US waters force thermal desorption and cuttings reinvestment adoption, expanding serviceable equipment hours per well.
- Pre-salt basin development:Brazil's ultra-deepwater drilling programs generate synthetic-based mud volumes requiring specialized handling, concentrating demand in the Campos and Santos basins.
- Closed-loop fluid systems:Operators deploy centrifuge-integrated shaker packages to reduce freshwater consumption and chemical exposure liability on multi-well pads.
Market Restraints
- High-sulfur steel input volatility:Centrifuge bowl and shaker screen manufacturing costs fluctuate with specialty alloy pricing, compressing equipment rental margins.
- North Sea supplier concentration:Thermal desorption unit fabrication relies on a limited Norwegian and Scottish vendor base, creating equipment availability bottlenecks during drilling campaign peaks.
- EU REACH chemical friction:Registration requirements for novel drilling fluid additives delay formulation approvals, slowing technology substitution cycles.
Strategic Opportunities
- Guyana-Suriname basin emergence:ExxonMobil-operated Stabroek block development creates demand for offshore waste handling infrastructure without established local treatment capacity.
- CCUS drilling waste integration:Carbon capture well construction generates novel cement-contaminated cuttings streams requiring modified thermal treatment chemistries.
- Norwegian NOx fund incentives:Tax relief programs for low-emission offshore equipment accelerate electric shaker and centrifuge adoption in North Sea operations.
Industry Challenges
- Thermal desorption technician scarcity:Specialized combustion chamber operation and emissions monitoring skills command premium wages, constraining fleet expansion.
- API RP 13C certification timelines:Shaker screen validation protocols extend product launch cycles, delaying competitive responses to abrasive formation demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Waste Management Services Market |
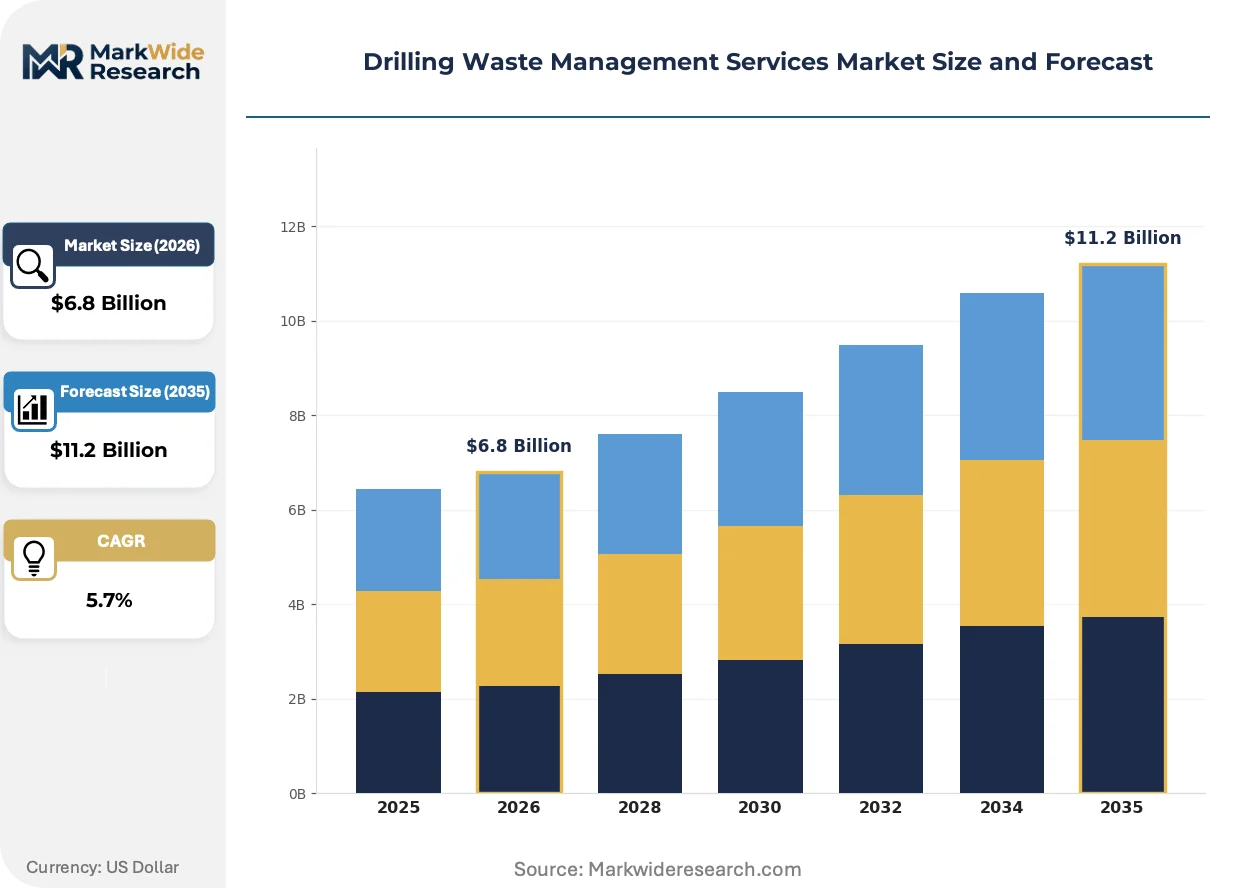
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Solid Control, Fluid Management, Waste Disposal, Environmental Compliance Application: Onshore Operations, Offshore Operations, Well Construction, Remediation Services End User: Oil Companies, Service Providers, Environmental Agencies, Contractors Technology: Centrifuges, Shakers, Thermal Desorption, Bioremediation |
| Companies Covered | Weatherford International PLC, TWMA Group Ltd, Halliburton Company, Secure Energy Services Inc., Clean Harbors Inc., Baker Hughes Company, National Oilwell Varco Inc., GN Solids Control, Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Waste Management Services Market Shifts & Advancements
Automation and real-time characterization are transforming waste segregation from manual sampling to continuous monitoring, compressing treatment decision cycles and reducing offshore personnel exposure.
Thermal desorption units with automated feed control and stack gas analysis are overtaking batch-operated legacy systems in offshore zero-discharge applications. North Sea contractors deploy these systems to maintain continuous operations through weather-restricted helicopter logistics. The technology is enabling 24-hour processing cycles that compress vessel time-on-station by eliminating batch cooldown periods.
Norway's Petroleum Safety Authority enforcement of OSPAR Convention guidelines mandates oil-on-cuttings below 1% for seabed discharge permits. This regulatory pressure accelerates thermal treatment equipment deployment against simpler skip-and-ship alternatives. Deepwater Gulf of Mexico operators now specify equivalent standards to preempt EPA enforcement actions.
Integrated service contracting is displacing discrete waste management procurement, with drilling contractors bundling solids control and disposal into day-rate structures. Independent service providers respond by offering equipment-as-a-service models with guaranteed uptime clauses. The shift is most visible in US shale plays where private equity-backed operators prioritize predictable cost structures over capital ownership.
Drilling Waste Management Services Market Segmentation
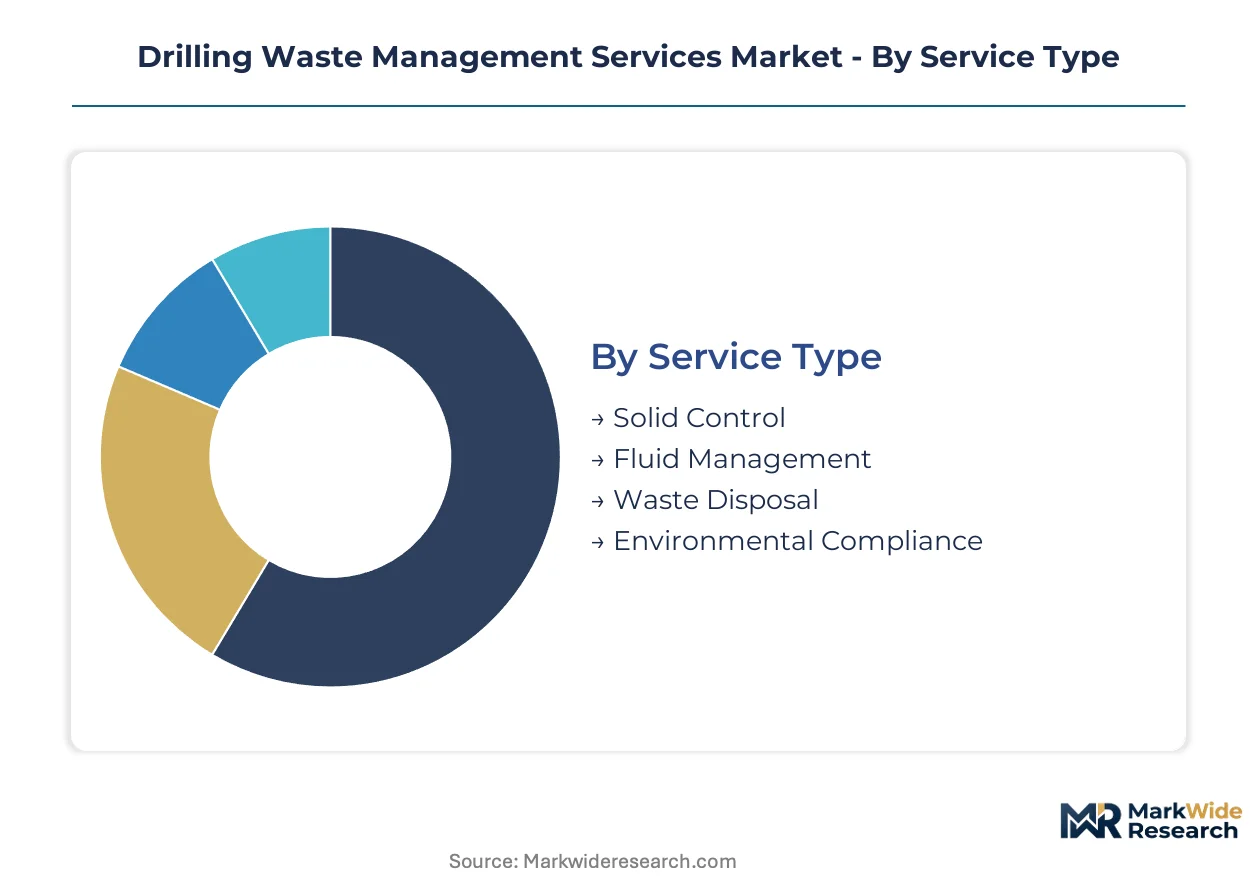
Service differentiation in drilling waste management determines equipment deployment models, regulatory compliance pathways, and contracting structures. Segmentation reveals where standalone vendors compete against integrated drilling contractors and which technology platforms command premium positioning.
Service Type:
Standalone service contracts dominate lower-complexity basins while integrated packages capture deepwater zero-discharge mandates.
- Solid Control:Centrifuge and shaker systems separate drill cuttings from returning fluids at the wellsite, achieving oil retention levels below regulatory thresholds. Demand concentrates in US shale plays where multi-well pad drilling maximizes equipment utilization rates and reduces per-well mobilization costs.
- Fluid Management:Closed-loop systems treat and recycle drilling fluids to reduce freshwater consumption and chemical procurement volumes. Norway's North Sea corridor drives specification intensity as OSPAR Convention compliance mandates continuous fluid characterization and automated dosing controls.
- Waste Disposal:Skip-and-ship operations transport untreated cuttings to shore-based treatment facilities or approved landfill sites. Onshore US Permian and Bakken basins sustain this segment through lower regulatory stringency and established road infrastructure.
- Environmental Compliance:Permitting support, emissions monitoring, and regulatory documentation services anchor project approval timelines. Brazil's pre-salt licensing requirements create specialized demand for IBAMA compliance documentation and seabed impact assessments.
Solid Control leads volumes today; Fluid Management is gaining share fastest.
Application:
Operational setting dictates treatment technology selection, personnel safety requirements, and logistics complexity.
- Onshore Operations:Land-based drilling permits simpler waste transport via road networks and lower-cost thermal treatment alternatives. US Gulf Coast shale operators deploy mobile centrifuge units that relocate between pads without vessel charter dependencies.
- Offshore Operations:Platform and drillship installations require zero-discharge capable equipment with automated operation to minimize helicopter personnel rotations. Brazil's Santos Basin and Norway's Johan Sverdrup field anchor specification intensity for continuous thermal desorption systems.
- Well Construction:Primary drilling phases generate the largest waste volumes and drive solids control equipment rental demand. Multi-well development programs in Guyana's Stabroek block concentrate procurement timing around rig contract commencements.
- Remediation Services:Legacy site cleanup and abandoned well restoration create episodic demand for specialized bioremediation and soil washing. Former Soviet bloc producing regions in Kazakhstan and Azerbaijan sustain this segment through state-funded environmental liability programs.
Well Construction anchors current revenue; Offshore Operations shows the steepest expansion trajectory.
End User:
Procurement authority shapes contract duration, performance guarantees, and technology adoption incentives.
- Oil Companies:Supermajors and national oil companies specify equipment standards and environmental performance clauses in drilling contracts. ExxonMobil, Equinor, and Petrobras drive thermal desorption adoption through internal sustainability targets that exceed regulatory minimums.
- Service Providers:Drilling contractors and integrated well service companies bundle waste management into day-rate structures to capture margin from equipment utilization. Halliburton and Baker Hughes leverage this model across deepwater Gulf of Mexico and North Sea campaigns.
- Environmental Agencies:Government regulators mandate treatment standards and audit compliance without direct equipment procurement. EPA, Norway's Petroleum Safety Authority, and Brazil's IBAMA influence technology selection through permit conditions and enforcement priorities.
- Contractors:Specialized waste management vendors compete for discrete service awards in basins with fragmented operator presence. Independent providers concentrate in US Permian and Canadian oil sands where drilling activity disperses across numerous small-to-mid-cap producers.
Service Providers capture the largest contract value today; Oil Companies are consolidating procurement authority fastest.
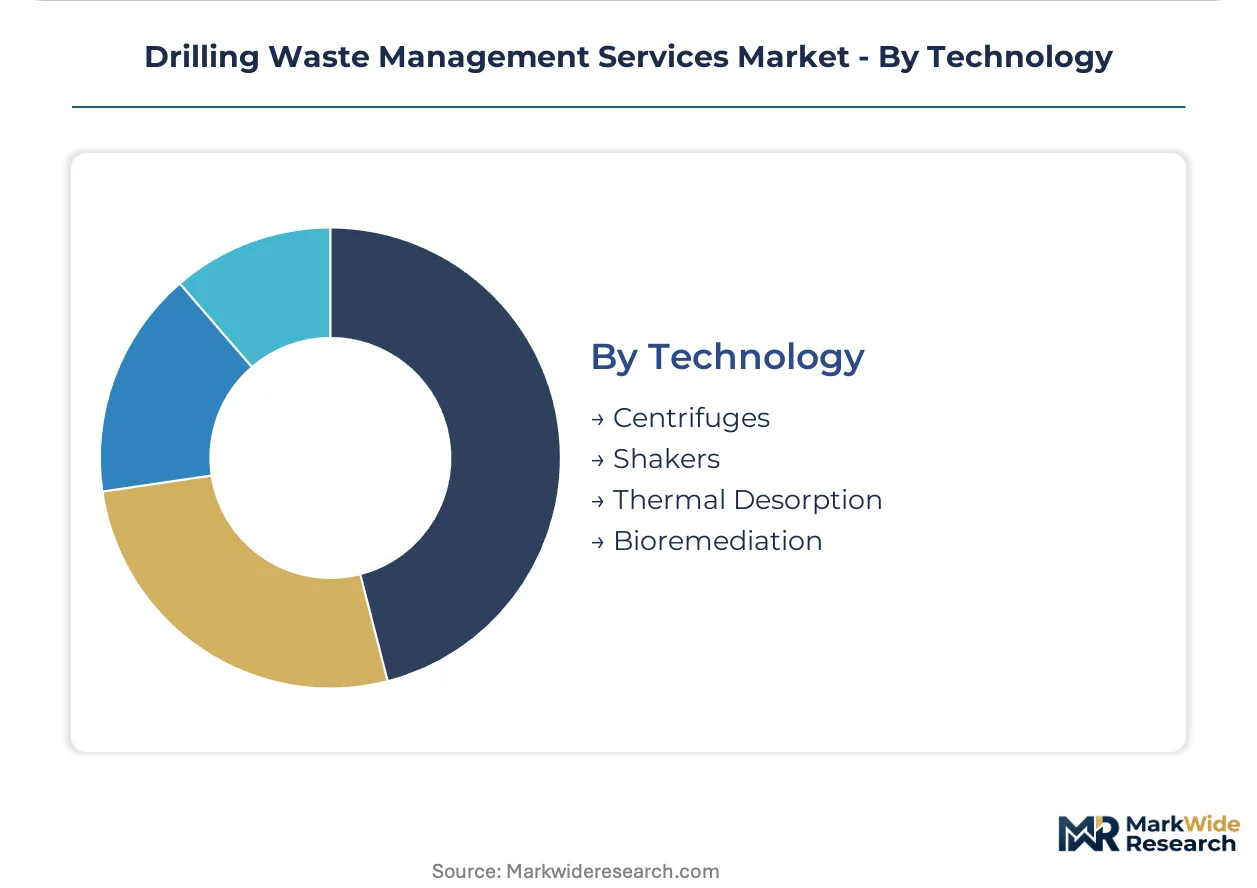
Technology:
Equipment selection balances capital intensity, operational footprint, and residue quality requirements.
- Centrifuges:High-speed rotating bowls separate fine solids from drilling fluids through differential density separation. Onshore US and Middle East land drilling sustain this segment through lower capital requirements and established maintenance supply chains.
- Shakers:Vibrating mesh screens perform primary solids removal at the flowline before fluid enters active circulation systems. API RP 13C certification requirements constrain supplier base and extend procurement lead times for abrasive formation applications.
- Thermal Desorption:Indirect heating systems volatilize hydrocarbons from cuttings to achieve oil-on-cuttings below 1% for offshore discharge compliance. Norway's NOx fund tax incentives accelerate electric-powered unit adoption in North Sea zero-discharge operations.
- Bioremediation:Microbial treatment processes degrade hydrocarbon contaminants in landfarming and bioreactor configurations. Kazakhstan's legacy soil remediation programs and select onshore US site closures sustain this lower-throughput alternative.
Shakers and Centrifuges dominate installed base today; Thermal Desorption is climbing the fastest on offshore specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting drilling waste management procurement toward jurisdictions where compliance costs align with project economics. Operators migrate thermal desorption capacity toward stricter enforcement zones to preempt liability exposure rather than retrofit legacy systems.
United States
Gulf of Mexico deepwater drilling and Permian Basin shale activity sustain dual demand tracks. EPA NPDES permit tightening forces platform operators toward continuous thermal treatment systems. Houston anchors equipment fabrication and service contractor headquarters concentration.
Norway
North Sea field redevelopment and Johan Sverdrup expansion drive zero-discharge specification intensity. Petroleum Safety Authority OSPAR enforcement mandates oil-on-cuttings below 1% for seabed discharge permits. Stavanger clusters thermal desorption unit engineering and specialist technician training facilities.
Brazil
Pre-salt basin development in Campos and Santos generates synthetic-based mud volumes requiring specialized handling. IBAMA licensing requirements create demand for integrated compliance documentation and seabed impact assessments. Rio de Janeiro concentrates Petrobras procurement authority and service provider regional headquarters.
United Kingdom
North Sea decommissioning and remaining field life extension sustain waste handling demand through 2035. HSE offshore environmental regulations align with OSPAR standards, preventing regulatory arbitrage with Norwegian operations. Aberdeen maintains solids control equipment maintenance and spare parts distribution infrastructure.
Canada
Alberta oil sands thermal drilling and British Columbia LNG development create distinct waste stream profiles. Provincial regulators enforce oil-based mud containment standards that exceed federal baseline requirements. Calgary hosts independent service provider contracting operations for Western Canadian Sedimentary Basin campaigns.
Drilling Waste Management Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated drilling contractors capturing bundled procurement in deepwater basins while independent vendors compete for discrete awards in fragmented onshore markets. The structure concentrates around three strategic archetypes: oilfield service conglomerates with bundled well construction portfolios, standalone waste management specialists with equipment-as-a-service models, and environmental services conglomerates with hazardous waste logistics networks. Competitive moves center on M&A for thermal treatment capacity acquisition and strategic partnerships for zero-discharge technology licensing in emerging basins.
Within the integrated service tier, Halliburton Company and Baker Hughes Company exemplify the bundled contracting model, anchoring deepwater Gulf of Mexico and North Sea procurement structures. Schlumberger Limited occupies a position emphasizing automated waste characterization systems. Among standalone specialists, TWMA Group Ltd represents the equipment-focused archetype with North Sea fabrication heritage, while Clean Harbors Inc. exemplifies environmental services conglomerate positioning through hazardous waste logistics scale. Secure Energy Services Inc. sits within the mid-cap independent tier competing for discrete awards in North American onshore basins.
| Leading Market Players |
|---|
| Weatherford International PLC |
| TWMA Group Ltd |
| Halliburton Company |
| Secure Energy Services Inc. |
| Clean Harbors Inc. |
| Baker Hughes Company |
| National Oilwell Varco Inc. |
| GN Solids Control |
| Schlumberger Limited |
| Others |
Supply & Pricing Matrix
Captive equipment manufacturing by integrated drilling contractors anchors supply positions while compressing pricing power for standalone rental vendors. Halliburton and Baker Hughes internalize centrifuge and shaker production to shield margins from high-sulfur steel volatility, forcing independents toward equipment-as-a-service models with uptime guarantees.
Pricing Analysis
Distributor margins for thermal desorption unit rentals absorb fabrication bottlenecks in Norway and Scotland. Three-tier pricing structure across premium automated systems, standard batch units, and economy skip-and-ship alternatives reflects OSPAR compliance intensity. Cost compression in the economy tier is intensifying because US shale operators prioritize predictable day-rates over capital ownership. National oil companies exhibit lowest price sensitivity due to sustainability targets exceeding regulatory floors.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian and Scottish fabrication yards for thermal desorption chamber assembly. Manufacturing draws from China for shaker screen mesh, Germany for precision centrifuge bearings, and US Gulf Coast for alloy steel castings. Tariff exposure on high-sulfur steel inputs threatens equipment rental margins. Distribution runs through Houston and Stavanger service hubs to deepwater basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA NPDES tightening and OSPAR enforcement continuously upgrade equipment specifications, embedding demand for thermal treatment capacity.
For Market Incumbents: Hedge against integrated contractor bundling by acquiring automated waste characterization capabilities. Secure fabrication slots at Aberdeen and Stavanger yards before drilling campaign peaks strain capacity. Thermal desorption technician scarcity threatens fleet expansion timelines.
For New Entrants and Emerging Players: The premium-to-economy price gap in offshore solids control opens white-space at the mid-tier automated shaker segment. Target Guyana-Suriname basin infrastructure gaps before local treatment capacity matures. Lead with electric-powered equipment qualifying for Norway's NOx fund tax relief.
For Investors and Strategic Acquirers: Roll-up economics work for independent thermal treatment specialists because North Sea supplier concentration prevents rapid capacity replication. Five-to-ten year viability hinges on CCUS drilling waste integration capabilities. Monitor IBAMA licensing velocity in Brazil's pre-salt as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Thermal Desorption Deployment | Norway's Petroleum Safety Authority mandates oil-on-cuttings below 1% for seabed discharge permits. |
| Electric Equipment Certification | NOx fund tax relief accelerates electric shaker and centrifuge adoption in North Sea zero-discharge operations. |
| CCUS Waste Stream Adaptation | Carbon capture well construction generates cement-contaminated cuttings requiring modified thermal chemistries. |
| Guyana-Suriname Basin Infrastructure | ExxonMobil-operated Stabroek block development lacks established local treatment capacity. |
| Closed-Loop Fluid System Integration | Multi-well pad drilling in US shale maximizes equipment utilization and reduces freshwater consumption liability. |
Research Methodology
Coverage spans the US Gulf Coast, Norway's North Sea corridor, and Brazil's pre-salt basins, with primary inputs from each. Drilling contractors, thermal desorption unit operators, EPA and IBAMA regulatory affairs specialists, and offshore logistics coordinators provided field intelligence. Secondary validation drew from EPA NPDES permit databases, OSPAR Convention compliance records, Norwegian Petroleum Safety Authority enforcement bulletins, and Petrobras procurement disclosures. Bottom-up equipment deployment counts triangulate against top-down operator capex allocations.
Rate-of-change decomposition separates volume growth from specification upgrading across the projection horizon. Segmentation dimensions modeled include service type, operational setting, end-user procurement authority, and treatment technology platform. CAGRs derive from equipment hours per well trajectories and regulatory-driven replacement cycles. Forecast inputs incorporate thermal desorption fleet utilization rates and synthetic-based mud volume projections from pre-salt drilling programs.
Caveats apply where EPA enforcement intensity or OSPAR guideline revisions could materially shift the outlook. Forecasts reflect assumptions about regulatory stability and drilling campaign timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Canada Waste-To-Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Nuclear Waste Recycling Market