
 North America Waste to Energy Market | 2026-2036
North America Waste to Energy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Waste to Energy Market Analytics
Biomass feedstock is decoupling from coal-dependent baseload economics in the North American power stack. Covanta Holding Corp dominates the incineration fleet across the United States with operational scale that anchors its tolling contracts with municipalities. Waste Management Inc. leverages its collection density to secure long-term feedstock agreements for energy recovery facilities. Babcock & Wilcox Enterprises, Inc. differentiates through boiler and emissions control technology leadership in utility-scale installations.
Waste to energy denotes thermal and biological processes that convert non-recyclable waste streams into electricity, heat, or synthetic fuels at combustion temperatures exceeding 850°C for incineration systems and controlled oxygen conditions for gasification. The primary purpose is volume reduction of municipal and industrial waste simultaneous with energy recovery, displacing fossil baseload while diverting material from landfill methane release. Incineration occupies the mature core of the technology mix with established operational track records and bankable project finance structures. Anaerobic digestion represents the fastest-expanding segment as agricultural and food waste regulations tighten organic diversion mandates across multiple jurisdictions. Gasification commands premium engineering margins but remains deployment-constrained by feedstock consistency requirements and capital intensity.
The EPA enforces Maximum Achievable Control Technology standards under the Clean Air Act that dictate particulate, mercury, and dioxin limits for municipal waste combustors, directly shaping stack gas treatment capital allocation. State-level renewable portfolio standards in California, New York, and Massachusetts classify WTE output as Tier 1 renewable generation, creating certificate value streams that improve project returns. The IRA production tax credit extension for waste-derived electricity further modifies developer underwriting assumptions. Stakeholders must monitor feedstock tipping fee trajectories against natural gas price volatility to assess baseload competitiveness.
Market Dynamics
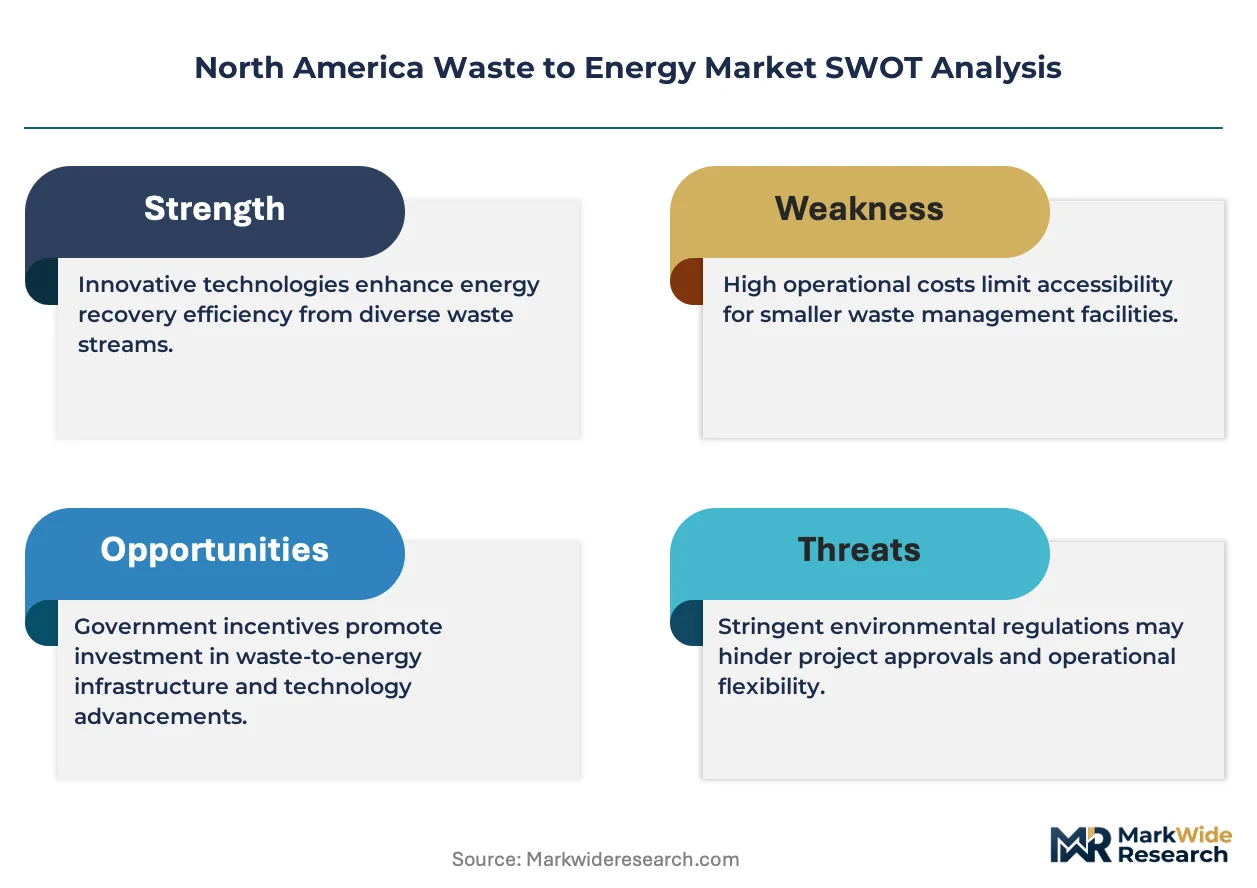
Landfill capacity constraints across the Northeast corridor are forcing municipalities toward thermal treatment infrastructure, while EPA Maximum Achievable Control Technology standards under the Clean Air Act drive capital deployment into flue gas scrubbing and continuous emissions monitoring systems.
Growth Catalysts
- Renewable Portfolio Standards:California, New York, and Massachusetts classify WTE output as Tier 1 renewable generation, creating certificate value streams that improve project underwriting.
- Landfill scarcity:Massachusetts, New Jersey, and upstate New York face exhaustion timelines under fifteen years, accelerating incineration capacity procurement.
- IRA production tax credits:The Inflation Reduction Act extends credits for waste-derived electricity, modifying developer return assumptions and debt sizing.
Market Restraints
- Natural gas price volatility:Henry Hub fluctuations compress spark spreads for baseload WTE power against combined-cycle gas turbines.
- Feedstock consistency requirements:Gasification systems demand homogeneous waste streams that municipal collection infrastructure struggles to deliver.
- Stack gas treatment capex:EPA mercury and dioxin limits require activated carbon injection and fabric filter upgrades that extend payback periods.
Strategic Opportunities
- Anaerobic digestion expansion:Agricultural and food waste diversion mandates in Vermont and Connecticut create feedstock pools for biogas upgrading facilities.
- Industrial symbiosis clusters:Co-location with cement kilns and district heating networks in the Great Lakes region enables heat offtake contracts.
- Carbon capture retrofits:Post-combustion amine systems on existing grate combustors qualify for 45Q credits, opening negative emissions revenue.
Industry Challenges
- Combustion engineering talent scarcity:Retiring boiler specialists and emissions control technicians outpace university training pipeline output.
- Interconnection queue delays:ISO-NE and NYISO backlogs extend energization timelines for new capacity, freezing capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Waste to Energy Market |
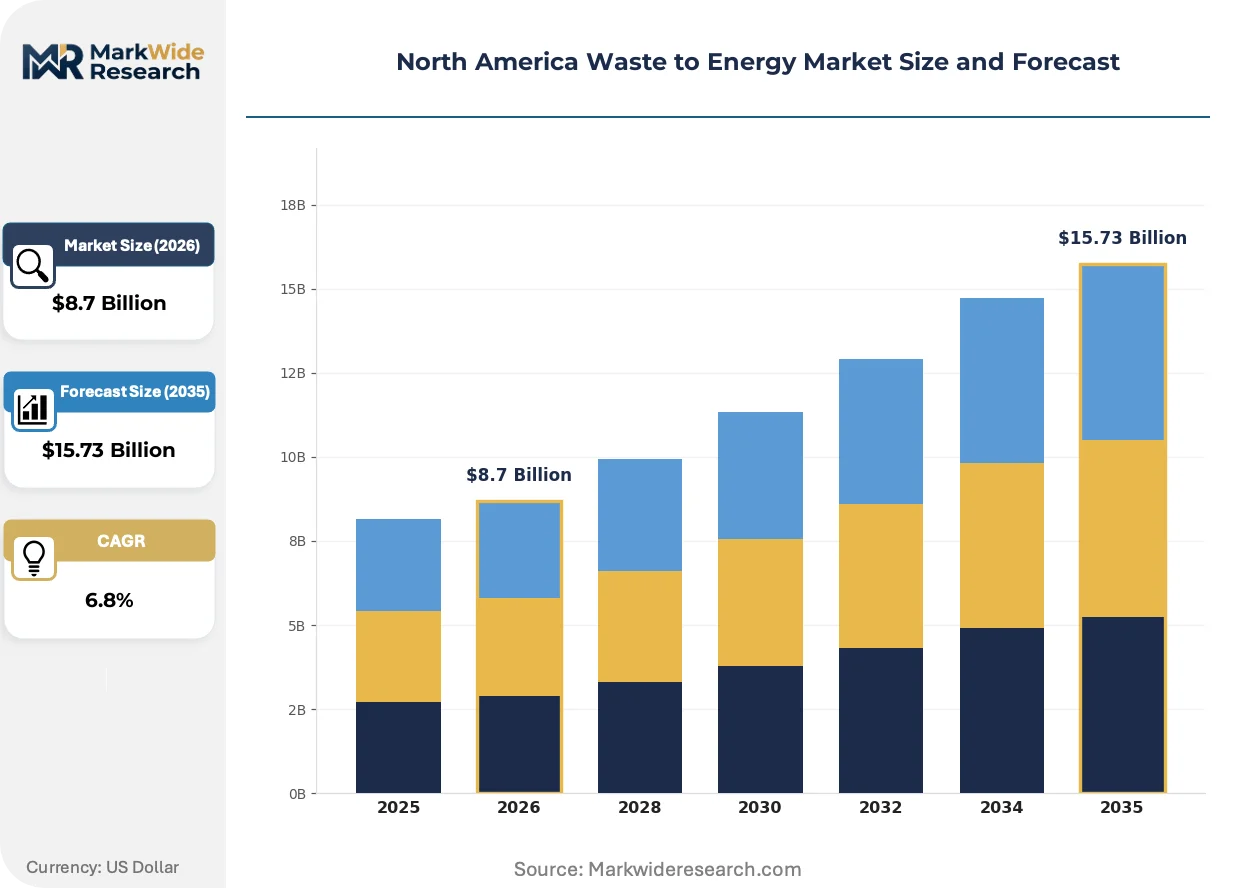
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Gasification, Anaerobic Digestion, Pyrolysis Feedstock: Municipal Solid Waste, Agricultural Residues, Industrial Waste, Biomass End User: Energy Utilities, Industrial Manufacturers, Government Entities, Waste Management Companies Application: Electricity Generation, Heat Production, Fuel Production, Waste Treatment |
| Companies Covered | Covanta Holding Corp, Waste Management Inc., Wheelabrator Technologies Inc, Suez SA, Veolia Environnement SA, Martin GmbH, Babcock & Wilcox Enterprises, Inc., Mitsubishi Heavy Industries Ltd, GFL Environmental Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Waste to Energy Market Evolving Landscape
Digital twin modeling of combustion grate performance is compressing outage schedules and optimizing auxiliary fuel consumption. Advanced sensor arrays and machine learning overlays are reshaping how operators manage thermal efficiency and regulatory compliance.
Plasma gasification is overtaking conventional grate combustion for hazardous and medical waste streams requiring destruction removal efficiencies above 99.99%. Healthcare systems in Texas and Florida are contracting dedicated capacity. The technology is overtaking legacy rotary kiln incinerators in premium feedstock segments where residue toxicity drives disposal economics.
The EPA's proposed Good Neighbor Rule on interstate ozone transport tightens NOx allocation budgets for stationary sources. WTE facilities in the Ozone Transport Region face incremental selective catalytic reduction investments. Maryland and Pennsylvania operators are pre-positioning ammonia slip monitoring to maintain compliance headroom.
Long-term tipping fee escalation clauses are replacing fixed-price waste supply agreements. Municipal solid waste departments in the Northeast corridor are accepting inflation-indexed structures that transfer commodity risk to ratepayers. This repricing is most visible in Massachusetts and New Jersey procurement documents issued since 2023.
North America Waste to Energy Market Segmentation
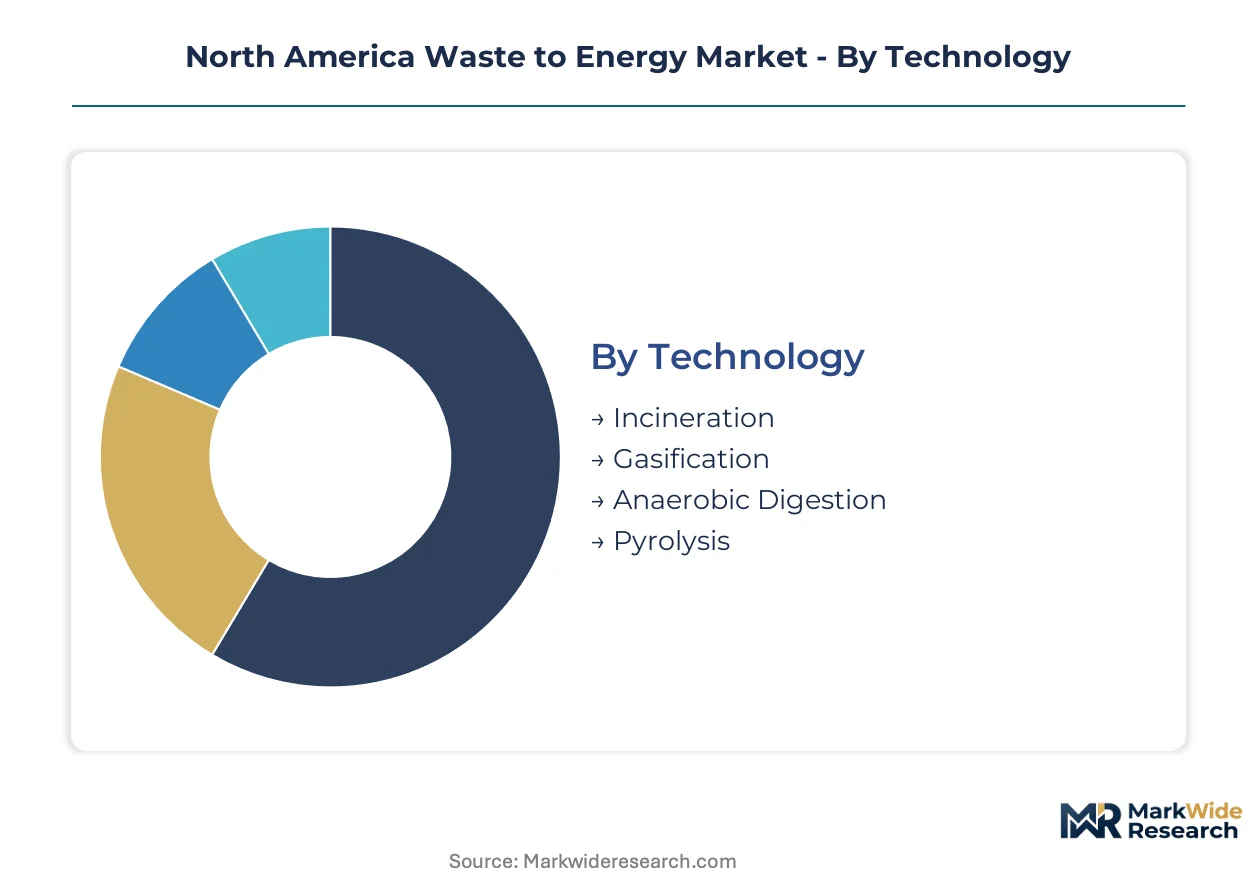
Technology choice dictates capital deployment timelines and regulatory compliance burdens across North American waste to energy infrastructure. Feedstock availability and end-user offtake structures further fragment procurement patterns and project finance terms.
Technology:
Capital intensity varies dramatically across thermal and biological conversion pathways, with grate combustion requiring the heaviest upfront civil works and emissions control investments.
- Incineration:Mass-burn grate systems operate at 850-1000°C with established flue gas treatment trains including fabric filters and selective catalytic reduction. Municipal utilities in Massachusetts and New Jersey anchor demand through long-term power purchase agreements that amortize construction costs over twenty-five year tenors.
- Anaerobic Digestion:Mesophilic and thermophilic biogas reactors process organic fractions at 35-55°C with lower thermal energy requirements than combustion routes. Vermont and Connecticut agricultural diversion mandates concentrate developer activity in dairy cluster regions where manure and food waste co-digestion improves biogas yields.
- Gasification:Partial oxidation at 700-1500°C in oxygen-starved environments produces syngas for power generation or chemical synthesis. Feedstock homogeneity requirements limit municipal deployment to industrial waste streams with consistent calorific values.
- Pyrolysis:Thermal decomposition in oxygen-absent conditions yields bio-oil, char, and syngas fractions. Tire and plastic waste processors in Texas deploy modular units for feedstock-specific recovery.
Incineration absorbs the bulk of installed capacity; anaerobic digestion is expanding most quickly.
Feedstock:
Collection infrastructure density and contamination rates determine which waste streams command viable tipping fees for energy recovery economics.
- Municipal Solid Waste:Mixed residential and commercial refuse with 8-12 MJ/kg calorific content forms the baseline feedstock for mass-burn facilities. Northeast corridor landfill scarcity tightens supply agreements with inflation-indexed pricing clauses.
- Industrial Waste:Manufacturing residues including paper sludge, packaging rejects, and process offcuts offer higher energy densities with lower moisture content. Great Lakes region pulp and paper mills co-locate combustors with production facilities.
- Agricultural Residues:Corn stover, wheat straw, and manure solids provide seasonal feedstock pools for rural digestion facilities. Upper Midwest grain belt logistics constrain year-round supply security.
- Biomass:Dedicated energy crops and forestry residues compete with pellet export markets for fiber supply. Pacific Northwest timber operations supply wood waste to co-generation installations.
Municipal solid waste dominates contracted volumes; industrial waste commands premium pricing for consistent quality.
End User:
Counterparty credit quality and offtake duration shape lender risk assessments and debt pricing for development projects.
- Energy Utilities:Investor-owned and municipal electric departments procure baseload capacity under renewable portfolio standard mandates. New York and California utilities value WTE for capacity factor reliability exceeding solar and wind intermittency.
- Waste Management Companies:Vertically integrated haulers secure feedstock supply through collection route density and tip floor control. Long-term service agreements bundle disposal with energy revenue streams.
- Industrial Manufacturers:Cement kilns, steel mills, and chemical plants purchase steam or syngas for process heat substitution. Ohio and Pennsylvania manufacturers seek thermal offtake to decarbonize Scope 1 emissions.
- Government Entities:Military installations and federal facilities procure dedicated waste destruction capacity under homeland security protocols. Department of Defense contracts specify destruction removal efficiency standards for classified material.
Energy utilities anchor the project finance market; waste management companies are consolidating vertical control over feedstock-to-energy chains.
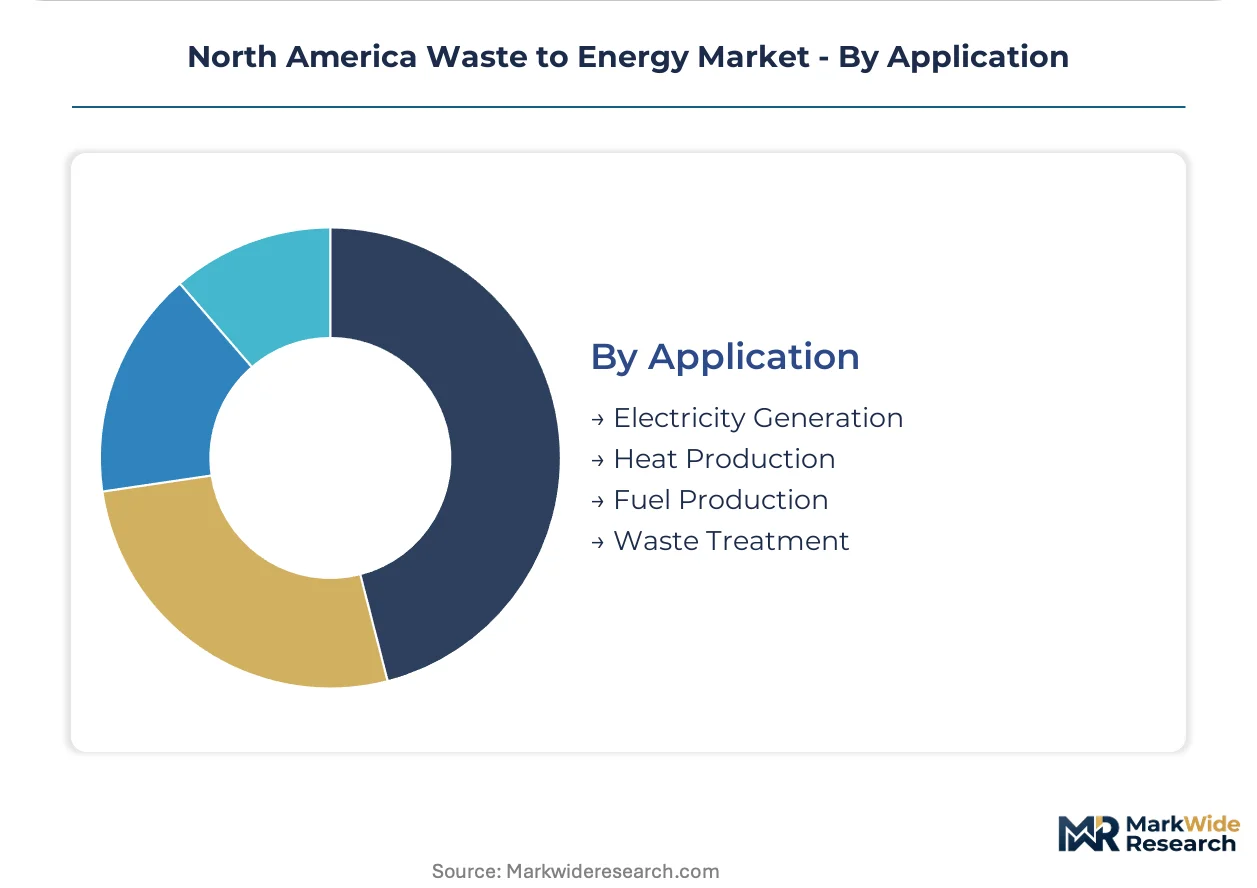
Application:
Revenue stack composition varies by whether facilities optimize for power sales, thermal offtake, or gate fee maximization.
- Electricity Generation:Steam turbine or reciprocating engine power blocks feed grid interconnection at distribution or transmission voltage levels. ISO-NE and NYISO capacity markets provide supplemental revenue beyond energy and renewable certificate sales.
- Waste Treatment:Volume reduction and residue stabilization drive procurement where landfill capacity constraints tighten disposal economics. Massachusetts municipalities prioritize tonnage diversion over energy yield optimization.
- Heat Production:District heating networks and industrial steam offtake contracts improve thermal efficiency by bypassing power cycle losses. Minneapolis-St. Paul district energy systems integrate WTE heat supply.
- Fuel Production:Biogas upgrading to pipeline-quality renewable natural gas or syngas catalysis to synthetic fuels targets transportation sector decarbonization. California LCFS credit values support biogas upgrading investments.
Electricity generation captures majority revenue share; fuel production is gaining policy support through low-carbon fuel standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration clusters in the Northeast corridor, where landfill scarcity intersects with aggressive renewable portfolio standards and EPA emission mandates. The United States dominates capacity deployment, while Canada and Mexico present divergent regulatory and infrastructure trajectories.
United States
Massachusetts, New York, and New Jersey municipalities face landfill exhaustion timelines under fifteen years, accelerating incineration procurement. EPA Maximum Achievable Control Technology standards under the Clean Air Act mandate activated carbon injection and fabric filter upgrades. The Greater Boston metro anchors the densest concentration of operational grate combustors, with Covanta Holding Corp facilities processing municipal solid waste under long-term tolling contracts.
Canada
Ontario and Quebec provinces prioritize anaerobic digestion for organic waste diversion under provincial landfill reduction targets. Environment and Climate Change Canada enforces stricter methane emission caps on waste facilities than federal US standards. The Toronto-Hamilton corridor hosts biogas upgrading infrastructure targeting renewable natural gas injection into Enbridge distribution networks.
Mexico
Mexico City Metro generates sufficient municipal solid waste volumes to support energy recovery economics, though collection infrastructure gaps limit feedstock quality. SEMARNAT environmental standards for waste combustors remain less stringent than EPA benchmarks, constraining technology transfer from US operators. The Bajío Region industrial corridor attracts pyrolysis investments for tire and plastic waste processing serving manufacturing supply chains.
North America Waste to Energy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated waste haulers controlling feedstock access while technology licensors capture engineering margins. The market exhibits tiered concentration: a dominant incumbent anchors incineration capacity, diversified environmental services conglomerates bundle collection with energy recovery, and specialized boiler fabricators supply emissions control systems. Strategic moves concentrate on long-term municipal service agreements and flue gas treatment retrofits.
Within the integrated environmental services tier, Covanta Holding Corp and Waste Management Inc. occupy positions that exemplify divergent approaches to feedstock security—tolling contracts versus collection route density. Babcock & Wilcox Enterprises, Inc. anchors the technology supply segment, representing engineering-intensive positioning in utility-scale boiler and emissions control installations.
| Leading Market Players |
|---|
| Covanta Holding Corp |
| Waste Management Inc. |
| Wheelabrator Technologies Inc |
| Suez SA |
| Veolia Environnement SA |
| Martin GmbH |
| Babcock & Wilcox Enterprises, Inc. |
| Mitsubishi Heavy Industries Ltd |
| GFL Environmental Inc. |
| Others |
Value Network & Pricing Analysis
Northeast corridor landfill exhaustion timelines under fifteen years are forcing municipalities toward inflation-indexed tipping fee structures that transfer commodity risk to ratepayers and reshape contractor procurement economics. This demand-side repricing pressure cascades backward through EPC contracting, feedstock logistics, and emissions control equipment sourcing.
Pricing Analysis
Volume contracts dominate municipal procurement while margin capture concentrates in technology licensing and flue gas retrofit services. Price differentiation rests on EPA MACT compliance tier and renewable certificate eligibility under state RPS frameworks. Cost compression in baseload power sales is intensifying because Henry Hub volatility compresses spark spreads against combined-cycle gas turbines. Municipal utilities exhibit highest price sensitivity due to ratepayer oversight, while Department of Defense contracts show lowest sensitivity given homeland security protocols.
Supply Chain Analysis
Domestic-content preferences in IRA-funded infrastructure are reshaping sourcing patterns for boiler fabrication and emissions control systems toward US-based manufacturing. Supply concentration centers on Germany, Japan, and the United States for grate combustion technology and selective catalytic reduction catalysts. Raw material dependencies include specialty steels for boiler pressure vessels, activated carbon for mercury capture, and ammonia reagents for NOx reduction. Single-source vulnerability sits with European catalyst suppliers facing energy cost volatility. Distribution runs through EPC contractors with established utility relationships and municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America waste to energy market is consolidating into a vertical-integration race where feedstock security and emissions technology control determine competitive position. Players are pursuing upstream collection density and downstream power marketing capabilities as the decisive levers.
For Market Incumbents: Anticipate feedstock competition from anaerobic digestion developers by securing long-term municipal service agreements with inflation-indexed tipping fee escalators. Deepen backward integration into collection route density through selective tuck-in acquisitions of regional haulers. Prioritize selective catalytic reduction and carbon capture retrofit capabilities to maintain EPA compliance headroom against tightening NOx allocations. For New Entrants and Emerging Players: Launch via anaerobic digestion platforms targeting Vermont and Connecticut agricultural diversion mandates where feedstock aggregation infrastructure remains underdeveloped. Concentrate on dairy cluster regions with manure and food waste co-digestion economics. Pursue biogas upgrading to renewable natural gas with California LCFS credit monetization as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors technology licensors with proprietary emissions control IP and established utility reference installations. Long-term viability rests on regulatory tailwinds for waste diversion and decarbonization credits rather than pure power market economics. Monitor EPA Good Neighbor Rule implementation and state RPS tier reclassifications as the critical inflection signals for asset valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Security Agreements | Long-term municipal tolling contracts with Covanta and Waste Management anchor project finance. |
| Emissions Control Retrofit Programs | EPA MACT upgrades to activated carbon injection systems extend facility operating licenses. |
| Anaerobic Digestion Capacity Buildout | Vermont and Connecticut organic diversion mandates create biogas upgrading investment pools. |
| Carbon Capture Integration | Post-combustion amine systems on grate combustors qualify for 45Q credit revenue streams. |
| Utility-Scale Power Purchase Agreements | ISO-NE and NYISO capacity market participation supplements energy and REC sales. |
Research Methodology
Independent corroboration across EPA enforcement databases, state renewable portfolio standard filings, and municipal procurement records underwrites the qualitative findings in this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and feedstock logistics specialists were cross-referenced against secondary validation from EIA power generation statistics, FERC interconnection queue filings, and IEA waste management reports. Bottom-up project pipeline tracking and top-down capacity factor modeling were reconciled through iterative triangulation.
Comparable-period anchoring to historical EPA compliance cost curves and state RPS adoption timelines established the forecast window boundaries. The analytical framework segments by technology pathway, feedstock category, end-user counterparty type, and application revenue stack across the projection horizon. CAGRs were derived from facility-level unit economics modeling incorporating tipping fee trajectories, natural gas price scenarios, and renewable certificate value projections. Forecast inputs include interconnection queue velocity, MACT retrofit capital schedules, and organic waste diversion mandate implementation pace.
Regulatory reclassification of WTE under state RPS tiers, feedstock contamination rate volatility, and carbon credit market liquidity are the dominant revision risks to the forecast envelope. Technological disruption from plasma gasification scale-up or policy shifts in federal production tax credit eligibility could materially alter deployment trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Energy Recovery Technologies Market