
 China Waste to Energy Market | 2026-2036
China Waste to Energy Market Size, Share, and Industry Trends Forecast 2026-2036
China Waste to Energy Market Analysis
The divergence between premium high-efficiency incineration plants and commodity-grade waste processing facilities is realigning competitive dynamics across China's waste-to-energy sector. Zhejiang Weiming Environment Protection leverages its coastal geographic dominance to sustain captive municipal feedstock contracts. China Everbright Environment Group anchors its position through vertical integration into equipment manufacturing and project operations.
China waste to energy encompasses thermal and biological processes that convert municipal solid waste, industrial refuse, and agricultural residues into electricity, heat, or synthetic fuel through controlled combustion, anaerobic digestion, or gasification at temperatures typically exceeding 850°C for incineration pathways. Incineration technology occupies the largest installed base due to proven scale and grid integration maturity, while gasification represents the fastest-growing segment as developers pursue higher thermal efficiency and lower residual waste outputs. Biological treatment holds concentrated margin pools in agricultural residue applications where feedstock costs remain minimal.
China's Ministry of Ecology and Environment enforces emission standards that mandate particulate matter and dioxin controls, while GB standards codify operational parameters for thermal conversion facilities. The National Development and Reform Commission shapes demand through tariff mechanisms that incentivize grid-connected waste power generation. Stakeholders must monitor how evolving carbon accounting rules and provincial waste classification mandates reshape project economics and technology selection across municipal procurement cycles.
Market Dynamics
The divergence between premium high-efficiency incineration plants and commodity-grade waste processing facilities is realigning competitive dynamics across China's waste-to-energy sector. Zhejiang Weiming Environment Protection leverages its coastal geographic dominance to sustain captive municipal feedstock contracts. China Everbright Environment Group anchors its position through backward integration into equipment manufacturing and project operations.
Growth Catalysts
- Dual Carbon Goals:China's MEE oversight accelerates technology upgrades toward higher-efficiency thermal conversion systems. Municipalities in eastern coastal provinces expand procurement of incineration-based electricity generation.
- Urban Waste Volumes:Climbing municipal solid waste generation in the Yangtze River Delta cluster spanning Shanghai, Jiangsu, and Zhejiang provinces creates sustained feedstock demand.
- Grid Integration Maturity:Proven scale and grid connection infrastructure for incineration technology reduces deployment risk for new project developers.
Market Restraints
- Feedstock Cost Volatility:Agricultural residue price fluctuations compress margin pools for biological treatment facilities. Seasonal availability variations disrupt continuous operations.
- Emission Control Burden:GB standards mandating particulate matter and dioxin controls at thermal conversion facilities impose capital-intensive scrubber and monitoring system requirements.
- Residual Ash Disposal:Bottom ash and fly ash handling regulations tighten landfill access. Hazardous classification of certain ash streams raises disposal costs substantially.
Strategic Opportunities
- Gasification Technology Convergence:Integration of plasma arc gasification with syngas cleanup systems enables higher thermal efficiency and lower residual waste outputs than conventional incineration.
- Anaerobic Digestion Expansion:Agricultural residue applications in interior provinces offer concentrated margin pools where feedstock costs remain minimal. Rural biogas-to-power projects unlock underserved markets.
- Carbon Accounting Rules:Evolving provincial carbon credit mechanisms reshape project economics for waste-to-energy developers. Early certification positioning captures premium tariff structures.
Industry Challenges
- Operational Expertise Gap:Advanced gasification and pyrolysis systems require specialized combustion engineering talent. Training pipelines for high-temperature process control remain underdeveloped.
- Legacy Incinerator Retrofit Complexity:Aging grate combustion facilities face efficiency and emission compliance gaps. Upgrade timelines compress against municipal contract renewal cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Waste to Energy Market |
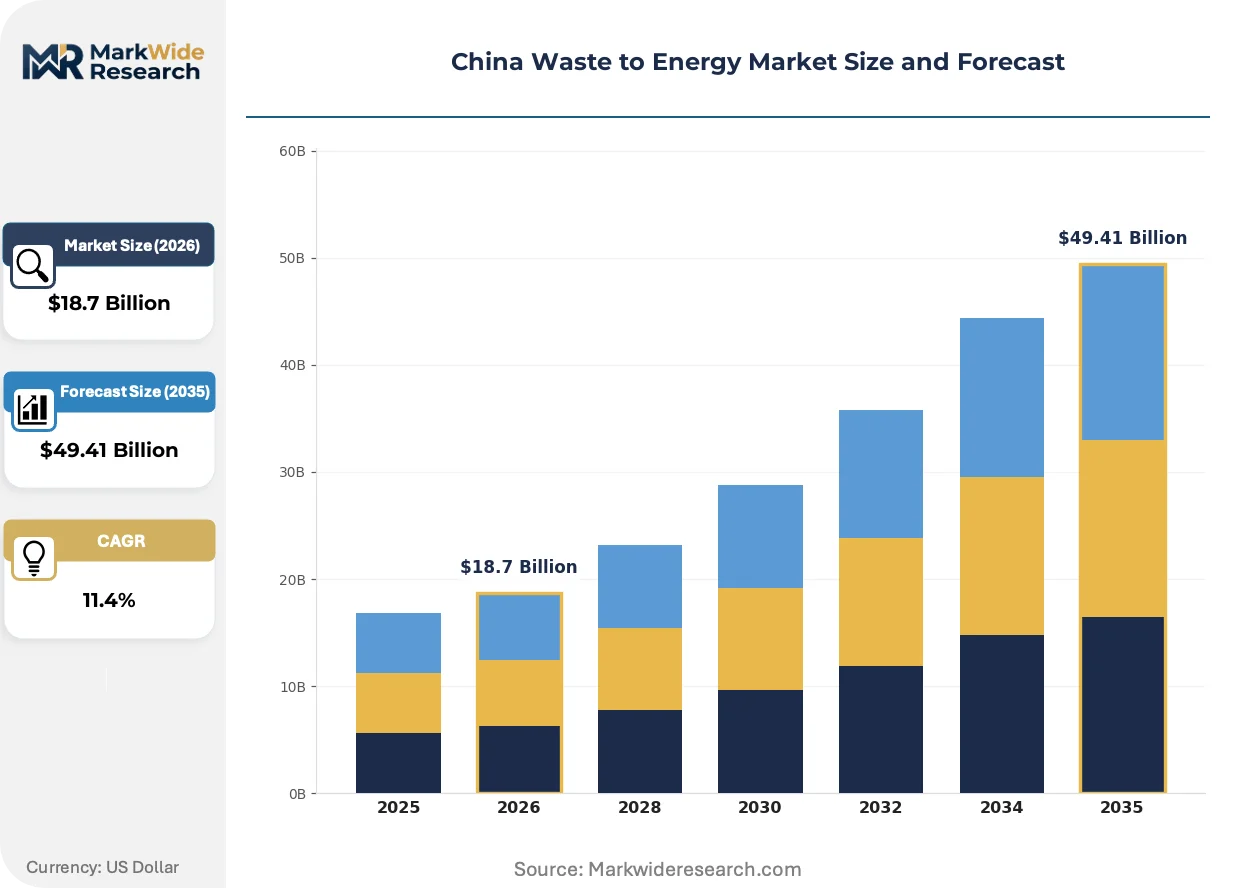
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal Conversion, Biological Treatment, Gasification, Incineration Feedstock Type: Municipal Solid Waste, Industrial Waste, Agricultural Residues, Biomass Application: Electricity Generation, Heat Production, Fuel Production, Landfill Diversion End User: Municipalities, Energy Corporations, Industrial Facilities, Waste Management Companies |
| Companies Covered | Zhejiang Weiming Environment Protection, China Tianying, China Everbright Environment Group, Beijing Enterprises Environment Group, Beijing Capital Eco-Environment Protection Group, Zheneng Jinjiang Environment Holding, Dynagreen Environmental Protection, Shanghai Environment Group, Grandblue Environment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Waste to Energy Market Emerging Trajectories
Technology trajectories in China's waste-to-energy sector center on thermal efficiency maximization and residual waste minimization. Developers pursue higher conversion rates through advanced gasification pathways.
Plasma arc gasification is electrifying waste-to-energy project economics by converting municipal solid waste into synthetic gas at temperatures exceeding 1,500°C. Developers in the Yangtze River Delta cluster adopt this technology for new-build facilities. The process is electrifying competitive positioning by enabling higher electrical output per ton of waste processed while eliminating bottom ash disposal requirements.
China's Ministry of Ecology and Environment enforces progressively stringent GB emission standards for thermal conversion facilities. Particulate matter limits and dioxin monitoring requirements now mandate continuous emissions monitoring systems. Municipal procurement cycles increasingly specify ultra-low emission technology packages as mandatory bid qualifications.
Municipal buyers are consolidating waste service contracts toward integrated operation-and-maintenance arrangements. Single-source accountability for feedstock collection, energy recovery, and residual disposal displaces fragmented multi-vendor structures. Shanghai and Zhejiang municipalities lead this consolidation pattern through 15-25 year concession agreements.
China Waste to Energy Market Segmentation
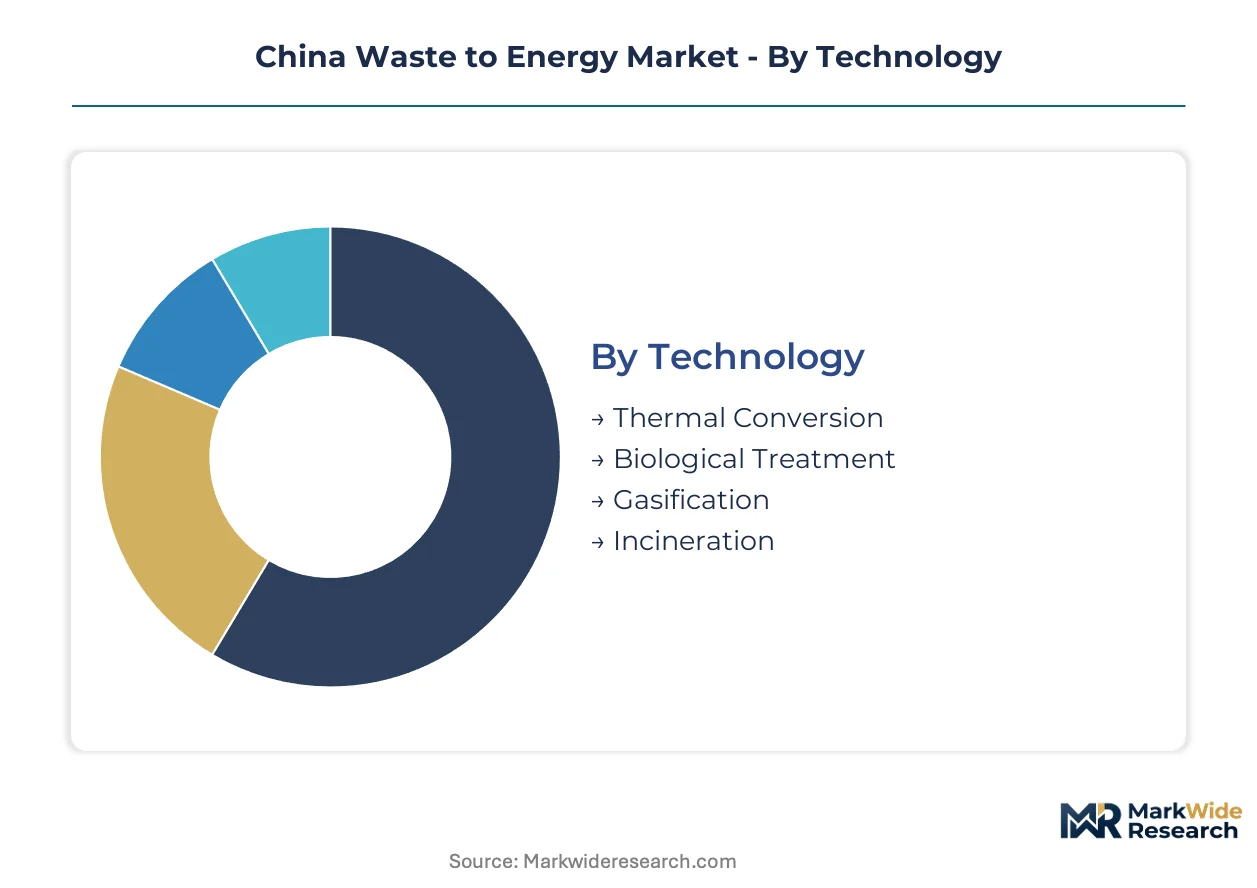
Technology selection determines capital intensity and regulatory compliance pathways for waste-to-energy developers. Feedstock characteristics and end-use applications further stratify project economics across China's municipal procurement landscape.
Technology:
Facility upgrade cycles and replacement timelines are accelerating as older grate combustion systems face emission standard tightening under MEE oversight.
- Incineration:Grate combustion systems operating at 850°C+ dominate China's installed base. Municipalities in the Yangtze River Delta cluster specify incineration for grid-connected power projects due to proven operational track records and established ash handling protocols.
- Gasification:Partial oxidation at 1,500°C+ converts waste into syngas for cleaner combustion. Developers in Zhejiang and Jiangsu provinces are adopting plasma arc configurations to eliminate bottom ash disposal and capture premium tariff structures under evolving carbon accounting rules.
- Thermal Conversion:Encompasses pyrolysis and conventional combustion pathways for industrial refuse applications. Chemical sector facilities in coastal provinces deploy these systems for captive energy recovery from process waste streams.
- Biological Treatment:Anaerobic digestion processes organic fractions at mesophilic temperatures. Agricultural residue applications in interior provinces exploit minimal feedstock costs for biogas-to-power generation.
Volume placements concentrate in Incineration; the faster expansion belongs to Gasification.
Feedstock Type:
Cost tier differentiation separates high-volume municipal contracts from specialized industrial waste streams with premium tipping fees.
- Municipal Solid Waste:Mixed urban refuse with 3,500-4,500 kcal/kg calorific value forms the baseline feedstock. Shanghai and Jiangsu municipalities lock in 15-25 year supply contracts with guaranteed minimum tonnage clauses.
- Industrial Waste:Manufacturing residues and hazardous-classified streams command higher processing fees. Chemical and textile clusters in Zhejiang province generate concentrated demand for specialized thermal treatment capacity.
- Agricultural Residues:Crop straw and animal manure feed rural biogas digesters. Seasonal availability constraints limit continuous operation models outside integrated agricultural processing zones.
- Biomass:Woody and herbaceous materials supplement thermal conversion blends. Forestry processing centers in Fujian and Guangdong provinces supply pelletized feedstock for co-firing arrangements.
Contract security favors Municipal Solid Waste; margin expansion is steepest in Industrial Waste.
Application:
Customer procurement priorities are shifting from pure electricity output toward integrated residual management services.
- Electricity Generation:Grid-connected power sales dominate revenue structures. National Development and Reform Commission tariff mechanisms guarantee feed-in premiums for waste power projects meeting GB emission standards.
- Landfill Diversion:Volume reduction and inert residue stabilization address municipal waste crisis pressures. Eastern coastal provinces mandate diversion rates exceeding 90% for new concession agreements.
- Heat Production:District heating and industrial process steam applications improve thermal efficiency. Northern municipalities integrate waste heat into combined heat and power configurations.
- Fuel Production:Syngas and biogas upgrading for vehicle fuel or chemical feedstock remains nascent. Pilot projects in Jiangsu province test RNG injection into natural gas distribution networks.
Revenue concentration sits with Electricity Generation; policy tailwinds are strongest for Landfill Diversion.
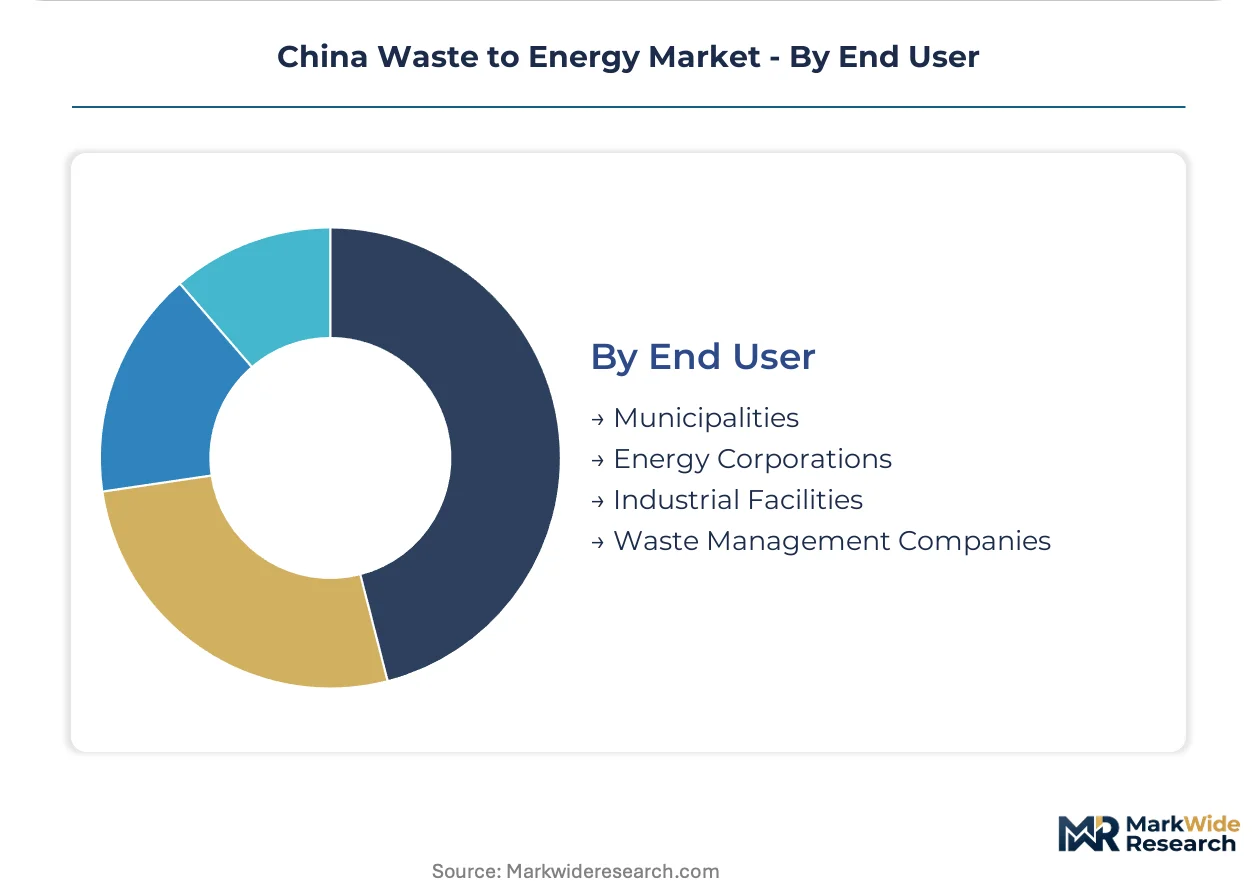
End User:
Customer maturity and technical capability determine project structuring between turnkey concessions and self-operated assets.
- Municipalities:Local governments procure integrated waste-to-energy services through long-term concessions. Urban districts in Shanghai and Hangzhou bundle collection, treatment, and residual disposal into single-source accountability structures.
- Energy Corporations:State-owned power groups diversify generation portfolios with waste fuel sources. Grid integration expertise reduces offtake risk for utility-scale project developers.
- Industrial Facilities:Manufacturing campuses deploy captive treatment for process waste and energy recovery. Petrochemical complexes in Ningbo and Dalian operate integrated thermal oxidation systems.
- Waste Management Companies:Specialized operators extend vertically into energy recovery from collection bases. Regional players leverage feedstock control to secure project equity positions.
Contract flow concentrates through Municipalities; operational sophistication is advancing fastest among Energy Corporations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta cluster anchors China's waste-to-energy deployment, with Shanghai, Jiangsu, and Zhejiang provinces driving procurement of high-efficiency thermal conversion systems under MEE oversight.
Shanghai Municipality
Shanghai's municipal government bundles waste collection, incineration, and residual disposal into 15-25 year concession agreements. The city's dual carbon commitments under MEE supervision mandate ultra-low emission technology packages for all new projects. Pudong and Minhang districts concentrate grid-connected power generation capacity with district heating integration.
Jiangsu Province
Jiangsu's manufacturing corridors generate substantial industrial waste streams requiring specialized thermal treatment. The province's National Development and Reform Commission tariff mechanisms guarantee feed-in premiums for compliant waste power projects. Nanjing and Suzhou municipalities lead procurement of plasma arc gasification systems to eliminate bottom ash disposal.
Zhejiang Province
Zhejiang's coastal cities leverage captive municipal feedstock contracts to sustain continuous operations. GB standards enforcement by provincial environmental authorities drives retrofit timelines for aging grate combustion facilities. Hangzhou and Ningbo anchor the province's integrated operation-and-maintenance contract consolidation.
Beijing-Tianjin-Hebei Region
The capital region's waste classification mandates reshape feedstock composition for thermal conversion facilities. MEE emission standards enforcement mandates continuous emissions monitoring systems across all operational plants. Beijing's municipal procurement specifies higher-efficiency thermal conversion systems to meet residual diversion targets exceeding 90%.
Guangdong Province
Guangdong's Pearl River Delta manufacturing base generates concentrated demand for industrial waste processing capacity. Provincial environmental regulators align project approvals with carbon accounting rules under evolving national frameworks. Shenzhen and Guangzhou municipalities test RNG injection pilot projects for biogas upgrading applications.
China Waste to Energy Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology efficiency tiers and concession contract durations. The sector exhibits consolidated leadership among state-affiliated environmental groups with multi-provincial project portfolios. Three archetypes dominate: vertically integrated equipment-to-operations specialists, geographic cluster specialists with captive municipal relationships, and diversified state-owned energy groups extending into waste fuel. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with developers securing long-term feedstock agreements before technology deployment.
Among coastal province specialists, Zhejiang Weiming Environment Protection and Shanghai Environment Group exemplify geographic cluster concentration with sustained municipal feedstock control. China Everbright Environment Group occupies a position representing backward integration into equipment manufacturing and project operations across multiple provincial markets. Beijing Enterprises Environment Group anchors the state-affiliated tier with diversified environmental infrastructure holdings.
| Leading Market Players |
|---|
| Zhejiang Weiming Environment Protection |
| China Tianying |
| China Everbright Environment Group |
| Beijing Enterprises Environment Group |
| Beijing Capital Eco-Environment Protection Group |
| Zheneng Jinjiang Environment Holding |
| Dynagreen Environmental Protection |
| Shanghai Environment Group |
| Grandblue Environment |
| Others |
Supply Flow & Price Mechanics
Municipal procurement consolidation toward 15-25 year integrated concession agreements is compressing vendor margins while demanding higher-efficiency technology packages from equipment suppliers. This buyer-side concentration forces developers to absorb upfront capital costs for ultra-low emission systems mandated by MEE oversight, reshaping how project economics flow through the value chain.
Pricing Analysis
Throughput-linked tariff structures anchored to National Development and Reform Commission feed-in premiums dominate revenue models for grid-connected facilities. Price differentiation rests on emission performance tier and grid integration reliability, with ultra-low emission certification commanding premium rates over standard GB compliance. Cost compression in commodity-grade grate combustion systems is intensifying as municipal buyers consolidate toward single-source operators. Municipalities in the Yangtze River Delta cluster show lowest price sensitivity due to dual carbon commitment pressures, while interior provinces prioritize capital efficiency over performance tier.
Supply Chain Analysis
Residual ash handling and fly ash detoxification flows create reverse-logistics complexity that elevates operational costs beyond initial equipment procurement. Equipment manufacturing concentrates in China, Germany, and Japan, with grate combustion systems drawing from domestic foundry capacity while plasma arc components rest on specialized ceramic and electrode imports. Supply chain risk centers on single-source vulnerability for high-temperature alloy components used in gasification reactor vessels. Distribution runs through municipal concession bidding platforms that bundle EPC contracts with long-term O&M arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's waste-to-energy sector is navigating a technology-transition phase as plasma arc gasification displaces legacy grate combustion systems. Municipal procurement specifications now mandate emission performance that legacy infrastructure cannot achieve without prohibitive retrofit investment.
For Market Incumbents: Anticipate accelerated concession renewal cycles that favor operators with demonstrated ultra-low emission track records. Secure feedstock contract extensions in coastal provinces before municipal buyers consolidate procurement. Backward integration into specialized combustion engineering talent pipelines addresses the operational expertise gap threatening legacy facility competitiveness.
For New Entrants and Emerging Players: The pricing gap between premium plasma arc installations and economy-grade grate retrofits creates entry space for mid-tier gasification technology providers. Agricultural residue applications in interior provinces offer the most penetrable segment given minimal incumbent concentration and seasonal feedstock availability constraints. Target rural biogas-to-power projects through provincial carbon credit certification positioning.
For Investors and Strategic Acquirers: Re-rating potential sits with equipment-to-operations specialists given evolving MEE emission standard enforcement as the catalyst for technology replacement demand. Long-term viability favors developers with captive municipal relationships spanning multiple provincial markets. Monitor provincial waste classification mandate rollout timelines as the inflection indicator for feedstock composition shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Arc Gasification Deployment | Enables MEE-compliant ultra-low emission performance while eliminating bottom ash disposal liability. |
| Backward Integration into Equipment Manufacturing | Captures margin pools from combustion system procurement cycles across provincial concession renewals. |
| Long-term Municipal Concession Agreements | Locks in 15-25 year feedstock supply security against competitive displacement in Yangtze River Delta cluster. |
| Carbon Credit Certification Positioning | Captures premium NDRC tariff structures under evolving provincial carbon accounting frameworks. |
| Agricultural Residue Supply Chain Development | Opens rural biogas-to-power markets with minimal feedstock cost exposure in interior provinces. |
Methodological Framework
Multi-period observation of municipal procurement cycles, concession award patterns, and MEE enforcement timelines anchored the trend analysis, supplemented by interviews with project development executives, EPC contractors, municipal environmental bureau officials, and grid operators. Secondary validation drew from NDRC tariff filings, provincial environmental disclosure databases, GB standards documentation, and project finance transaction records. Bottom-up facility capacity aggregation and top-down provincial waste generation estimates were triangulated to establish market sizing.
Segment-weighting approaches modeled technology selection trajectories, feedstock type economics, application revenue structures, and end-user procurement maturity across the projection horizon. CAGRs were derived from facility deployment pipelines, replacement cycle acceleration under emission standard tightening, and municipal budget allocation patterns for environmental infrastructure. Forecast inputs incorporated provincial dual carbon commitment timelines and evolving carbon credit mechanism designs.
Inputs from municipal procurement disclosure platforms and provincial environmental bureaus were available through the study window; gaps in private concession contract terms and unannounced technology retrofit schedules introduce uncertainty bands around capacity expansion timelines. Forecasts reflect documented assumptions regarding MEE enforcement intensity and NDRC tariff stability. Practitioners should monitor provincial waste classification mandate implementation and carbon accounting rule finalization for early signals of feedstock and pricing structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
Canada Waste-To-Energy Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
ORC Waste Heat to Power Market