
 Austria Waste to Energy Market | 2026-2036
Austria Waste to Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Waste to Energy Market Outlook
Fragmentation among municipal buyers across Austria's nine provinces is recalibrating procurement patterns for WTE capacity. REMONDIS SE & Co. KG leverages its integrated collection-to-energy footprint across Upper Austria and Salzburg. EEW Energy from Waste GmbH anchors the market through large-scale incineration assets with high electrical efficiency rates. Veolia Environnement S.A. competes by bundling waste management contracts with long-term heat supply agreements to urban district heating networks.
Waste to energy denotes thermal and biological processes that convert non-recyclable waste streams into electricity, heat, or synthetic fuels through controlled combustion, gasification, or anaerobic decomposition at operating temperatures typically exceeding 850 degrees Celsius for incineration pathways. Incineration dominates installed capacity due to proven reliability and grid-scale output, while anaerobic digestion captures expanding organic waste volumes from Austria's agricultural sector. Gasification occupies a niche but growing position for industrial waste streams with higher calorific value, where margin pools favor specialized engineering contracts over commodity tipping fees.
The Federal Ministry of Climate Action, Environment, Energy, Mobility, Innovation and Technology enforces Austria's landfill ban on untreated municipal waste, while EMAS and ISO 14001 certifications shape operator eligibility for public tenders. The EU Emissions Trading System and national CO2 pricing mechanisms directly affect plant economics by penalizing fossil-derived waste fractions. Stakeholders must monitor feedstock composition shifts as separate collection mandates for biowaste and plastics alter calorific values and residue volumes entering thermal treatment lines.
Market Dynamics
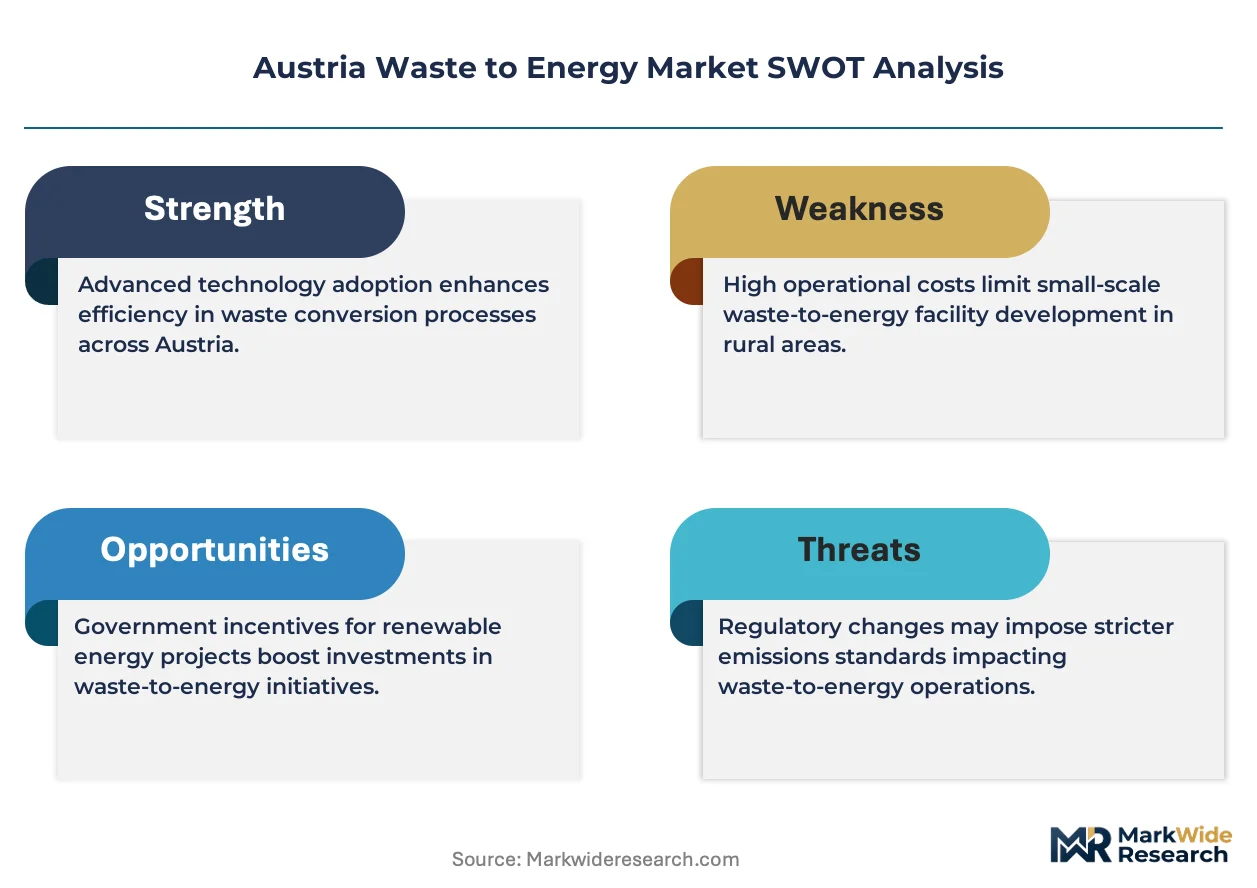
The EU Green Deal is compressing landfill diversion timelines across Austria's nine provinces, forcing municipal utilities to accelerate offtake negotiations for district heat from WTE facilities before 2030 compliance deadlines.
Growth Catalysts
- Lower Austria's district heating expansion:Municipal utilities in St. Pölten and surrounding districts are signing 15-year heat supply contracts with WTE operators, locking in baseload thermal capacity for residential networks.
- EU Emissions Trading System carbon pricing:The escalating CO2 cost curve is rendering landfill disposal economically unviable for untreated municipal waste streams, redirecting volumes toward thermal recovery pathways.
- Biowaste anaerobic digestion:Agricultural cooperatives in Burgenland are installing farm-scale digesters to capture methane from livestock manure, feeding upgraded biogas into regional gas grids.
Market Restraints
- Residual plastic contamination:Separate collection mandates for packaging waste are reducing calorific values in residual waste streams, forcing incineration plants to blend higher-energy industrial refuse to maintain furnace temperatures.
- Upper Austria supply concentration:REMONDIS controls integrated collection infrastructure across Salzburg and Linz corridors, creating bottleneck risk for independent WTE developers seeking feedstock security.
- Grid connection queuing:Vienna's metropolitan energy corridor faces 18-24 month delays for new CHP electrical interconnection approvals from the national regulator.
Strategic Opportunities
- Tyrol alpine tourism clusters:Ski resort municipalities in Kitzbühel and Innsbruck lack district heating density, creating openings for modular gasification units serving isolated thermal loads.
- Industrial symbiosis with cement kilns:Carinthia's Lafarge and Holcim plants are piloting refuse-derived fuel co-firing, diverting pre-processed waste fractions from dedicated incineration.
- Green hydrogen co-production:Steam electrolysis integration at Vienna Spittelau and other large CHP sites could qualify for EU Innovation Fund support under renewable hydrogen definitions.
Industry Challenges
- Flue gas treatment chemistry:Operators struggle to source qualified technicians for wet scrubber and selective catalytic reduction system maintenance as veteran plant engineers retire.
- Bottom ash utilization certification:EMAS and ISO 14001 compliance timelines for construction aggregate applications are extending 8-14 months due to regional environmental agency backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Waste to Energy Market |
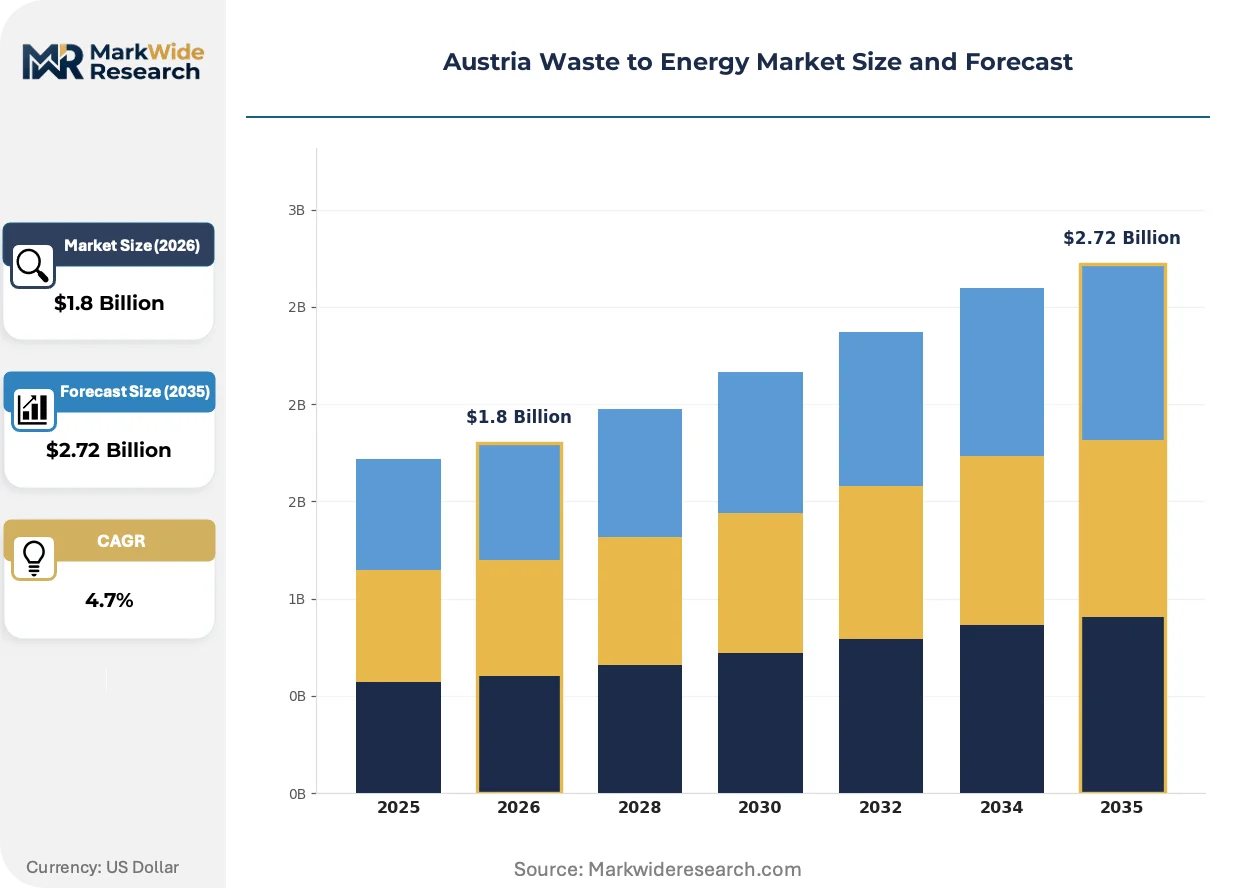
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Gasification, Anaerobic Digestion, Plasma Arc Waste Type: Municipal Solid Waste, Industrial Waste, Agricultural Residue, Biomass End User: Energy Producers, Waste Management Companies, Municipalities, Industrial Plants Application: Electricity Generation, Heat Production, Fuel Production, Waste Reduction |
| Companies Covered | REMONDIS SE & Co. KG, Dalkia Wastenergy, EEW Energy from Waste GmbH, Austrian Energy & Environment AG, Suez, Veolia Environnement S.A., Hitachi Zosen Corporation, BMH Technology Oy, MVV Energie AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Waste to Energy Market Strategic Shifts
Digital feedstock monitoring and advanced combustion control systems are reshaping how Austrian WTE plants optimize thermal efficiency and emissions performance in real-time operations.
Plasma gasification of industrial hazardous waste is rewriting the economics for specialized disposal streams in Vorarlberg's chemical corridor. BASF's Ludwigshafen supply chain partners are piloting mobile plasma units for chlorinated solvent destruction. The technology is compressing transport costs and landfill liability exposure for high-calorific toxic residues that conventional incineration struggles to process.
The EU Green Deal's landfill diversion mandates are tightening enforcement timelines through Austria's Federal Ministry of Climate Action. Industrial waste generators in Graz and Linz industrial zones face 2025 deadlines for pre-treatment certification. Chemical manufacturers are responding by consolidating waste streams through third-party pre-processing facilities to qualify for thermal recovery eligibility.
Municipal procurement departments are unbundling long-term waste management contracts from energy offtake agreements. Vienna's municipal utility Wien Energie now negotiates heat supply separately from collection services, enabling competitive tendering for each component. This bifurcation is most visible in Styria's regional capital Graz, where the municipal waste association split its 2024 contract renewal into three distinct service lots.
Austria Waste to Energy Market Segmentation
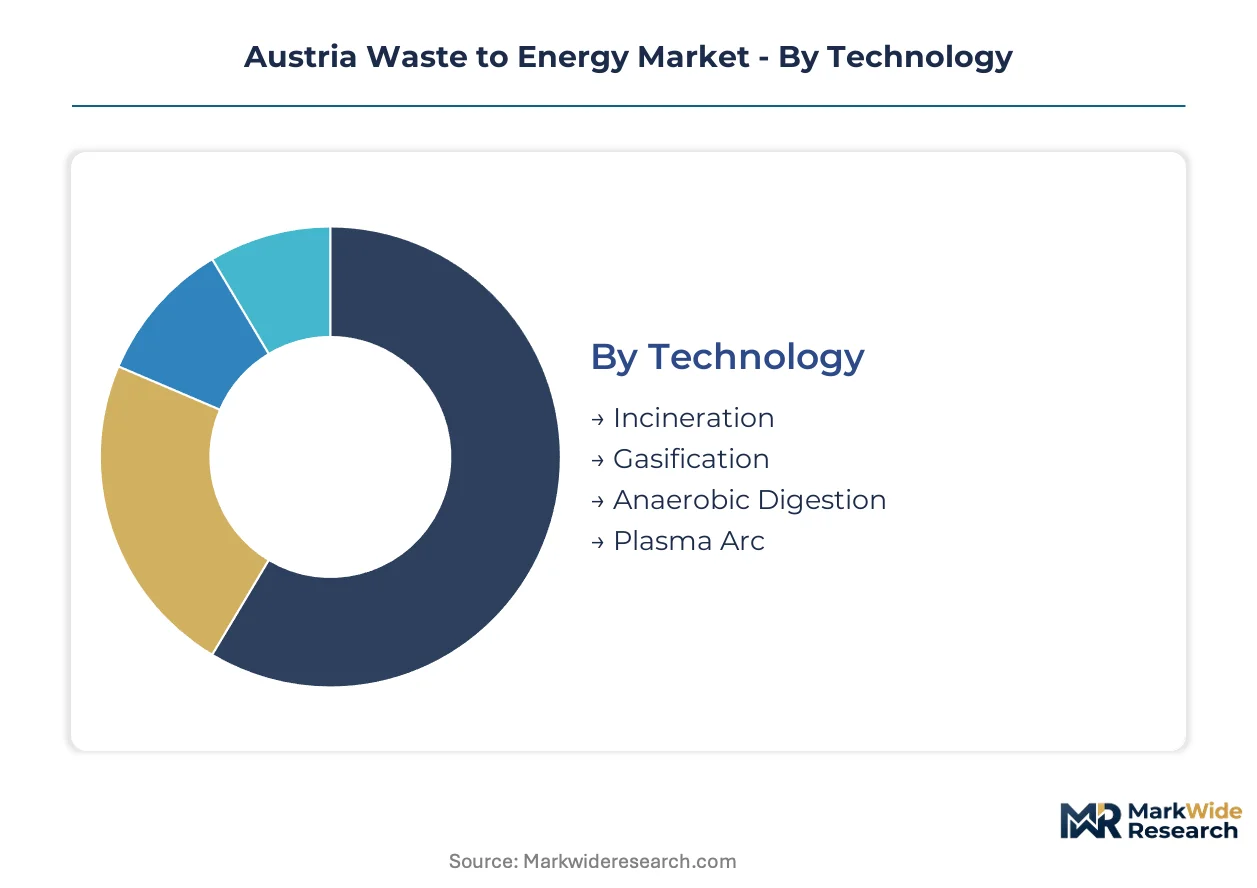
Technology choice in Austria's WTE sector dictates regulatory exposure, with incineration facing stricter EU ETS carbon pricing while anaerobic digestion qualifies for renewable energy certificates. Feedstock composition and end-use thermal demand shape plant economics across the country's provincial energy corridors.
Technology:
Certification burdens diverge sharply across thermal pathways. Incineration requires continuous emissions monitoring under EU Industrial Emissions Directive permits. Anaerobic digestion farms seek agricultural biogas registration with Austria's national renewable energy authority. Gasification pilots need technology-specific environmental impact assessments. Plasma arc installations face hazardous waste operator licensing from regional environmental agencies.
- Incineration:Mass-burn grate systems process 850°C+ combustion of residual municipal waste, producing steam for Vienna's district heating network and grid electricity. Wien Energie's Spittelau facility exemplifies combined heat and power integration with 60,000+ household thermal connections.
- Anaerobic Digestion:Mesophilic and thermophilic bacterial decomposition of organic substrates generates methane-rich biogas. Agricultural cooperatives in Burgenland deploy farm-scale digesters for livestock manure, feeding upgraded biomethane into regional gas distribution infrastructure.
- Gasification:Partial oxidation at 700-1,000°C converts carbonaceous feedstock into syngas for power generation or chemical synthesis. Industrial waste streams with elevated calorific value in Upper Austria's manufacturing zones suit this pathway.
- Plasma Arc:Electric arc discharge at 3,000-7,000°C vitrifies hazardous residues into inert slag. Vorarlberg's chemical corridor hosts mobile units for chlorinated solvent destruction serving BASF supply chain partners.
Incineration sits at the top of the volume ranking, with anaerobic digestion climbing the fastest.
Waste Type:
Cost tiers separate feedstock categories by collection infrastructure requirements and pre-treatment intensity. Municipal streams carry established tipping fee structures through inter-municipal associations. Industrial waste commands premium gate fees reflecting specialized handling. Agricultural residues leverage existing farm logistics networks.
- Municipal Solid Waste:Post-recycling residual streams from household collection systems, subject to Austria's landfill ban on untreated fractions. Lower Austria's district heating expansion drives offtake demand from St. Pölten municipal utilities.
- Industrial Waste:Manufacturing byproducts, packaging rejects, and process residues requiring pre-treatment certification. Linz and Graz industrial zones face 2025 compliance deadlines for thermal recovery eligibility under tightened EU Green Deal enforcement.
- Agricultural Residue:Crop straw, orchard prunings, and livestock bedding materials. Styria's wine-growing regions generate seasonal biomass volumes suitable for co-digestion or combustion blending.
- Biomass:Dedicated energy crops and forestry residues with standardized moisture and ash specifications. Alpine regions in Tyrol sustain localized heating applications through wood chip supply chains.
Municipal solid waste commands the largest throughput volumes, though industrial waste is gaining share fastest as manufacturing pre-treatment mandates tighten.
End User:
Customer type determines contract structure and investment horizon. Energy producers prioritize electrical efficiency and grid balancing revenues. Waste management companies seek feedstock security through vertical collection integration. Municipalities value long-term price predictability for district heating tariffs.
- Energy Producers:Utilities and independent power developers operating CHP assets under renewable energy support mechanisms. Wien Energie anchors procurement through 15-year heat supply agreements.
- Waste Management Companies:Integrated operators controlling collection-to-disposal value chains. REMONDIS leverages infrastructure dominance across Salzburg and Upper Austria corridors.
- Municipalities:Provincial and city governments procuring thermal capacity for district heating networks. Styria's regional capital Graz unbundled its 2024 contract renewal into distinct service lots.
- Industrial Plants:Manufacturing facilities with captive thermal demand and on-site waste streams. Carinthia's cement kilns pilot refuse-derived fuel co-firing with Lafarge and Holcim operations.
Waste management companies hold the deepest feedstock positions, while municipalities are expanding their direct offtake contracting fastest.
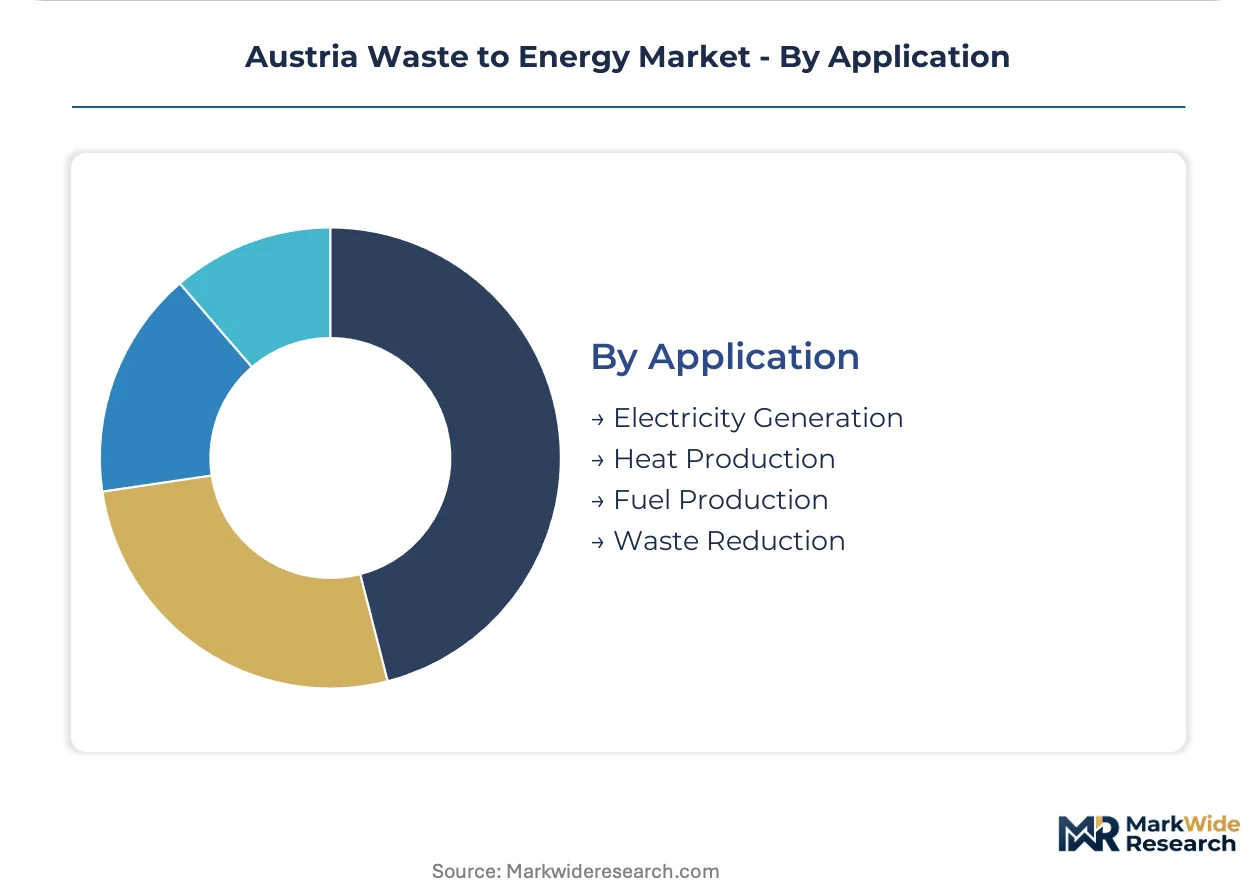
Application:
Margin profiles vary by energy output form. Electricity generation competes on wholesale market pricing and renewable certificate values. Heat production secures long-term baseload contracts with municipal utilities. Fuel production targets transport sector decarbonization mandates.
- Electricity Generation:Steam turbine or engine-driven power output feeding national transmission networks. Grid connection queuing in Vienna's metropolitan corridor extends 18-24 months for new CHP approvals.
- Heat Production:District heating supply to residential and commercial building networks. Lower Austria's municipal utilities lock in thermal baseload through expanded offtake agreements.
- Fuel Production:Syngas upgrading to biomethane or hydrogen for grid injection or transport use. Steam electrolysis integration at large CHP sites targets EU Innovation Fund qualification.
- Waste Reduction:Volume minimization and hazardous material destruction as primary service. Plasma arc vitrification eliminates landfill liability for toxic industrial residues.
Heat production leads installed capacity, with fuel production showing the steepest expansion trajectory as hydrogen co-production pilots advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's waste-to-energy infrastructure outpaces Austria in installed capacity per capita, while Switzerland's alpine constraints have driven earlier adoption of modular gasification for isolated thermal loads.
Lower Austria
Municipal utilities in St. Pölten and surrounding districts are locking in 15-year heat supply contracts with WTE operators. The Federal Ministry of Climate Action enforces landfill diversion mandates through tightened EU Green Deal timelines. District heating density in the Vienna metropolitan energy corridor supports combined heat and power integration at scale.
Styria
The regional capital Graz unbundled its 2024 waste management contract renewal into three distinct service lots. Agricultural cooperatives deploy farm-scale digesters to capture methane from livestock manure. Wine-growing regions generate seasonal biomass volumes suitable for co-digestion or combustion blending.
Upper Austria
Integrated collection infrastructure across Salzburg and Linz corridors creates feedstock concentration for large-scale incineration assets. Industrial waste generators in Linz face 2025 pre-treatment certification deadlines. Manufacturing zones generate elevated-calorific refuse streams suited to gasification pathways.
Vorarlberg
Chemical corridor operators pilot mobile plasma units for chlorinated solvent destruction serving supply chain partners. Regional environmental agencies administer hazardous waste operator licensing for high-temperature vitrification installations. Alpine topography limits district heating network expansion, favoring distributed thermal solutions.
Tyrol
Ski resort municipalities in Kitzbühel and Innsbruck lack district heating density for conventional CHP economics. Modular gasification units target isolated thermal loads from alpine tourism clusters. Seasonal occupancy patterns drive demand for flexible, small-scale waste processing capacity.
Austria Waste to Energy Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Austria's provincial energy corridors. The market structure shows moderate concentration, with integrated waste management groups controlling collection-to-energy value chains alongside independent power developers operating captive thermal assets. Three archetypes dominate: vertically integrated waste utilities, specialized energy-from-waste engineering firms, and municipal utility partnerships. Competitive moves center on feedstock security through collection infrastructure acquisition and long-term heat supply contracting with district heating networks.
Among Germany-based operators, REMONDIS SE & Co. KG and EEW Energy from Waste GmbH exemplify contrasting strategic positions—one representing integrated collection-to-energy control, the other anchoring large-scale incineration with high electrical efficiency. Veolia Environnement S.A. sits within the diversified environmental services tier, bundling waste management contracts with thermal offtake agreements. These three occupy distinct competitive spaces while competing for municipal procurement mandates across Austria's nine provinces.
| Leading Market Players |
|---|
| REMONDIS SE & Co. KG |
| Dalkia Wastenergy |
| EEW Energy from Waste GmbH |
| Austrian Energy & Environment AG |
| Suez |
| Veolia Environnement S.A. |
| Hitachi Zosen Corporation |
| BMH Technology Oy |
| MVV Energie AG |
| Others |
Value Chain & Pricing Dynamics
Qualified flue gas treatment technicians in Upper Austria and Styria command wage premiums that compress margin spreads between premium-certified and standard-tier WTE operations. Labor-cost differentials across Austria's nine provinces widen pricing-tier spreads as EMAS and ISO 14001 certification requirements intensify.
Pricing Analysis
Capacity additions in Lower Austria are reshaping price floors for district heat contracts as municipal utilities consolidate procurement. Three-tier pricing structure across premium-certified, standard-compliant, and economy-tier operators reflects diverging EMAS certification levels and after-sales service bundling. Cost compression in economy-tier incineration is intensifying because residual plastic contamination reduces calorific values and forces expensive industrial refuse blending. Municipal utilities in Vienna's metropolitan corridor show least price sensitivity due to long-term baseload requirements, while alpine tourism municipalities in Tyrol exhibit highest sensitivity to upfront capital costs.
Supply Chain Analysis
EMAS and ISO 14001 certification gating determines operator eligibility for public tenders and shapes feedstock access across Austria's provincial corridors. Equipment manufacturing draws from Germany, Switzerland, and the Netherlands for combustion grates, emissions control systems, and digital monitoring platforms. Specialized refractory materials and selective catalytic reduction catalysts rest on single-source supply relationships with German chemical suppliers. Tariff exposure on Chinese steel components creates vulnerability for new plant construction timelines. Distribution runs through inter-municipal waste associations that control collection infrastructure and gate fee negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through green hydrogen co-production pilots that capture EU Innovation Fund premiums and offset carbon pricing exposure.
For Market Incumbents: Hedge against feedstock quality erosion by securing long-term industrial waste supply contracts in Upper Austria's manufacturing zones. Invest in steam electrolysis integration at existing CHP sites to qualify for renewable hydrogen certificates before regulatory windows narrow. Capacity additions by REMONDIS in Salzburg threaten independent developers' feedstock security. For New Entrants and Emerging Players: The EU Green Deal in Austria opens a window for modular gasification units targeting Tyrol's alpine tourism clusters where district heating density remains insufficient for conventional CHP economics. Target farm-scale anaerobic digestion in Burgenland's agricultural cooperatives as the most penetrable segment. Pursue technology licensing partnerships with established emissions control suppliers to accelerate permitting timelines. For Investors and Strategic Acquirers: Diversified environmental services conglomerates are the most active acquirer in this space, seeking collection-to-energy vertical integration across Austria's provincial corridors. Five-to-ten year viability hinges on feedstock security through collection infrastructure control rather than pure generation assets. Monitor EU ETS carbon price trajectories as the critical inflection indicator for landfill diversion economics and thermal recovery competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Co-Production | Steam electrolysis at Vienna Spittelau qualifies for EU Innovation Fund support under renewable hydrogen definitions. |
| District Heating Expansion | Lower Austria's municipal utilities lock in 15-year baseload contracts with WTE operators in St. Pölten corridors. |
| Feedstock Security Integration | REMONDIS leverages collection infrastructure dominance across Salzburg and Upper Austria to control gate fees. |
| Plasma Gasification Piloting | Vorarlberg's chemical corridor deploys mobile units for chlorinated solvent destruction serving BASF supply chains. |
| Anaerobic Digestion Scale-Up | Burgenland agricultural cooperatives feed upgraded biomethane into regional gas grids from farm-scale digesters. |
Study Parameters
Coverage spans Austria's nine federal provinces, with primary inputs from each regional energy corridor. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation from EIA data, IEA reports, FERC-equivalent Austrian regulatory filings, and project development databases. Bottom-up plant-level capacity modeling triangulates against top-down provincial energy demand projections.
Granularity-level modeling disaggregates volume and value outputs across technology pathway, feedstock composition, end-user archetype, and application type throughout the forecast period. CAGRs derive from installed capacity expansion rates, district heating connection growth, and EU ETS carbon price trajectory assumptions. Industry-specific forecast inputs include municipal waste generation per capita trends and agricultural biogas registration volumes with Austria's national renewable energy authority.
Revisions become necessary when EU Green Deal enforcement timelines accelerate, carbon pricing mechanisms shift, or feedstock composition changes materially alter plant economics. Forecasts reflect documented assumptions on regulatory compliance costs and technology cost curves. A model refresh is warranted upon material change in EU ETS allowance prices or landfill diversion mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Canada Waste-To-Energy Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
North America Waste to Energy Market