
 Gulf of Mexico Oil & Gas Decommissioning Market | 2026-2036
Gulf of Mexico Oil & Gas Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf of Mexico Oil & Gas Decommissioning Market Insights
Platform preparation and well plugging revenue is reshaping contractor economics across the Gulf of Mexico shelf. TechnipFMC PLC leverages integrated subsea engineering capabilities to capture complex decommissioning bundles. Acteon Group Limited anchors marine site investigation and cutting tool deployment across multiple lease holders. Petrofac competes through project management discipline on large-scale platform removal campaigns.
Gulf of Mexico oil and gas decommissioning encompasses the engineered retirement of offshore hydrocarbon infrastructure, including the permanent plugging of subsea wells with cement barriers rated to formation pressures, removal of surface and subsea structures, and seabed restoration to regulatory baseline conditions. The primary purpose is to eliminate environmental liability exposure and satisfy federal lease obligations. Plug and Abandonment commands the dominant share of service value due to technical complexity and regulatory scrutiny, while Structure Removal is accelerating as vintage platforms reach end-of-design life across the 1950s-1980s installation cohort. Subsea Robotics occupies the highest-margin technology tier where ROV-deployed cutting systems reduce diver exposure and compress schedules.
BSEE enforces decommissioning timelines through idle iron regulations and lease stipulations that mandate removal within one year of production cessation, directly compelling operator spending. EPA coordinates National Pollutant Discharge Elimination System permitting for platform discharges during abandonment, shaping contractor mobilization sequencing and waste handling protocols. Stakeholders must monitor BSEE enforcement consistency and EPA permit backlogs as determinants of project start timing and contractor fleet utilization.
Market Dynamics
BSEE idle iron enforcement is compressing operator decommissioning timelines and expanding the contractor addressable base across Louisiana and Texas lease blocks. Subsea cutting technology advances are reducing diver exposure while accelerating platform removal schedules.
Growth Catalysts
- Regulatory Enforcement Intensification:BSEE idle iron regulations mandate structure removal within one year of production cessation, compelling operator capital deployment toward abandonment services.
- Vintage Infrastructure Cohort:Platforms installed during the 1950s-1980s drilling boom are reaching end-of-design life simultaneously across the Outer Continental Shelf.
- ROV-Deployed Cutting Systems:Subsea robotics technology is reducing personnel risk and compressing well severance timelines in deepwater applications.
Market Restraints
- Specialized Vessel Scarcity:Heavy-lift crane barges and platform removal vessels concentrate among a limited Gulf Coast supplier base, creating fleet utilization bottlenecks during seasonal weather windows.
- Steel Price Volatility:Scrap metal recovery economics fluctuate with commodity cycles, undermining structure removal project returns when global steel prices decline.
- Technical Complexity of Subsea Wells:High-pressure high-temperature formations and deteriorating cement barriers in aging wellbores escalate plugging difficulty beyond standard abandonment procedures.
Strategic Opportunities
- Integrated Service Bundling:Contractors combining plug and abandonment, structure removal, and site clearance under single project management capture margin expansion through scope consolidation.
- Decommissioning Liability Transfers:Financial assurance instruments and orphan well programs create third-party intervention models for distressed operator assets.
- Artificial Reef Conversion:EPA and state coastal resource agencies facilitate rigs-to-reef programs, reducing removal costs while satisfying environmental compliance.
Industry Challenges
- Experienced Personnel Shortage:Subsea engineers and offshore project managers with vintage platform expertise are aging out of the workforce faster than training pipelines replenish.
- Permit Sequencing Complexity:EPA National Pollutant Discharge Elimination System permit backlogs and state coastal coordination create mobilization delays that fragment contractor scheduling.
- Legacy Documentation Gaps:Incomplete as-built records and missing wellbore schematics from decades-old installations force costly site investigation before abandonment execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf of Mexico Oil & Gas Decommissioning Market |
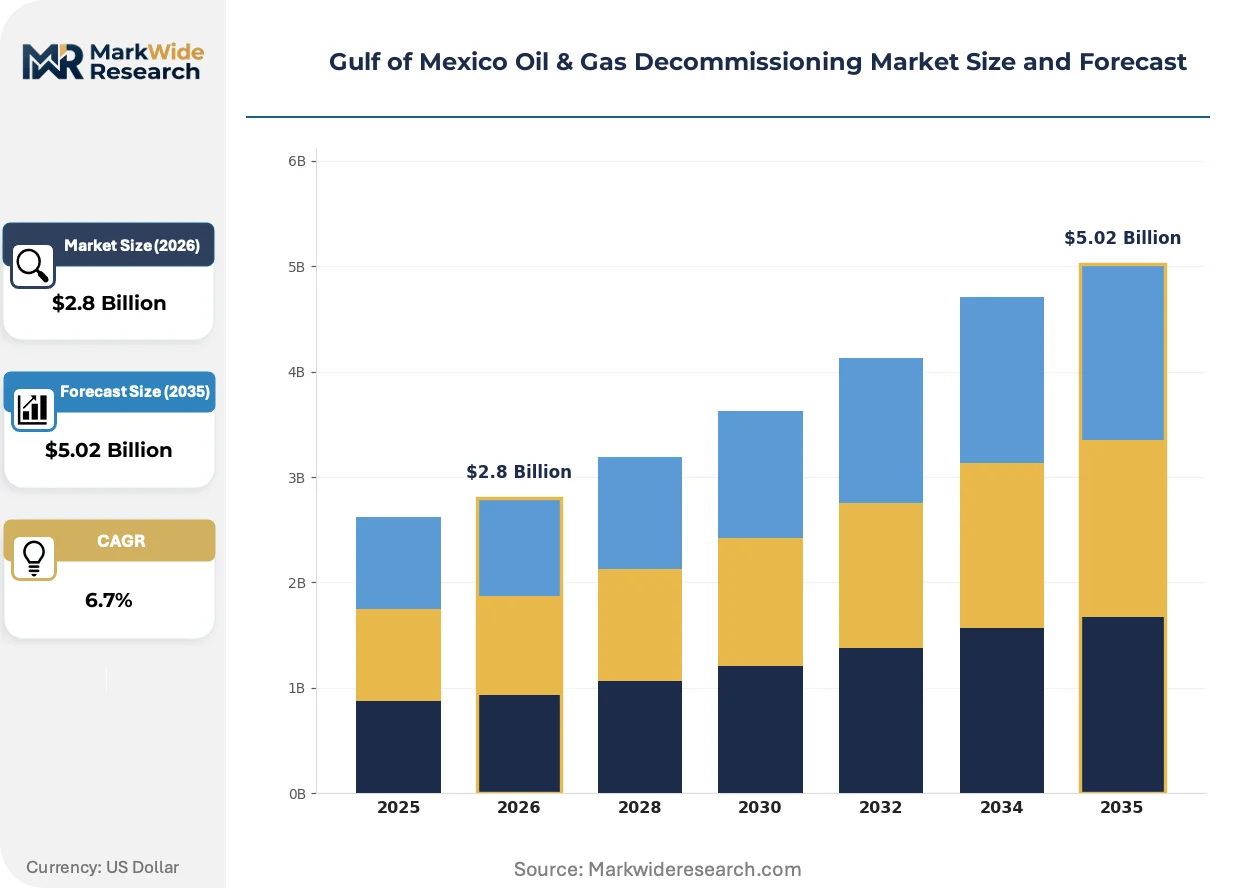
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Plug and Abandonment, Site Clearance, Waste Management, Structure Removal Technology: Subsea Robotics, ROVs, Drones, Cutting Equipment End User: Oil Companies, Government Agencies, Environmental Firms, Contractors Installation: Offshore Platforms, Pipelines, Subsea Facilities, Shoreline Terminals |
| Companies Covered | Proserv Group Inc., Ramboll Group, TETRA Technologies, Inc., Ardent Global LLC, Petrofac, Promethean Decommissioning Company, Danos, Acteon Group Limited, TechnipFMC PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf of Mexico Oil & Gas Decommissioning Market Trends and Innovations
Automation and remote operation technologies are displacing conventional diver-dependent methods across Gulf decommissioning workflows. Digital twin applications and predictive analytics are entering project planning phases.
Explosive severance technology is hybridizing with precision abrasive waterjet cutting in subsea pipeline and conductor removal applications. Major operators are adopting hybrid cutting packages for high-pressure wellheads where pure explosive methods risk formation damage. This convergence is hybridizing contractor equipment fleets and forcing capital retooling toward multi-modal cutting capability.
EPA has tightened National Pollutant Discharge Elimination System permitting requirements for platform discharge during abandonment preparation. Industrial consequence includes extended pre-mobilization timelines and mandatory waste handling protocol revisions. Structure removal contractors operating across Louisiana and Texas state waters are responding with dedicated environmental compliance personnel embedded in project teams.
Operator procurement of decommissioning services is consolidating toward integrated lump-sum contracts rather than discrete phase awards. Discrete service contractors face margin compression as bundled project managers capture schedule coordination premiums. This pattern concentrates most visibly among supermajors with multi-platform retirement campaigns across the Central Gulf planning area.
Gulf of Mexico Oil & Gas Decommissioning Market Segmentation
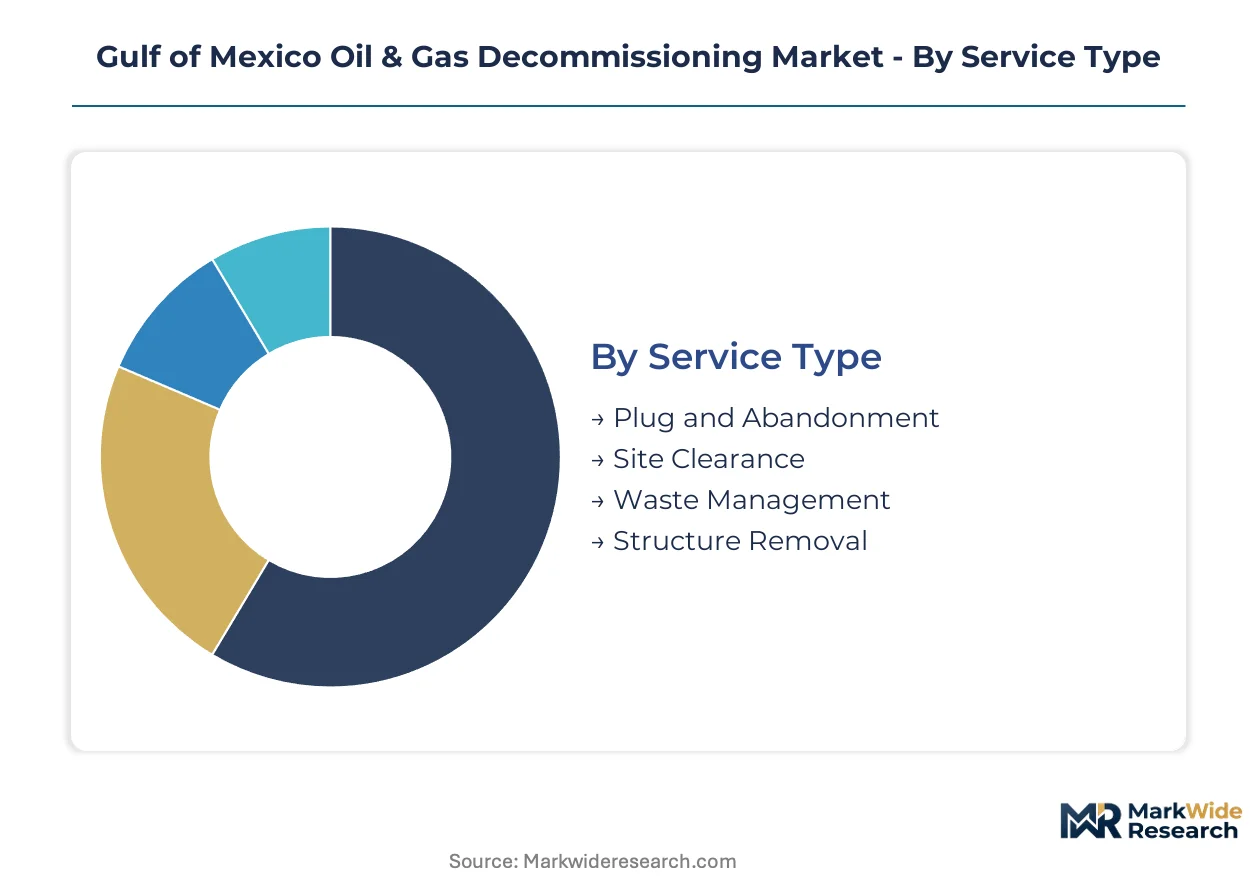
Segmentation reveals how contractor capabilities align with distinct technical requirements across the decommissioning value chain. Service complexity, technology deployment depth, and asset type dictate procurement patterns and margin structures.
Service Type:
After-sales service intensity varies dramatically across service categories, with well integrity verification and post-abandonment monitoring creating multi-year revenue attachments.
- Plug and Abandonment:Cement barrier installation and mechanical plug deployment seal wellbores against formation pressure. Louisiana shelf operators drive demand as BSEE idle iron deadlines compress execution windows for aging wellbores.
- Site Clearance:Seabed survey and debris removal restore lease blocks to regulatory baseline conditions. Texas state waters concentrate procurement where coastal resource agencies coordinate post-removal verification.
- Waste Management:Hydrocarbon-contaminated material handling and onshore disposal coordination.
- Structure Removal:Platform jacket severance and topside lift operations using heavy-lift marine assets.
By volume, Plug and Abandonment leads. By growth pace, Structure Removal is expanding most quickly as vintage platforms reach end-of-design life.
Technology:
Technology selection tracks water depth and diver exposure limits, with deeper Gulf applications demanding greater capital intensity per intervention.
- Subsea Robotics:ROV-deployed manipulator systems execute valve operation and cutting tasks in depths exceeding diver limits. Deepwater lease blocks off Louisiana anchor procurement as operators eliminate personnel risk in high-pressure environments.
- ROVs:Tethered vehicles provide visual inspection and light intervention across shelf and slope installations. Multiple Texas and Louisiana operators maintain standing ROV contracts for routine structural assessments.
- Drones:Aerial platforms conduct topside flare boom and helideck surveys.
- Cutting Equipment:Abrasive waterjet and explosive severance tools for conductor and pipeline sectioning.
By deployment frequency, ROVs dominate. By capability expansion, Subsea Robotics is gaining share fastest.
End User:
End user procurement authority shapes contract structure, with supermajors favoring bundled awards and government entities driving orphan well liability transfers.
- Oil Companies:Supermajors and independents holding federal lease obligations commission full-scope decommissioning campaigns. Central Gulf planning area operators concentrate spending as asset retirement obligations mature simultaneously.
- Government Agencies:BSEE enforcement actions and state orphan well programs fund remediation of abandoned assets. Louisiana and Texas coastal restoration initiatives channel federal and state dollars toward liability relief.
- Environmental Firms:Third-party consultants conduct compliance verification and restoration monitoring.
- Contractors:Prime contractors subcontract specialized scope to niche service providers.
By project count, Oil Companies lead. By contract value acceleration, Government Agencies are climbing the fastest as orphan well programs expand.
Installation:
Installation type determines removal methodology, with fixed platforms requiring heavy-lift marine assets and subsea facilities demanding precision cutting at depth.
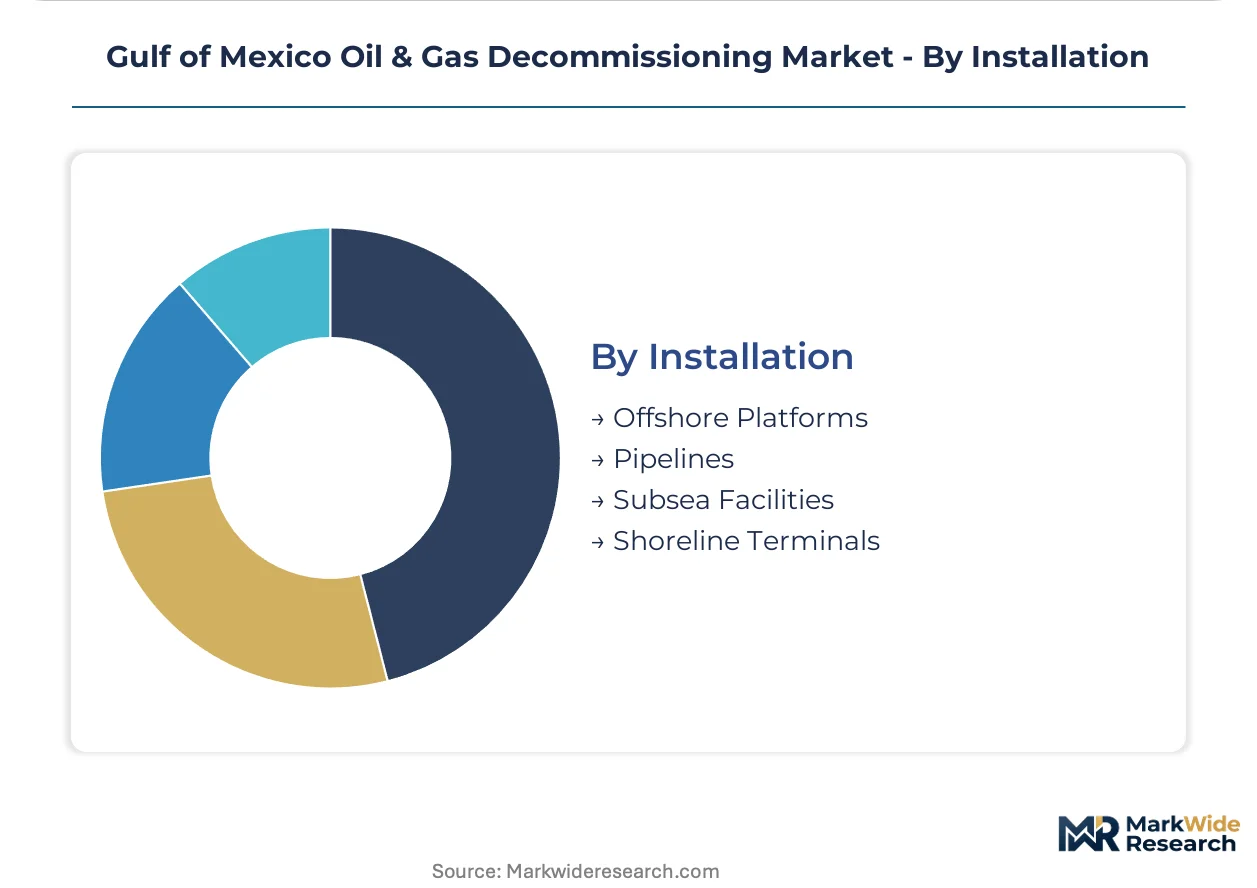
- Offshore Platforms:Fixed steel jackets and compliant towers installed across the 1950s-1980s drilling boom require complete removal or reef conversion. Outer Continental Shelf lease blocks off Louisiana concentrate the heaviest decommissioning liability.
- Pipelines:Subsea flowlines and export trunk lines demand severance and burial or removal based on diameter and location. Texas coastal corridor operators prioritize pipeline abandonment as coastal development encroaches on legacy corridors.
- Subsea Facilities:Manifolds, wellheads, and tie-in assemblies on the seafloor.
- Shoreline Terminals:Nearshore processing and storage infrastructure in state waters.
By decommissioning obligation volume, Offshore Platforms lead. By regulatory priority, Pipelines are advancing fastest as coastal zone management tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Operator price sensitivity varies sharply across the Gulf basin. Shelf independents facing BSEE idle iron penalties exhibit highest elasticity, while deepwater supermajors with asset retirement obligation reserves absorb premium pricing for integrated service bundles.
Louisiana Outer Continental Shelf
Vintage platform clusters installed during the 1950s-1980s drilling boom drive concentrated decommissioning demand. BSEE enforces strict idle iron removal timelines that compress contractor selection windows. Port Fourchon anchors heavy-lift vessel mobilization for structure removal campaigns across the Central Gulf planning area.
Texas State Waters
Coastal pipeline corridors face abandonment pressure as urban development encroaches on legacy infrastructure. EPA National Pollutant Discharge Elimination System permitting requirements shape pre-mobilization sequencing. Corpus Christi contractors coordinate with state coastal resource agencies on post-removal seabed verification protocols.
Federal Waters Offshore Mississippi and Alabama
Smaller platform inventories create sporadic demand spikes that challenge contractor fleet scheduling. BSEE lease stipulations mandate removal within one year of production cessation. Mobile Bay service companies specialize in shallow-water platform preparation and well plugging execution.
Eastern Gulf Planning Area
Deepwater subsea facilities demand ROV-deployed cutting systems at depths exceeding diver limits. BSEE well integrity regulations escalate technical complexity for high-pressure wellbore abandonment. Tampa-based marine contractors supply remotely operated vehicles for precision severance operations.
Gulf of Mexico Oil & Gas Decommissioning Market Competitive Landscape
Integrated project managers and specialized technology providers split the market into distinct capability tiers. The vendor base concentrates among Gulf Coast-based operators with standing BSEE relationships and heavy-marine asset access. Three archetypes dominate: full-scope integrators bundling plug-and-abandonment through site clearance; cutting technology specialists deploying subsea robotics; and marine construction firms with platform removal vessel fleets. Competitive positioning hinges on lump-sum contract capture and multi-platform campaign awards from supermajors.
Among full-scope integrators, TechnipFMC PLC and Petrofac occupy positions as bundled service anchors. Acteon Group Limited exemplifies the technology-specialist archetype through marine site investigation and cutting tool deployment. These three entities represent the dominant competitive vectors where scope consolidation and subsea robotics capability determine procurement outcomes across Louisiana and Texas lease blocks.
| Leading Market Players |
|---|
| Proserv Group Inc. |
| Ramboll Group |
| TETRA Technologies, Inc. |
| Ardent Global LLC |
| Petrofac |
| Promethean Decommissioning Company |
| Danos |
| Acteon Group Limited |
| TechnipFMC PLC |
| Others |
Pricing and Supply Chain Analysis
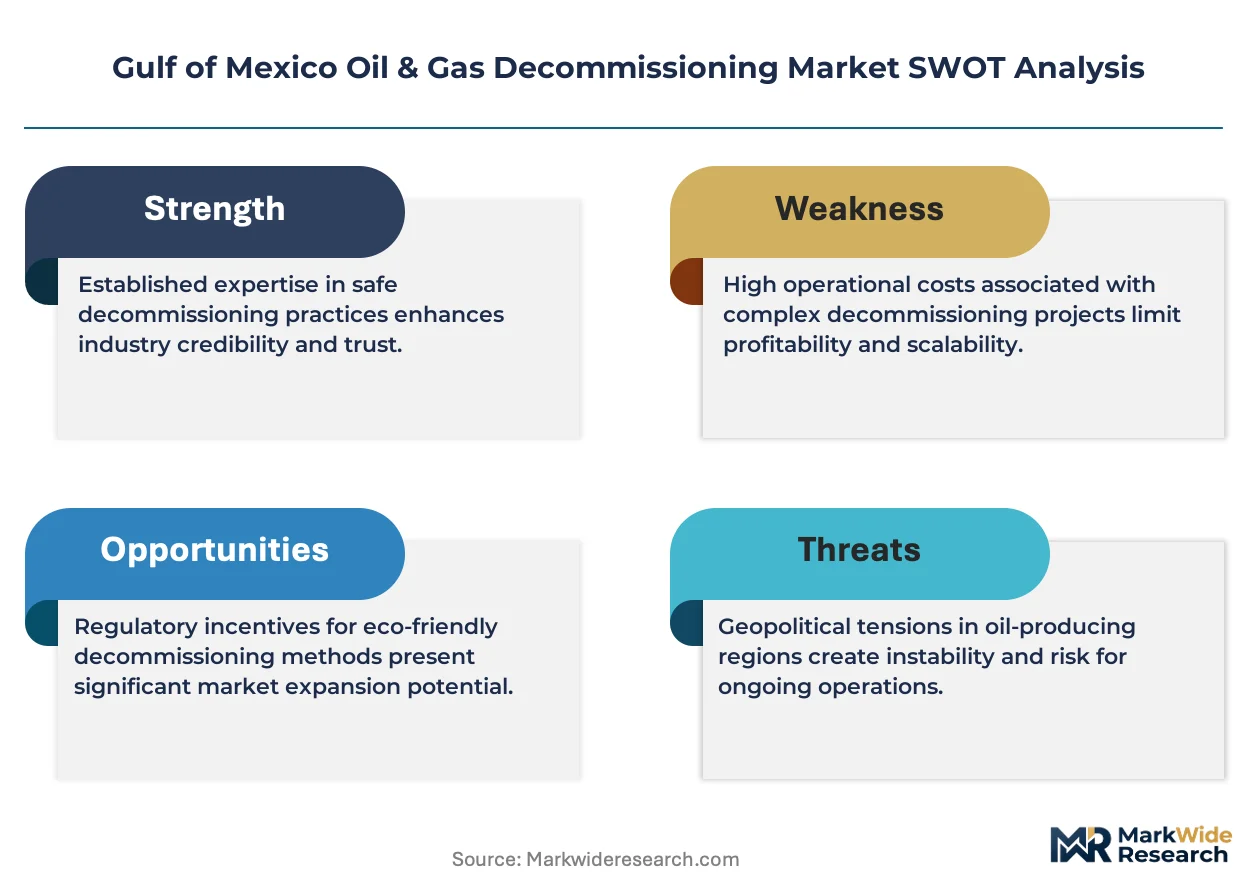
Port Fourchon marine logistics corridors anchor cost dynamics across the Gulf decommissioning supply base, concentrating heavy-lift vessel mobilization capacity within a single Louisiana hub. This geographic chokepoint feeds pricing power to incumbent marine contractors while forcing shelf independents into premium spot-market rates during seasonal weather windows.
Pricing Analysis
Post-abandonment monitoring and well integrity verification contracts drive lifetime value for contractors securing multi-year service attachments. Three-tier pricing structure across integrated lump-sum bundles, discrete phase awards, and spot-market intervention separates supermajors with asset retirement obligation reserves from price-sensitive shelf independents facing BSEE idle iron penalties. Cost compression in discrete phase contracting is intensifying because bundled project managers capture schedule coordination premiums. Shelf independents exhibit highest price sensitivity; deepwater supermajors absorb premium pricing for integrated service bundles.
Supply Chain Analysis
Heavy-lift crane barge capacity concentrates among Gulf Coast marine construction firms with standing BSEE relationships and Port Fourchon berthing priority. Equipment and vessel sourcing draws from Texas fabrication yards, Louisiana marine terminals, and Mississippi specialty steel suppliers. Single-source vulnerability runs through limited heavy-lift vessel availability during hurricane season weather windows. Distribution runs through prime contractor-subcontractor tiers with specialized cutting technology providers and ROV operators feeding into integrated project managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as BSEE enforcement intensification splinters demand across urgent idle iron compliance deadlines, creating niches for rapid-response contractors and liability transfer specialists.
For Market Incumbents: Build regulatory relationship moats through embedded compliance personnel and pre-approved EPA permit pathways. Consolidate cutting technology capabilities through equipment fleet hybridization toward multi-modal abrasive waterjet and explosive severance systems. Capacity addition in Port Fourchon heavy-lift anchorage protects against seasonal weather bottlenecks threatening competitor mobilization. For New Entrants and Emerging Players: Texas coastal pipeline corridors facing urban encroachment represent the most penetrable entry point for specialized abandonment contractors. Louisiana shelf well plugging execution for distressed independents offers second white-space target with urgent BSEE deadline pressure. Go-to-market angle centers on rapid permitting expertise compressing pre-mobilization timelines against incumbent bureaucratic inertia. For Investors and Strategic Acquirers: Carve-out targets emerge from supermajor asset retirement obligation reserve restructurings and orphan well program fund allocations. Long-term viability frames around regulatory enforcement permanence and vintage infrastructure cohort age-out dynamics. Signal to watch is EPA National Pollutant Discharge Elimination System permit backlog clearance rates indicating project start velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Bundling | Captures margin expansion through plug-and-abandonment-to-site-clearance scope consolidation under single project management. |
| Subsea Robotics Capability Expansion | Reduces diver exposure in deepwater Louisiana lease blocks while compressing well severance timelines against conventional methods. |
| Artificial Reef Conversion Partnership | Lowers structure removal costs through EPA and state coastal resource agency coordination on rigs-to-reef program eligibility. |
| Heavy-Lift Vessel Fleet Addition | Addresses specialized marine asset scarcity creating utilization bottlenecks during Central Gulf planning area campaign peaks. |
| Decommissioning Liability Transfer Instruments | Creates third-party intervention models for distressed operator assets through financial assurance and orphan well program structures. |
Research Methodology
Initial hypotheses were tested against primary input from offshore project managers, BSEE compliance officers, marine construction procurement leads, and heavy-lift vessel operators and refined through secondary validation. Sources included BSEE idle iron enforcement databases, EPA National Pollutant Discharge Elimination System permit filings, SEC 10-K asset retirement obligation disclosures, and Gulf Coast marine terminal customs records. Bottom-up contractor revenue aggregation and top-down operator spending obligation triangulation anchored market sizing.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled encompass service type complexity tiers, technology deployment depth, end-user procurement authority, and water depth classifications. CAGRs derived from vintage infrastructure age-out curves and regulatory deadline enforcement intensity trajectories. Forecast inputs incorporated BSEE permit approval velocity and heavy-lift vessel fleet utilization seasonal patterns.
Macroeconomic conditions sit as an overlay; deviation in steel scrap commodity cycles and Gulf Coast labor availability would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement consistency and technology adoption rates. Quarterly review of BSEE enforcement action volumes and EPA permit backlog clearance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
South Sudan Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Floating LNG Power Plant Market