
 Marine Incinerators Market | 2026-2036
Marine Incinerators Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Incinerators Market Outlook
IMO Tier III and MARPOL Annex VI compliance specifications is redrawing procurement priorities across the marine incinerators sector. Alfa Laval leverages its exhaust gas cleaning integration expertise to bundle incineration with scrubber retrofits. Wärtsilä Corporation anchors large-vessel contracts through its integrated power and propulsion platform sales. ATLAS INCINERATORS ApS specializes in compact, high-temperature units purpose-built for offshore supply vessels and naval auxiliaries.
Marine incinerators are self-contained combustion systems engineered to thermally destroy shipboard waste at temperatures exceeding 850 degrees Celsius, reducing solid refuse and oily sludge to inert ash for compliant disposal at port reception facilities. Fixed incinerators dominate newbuild installations due to permanent structural integration and higher throughput capacity, while modular incinerators represent the fastest-growing product category as shipyards seek pre-fabricated, skid-mounted solutions that compress yard time and simplify class society approval. Oil-fired units retain the largest fuel-type share given existing bunker infrastructure, though biogas-compatible designs are gaining traction where dual-fuel engine adoption creates captive biogas availability.
The International Maritime Organization's MARPOL framework, the European Union's MRV and ETS maritime extensions, and the US Coast Guard's NVIC pollution prevention guidelines collectively mandate onboard waste minimization and documented thermal treatment. These standards compel operators to replace older overboard discharge systems with certified incineration or force vessels into restricted operational zones. Shipowners and equipment suppliers must monitor evolving port-state control inspection protocols and carbon accounting boundaries that could redefine incinerator emissions compliance thresholds.
Market Dynamics
IMO MARPOL Annex V enforcement is compressing overboard discharge windows and forcing fleet-wide retrofits, while East Asian shipbuilding concentration is reshaping supplier-procurement relationships through integrated yard contracts.
Growth Catalysts
- MARPOL Annex VI sulfur caps:Tightened emission standards across international waters mandate thermal treatment of sludge and refuse, eliminating cheaper overboard alternatives for deep-sea operators.
- Offshore supply vessel expansion:North Sea and Gulf of Mexico drilling activity is generating demand for compact, high-temperature incinerators purpose-built for platform supply fleets.
- Port reception facility fees:Rotterdam, Singapore, and Long Beach have implemented escalating charges for untreated waste landing, making onboard incineration cost-competitive against shore disposal.
Market Restraints
- Stainless steel alloy volatility:Incinerator combustion chambers require heat-resistant 310S and 253MA grades, exposing manufacturers to nickel and chromium price swings from Indonesian and South African supply.
- South Korean yard concentration:Hyundai Heavy Industries, Samsung Heavy Industries, and Daewoo Shipbuilding control over sixty percent of newbuild incinerator procurement, creating single-source dependency risk for component suppliers.
- Scrubber-washwater treatment substitution:Open-loop exhaust gas cleaning systems reduce sludge generation, directly compressing incinerator throughput requirements on retrofitted vessels.
Strategic Opportunities
- Indian coastal shipping modernization:The country's Sagarmala port development program and domestic fleet renewal create first-mover potential for incinerator suppliers targeting the underpenetrated subcontinent market.
- Biogas-compatible dual-fuel designs:LNG and methanol engine adoption aboard newbuilds generates captive biogas streams that can displace bunker fuel in thermal oxidation systems.
- Class society pre-approval channels:Lloyd's Register and DNV pre-certified skid-mounted modules are compressing yard installation timelines and opening aftermarket retrofit demand outside newbuild cycles.
Industry Challenges
- Marine welding certification scarcity:Qualified ASME Section IX and IIW-certified welders for high-temperature alloy fabrication command premium wages and extended lead times, constraining production scaling.
- IMO MEPC circular interpretation variance:Port state control inspectors in different flag states apply inconsistent standards for ash residue documentation and combustion temperature verification, creating compliance uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Incinerators Market |
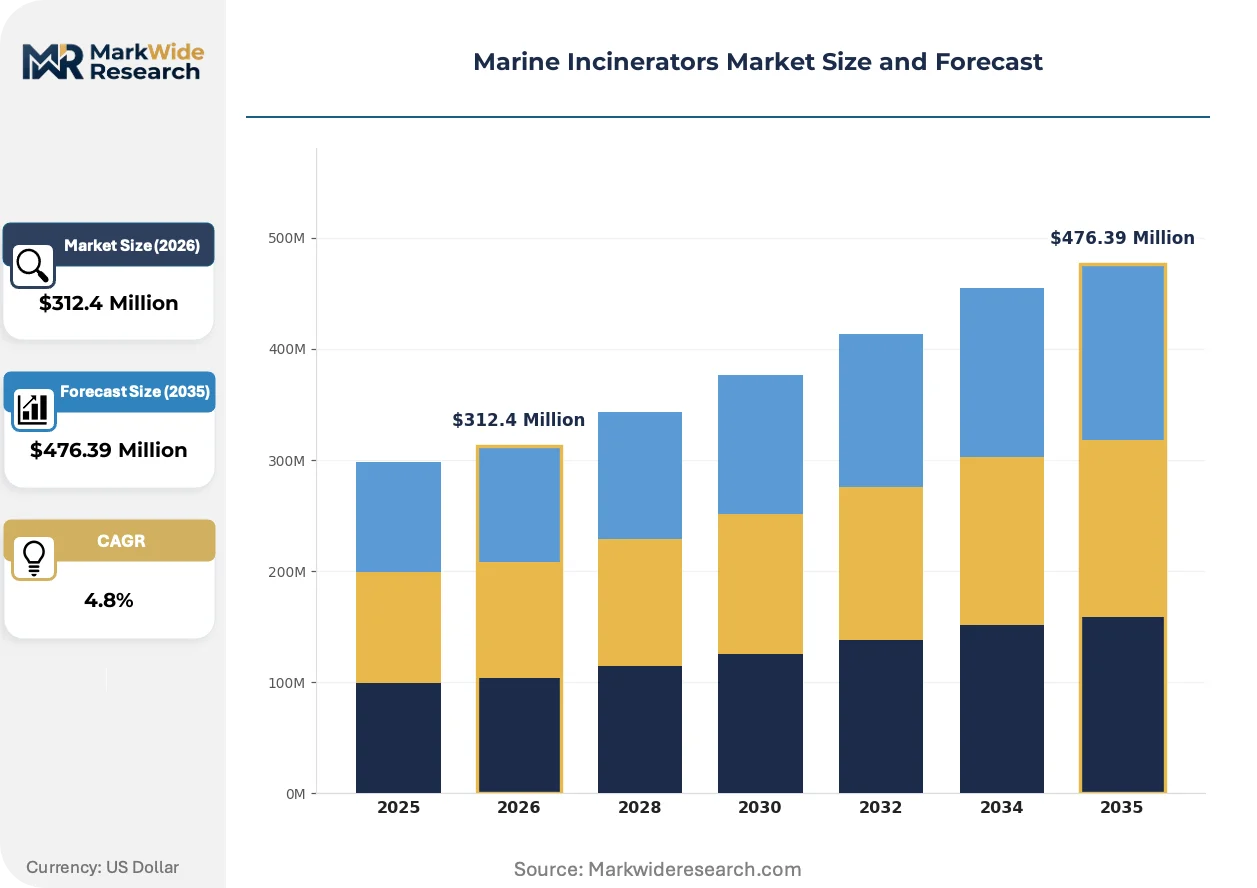
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Incinerators, Portable Incinerators, Specialized Incinerators, Modular Incinerators Fuel Type: Oil, Gas, Biogas, Solid Waste Installation Type: Onboard, Shore-Based, Containerized, Mobile End User: Shipping Companies, Government Agencies, Waste Management Firms, Research Institutions |
| Companies Covered | Alfa Laval, TeamTec AS, ATLAS INCINERATORS ApS, DETEGASA, INCINER8 Limited, Wärtsilä Corporation, China Deyuan Marine Fitting Co., Ltd., Fuente International Co., Ltd., ACS, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Incinerators Market Strategic Shifts
Equipment architecture is splitting between maximized throughput for cruise and container sectors versus minimized footprint for offshore and naval applications, with digitization threading through both paths.
Plasma-assisted incineration is bifurcating the high-temperature waste destruction segment. This technology achieves combustion temperatures exceeding 1,200 degrees Celsius through electrical arc generation, enabling complete destruction of medical and hazardous refuse without residual ash. Cruise operators with large passenger complements and complex waste streams are piloting units on newbuild megaships. The technology is compressing maintenance intervals and enabling smaller physical footprints relative to conventional oil-fired chambers.
EU MRV and ETS maritime extensions are tightening emissions accounting boundaries for vessel auxiliary systems. Incinerator CO2 output must now be logged and reported alongside propulsion emissions, forcing suppliers to integrate continuous emissions monitoring hardware. Container lines with European trading routes are prioritizing certified low-NOx burner designs to minimize carbon liability exposure.
Buyer consolidation through fleet management companies is compressing procurement cycles and unbundling after-sales service contracts. Large operators like MSC Shipmanagement and V.Group are negotiating multi-vessel framework agreements that separate equipment purchase from installation and commissioning. This pattern is most visible in Greek and German owner-operator markets, where centralized technical departments override traditional yard-specified packages.
Marine Incinerators Market Segmentation
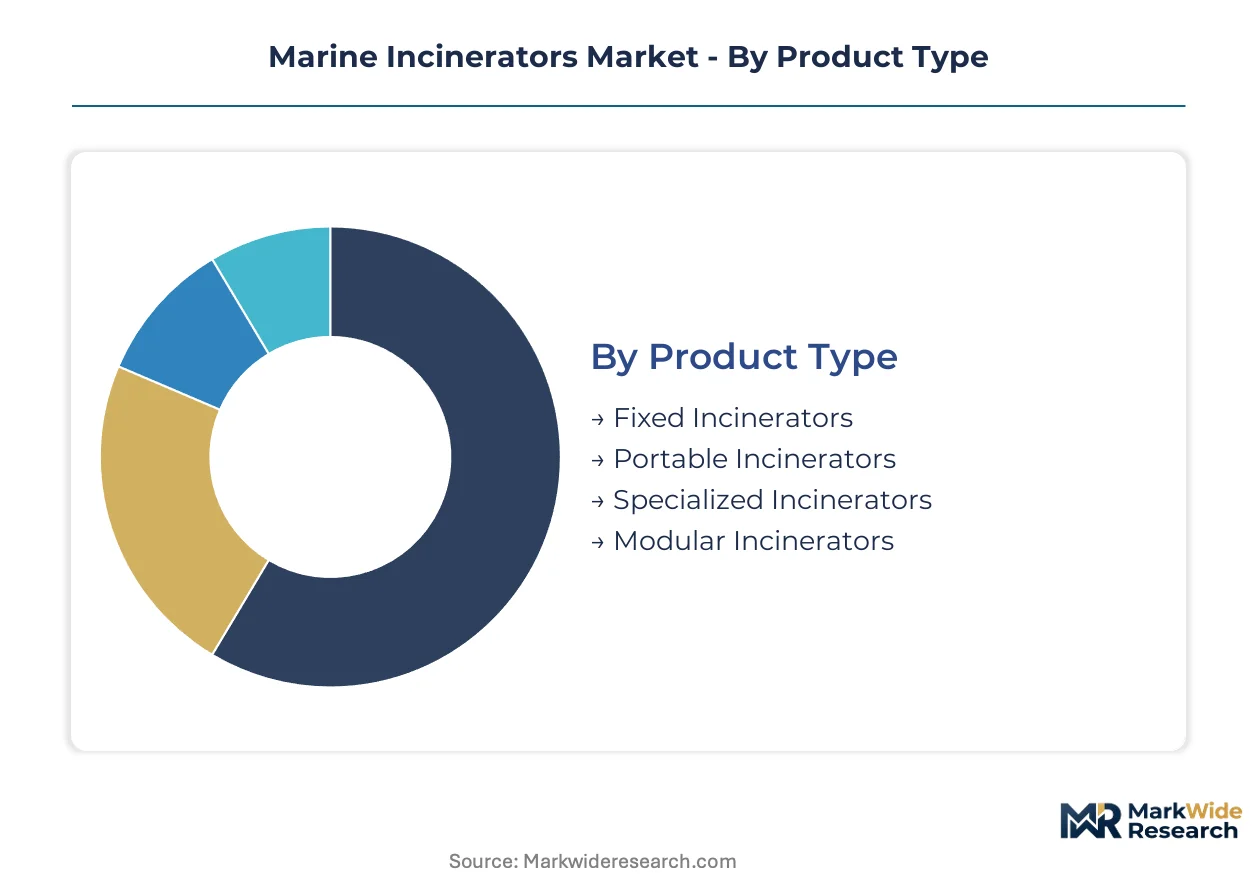
Marine incinerator procurement splits sharply between permanent newbuild installations and flexible retrofit solutions, with fuel compatibility and regulatory jurisdiction dictating technical specifications across vessel categories.
Product Type:
Fixed incinerators command the widest margin pools due to structural integration complexity and recurring service attach rates, while modular formats are compressing yard labor costs and accelerating approval cycles.
- Fixed Incinerators:Permanent combustion chambers welded directly into vessel engine room structures achieve throughput rates exceeding 500 kg per hour for cruise and container fleets. South Korean newbuild yards at Hyundai Heavy Industries and Samsung Heavy Industries specify these units for 12,000+ TEU container vessels under long-term class society certification.
- Modular Incinerators:Pre-fabricated skid-mounted systems reduce shipyard installation time by 40-60% through factory-tested subassemblies. Chinese yards at Dalian and Shanghai are adopting these for mid-size bulk carriers where compressed delivery schedules outweigh permanent integration benefits.
- Portable Incinerators:Compact units deployed on offshore platforms and temporary research vessels where permanent installation is impractical.
- Specialized Incinerators:Medical waste and hazardous material variants for naval hospital ships and polar research fleets requiring temperature verification above 1,100 degrees Celsius.
Fixed incinerators hold installed capacity. Modular incinerators are rotating up the share rankings.
Fuel Type:
Biogas-compatible designs are climbing the fastest as LNG and methanol dual-fuel engine adoption creates captive fuel availability aboard newbuilds.
- Oil:Residual fuel oil and diesel variants dominate existing fleet retrofits, leveraging ubiquitous bunker infrastructure at Singapore, Rotterdam, and Fujairah. These units face carbon accounting pressure under EU ETS maritime extensions.
- Biogas:Methane-compatible burner systems integrate with engine boil-off gas recovery, eliminating separate fuel storage for thermal oxidation. Wärtsilä's dual-fuel engine contracts increasingly bundle these incinerators for LNG carriers.
- Gas:LPG and natural gas variants for coastal ferries and short-sea shipping where shore-side refueling infrastructure exists.
- Solid Waste:Pelletized refuse and processed sludge systems for vessels with extensive onboard waste sorting and drying capabilities.
Oil-fired units retain legacy fleet dominance. Biogas designs are expanding most quickly in newbuild specifications.
Installation Type:
Onboard systems generate recurring revenue through class society recertification, while containerized formats serve intermittent demand from expedition fleets and temporary drilling campaigns.
- Onboard:Engine room and auxiliary machinery space installations subject to SOLAS fire safety regulations and flag state inspection protocols. These systems require continuous emissions monitoring integration under IMO MRV frameworks.
- Containerized:Standard ISO-frame units for offshore supply vessels and seismic research fleets rotating between contracts. Gulf of Mexico operators lease these during drilling campaigns rather than permanent installation.
- Shore-Based:Port reception facility incinerators at Rotterdam, Singapore, and Long Beach handling waste from vessels without onboard thermal treatment capability.
- Mobile:Trailer-mounted systems for naval auxiliary fleets and emergency response vessels requiring rapid redeployment.
Onboard installation anchors revenue stability. Containerized formats are gaining share in cyclical offshore markets.
End User:
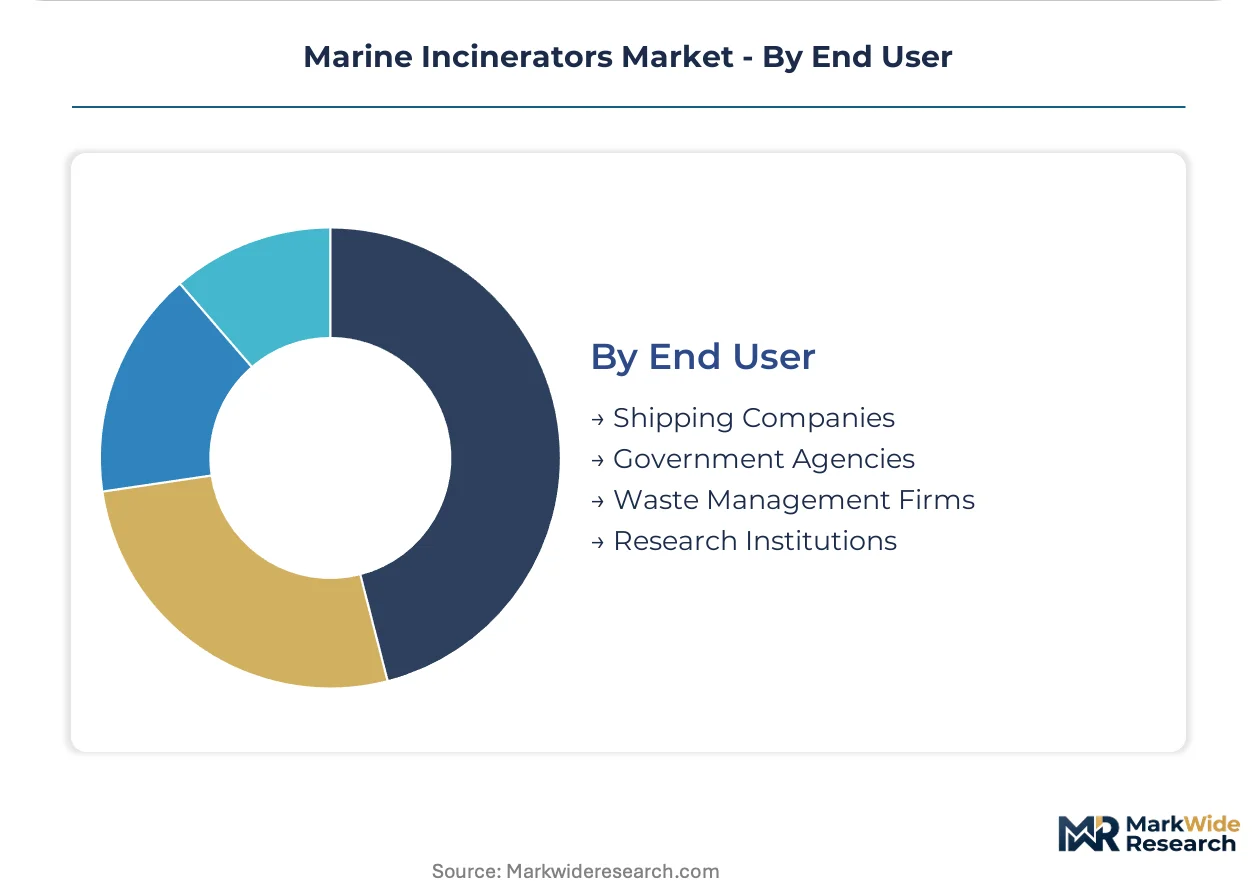
Shipping companies concentrate procurement volume through fleet management frameworks, while government agencies dictate technical specifications through naval architecture standards.
- Shipping Companies:MSC Shipmanagement, V.Group, and Anglo-Eastern negotiate multi-vessel framework agreements unbundling equipment purchase from installation. Greek and German owner-operators centralize technical procurement decisions.
- Government Agencies:Naval procurement through US Navy, Royal Navy, and coast guard fleets mandates MIL-SPEC corrosion resistance and shock certification. These contracts carry 15-20 year service life requirements.
- Waste Management Firms:Port reception facility operators at Singapore's PSA Marine and Rotterdam's Port Authority contract shore-based thermal treatment for untreated vessel waste landing.
- Research Institutions:Polar and oceanographic fleets including Scripps Institution and British Antarctic Survey require specialized medical waste destruction for extended isolation missions.
Shipping companies hold contract volume concentration. Government agencies are rotating up the specification influence rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade imbalances in shipbuilding capacity and vessel registrations are redrawing marine incinerator procurement geography. Export-heavy newbuild yards in East Asia supply equipment to import-dependent owner-operators in Europe and North America.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries command over sixty percent of global newbuild incinerator procurement. The country's Ministry of Oceans and Fisheries enforces strict MARPOL compliance timelines for domestically flagged vessels. Ulsan and Geoje shipbuilding clusters integrate fixed incinerators into 12,000+ TEU container vessels under long-term class society certification.
China
Dalian and Shanghai yards are adopting modular skid-mounted systems to compress delivery schedules for mid-size bulk carriers. The Ministry of Ecology and Environment tightens port reception facility standards along the Yangtze River Delta. Jiangsu province shipbuilders now bundle pre-certified incinerator modules with newbuild contracts.
Germany
Greek and German owner-operators centralize technical procurement through Hamburg and Bremen-based fleet management companies. The Federal Maritime and Hydrographic Agency enforces EU MRV emissions reporting for auxiliary systems including incinerators. Northern German ports of Hamburg and Bremerhaven have implemented escalating charges for untreated waste landing.
United States
Gulf of Mexico drilling activity generates demand for containerized incinerator leases during temporary drilling campaigns. The US Coast Guard's NVIC pollution prevention guidelines mandate onboard waste minimization for vessels calling at American ports. Houston and New Orleans serve as distribution nodes for offshore supply vessel equipment.
Norway
North Sea offshore supply fleets require compact high-temperature units for platform supply operations. The Norwegian Maritime Authority enforces stringent combustion temperature verification protocols. Stavanger and Bergen clusters specialize in Arctic-class incinerator specifications for polar research and naval auxiliary vessels.
Marine Incinerators Market Competitive Environment
Listed leaders compete with private specialists across technology integration and yard relationship depth. The vendor base splits between diversified industrial conglomerates and focused combustion equipment fabricators. Three archetypes dominate: exhaust gas cleaning integrators bundling incineration with scrubber retrofits, power and propulsion platform suppliers anchoring large-vessel contracts, and compact high-temperature specialists serving offshore and naval segments. Capacity expansion and class society pre-certification partnerships constitute the dominant competitive moves.
Among Scandinavian-based specialists, ATLAS INCINERATORS ApS and TeamTec AS occupy positions within the compact high-temperature tier. Wärtsilä Corporation represents the integrated platform archetype. Alfa Laval exemplifies the exhaust gas cleaning bundling strategy. China Deyuan Marine Fitting Co., Ltd. and Fuente International Co., Ltd. anchor the Chinese fabricator segment. DETEGASA and INCINER8 Limited sit within the European private specialist tier. ACS, Inc. represents North American market presence.
| Leading Market Players |
|---|
| Alfa Laval |
| TeamTec AS |
| ATLAS INCINERATORS ApS |
| DETEGASA |
| INCINER8 Limited |
| Wärtsilä Corporation |
| China Deyuan Marine Fitting Co., Ltd. |
| Fuente International Co., Ltd. |
| ACS, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between South Korean shipyards and stainless steel suppliers lock in heat-resistant alloy access while capping combustion chamber cost volatility for incinerator manufacturers. These arrangements bundle 310S and 253MA grade procurement with fixed pricing tiers that extend across newbuild cycles at Hyundai Heavy Industries and Samsung Heavy Industries.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on class society certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because Chinese yards at Dalian and Shanghai are negotiating unbundled equipment-only purchases. Greek owner-operators demonstrate highest price sensitivity, while cruise operators with MARPOL Annex VI compliance mandates show lowest.
Supply Chain Analysis
Strategic stockpiling of nickel and chromium dominates over just-in-time preferences given Indonesian and South African supply volatility. Manufacturing concentrates in South Korea, China, and Norway. Raw material dependencies draw from heat-resistant alloy foundries, burner system fabricators, and emissions monitoring hardware. Single-source vulnerability runs through South Korean yard procurement concentration. Distribution feeds from yard-integrated supply chains to fleet management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine incinerator procurement is shifting toward platform economics as exhaust gas cleaning and power system bundling redefines vendor relationships. Interoperability between incineration and scrubber retrofits at Alfa Laval exemplifies this ecosystem consolidation.
For Market Incumbents: Consolidate yard relationships through class society pre-certification partnerships that compress approval timelines. Deepen backward integration into heat-resistant alloy supply to offset nickel price volatility from Indonesian sources. Defend against modular specialist encroachment by anchoring large-vessel platform contracts. For New Entrants and Emerging Players: Lloyd's Register fast-track certification opens retrofit demand outside newbuild cycles. Target containerized formats for Gulf of Mexico offshore supply fleets where temporary drilling campaigns favor lease-over-buy economics. Pursue biogas-compatible burner designs as LNG carrier newbuilds generate captive fuel availability. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform suppliers over standalone component fabricators. Long-term viability hinges on emissions monitoring hardware integration under EU MRV frameworks. Watch for IMO MEPC circular interpretation convergence as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Class Society Pre-Certification | Lloyd's Register and DNV pre-approval compresses yard installation timelines for modular formats. |
| Backward Integration into Alloys | In-house 310S and 253MA supply reduces exposure to Indonesian nickel volatility. |
| Biogas-Compatible Design Development | Methane burner systems capture LNG carrier boil-off gas for thermal oxidation fuel. |
| Fleet Management Framework Agreements | MSC Shipmanagement-style unbundling separates equipment purchase from installation services. |
| Emissions Monitoring Hardware Integration | Continuous CO2 logging meets EU ETS maritime auxiliary system reporting requirements. |
Study Parameters
A standing panel of shipyard procurement directors, fleet management technical officers, class society surveyors, and aftermarket service heads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from IMO MEPC circulars, Lloyd's Register certification databases, customs trade records for heat-resistant alloy shipments, and SEC filings from listed marine equipment suppliers. Bottom-up vessel fleet modeling and top-down shipbuilding output triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. The analytical framework modeled segmentation across product type, fuel compatibility, installation format, and end-user procurement concentration. CAGRs derived from shipbuilding orderbook trajectories and regulatory compliance deadline clustering. Industry-specific inputs included MARPOL Annex V enforcement timelines and EU ETS maritime extension implementation phases.
Decision-makers should treat outputs as directional under assumptions of sustained MARPOL enforcement and stable East Asian shipbuilding capacity; material deviation would warrant model refresh. Specific risks include South Korean yard consolidation altering procurement patterns and plasma-assisted incineration adoption accelerating beyond modeled penetration. Revision becomes warranted when scrubber-washwater treatment substitution crosses threshold levels that compress incinerator throughput requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Oil and Gas Waste Heat Recovery Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Brazil Waste to Energy Market