
 US Electric Vehicle Charging Infrastructure Market | 2026-2036
US Electric Vehicle Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Vehicle Charging Infrastructure Market Intelligence
Bi-directional charging integration is reshaping how grid services and vehicle-to-home applications merge into station design. Tesla leverages its proprietary connector standard and Supercharger network density to dominate highway corridor positioning. ChargePoint sustains broad installation coverage across commercial real estate and workplace settings. EVgo anchors its competitive stance through partnerships with retail hosts and utility-backed rate structures.
US Electric Vehicle Charging Infrastructure encompasses the hardware, software, and grid interconnection systems that deliver electrical energy to battery electric vehicles, spanning power levels from residential Level 1 units below 7 kW to DC Fast Charging systems exceeding 350 kW. The primary purpose centers on replenishing stored energy to sustain vehicle mobility while managing grid load profiles and demand response protocols. DC Fast Charging commands the highest capital intensity and utility coordination requirements, creating concentrated margin pools for operators with secured grid capacity. Residential installations maintain volume leadership through garage and multi-unit dwelling deployments, though per-unit economics remain thinner. Fleet charging represents the fastest-expanding installation category as logistics operators electrify depots and seek predictable overnight load scheduling.
The Federal Highway Administration administers NEVI formula funding that mandates Buy America compliance and interstate spacing standards for qualified charging projects. The EPA tailpipe emissions rules and California Air Resources Board zero-emission vehicle mandates create complementary demand pressures that expand the addressable vehicle base requiring charging access. OSHA electrical safety standards and NEC Article 625 govern installer certification and equipment grounding protocols that shape market entry requirements. Stakeholders must monitor how state utility commission rate case outcomes and interconnection queue reforms determine project economics and deployment velocity across fragmented regulatory landscapes.
Market Dynamics
Fleet electrification mandates and NEVI formula funding are compressing deployment timelines while forcing simultaneous investments in grid interconnection, software integration, and hardware standardization across fragmented state regulatory environments.
Growth Catalysts
- NEVI Interstate Spacing Mandates:The Federal Highway Administration requires qualified charging stations every 50 miles along designated corridors, locking in corridor development priorities and anchor tenant positioning for qualified project sponsors.
- California ZEV Mandates:The California Air Resources Board's escalating zero-emission vehicle sales requirements through 2035 guarantee expanding addressable fleet sizes requiring charging access statewide.
- Fleet Depot Electrification:Logistics operators with centralized vehicle return patterns are deploying megawatt-scale charging hubs with predictable overnight load profiles that improve project financeability.
Market Restraints
- Transformer Lead Times:Utility-scale electrical equipment procurement cycles now extend 12-18 months, creating grid interconnection bottlenecks that delay revenue recognition for site developers.
- Buy America Compliance Costs:NEVI funding recipients must source 55% domestic content for iron and steel, limiting supplier pools and inflating hardware procurement expenses versus global sourcing alternatives.
- Permitting Fragmentation:Local zoning authorities across 50 states maintain inconsistent EVSE siting standards, forcing redundant engineering reviews and extending pre-construction timelines.
Strategic Opportunities
- Texas Corridor Density:The state's limited existing fast-charging coverage along I-10 and I-35 corridors creates first-mover positioning for NEVI-funded sites with minimal competitive overlap.
- Vehicle-to-Grid Integration:Bi-directional charging protocols enable fleet operators to monetize battery capacity through frequency regulation services and peak demand reduction programs.
- Multi-Unit Dwelling Retrofits:California's Title 24 building code amendments now mandate EV-ready parking in new construction, opening retrofit markets across 12 million existing apartment units.
Industry Challenges
- Licensed Electrician Scarcity:NEC Article 625 installation requirements and OSHA electrical safety standards demand certified journeymen that command wage premiums and limit crew scaling velocity.
- Software Interoperability:OCPP protocol variations across hardware vendors force custom integration work for network operators managing mixed-voltage site configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Vehicle Charging Infrastructure Market |
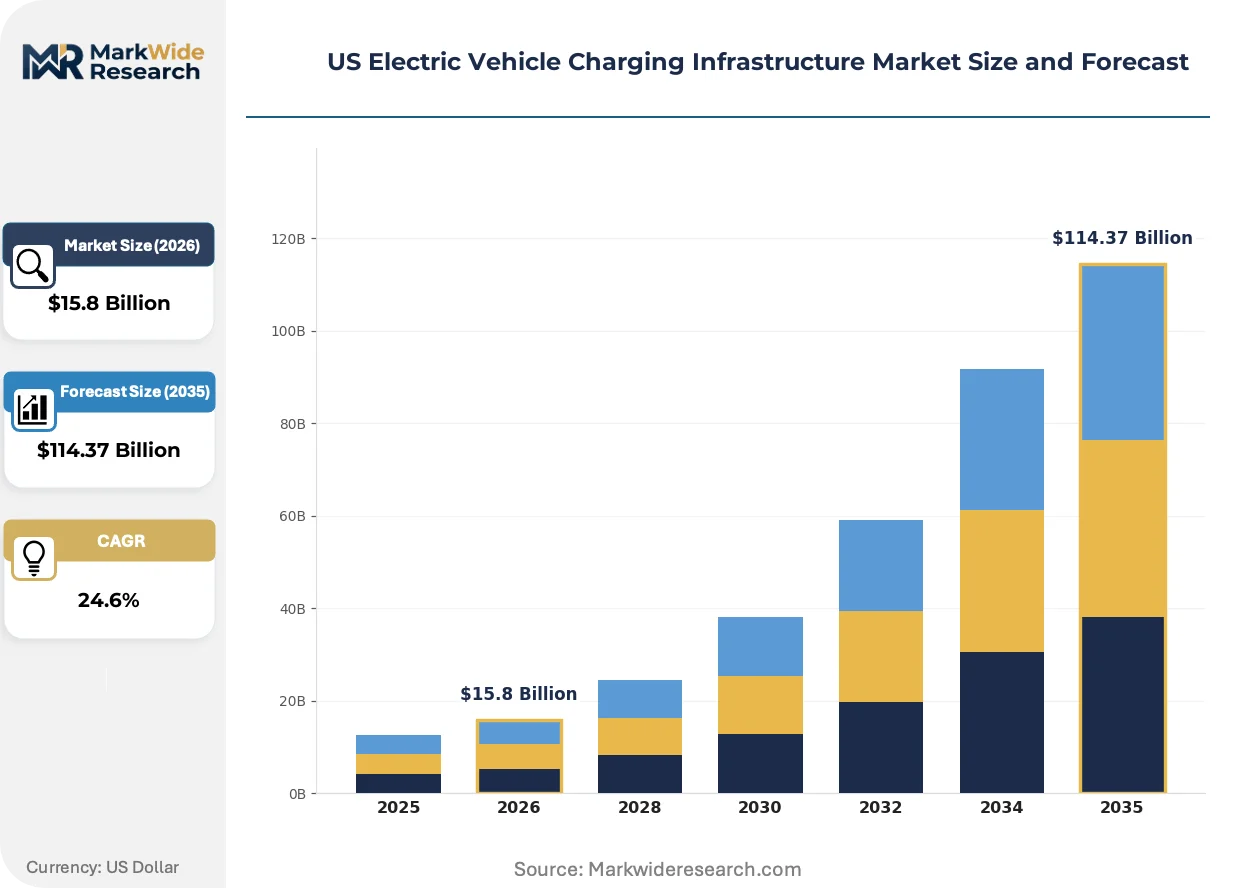
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $114.37 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Level 1, Level 2, DC Fast Charging, Wireless Charging Installation Type: Residential, Commercial, Public, Fleet Charging Network: Open Network, Closed Network, Semi-Private Network, Private Network Power Supply: AC Supply, DC Supply, Solar Charging, Grid-Tied |
| Companies Covered | EVgo, EV Connect, Tesla, Ionna, Red E Charge, ChargePoint, Blink Charging, Francis Energy, Electrify America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Vehicle Charging Infrastructure Market Strategic Shifts & Innovations
Hardware-software convergence and grid-interactive capabilities are redefining charging infrastructure from passive electricity delivery to active grid asset management, with implications for capital deployment patterns and operator business models.
Dynamic load management software is digitizing how charging stations balance multiple vehicle power draws against contracted utility demand limits and time-of-use rate structures. Fleet operators with centralized depots are adopting these platforms fastest, compressing infrastructure upgrade costs by avoiding dedicated transformer installations. The technology is digitizing site design economics by substituting intelligent power allocation for brute-force electrical capacity expansion.
The EPA's tailpipe emissions standards finalized in 2024 create complementary pressure to California's ZEV program, expanding the geography of guaranteed EV sales growth requiring charging infrastructure. Manufacturers must now plan charging access across 20+ states with tightening emissions budgets rather than California-isolated compliance strategies. Heavy-duty trucking corridors linking Texas ports to Midwest distribution centers face the most acute infrastructure gaps under these combined regulatory pressures.
Charging-as-a-service contracting is displacing capital purchase models among mid-size fleet operators seeking predictable per-mile energy costs. Third-party providers assume hardware, installation, and maintenance risks while retaining grid-interaction revenue streams. This shift concentrates most visibly among California regional delivery fleets with 50-200 vehicle counts and limited internal engineering capacity.
US Electric Vehicle Charging Infrastructure Market Segmentation
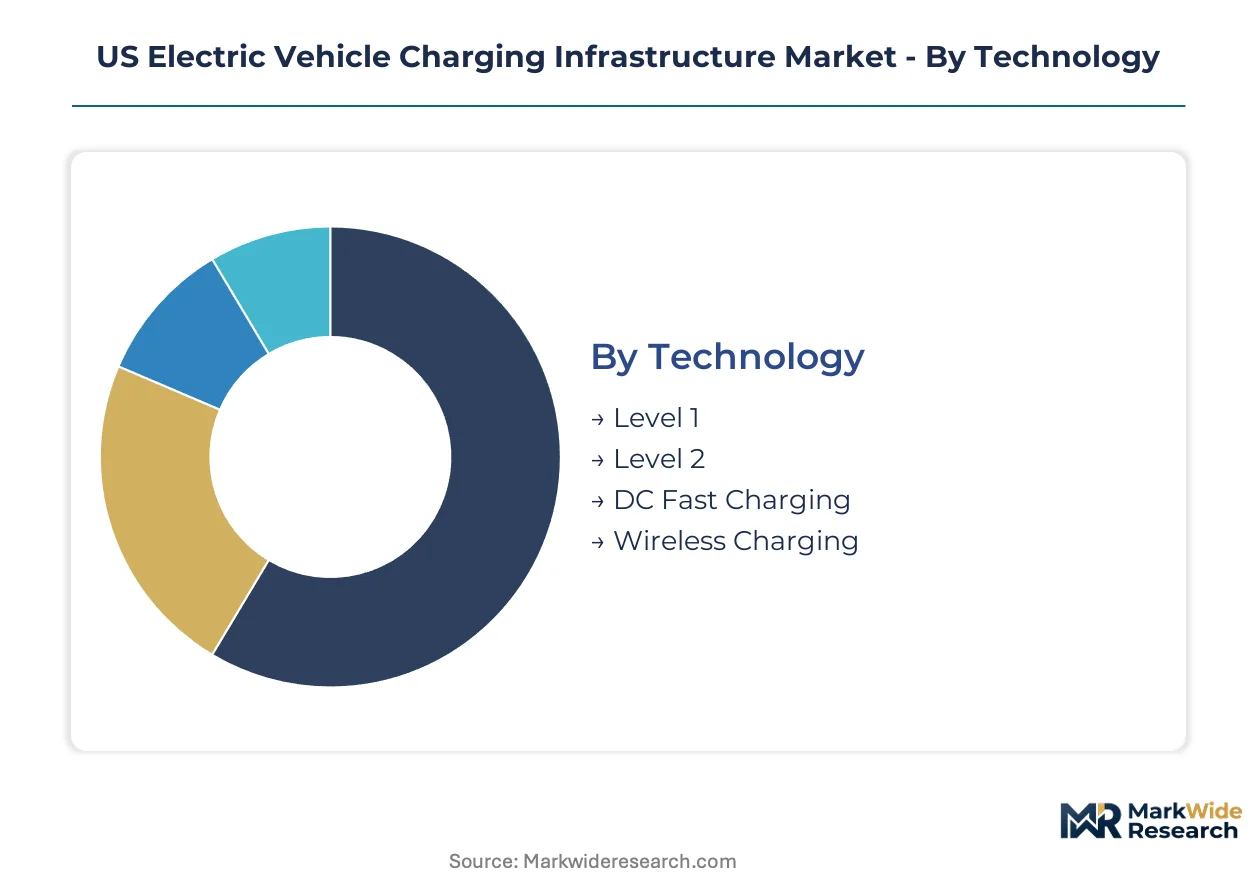
Technology tiers, installation contexts, network architectures, and power supply configurations create distinct investment profiles and margin structures across the US charging infrastructure landscape. Each dimension shapes capital deployment patterns, regulatory exposure, and customer acquisition economics differently.
Technology:
Power delivery specifications segment the market across voltage levels and charging speeds that determine hardware costs, grid interconnection complexity, and use-case fit.
- Level 1:Standard 120V residential outlets deliver below 7 kW through existing household circuits. Overnight charging in single-family garages dominates deployment, constrained by speed limitations that restrict commercial viability.
- Level 2:240V systems spanning 7-19 kW serve workplace, retail, and multi-unit dwelling installations. California's Title 24 mandates and Texas corridor buildouts concentrate demand as property owners electrify parking assets ahead of tenant requirements.
- DC Fast Charging:Direct current systems from 50-350 kW enable 20-80% replenishment in 20-40 minutes. Highway corridor positioning under NEVI spacing mandates and fleet depot megawatt hubs drive capital allocation.
- Wireless Charging:Inductive pad systems eliminate connector wear but suffer efficiency losses and higher capital costs. Limited pilot deployments target autonomous vehicle fleets and premium residential applications.
Level 2 commands the established base. The steepest expansion runs through DC Fast Charging.
Installation Type:
Site ownership and access models determine customer concentration, utilization predictability, and maintenance responsibility allocation.
- Residential:Single-family garage and driveway installations dominate unit volumes with thinner per-site economics. NEM 3.0 net metering reforms in California and utility time-of-use rate structures reshape home charging cost calculations.
- Commercial:Workplace and retail host locations balance customer dwell time against parking space revenue tradeoffs. ChargePoint's real estate partnerships and EVgo's retail anchor strategy exemplify divergent customer acquisition approaches.
- Public:Municipal and highway corridor sites face 24/7 availability requirements and higher vandalism exposure. NEVI formula funding eligibility hinges on open-network access and interstate spacing compliance.
- Fleet:Centralized depot installations with predictable overnight return patterns enable megawatt-scale transformer sizing and demand response program participation. Regional delivery operators in California and Texas anchor the fastest-climbing installation category.
Residential maintains volume leadership. Fleet installations are climbing the fastest.
Charging Network:
Access protocols determine interoperability obligations, customer roaming capabilities, and revenue model flexibility for station operators.
- Open Network:Any EV driver can initiate charging without membership restrictions. NEVI funding mandates and state public utility commission requirements increasingly favor this architecture for public dollars.
- Closed Network:Restricted access ties charging to specific vehicle brands or subscription services. Tesla's Supercharger network maintained this model until opening select corridors to non-Tesla vehicles.
- Semi-Private Network:Workplace or multi-family dwelling installations limit access to employees or residents while maintaining OCPP interoperability. Property managers balance amenity value against electricity cost recovery.
- Private Network:Fleet operators maintain exclusive depot access with custom software integration and dedicated maintenance contracts. Charging-as-a-service providers assume operational risk under long-term energy cost agreements.
Open Network configurations gain regulatory preference. Private Network deployments are expanding most quickly among logistics electrification mandates.
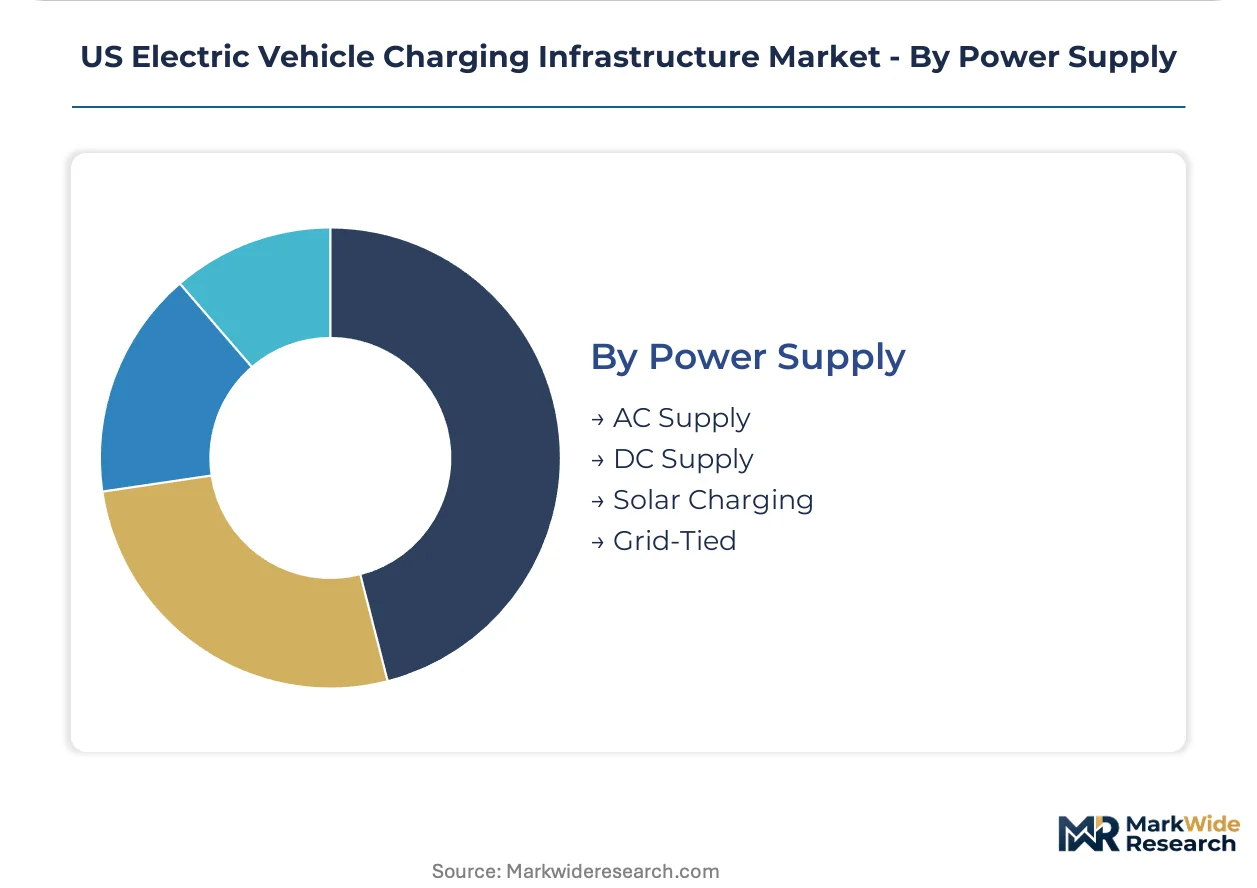
Power Supply:
Electrical source architecture shapes grid dependency, carbon intensity claims, and resilience against utility rate volatility.
- AC Supply:Alternating current from standard grid connections feeds Level 1 and Level 2 systems through onboard vehicle rectifiers. Ubiquitous infrastructure access keeps capital costs lowest for residential and workplace segments.
- DC Supply:Direct current bypasses onboard conversion losses for DC Fast Charging efficiency. Utility interconnection queues and transformer procurement delays constrain deployment velocity.
- Solar Charging:On-site photovoltaic generation paired with battery storage reduces grid dependency and peak demand charges. California SGIP incentives and federal ITC stacking improve project economics for commercial hosts.
- Grid-Tied:Bi-directional inverters enable vehicle-to-home and vehicle-to-grid services through managed charging software. FERC Order 2222 implementation and state-level interconnection standards determine revenue stack viability.
AC Supply retains the widest installed base. Grid-Tied capabilities are gaining share fastest as bi-directional protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and corridor developers concentrate demand across distinct state-level regulatory environments, with NEVI formula funding and zero-emission mandates creating divergent deployment timelines. California's ZEV program and Texas's limited existing coverage generate the sharpest competitive positioning opportunities.
California
CARB's escalating zero-emission vehicle sales requirements through 2035 guarantee expanding addressable fleet sizes requiring charging access statewide. Title 24 building code amendments now mandate EV-ready parking in new construction, opening retrofit markets across 12 million existing apartment units. The Los Angeles-San Diego corridor anchors megawatt-scale depot electrification for regional delivery operators.
Texas
Limited existing fast-charging coverage along I-10 and I-35 corridors creates first-mover positioning for NEVI-funded sites with minimal competitive overlap. ERCOT grid interconnection queue reforms and utility-backed rate structures shape project financeability for corridor developers. Houston and Dallas-Fort Worth metro areas concentrate fleet depot investments from logistics operators seeking predictable overnight load scheduling.
Florida
Tourism-driven corridor charging demand along I-95 and I-75 intersects with urban density in Miami-Dade and Orange counties, creating overlapping infrastructure needs. State-level permitting fragmentation forces redundant engineering reviews, though NEVI spacing mandates lock in development priorities. The Tampa-Orlando corridor attracts retail-host partnerships seeking dwell-time revenue optimization.
New York
Multi-unit dwelling retrofits dominate deployment patterns across the five boroughs and Westchester County, with Con Edison demand response programs improving project economics. NYSERDA incentive stacking and building electrification mandates accelerate workplace installation timelines. The Albany-Syracuse corridor faces acute heavy-duty trucking infrastructure gaps under federal emissions standards.
Illinois
Midwest distribution center electrification concentrates around Chicago's intermodal freight hubs, with ComEd rate case outcomes determining fleet charging project viability. State utility commission interconnection standards and Buy America compliance requirements shape hardware procurement decisions. The I-80/I-55 corridor intersection anchors NEVI-funded positioning for qualified project sponsors.
US Electric Vehicle Charging Infrastructure Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented site ownership models, with highway corridor positioning and fleet depot contracts determining margin concentration. The vendor base spans integrated network operators, hardware manufacturers, and charging-as-a-service providers with divergent capital intensity profiles. Two strategic archetypes dominate: vertically integrated platform operators controlling site access and software, and hardware-agnostic network managers aggregating third-party installations. M&A activity concentrates on corridor site portfolios and utility interconnection queue positions, while strategic partnerships with retail hosts and logistics operators secure utilization predictability.
Within the integrated platform tier, Tesla and ChargePoint anchor divergent positioning strategies, with the former exemplifying closed-network corridor dominance and the latter representing open-architecture workplace and retail penetration. EVgo occupies a position between these archetypes through retail-host partnerships and utility rate structure optimization. These three entities collectively represent the competitive template against which mid-scale operators benchmark site acquisition and software integration capabilities.
| Leading Market Players |
|---|
| EVgo |
| EV Connect |
| Tesla |
| Ionna |
| Red E Charge |
| ChargePoint |
| Blink Charging |
| Francis Energy |
| Electrify America |
| Others |
Cost & Logistics Intelligence
Buy America compliance costs create a dual squeeze on hardware procurement economics and supplier pool depth, forcing NEVI-funded developers toward domestic sourcing premiums that widen pricing spreads between federally subsidized corridor projects and privately financed installations. This regulatory chokepoint simultaneously concentrates supply chain leverage among qualified domestic manufacturers and compresses margins for operators unable to pass through steel and iron content premiums.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate NEVI-funded deployments, insulating developers from commodity volatility while locking in domestic content premiums. Price differentiation hinges on Buy America certification tier and transformer sizing scale, with megawatt-scale fleet hubs commanding standard rates and smaller commercial sites facing economy-tier procurement constraints. Cost compression in Level 2 hardware is intensifying because of Asian import competition unrestricted by federal funding mandates. Fleet operators with charging-as-a-service contracts exhibit lowest price sensitivity; independent site developers relying on per-session revenue show highest.
Supply Chain Analysis
Export controls on power electronics and semiconductor components limit flows from China, forcing hardware vendors toward South Korean and Japanese module sourcing. The supply chain draws from Mexico for enclosure fabrication, South Korea for power conversion systems, and domestic foundries for transformer cores. Silicon carbide MOSFETs, high-voltage cabling, and liquid cooling systems constitute critical input dependencies. Single-source vulnerability concentrates in transformer manufacturing where 12-18 month lead times create interconnection bottlenecks. Distribution runs through utility-approved EPC contractors with NEC Article 625 certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification mandates and NEVI formula funding create an early-cycle expansion story with guaranteed demand visibility through 2035 as zero-emission vehicle sales requirements lock in addressable fleet growth.
For Market Incumbents: Pre-empt corridor site saturation by securing transformer queue positions ahead of NEVI spacing mandate deadlines. Acquire licensed electrical contractor capacity to bypass journeyman scarcity constraints. Vertical integration into power electronics assembly mitigates Buy America compliance cost inflation. For New Entrants and Emerging Players: Texas I-35 corridor underpenetration offers first-mover positioning with minimal competitive overlap from established networks. Target fleet depot electrification in Houston and Dallas-Fort Worth metro areas where logistics operators seek predictable overnight load scheduling. Pursue charging-as-a-service contracting to displace capital purchase friction among mid-size regional delivery fleets. For Investors and Strategic Acquirers: EPA tailpipe emissions standards finalized in 2024 reshape the acquisition landscape by expanding guaranteed EV sales geography beyond California-isolated compliance strategies. Long-term viability centers on operators with secured utility interconnection queue positions and software platforms capable of bi-directional grid integration. Monitor FERC Order 2222 implementation progress as the signal for vehicle-to-grid revenue stack maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Transformer Queue Positioning | Secured interconnection capacity determines project financeability ahead of NEVI mandate deadlines. |
| Licensed Contractor Acquisition | NEC Article 625 certified crews command wage premiums that limit competitor scaling velocity. |
| Bi-Directional Software Development | Grid-interactive capabilities unlock frequency regulation revenue streams under FERC Order 2222. |
| Retail Host Partnership Expansion | Dwell-time optimization at grocery and convenience locations improves utilization predictability. |
| Buy America Supply Chain Localization | Domestic steel and iron sourcing qualifies projects for federal formula funding eligibility. |
Research Approach
A spread of perspectives from utility interconnection planners, fleet electrification directors, hardware procurement leads, and NEC-certified installation contractors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FERC filings, EIA grid interconnection queue data, NEVI program disbursement records, and state utility commission rate case outcomes. Bottom-up site-level economics triangulated against top-down market sizing across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling adoption curves against transformer manufacturing capacity and licensed electrician supply constraints. Segmentation dimensions spanned power delivery technology, installation context, network access architecture, and fleet versus retail utilization patterns. CAGRs derived from installed base build rates and revenue per port economics. Key inputs included NEVI funding disbursement timelines, CARB ZEV mandate trajectory, and ERCOT grid interconnection reform implementation.
Practitioners should monitor transformer procurement lead times, utility rate case outcomes, and OCPP protocol standardization progress for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
High Power Charger for Electric Vehicle Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
North America EV Charging Stations Market