
 ORC Industrial Waste Heat to Power Market | 2026-2036
ORC Industrial Waste Heat to Power Market Size, Share, and Industry Trends Forecast 2026-2036
ORC Industrial Waste Heat to Power Market Analysis
High-efficiency turbine specifications above 20% gross electrical efficiency is reorganizing competitive dynamics in the ORC Industrial Waste Heat to Power space. Turboden leverages its vertical integration into precision turbine manufacturing to sustain premium positioning across European cement and steel installations. Ormat Technologies anchors its presence through decades of geothermal-to-ORC technology transfer, while Exergy International differentiates via radial outflow turbine architectures that occupy niche high-temperature industrial exhaust applications.
Organic Rankine Cycle systems convert low-to-medium grade waste heat into electricity using organic working fluids with boiling points below water, typically operating between 80°C and 350°C thermal sources to serve industrial efficiency and carbon reduction objectives. The Organic Rankine Cycle technology segment leads installed capacity due to decades of operational validation across cement kilns and refinery flue gas streams, while the Oil & Gas application category shows the fastest structural expansion as stranded gas and flare-gas recovery projects multiply. Modular Systems installations command margin concentration because factory-built skids reduce field engineering costs and compress commissioning timelines for remote refinery and offshore platform deployments.
The EU Green Deal and F-Gas Regulation constrain working fluid selections across European installations, while EPA emissions enforcement under the Clean Air Act shapes project economics for US-based refinery and petrochemical adopters. China's MEE efficiency mandates and GB standard compliance requirements create divergent certification pathways that fragment supplier go-to-market strategies. Stakeholders must monitor regulatory fluid-phaseout schedules and national efficiency target revisions to align R&D pipelines with jurisdiction-specific compliance timelines.
Market Dynamics
High-efficiency turbine architectures above 20% gross electrical efficiency are compressing margins for legacy equipment suppliers while rewarding integrated system manufacturers with captive precision manufacturing capabilities.
Growth Catalysts
- EU Green Deal:Binding industrial emissions reduction targets accelerate cement and steel producer capital deployment toward waste heat recovery retrofits across German and Polish manufacturing corridors.
- China MEE efficiency mandates:State-backed enforcement of GB standard compliance drives large-scale ORC installations across heavy manufacturing zones in Shandong and Hebei provinces.
- Radial outflow turbine designs:Advanced architectures unlock economic viability from high-temperature industrial exhaust streams previously considered marginal for power generation.
Market Restraints
- Working fluid cost volatility:Perfluorinated compound supply concentration in Chinese chemical manufacturing creates input price instability for European project developers.
- F-Gas Regulation phaseout schedules:Accelerated HFC refrigerant restrictions under EU law compress R&D timelines and strand existing fluid inventories.
- Geothermal technology substitution:Mature flash steam plants in high-enthalpy volcanic regions displace ORC economics for developers with portfolio flexibility.
Strategic Opportunities
- Modular skid fabrication:Factory-built system integration reduces field engineering costs and compresses commissioning timelines for remote refinery and offshore platform deployments.
- India cement sector:Underpenetrated waste heat recovery installation base across UltraTech and Ambuja facilities creates first-mover expansion potential for efficiency technology suppliers.
- US IRA clean energy tax credits:Investment incentives for industrial decarbonization projects improve project IRRs for petrochemical and refining sector adopters.
Industry Challenges
- ORC thermodynamic modeling expertise:Scarcity of engineers trained in organic working fluid property optimization constrains EPC contractor execution capacity.
- Legacy DCS integration:Proprietary communication protocols in existing distributed control systems demand custom interface development for each brownfield installation.
- Fluid certification timelines:ASHRAE safety classification and EPA SNAP approval processes extend commercialization cycles for novel low-GWP working fluid formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ORC Industrial Waste Heat to Power Market |
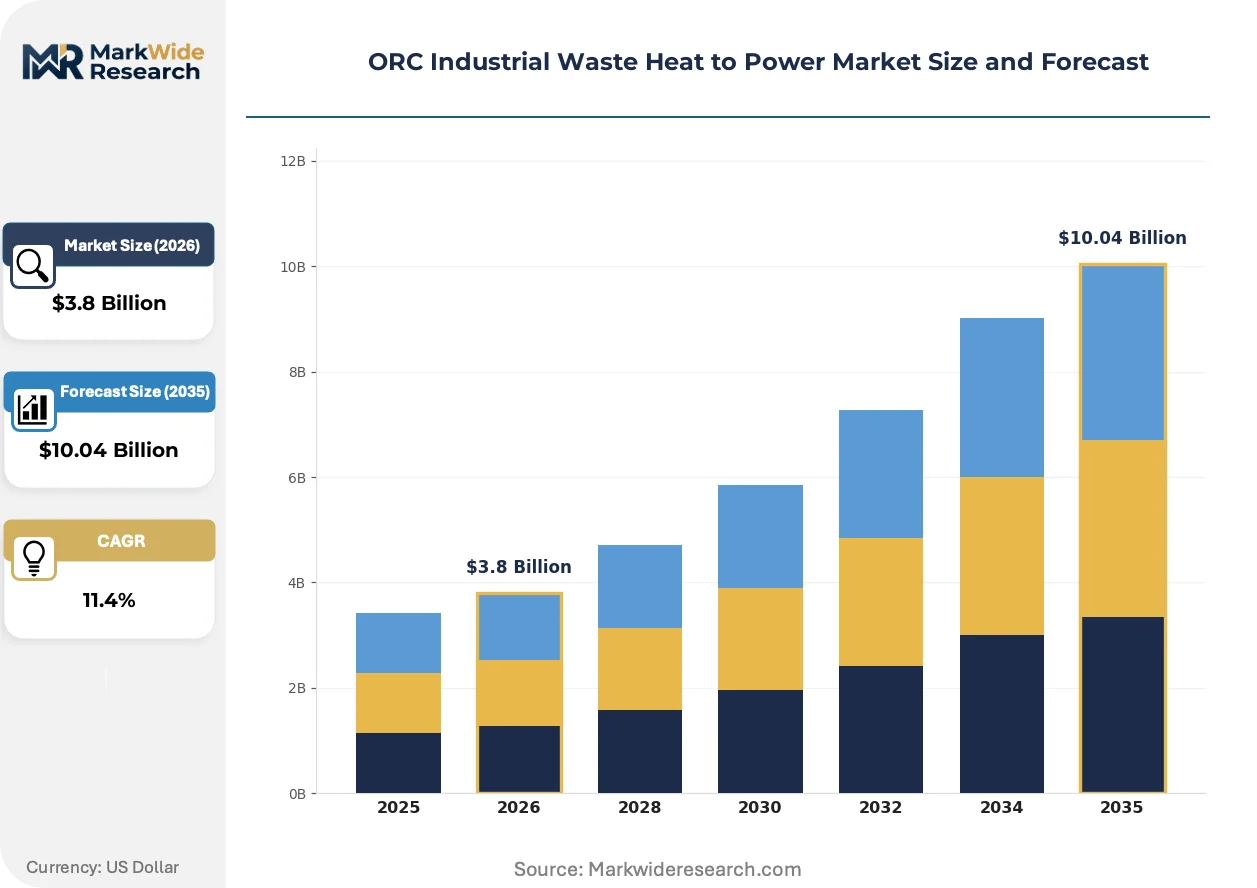
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Organic Rankine Cycle, Kalina Cycle, Supercritical Cycle, Combined Cycle Application: Manufacturing, Oil & Gas, Power Generation, Marine End User: Industrial Plants, Refineries, Power Utilities, Shipping Companies Installation: Onshore, Offshore, Modular Systems, Combined Heat and Power |
| Companies Covered | Turboden, Ormat Technologies, Exergy International, ElectraTherm, Enertime, Orcan Energy, Enogia, Triogen, Zuccato Energia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ORC Industrial Waste Heat to Power Market Emerging Trajectories
Technology roadmaps in the ORC Industrial Waste Heat to Power space are diverging between efficiency-maximizing premium architectures and cost-optimized modular platforms.
Supercritical CO2 turbine cycles are bifurcating competitive positioning in high-temperature waste heat applications. Cement kiln exhaust recovery projects above 300°C source temperature increasingly specify sCO2 systems for their compact footprint and reduced working fluid complexity. This technology is compressing addressable market scope for traditional organic fluid ORC suppliers in the premium efficiency tier.
EPA emissions enforcement under the Clean Air Act tightens flare-gas recovery requirements across Texas and Louisiana refining corridors. Refinery operators face binding consent decree timelines that accelerate ORC project sanctioning. Stranded gas recovery installations now represent the fastest-expanding application category as developers exploit regulatory pressure to secure offtake agreements.
Equipment procurement patterns favor turnkey EPC contracts with guaranteed performance clauses over component supply arrangements. Cement and steel producers transfer operational risk to integrators capable of wrapping turbine, heat exchanger, and balance-of-plant scope under single-point accountability. This consolidation concentrates contract awards among vertically integrated suppliers with in-house heat transfer engineering capabilities.
ORC Industrial Waste Heat to Power Market Segmentation
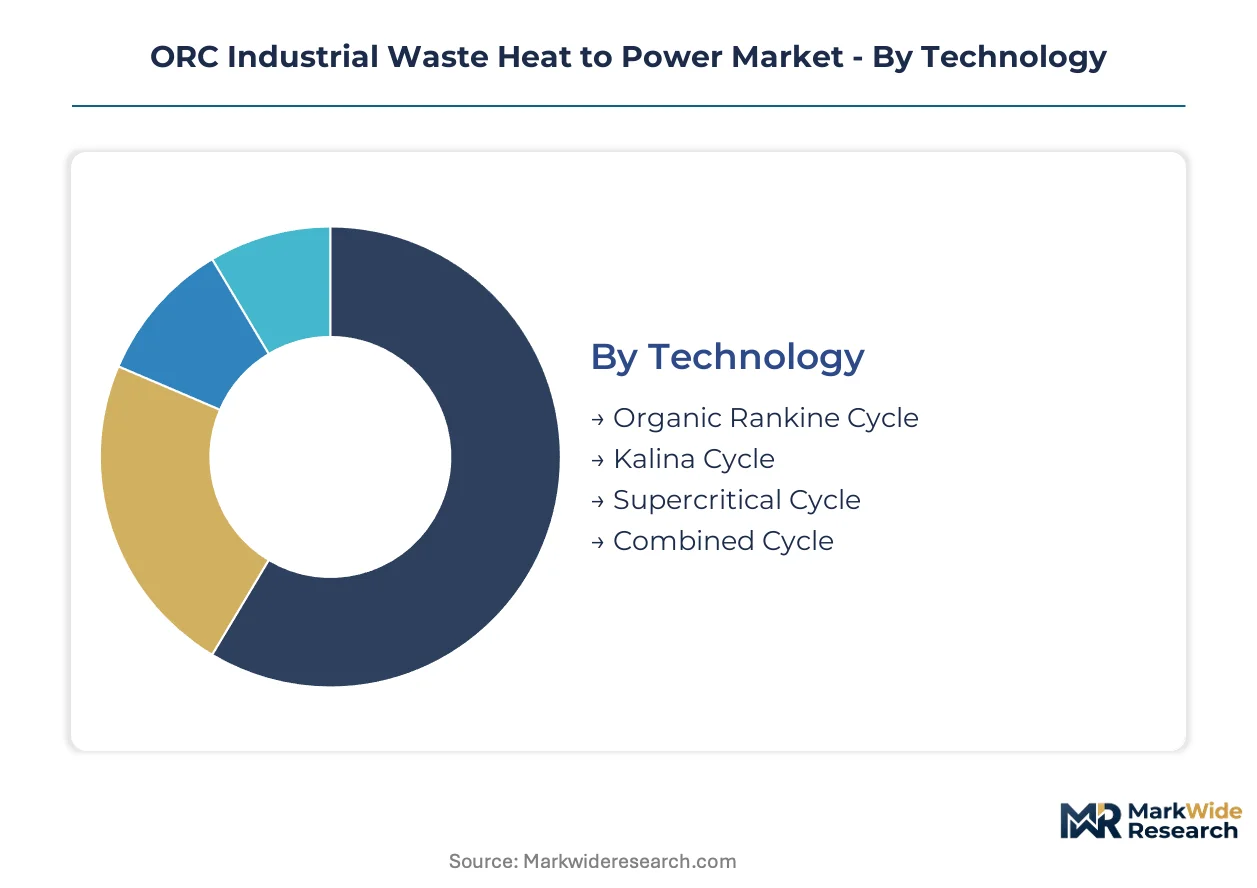
Technology selection in ORC systems determines working fluid chemistry, turbine architecture, and regulatory compliance pathways. End-use characteristics and installation constraints further segment procurement patterns across heavy manufacturing and energy infrastructure.
Technology:
EU F-Gas Regulation and EPA SNAP approval timelines create divergent certification burdens across working fluid categories, fragmenting supplier R&D roadmaps.
- Organic Rankine Cycle:Decades of operational validation across cement kilns and refinery flue gas streams anchor installed capacity leadership. MEE efficiency mandates in China's Shandong and Hebei provinces drive large-scale deployments where proven reliability outweighs efficiency premiums.
- Supercritical Cycle:Compact footprint and reduced working fluid complexity attract cement producers recovering exhaust above 300°C. German and Polish manufacturing corridors under EU Green Deal emissions targets increasingly specify sCO2 architectures for premium efficiency tier projects.
- Kalina Cycle:Ammonia-water working fluid mixtures suit geothermal-hybrid industrial applications with variable heat source temperatures.
- Combined Cycle:Integration with gas turbine exhaust or reciprocating engine jacket water serves refinery and petrochemical complexes seeking maximum energy recovery.
Established volume favors Organic Rankine Cycle; emerging adoption favors Supercritical Cycle.
Application:
Cost tier differentiation separates capital-intensive brownfield retrofits from greenfield modular installations.
- Oil & Gas:Stranded gas and flare-gas recovery projects multiply under EPA Clean Air Act enforcement across Texas and Louisiana refining corridors. Binding consent decree timelines accelerate ORC project sanctioning as operators face regulatory pressure to secure offtake agreements.
- Manufacturing:Cement and steel producers transfer operational risk to integrators under turnkey EPC contracts with guaranteed performance clauses. Heat transfer engineering capabilities concentrate contract awards among vertically integrated suppliers.
- Power Generation:Waste heat-to-power additions at existing thermal plants improve fleet efficiency metrics under national decarbonization mandates.
- Marine:IMO emissions regulations and fuel cost pressures drive interest in exhaust gas energy recovery for container shipping and tanker fleets.
Procurement concentration clusters in Oil & Gas; manufacturing retrofits expand most quickly.
End User:
Customer type determines risk allocation preferences between component supply and integrated performance contracts.
- Industrial Plants:Cement and steel producers dominate waste heat recovery demand, with UltraTech and Ambuja facilities in India presenting underpenetrated expansion potential for efficiency technology suppliers.
- Refineries:Brownfield distributed control system integration demands custom interface development for each installation, constraining EPC contractor execution capacity.
- Power Utilities:Portfolio flexibility allows technology substitution where mature flash steam plants displace ORC economics in high-enthalpy regions.
- Shipping Companies:Offshore platform and vessel deployments favor factory-built modular skids that reduce field engineering costs and compress commissioning timelines.
Industrial Plants command current revenue concentration; Refineries present the steepest expansion trajectory.
Installation:
Supply chain configuration separates field-erected systems from factory-integrated platforms.
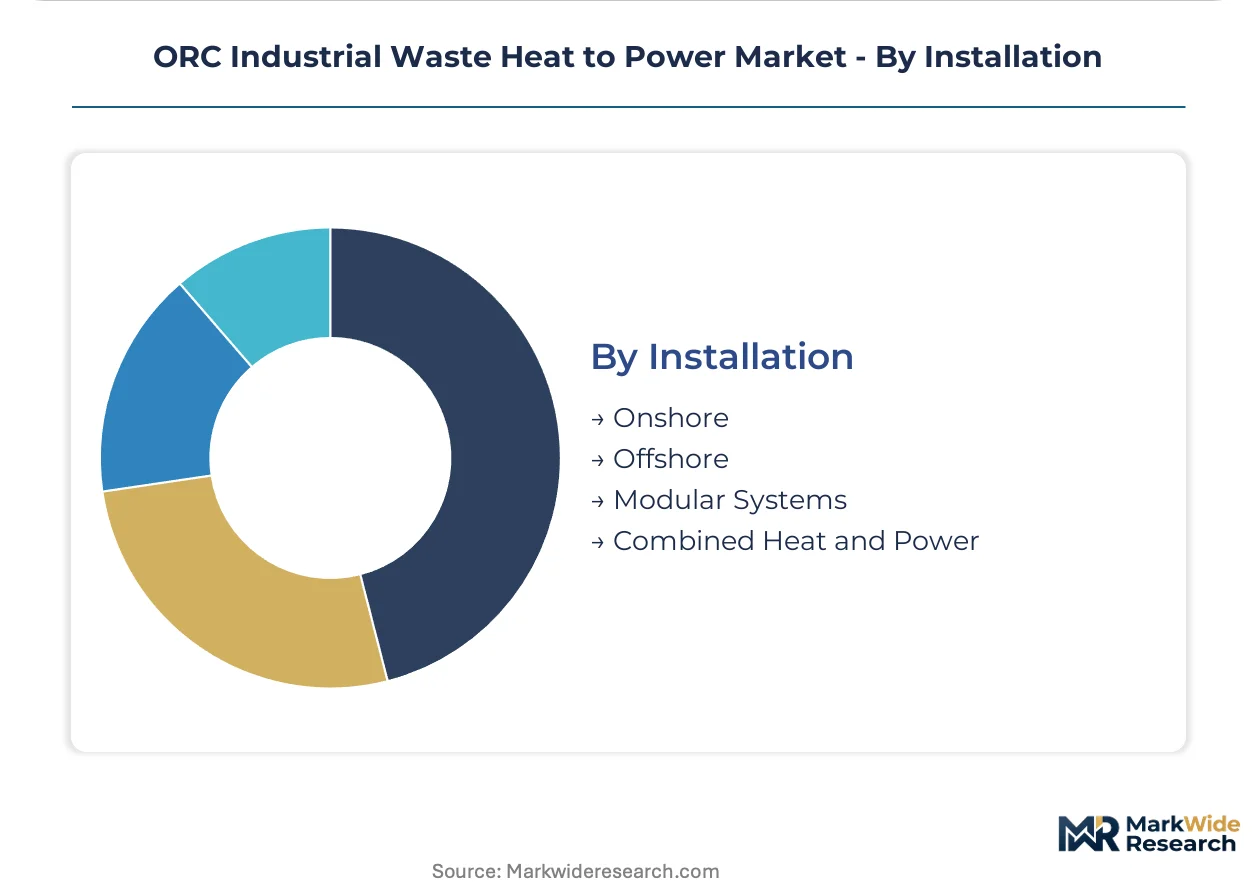
- Modular Systems:Factory-built skids reduce field engineering costs and compress commissioning timelines for remote refinery and offshore platform deployments. Margin concentration accrues to suppliers with captive precision manufacturing capabilities.
- Onshore:Brownfield cement kiln and steel furnace retrofits dominate project pipelines across German manufacturing corridors and Chinese heavy industry zones.
- Offshore:Platform space constraints and maintenance access limitations favor compact ORC architectures with minimal balance-of-plant footprint.
- Combined Heat and Power:District heating integration in Nordic and Eastern European markets adds thermal revenue streams to power-only economics.
Onshore retains volume leadership; Modular Systems gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India exhibit high price elasticity, prioritizing proven reliability over efficiency premiums, while German and US purchasers accept cost premiums for guaranteed performance contracts and turnkey integration.
China
Shandong and Hebei provinces host concentrated cement and steel manufacturing clusters where MEE efficiency mandates drive large-scale ORC deployments. GB standard compliance requirements create certification pathways that favor domestically integrated suppliers. Heavy industry zones in Tangshan and Jinan prioritize operational uptime over marginal efficiency gains.
Germany
EU Green Deal emissions targets compress project approval timelines across cement and steel corridors. F-Gas Regulation working fluid restrictions fragment supplier R&D roadmaps toward low-GWP alternatives. Manufacturing clusters in North Rhine-Westphalia specify premium efficiency architectures with single-point EPC accountability.
United States
EPA Clean Air Act enforcement tightens flare-gas recovery requirements across Texas and Louisiana refining corridors. IRA clean energy tax credits improve project IRRs for petrochemical sector adopters. Houston and Lake Charles processing hubs accelerate ORC sanctioning under binding consent decree timelines.
India
UltraTech and Ambuja cement facilities present underpenetrated waste heat recovery installation bases with first-mover expansion potential. Central Electricity Authority efficiency guidelines create divergent state-level implementation schedules. Gujarat and Rajasthan clinker production clusters favor modular skid configurations to minimize field engineering costs.
ORC Industrial Waste Heat to Power Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium efficiency specialists coexist with volume-oriented modular fabricators. The vendor base separates into three strategic archetypes: vertically integrated precision turbine manufacturers, geothermal-to-ORC technology transfer specialists, and radial outflow turbine niche architects. Dominant competitive moves include backward integration into captive heat exchanger production and geographic expansion through turnkey EPC capability acquisition.
Among European precision engineering specialists, Turboden and Exergy International exemplify contrasting technology anchoring strategies, while Ormat Technologies represents the geothermal technology transfer archetype with decades of operational validation. These three occupy distinct competitive positions: Turboden leverages in-house turbine manufacturing for premium cement and steel installations, Exergy International anchors high-temperature industrial exhaust niches through radial outflow architectures, and Ormat Technologies draws on geothermal project execution scale to serve refinery and petrochemical brownfield retrofits. Each archetype commands margin concentration through differentiated integration depth rather than component supply alone.
| Leading Market Players |
|---|
| Turboden |
| Ormat Technologies |
| Exergy International |
| ElectraTherm |
| Enertime |
| Orcan Energy |
| Enogia |
| Triogen |
| Zuccato Energia |
| Others |
Supply Flow & Price Mechanics
Factory utilization rates above 85 percent at precision turbine manufacturers in Germany and Italy compress cost curves for premium ORC systems while elevating price floors for modular skids sourced from lower-scale fabricators. Scale concentration in European precision engineering clusters allows integrated suppliers to defend margin structures against Chinese competitors serving price-sensitive cement producers in Shandong province.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European ORC installations by imposing compliance cost differentials on working fluid selections. Project-based contracting dominates, with price differentiation driven by certification grade under GB standards and after-sales service bundling. Cost compression in economy-tier modular systems intensifies because Chinese MEE efficiency mandates favor proven reliability over efficiency premiums. Cement producers in Hebei province exhibit highest price sensitivity; German steel manufacturers accept cost premiums for guaranteed performance contracts.
Supply Chain Analysis
Strategic stockpiling of perfluorinated working fluids prevails among European project developers confronting phased F-Gas Regulation restrictions. Supply concentrates in China, Germany, and Italy for precision turbine components and heat exchanger assemblies. Raw material dependencies include specialty steel alloys, organic working fluids, and precision bearings. Single-source vulnerability in Chinese chemical manufacturing for HFC refrigerants creates exposure to input price instability. Distribution runs through turnkey EPC contractors with captive installation crews rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among cement and steel producers pursuing consolidated procurement across multi-site retrofit programs, fragmenting pricing leverage for component-only suppliers.
For Market Incumbents: Shield premium positioning by deepening backward integration into heat exchanger production and securing captive supply of low-GWP working fluids certified under ASHRAE safety classifications. Supercritical CO2 substitution in high-temperature cement kiln applications threatens traditional ORC architectures. Capacity addition in North Rhine-Westphalia manufacturing corridors reinforces proximity to EU Green Deal project pipelines. For New Entrants and Emerging Players: Differentiate on modular skid fabrication speed to capture India's underpenetrated cement sector where UltraTech and Ambuja facilities lack waste heat recovery infrastructure. Target Gujarat and Rajasthan clinker production clusters with factory-built configurations minimizing field engineering costs. Pursue channel partnerships with domestic EPC contractors holding existing relationships with central electricity authority officials. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated suppliers with long-term service contracts wrapping turbine maintenance and working fluid replenishment. Long-term viability favors precision engineering specialists with demonstrated project execution across multiple regulatory jurisdictions. Acquisition target archetype: mid-cap modular fabricators with certified manufacturing footprints in India or Southeast Asia. Monitor F-Gas Regulation phaseout acceleration as inflection indicator for working fluid inventory stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Production | Captive manufacturing of precision heat transfer equipment secures margin concentration against commodity suppliers. |
| Low-GWP Working Fluid Certification Program | ASHRAE safety classification and EPA SNAP approval timelines determine competitive access to EU and US project pipelines. |
| Modular Skid Manufacturing Scale-Up | Factory-built system integration compresses commissioning timelines for remote refinery and offshore platform deployments. |
| Turnkey EPC Capability Acquisition | Single-point accountability contracts transfer operational risk from cement and steel producers to integrated suppliers. |
| Geographic Expansion Through Local Partnership | Domestic EPC relationships in India bypass fragmented state-level implementation schedules under central electricity authority guidelines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with ORC project developers, EPC contractors, and plant engineering directors at cement and steel facilities; and secondary validation against customs trade data, MEE enforcement bulletins, EPA consent decree filings, and EU ETS transaction registries. Bottom-up installation capacity tallies across Shandong, Hebei, North Rhine-Westphalia, Texas, and Louisiana manufacturing corridors were triangulated against top-down market value estimates derived from disclosed contract values and equipment procurement patterns.
Across the projection horizon, the analytical framework modeled technology selection, application category, end-user type, and installation configuration as core segmentation dimensions. CAGRs were derived from regression analysis of historical deployment rates against regulatory enforcement intensity and efficiency mandate revision schedules. Forecast inputs incorporated MEE efficiency target trajectories, EU Green Deal emissions reduction pathways, and IRA tax credit utilization rates among petrochemical sector adopters.
Material uncertainties — working fluid phaseout acceleration, geothermal technology substitution in high-enthalpy regions, and cement sector demand cyclicality — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and project sanctioning velocity under binding consent decrees. Revision becomes warranted when supercritical CO2 cost curves cross ORC economic thresholds in high-temperature waste heat applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Brazil Waste to Energy Market
Waste to Energy Systems
North America Waste to Energy Market
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market